
 Tacky Transfer Paper Market | 2026-2036
Tacky Transfer Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Tacky Transfer Paper Market Analytics
A capital-intensity divergence between integrated paper mills and coating specialists is redrawing competitive boundaries. Asia Pulp and Paper leverages captive pulp supply to control input costs across Southeast Asian operations. Avery Dennison Corporation sustains premium positioning through precision coating capabilities and direct brand relationships with industrial label converters. Zhejiang Jinchang Special Paper anchors Chinese domestic supply with regional distribution density and customized substrate formulations.
Tacky transfer paper comprises a coated substrate bearing a repositionable adhesive layer, typically silicone-modified or acrylic-based, engineered to receive printed or cut designs for clean release onto textiles, ceramics, or other surfaces. The coating weight, expressed in grams per square meter, determines tack level and transfer fidelity for heat-press or hand-burnish applications. Glossy paper variants dominate volume in craft and hobby channels where visual finish drives consumer selection, while matte paper segments expand fastest in textile printing for sportswear and promotional apparel where reduced glare matters. Transparent paper occupies specialized niches in layered scrapbooking and decal applications where substrate visibility preserves design integrity.
EPA oversight of volatile organic compound emissions from adhesive coating operations shapes manufacturing location decisions for US-serving production. REACH registration requirements in Europe constrain formulation choices for exporters serving EU textile printers and craft distributors. China's GB standards for paper products and adhesive safety, administered by SAMR, set baseline compliance thresholds for domestic and export-bound output. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across major economies, as adhesive chemistry pivots toward fluorine-free alternatives without sacrificing thermal stability during transfer processes.
Market Dynamics
REACH compliance in Europe is forcing adhesive formulators to eliminate legacy chemistries from coating operations, compressing product development cycles while textile printers in Asia-Pacific accelerate specification changes to maintain export eligibility.
Growth Catalysts
- Textile Printing Automation:Heat-press equipment manufacturers in Vietnam and Bangladesh are bundling tacky transfer paper with digital print systems, embedding substrate specifications into machine calibration protocols.
- EU Green Deal Procurement Mandates:Public sector promotional apparel tenders in Germany and France now require fluorine-free adhesive documentation, redirecting specification authority toward certified converters.
- Ceramic Decal Reshoring:Italian tableware producers are repatriating decal printing from Chinese converters to domestic facilities, generating demand for precision-coated European substrates.
Market Restraints
- Pulp Cost Volatility:Hardwood pulp prices, the dominant input for release liners, fluctuate with Brazilian weather patterns and Indonesian export quotas, compressing coating specialists' margin predictability.
- Coating Equipment Concentration:Slot-die coating lines above two-meter widths are manufactured by only three European and Japanese equipment builders, creating multi-year capacity expansion queues.
- Digital Ink Substitution:Direct-to-garment inkjet systems using pretreated cotton are capturing short-run sportswear orders previously served by transfer paper workflows.
Strategic Opportunities
- Indian Textile Export Corridor:Tiruppur and Surat apparel clusters lack domestic coating capacity, creating white space for regional substrate converters to displace imported Chinese supply.
- Per- and Polyfluoroalkyl Substance Bans:US state-level restrictions in Maine and Washington are accelerating demand for silicone-modified adhesive formulations that European suppliers have already certified.
- Subscription Craft Supply Models:Monthly kit distributors in North America are consolidating hobby-channel purchasing power, enabling exclusive substrate specifications that bypass traditional wholesale tiers.
Industry Challenges
- Adhesive Chemist Scarcity:Formulation expertise bridging silicone rheology and paper surface chemistry resides with retiring specialists at German and Japanese coating houses, constraining new product development velocity.
- Dual Certification Timelines:Simultaneous OEKO-TEX and bluesign audits for textile-facing products extend commercialization cycles by eight to fourteen months, delaying revenue recognition for reformulated lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tacky Transfer Paper Market |
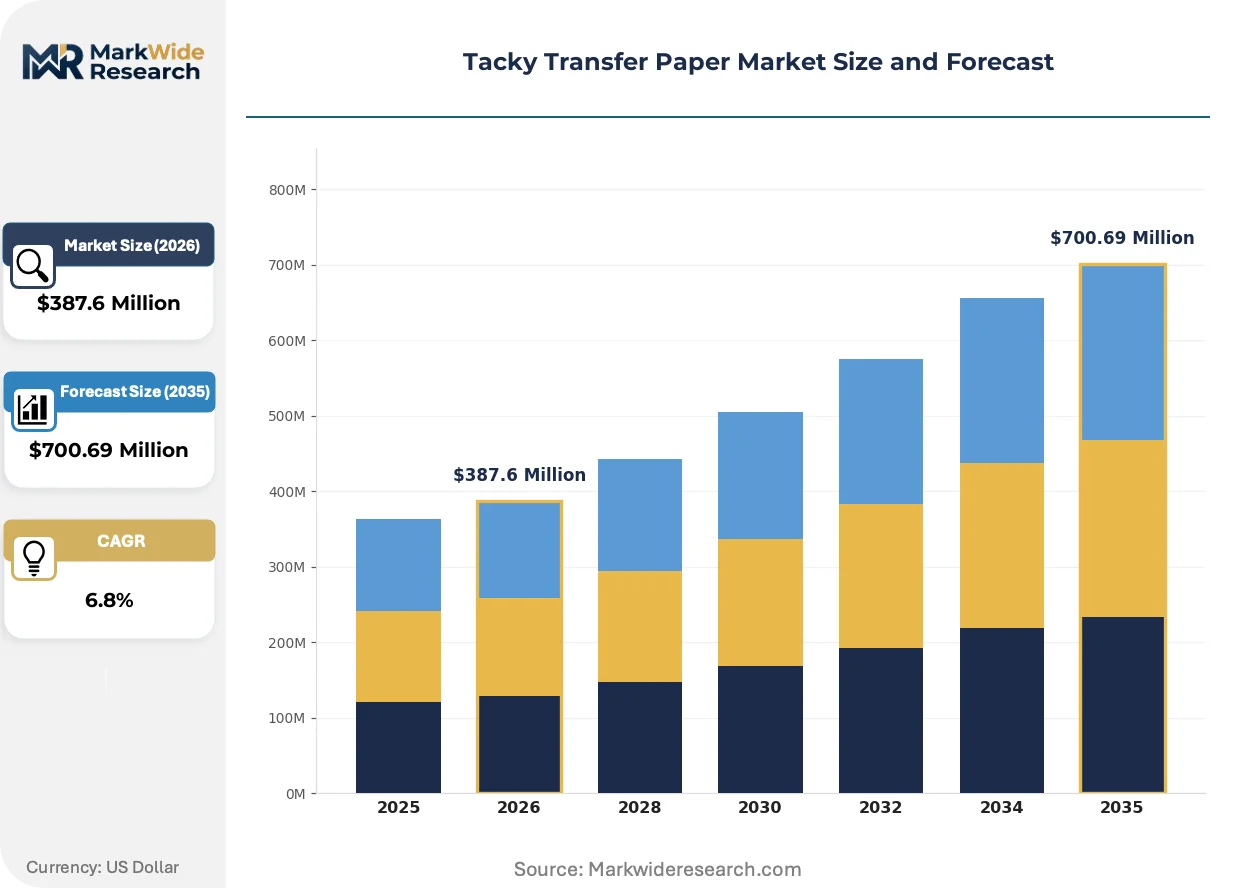
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy Paper, Matte Paper, Transparent Paper, Colored Paper Application: Craft Projects, Textile Printing, Scrapbooking, Label Making End User: Artists, Hobbyists, Manufacturers, Educators Distribution Channel: Online Stores, Brick-and-Mortar, Distributors, Wholesale Dealers |
| Companies Covered | Pt Pura Barutama, Quad Inc, RR Donnelley & Sons, Deluxe Corporation, Miquel y Costas & Miquel, Asia Pulp and Paper, Zhejiang Jinchang Special Paper, Alizarin Coating, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tacky Transfer Paper Market Evolving Landscape
Silicone chemistry platforms are fragmenting as regional regulatory divergence accelerates, while digital printhead resolution advances compress the tolerance specifications for adhesive coating uniformity.
Laser-deactivatable silicone release coatings are decomposing the traditional mechanical die-cutting workflow in textile transfer applications. Sportswear decorators in Portugal and North Carolina are adopting these chemistries to enable on-demand contour cutting without blade maintenance. The technology is decomposing capital barriers between short-run digital operations and high-volume screen-printing facilities.
REACH authorization requirements for cyclic siloxanes are tightening disclosure obligations for adhesive importers serving EU textile printers. Coating operations in Zhejiang and Guangdong are requalifying supply chains to maintain export eligibility. Matte-finish paper grades for anti-glare sportswear applications face the steepest compliance recertification burdens.
Specification consolidation among North American promotional products distributors is compressing supplier rosters from twelve to three approved substrates per product category. Large decorators in Florida and Texas are mandating lot-level adhesive composition certificates. This concentration is most visible in corporate uniform programs where liability exposure drives documentation requirements.
Tacky Transfer Paper Market Segmentation
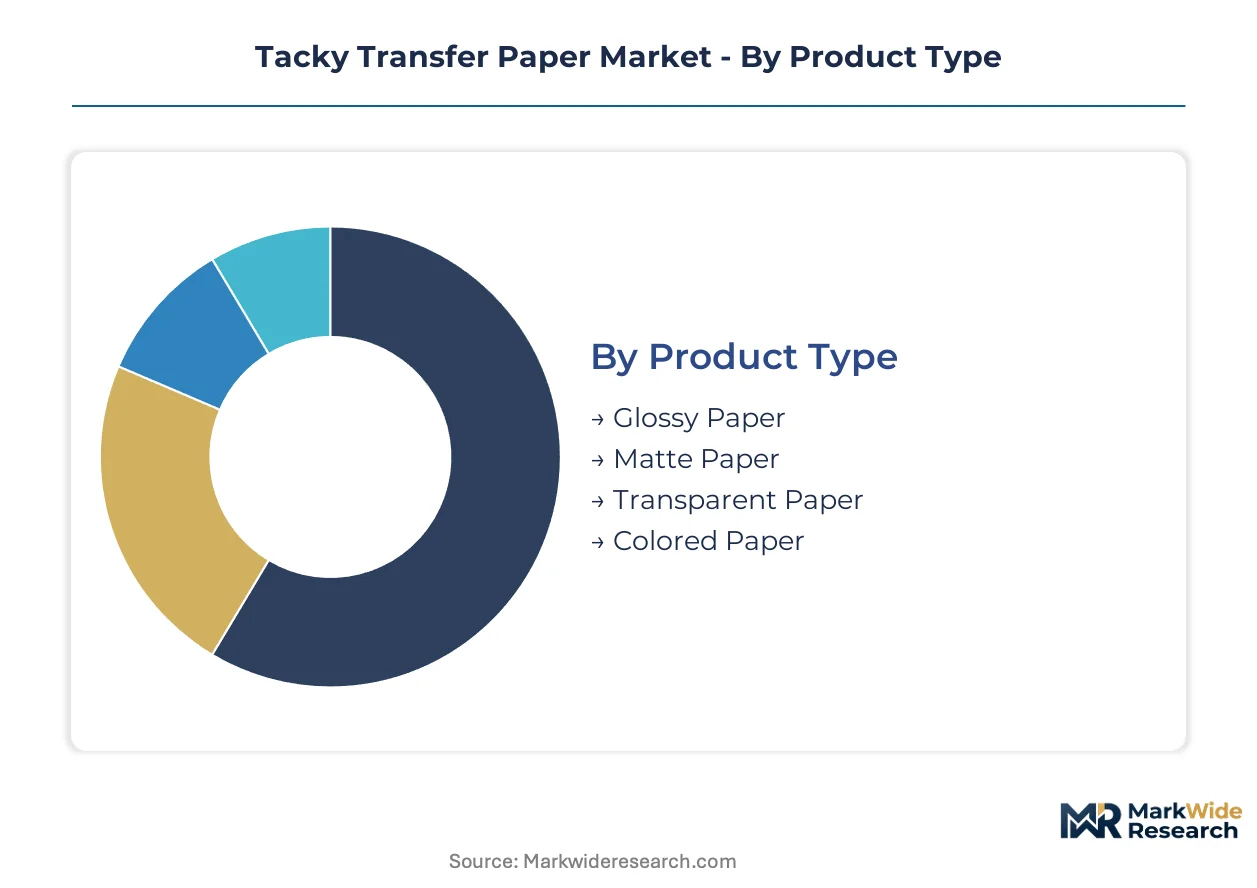
Segmentation in tacky transfer paper reveals how coating specifications, application workflows, and procurement channels create distinct margin architectures. Manufacturers calibrate adhesive formulations and substrate finishes to match the precision demands of industrial textile printers against the price elasticity of hobbyist consumers.
Product Type:
Premium margin pools concentrate in specialized finishes where coating complexity creates formulation barriers for commodity producers.
- Glossy Paper:High-sheen clay-coated substrates deliver maximum color vibrancy for photographic transfers and decorative decals. Craft retailers in the United States and Germany stock glossy grades as default SKUs, though EPA VOC regulations on solvent-based coatings compress domestic manufacturing margins.
- Matte Paper:Calcium carbonate-loaded coatings eliminate surface reflection for sportswear applications where photographers capture team imagery under stadium lighting. REACH fluorine-free mandates are accelerating reformulation costs for European-serving production lines.
- Transparent Paper:Cellulose acetate or glassine bases enable layered scrapbooking compositions where substrate visibility preserves dimensional effects.
- Colored Paper:Pigmented stock eliminates white borders on dark garment transfers, popular among DIY decorators seeking finished aesthetics without weeding labor.
The dominant share belongs to Glossy Paper, while Matte Paper is closing the gap fastest.
Application:
Volume concentration tracks automation intensity, with digitally integrated workflows commanding specification authority over hand-burnish craft segments.
- Craft Projects:Heat-press hobbyists and Cricut-enabled consumers drive replenishment purchasing through subscription box channels. Amazon and Michaels Stores capture the bulk of North American volume with private-label substrate lines.
- Textile Printing:Industrial decorators in Vietnam and Bangladesh specify coating weights above 80 gsm for automated platen presses handling polyester sportswear. Bundled equipment-paper procurement is displacing independent substrate selection.
- Scrapbooking:Archival-grade pH-neutral papers serve memory-keeping enthusiasts through specialty retailers like Scrapbook.com and independent craft stores.
- Label Making:Repositionable adhesive papers for industrial barcode and shipping applications require silicone release liners with tight thickness tolerances.
Textile Printing commands the volume leadership position, whereas Craft Projects demonstrate the steepest expansion trajectory in absolute unit terms.
End User:
Procurement sophistication separates institutional buyers with technical specifications from discretionary purchasers driven by visual finish and price promotion.
- Artists:Professional decorators and studio operators demand lot-level consistency for commissioned work, often purchasing through specialized distributors with color-matching services.
- Hobbyists:Weekend crafters exhibit high price elasticity and channel-switching behavior between Amazon, Temu, and big-box craft retailers.
- Manufacturers:Apparel decorators and promotional products converters issue annual contracts with adhesive composition certificates and bluesign compliance documentation.
- Educators:School districts and makerspaces purchase through cooperative purchasing agreements with standardized specifications and bulk pricing tiers.
Manufacturers retain the dominant procurement value, while Hobbyists are gaining share fastest through e-commerce channel expansion.
Distribution Channel:
Channel selection determines margin capture, with direct digital relationships enabling subscription models that bypass wholesale markups entirely.
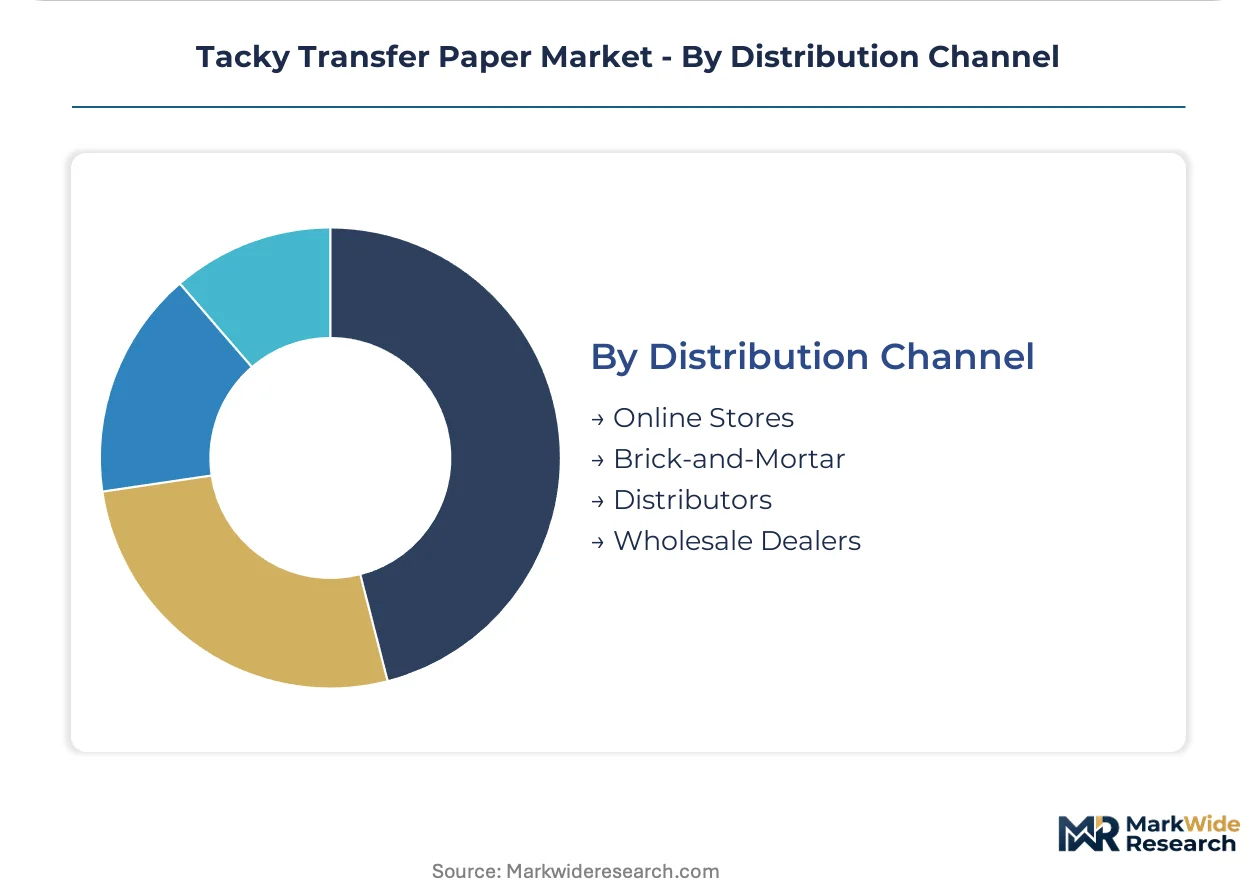
- Online Stores:Amazon, Etsy, and specialty craft platforms aggregate global demand with algorithmic search placement determining SKU visibility. Temu's direct-from-China model is compressing price points for standard glossy grades.
- Brick-and-Mortar:Michaels, Jo-Ann, and Hobby Lobby maintain tactile merchandising with in-store heat-press demonstrations that drive impulse substrate purchases.
- Distributors:Regional paper merchants like Spicers and Xpedx serve industrial converters with technical support and just-in-time inventory programs.
- Wholesale Dealers:Volume aggregators supply promotional products distributors with private-label substrate lines and exclusive finish specifications.
Online Stores hold the dominant channel position, though Distributors are expanding most quickly in textile-facing industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with European coating specialists commanding premiums for REACH-certified formulations, while Chinese producers compete on scale and regional distribution density across domestic textile clusters.
China
Zhejiang and Guangdong provinces house the dominant substrate coating capacity serving both domestic apparel decorators and export markets. SAMR-administered GB standards for paper products and adhesive safety establish baseline compliance thresholds that regional converters must meet. Zhejiang Jinchang Special Paper anchors supply from Jinhua city with customized formulations for sportswear transfer applications.
United States
EPA oversight of volatile organic compound emissions from adhesive coating operations shapes manufacturing location decisions for domestic-serving production. Florida and Texas-based large decorators now mandate lot-level adhesive composition certificates for corporate uniform programs. Michaels Stores and Amazon aggregate hobby-channel demand through private-label substrate lines and algorithmic search placement.
Germany
EU Green Deal procurement mandates for public sector promotional apparel now require fluorine-free adhesive documentation, redirecting specification authority toward certified converters. ECHA REACH authorization requirements for cyclic siloxanes tighten disclosure obligations for coating operations. Bavarian industrial decorators are consolidating supplier rosters from twelve to three approved substrates per product category.
Italy
Italian tableware producers are repatriating decal printing from Chinese converters to domestic facilities, generating demand for precision-coated European substrates. ANSM chemical safety protocols govern adhesive imports for food-contact ceramic applications. Emilia-Romagna hosts specialized coating houses serving luxury homeware brands with archival-grade transfer specifications.
Vietnam
Heat-press equipment manufacturers in Ho Chi Minh City and Hanoi are bundling tacky transfer paper with digital print systems, embedding substrate specifications into machine calibration protocols. Textile export growth from Tiruppur-linked supply chains drives specification changes to maintain EU eligibility. Local converters lack domestic coating capacity, creating import dependence on Chinese and South Korean supply.
Tacky Transfer Paper Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision coating specialists commanding premium positioning while integrated paper mills leverage captive pulp supply for margin control. The vendor base stratifies across three tiers: multinational adhesive technology licensors, regional substrate converters with equipment bundling relationships, and commodity producers serving price-sensitive hobby channels. Consolidation pressure is accelerating as specification authority concentrates among large textile decorators and subscription craft distributors. Dominant competitive moves include backward integration into adhesive formulation and geographic expansion through equipment-paper bundling partnerships.
Among Asia-Pacific integrated producers, Asia Pulp and Paper and Zhejiang Jinchang Special Paper exemplify scale-driven positioning with regional distribution density advantages. Avery Dennison Corporation occupies the premium-tier vector with precision coating capabilities and direct brand relationships with industrial label converters. Pt Pura Barutama represents Southeast Asian regional supply concentration serving domestic textile export corridors.
| Leading Market Players |
|---|
| Pt Pura Barutama |
| Quad Inc |
| RR Donnelley & Sons |
| Deluxe Corporation |
| Miquel y Costas & Miquel |
| Asia Pulp and Paper |
| Zhejiang Jinchang Special Paper |
| Alizarin Coating |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
Two-meter-plus slot-die coating line scarcity concentrates manufacturing scale among Zhejiang and Guangdong operators, compressing unit economics for smaller converters while establishing price floors that bundled equipment-paper procurement can undercut. This capacity bottleneck reinforces margin stratification between REACH-certified European specialists and volume-driven Chinese producers serving hobby channels.
Pricing Analysis
The customization-premium spread separates configured-to-order textile grades from standard glossy craft SKUs. Three-tier pricing structure across premium REACH-certified, standard industrial, and economy hobby levels tracks certification burden and coating complexity. Price differentiation hinges on fluorine-free adhesive documentation and lot-level composition certificates. Pricing pressure stems from Temu's direct-from-China model compressing standard-grade price points. Hobbyists exhibit highest price sensitivity through algorithmic platform switching, while German public-sector procurement mandates lowest sensitivity due to liability documentation requirements.
Supply Chain Analysis
Inbound logistics costs through Ningbo and Shanghai ports fluctuate with container availability on Asia-Europe trade lanes, affecting European distributor landed costs. Supply concentrates in China, South Korea, and Germany, with coating operations drawing from Brazilian hardwood pulp and German silicone resin inputs. Single-source vulnerability sits with three European and Japanese equipment builders controlling two-meter-plus slot-die line manufacturing. Distribution runs through bundled equipment-paper procurement for textile printers and algorithmic platform aggregation for hobby channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tacky transfer paper demand cycles with apparel export volumes and heat-press equipment replacement waves, positioning the market for recovery as Vietnamese and Bangladeshi textile automation accelerates specification refresh.
For Market Incumbents: Fortify specification authority through backward integration into silicone adhesive formulation, capturing margin pools currently licensed to German and Japanese coating houses. Deepen equipment bundling partnerships with Ho Chi Minh City and Hanoi heat-press manufacturers to embed substrate calibration protocols. Accelerate fluorine-free certification pipelines ahead of US state-level PFAS restrictions in Maine and Washington.
For New Entrants and Emerging Players: OEKO-TEX fast-track certification enables white-space entry into Indian Tiruppur and Surat apparel clusters lacking domestic coating capacity. Target subscription craft supply distributors consolidating North American hobby-channel purchasing power. Pursue direct digital relationships with monthly kit distributors to bypass wholesale markups entirely.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-bundled substrate suppliers with embedded machine calibration protocols. Five-to-ten year viability favors precision coating specialists with REACH-certified formulation libraries over commodity glossy producers exposed to Temu price compression. Watch for PFAS restriction acceleration as inflection signal favoring silicone-modified adhesive portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | Captures margin pools from German and Japanese licensing houses while securing REACH compliance pathways. |
| Equipment-Paper Bundling Partnerships | Embeds substrate specifications into Vietnamese and Bangladeshi heat-press calibration protocols. |
| Fluorine-Free Certification Investment | Anticipates US state-level PFAS restrictions and EU Green Deal procurement mandates. |
| Regional Coating Capacity Expansion | Addresses Indian textile cluster import dependence on Chinese and South Korean supply. |
| Subscription Channel Direct Relationships | Bypasses wholesale tiers through exclusive specifications with monthly craft kit distributors. |
Research Methodology
Operator-level perspectives from coating plant managers, textile printer procurement leads, adhesive formulation chemists, and craft channel category buyers anchored the qualitative base. Primary interviews combined with secondary validation against customs trade data, SAMR GB standard filings, SEC 10-K disclosures from listed paper producers, and ECHA REACH registration databases. Bottom-up capacity modeling across Zhejiang and Guangdong coating lines triangulated with top-down demand estimation from heat-press equipment shipment data.
Sensitivity analysis tested forecast outputs against pulp cost volatility scenarios and PFAS restriction acceleration timelines across the projection horizon. Segmentation dimensions modeled include finish type, application workflow, end-user procurement sophistication, and distribution channel structure. CAGRs derived from equipment bundling penetration rates and textile export corridor automation intensity. Industry-specific inputs incorporated slot-die coating line capacity queues and dual certification timeline distributions.
Decision-makers should treat outputs as directional under base assumptions of continued REACH compliance cost pass-through and stable Brazilian hardwood pulp supply; material deviation would warrant model refresh. Specific risks include adhesive chemist retirement waves constraining new product development velocity and cyclic siloxane authorization tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Envelope Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market