
 Food Wrapping Paper Market | 2026-2036
Food Wrapping Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Food Wrapping Paper Market Analysis
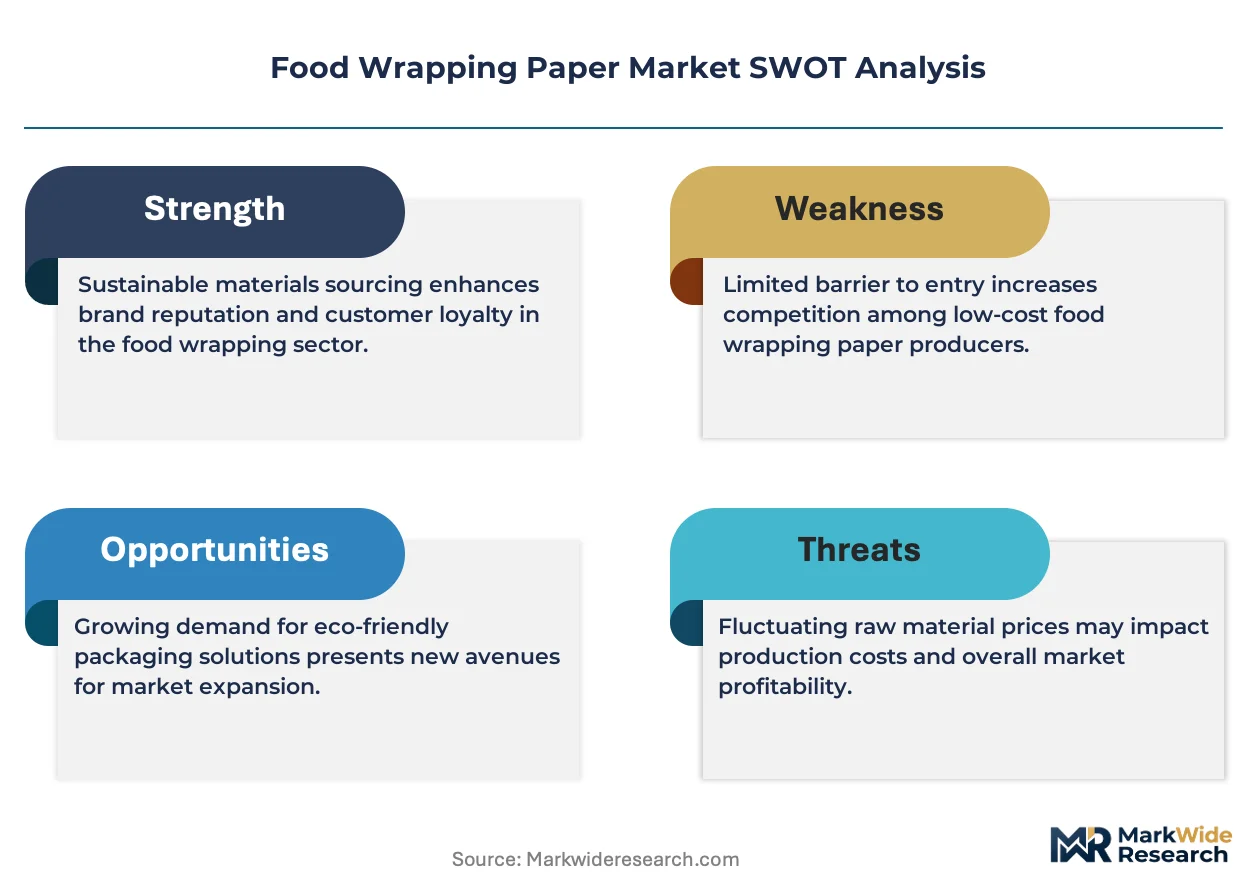
Multi-source procurement of virgin and recycled pulp is hardening as converters buffer against fiber price volatility and supply disruptions. Huhtamaki Oyj leverages its integrated mill network across Europe to secure kraft pulp for greaseproof grades. Mondi Plc anchors its competitive position through backward integration into sustainable forestry operations in Scandinavia. WestRock Company competes via scale advantages in North American containerboard, repurposing linerboard capacity into food-contact wrapping substrates.
Food wrapping paper comprises bleached or unbleached kraft sheets, typically 30–50 gsm, treated with FDA-compliant fluorochemical-free coatings to resist oil and moisture penetration while maintaining breathability for fresh bakery and protein applications. The material type dimension shows PAPER and WAXED grades capturing margin pools as quick-service chains abandon plastic clamshells, while FOIL laminates retain niche premium positioning for hot-hold proteins. Within end users, HOSPITALITY and FOOD MANUFACTURERS represent the fastest-expanding demand channels as centralized commissaries replace in-store wrapping with pre-portioned branded sheets.
FDA food-contact substance notifications and EU Framework Regulation EC 1935/2004 govern migration limits and coating chemistries, while Germany's national packaging ordinance enforces extended producer responsibility fees that favor certified recyclable substrates. California's SB 54 mandates 65% single-use packaging recycling rates by 2032, directly elevating paper wrap specifications for brands distributing in that state. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as pending EPA rules and ECHA proposals threaten existing oil-barrier chemistries and will force coating reformulation decisions within product development cycles.
Market Dynamics
Single-use plastic bans across multiple jurisdictions are forcing foodservice operators to requalify entire packaging portfolios, creating immediate substitution demand for grease-resistant paper substrates that meet both functional performance and emerging per- and polyfluoroalkyl substance restrictions.
Growth Catalysts
- EU Single-Use Plastics Directive:Foodservice chains in Germany, France, and Italy are converting sandwich and bakery packaging to certified compostable paper wraps to comply with mandated plastic reduction targets.
- Quick-service restaurant expansion:Deli chains across North America are standardizing fluorochemical-free greaseproof paper for hot-hold proteins and fresh bakery applications.
- Kraft pulp availability:Integrated converters with captive Scandinavian forestry operations are securing fiber supply for high-barrier food-contact grades.
Market Restraints
- Fluorochemical coating phase-outs:Pending EPA rules and ECHA proposals threaten existing oil-barrier chemistries, forcing costly reformulation cycles.
- Pulp price volatility:Virgin and recycled fiber markets experience cyclical swings that compress converter margins on fixed-price foodservice contracts.
- Silicone-coated parchment substitution:Premium bakery segments retain preference for silicone-treated alternatives in high-temperature applications.
Strategic Opportunities
- California SB 54 compliance services:Packaging distributors can capture value by pre-certifying paper wrap specifications for brands facing 65% recycling mandates by 2032.
- Centralized commissary conversion:Food manufacturers replacing in-store wrapping with pre-portioned branded sheets represent an underpenetrated volume channel.
- Bio-based barrier coatings:Convergence of plant-derived polymers with conventional kraft substrates opens premium positioning for certified home-compostable grades.
Industry Challenges
- Migration testing capacity:FDA food-contact substance notifications and EU Framework Regulation EC 1935/2004 compliance create bottlenecks as reformulation cycles accelerate.
- Coating equipment reconfiguration:Shifting from fluorochemical to bio-based barrier systems requires capital-intensive dryer and applicator modifications at converter facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Wrapping Paper Market |
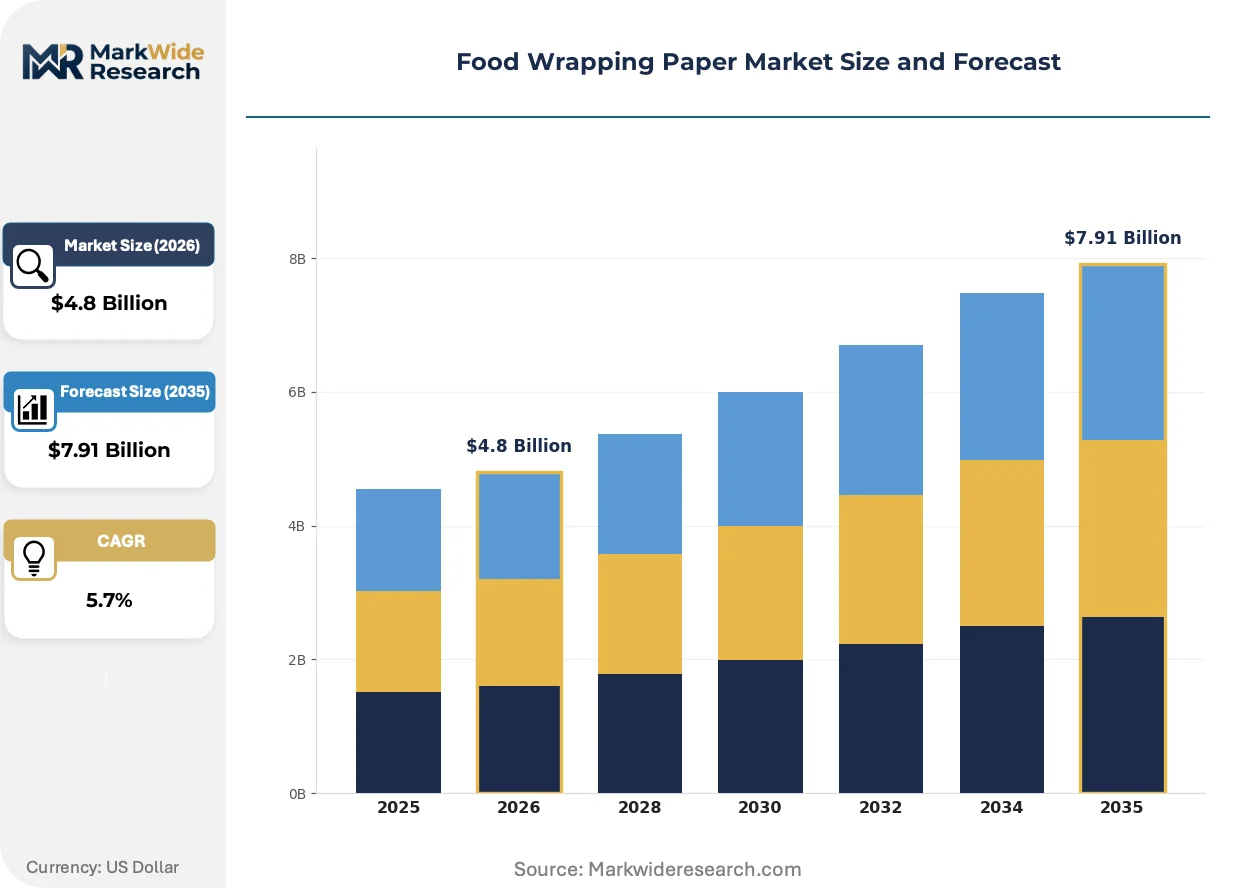
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PAPER, PLASTIC, FOIL, WAXED End User: HOUSEHOLDS, HOSPITALITY, RETAIL, FOOD MANUFACTURERS Packaging Size: SMALL, MEDIUM, LARGE, ROLLS Application: SANDWICHES, BAKERY PRODUCTS, MEAT, FRUITS |
| Companies Covered | Amcor Plc, Berry Global Inc., Huhtamaki Oyj, Mondi Plc, Georgia-Pacific LLC, International Paper Company, WestRock Company, Ardagh Group, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Wrapping Paper Market Emerging Trajectories
Barrier coating chemistry is undergoing forced evolution as regulatory pressure compounds with foodservice sustainability commitments, compressing development timelines and redefining performance benchmarks for oil and moisture resistance.
Fluorochemical-free greaseproof technology is integrating bio-based polymers and refined mechanical pulp treatments to achieve oil resistance without per- and polyfluoroalkyl substances. Quick-service chains in California and New York are piloting these substrates for sandwich wraps at accelerated qualification schedules. The technology is integrating into mainstream foodservice specifications, displacing legacy fluorinated chemistries before regulatory deadlines.
REACH restrictions on persistent organic pollutants are tightening acceptable coating chemistries for food-contact materials entering the European Economic Area. Industrial consequence includes mandatory supply chain requalification for exporters serving German retail and hospitality channels. Bakery and protein wrapping segments are responding by consolidating procurement around pre-certified compostable grades from integrated European converters.
Centralized procurement by multi-unit restaurant operators is compressing supplier qualification cycles and demanding volume-tiered pricing with embedded compliance documentation. Distributors serving national quick-service chains are replacing fragmented local supply with approved vendor lists. This pattern is most visible in North American sandwich and bakery segments where corporate sustainability mandates override franchisee purchasing autonomy.
Food Wrapping Paper Market Segmentation
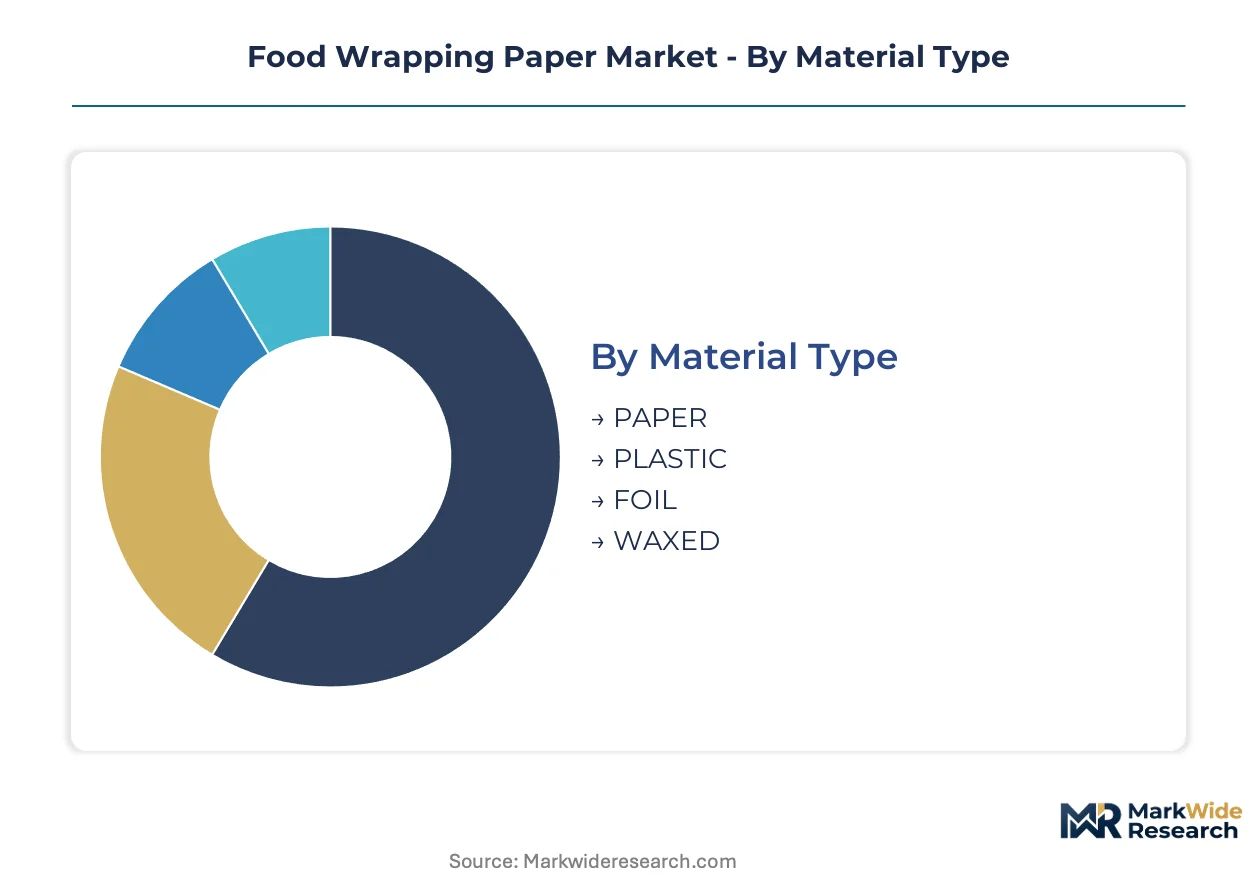
Foodservice procurement teams select wrapping substrates based on barrier performance, regulatory compliance, and operational throughput requirements. Material chemistry and end-use application together determine pricing tiers and supplier qualification cycles. Packaging size and format specifications reflect automation compatibility and portion control needs across centralized commissaries.
Material Type:
Purchasing decisions in this dimension center on grease resistance, compostability certification, and coating migration compliance under FDA and EU Framework Regulation EC 1935/2004.
- PAPER:Bleached or unbleached kraft sheets at 30–50 gsm, treated with fluorochemical-free coatings for oil and moisture resistance. Quick-service restaurants in California and New York are standardizing these substrates to meet SB 54 recycling mandates and pending EPA per- and polyfluoroalkyl substance restrictions.
- WAXED:Paraffin or vegetable-based wax coatings applied to kraft substrates for enhanced moisture barrier in chilled protein applications. German retail chains favor certified compostable waxed grades to comply with national packaging ordinance extended producer responsibility fees.
- FOIL:Aluminum-laminated structures for hot-hold protein retention in premium deli segments. Limited volume due to cost and recycling complexity.
- PLASTIC:Polypropylene and polyethylene films facing displacement from EU Single-Use Plastics Directive jurisdictions. Surviving demand concentrates in non-food contact interleaving applications.
Volume sits with PAPER; growth tilts toward WAXED as bio-based coating formulations achieve performance parity.
End User:
Channel structure determines order frequency, specification complexity, and compliance documentation requirements.
- HOSPITALITY:Hotels, restaurants, and catering operations requiring branded, pre-portioned sheets for buffet and room service applications. Centralized procurement by multi-unit operators is compressing supplier lists and demanding embedded sustainability certifications.
- FOOD MANUFACTURERS:Centralized commissaries producing pre-wrapped sandwich and protein portions for retail and foodservice distribution. This channel is expanding most quickly as operators replace in-store wrapping with off-site production.
- RETAIL:Supermarket deli counters and bakery sections sourcing generic or private-label wraps. Price-sensitive procurement with shorter qualification cycles.
- HOUSEHOLDS:Consumer rolls and sheets through grocery and e-commerce channels. Lowest specification tier with minimal compliance documentation.
Procurement scale concentrates with FOOD MANUFACTURERS; margin expansion favors HOSPITALITY through branded specification premiums.
Packaging Size:
Format selection tracks equipment automation level, portion standardization, and storage density requirements.
- ROLLS:Continuous formats for high-speed inline cutting at food manufacturing facilities. Preferred by centralized commissaries for flexibility across product formats.
- LARGE:Pre-cut sheets for bulk protein and bakery tray applications. Dominates hotel and catering procurement.
- MEDIUM:Standard sandwich and wrap portions for quick-service restaurant chains. Steepest expansion trajectory as chains standardize portion control.
- SMALL:Individual patty and confectionery interleaving. Niche volume in premium bakery segments.
Throughput economics favor ROLLS; specification standardization is pushing growth toward MEDIUM pre-cut formats.
Application:
Functional requirements vary by moisture content, fat migration, and temperature exposure during holding and distribution.
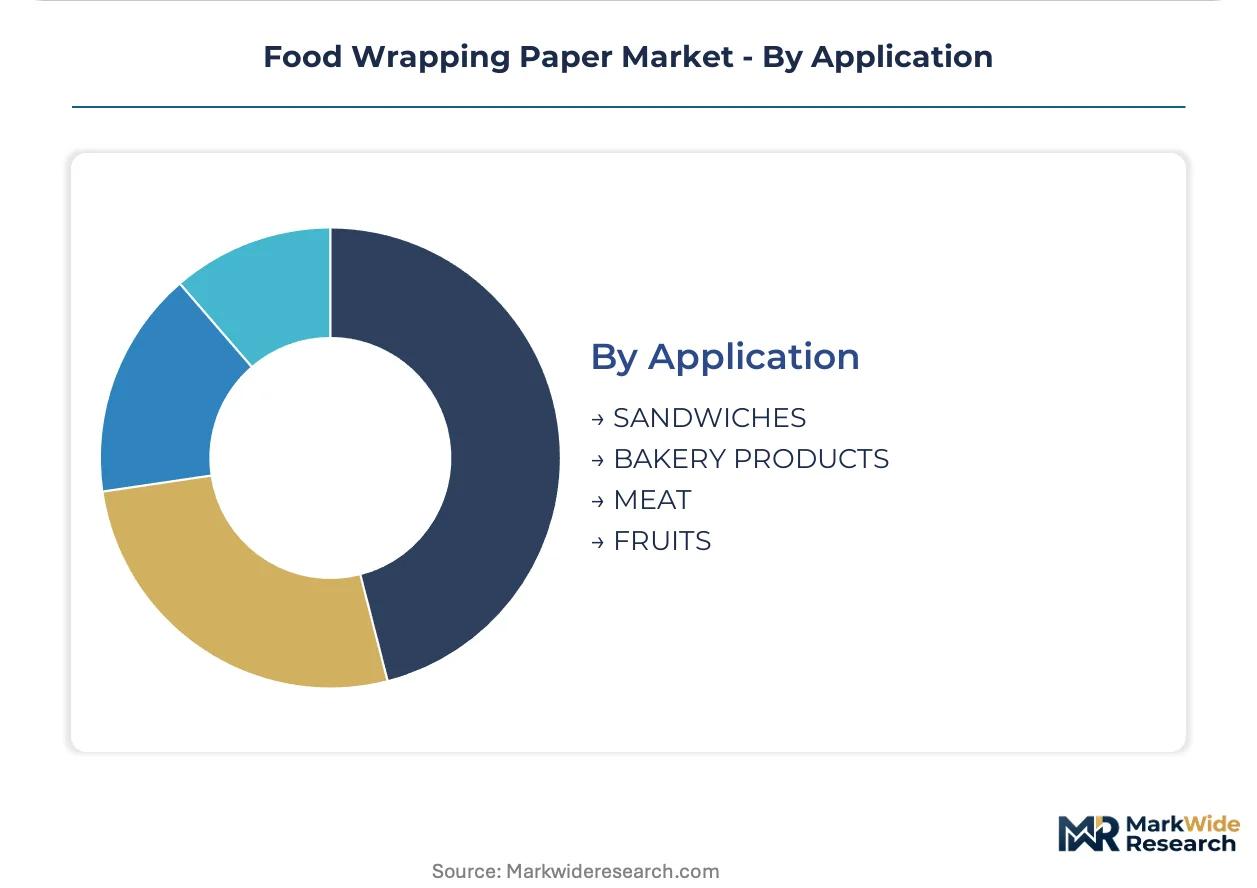
- SANDWICHES:Grease-resistant paper wraps for cold and hot sandwich formats requiring breathability to prevent sogginess. Deli chains across North America are converting from plastic clamshells to certified compostable paper wraps.
- BAKERY PRODUCTS:Breathable kraft substrates for bread, pastries, and cakes requiring moisture equilibrium. German packaging converters serve central European retail chains with home-compostable certified grades.
- MEAT:High-barrier structures for fresh and processed protein with elevated fat content. Silicone-coated parchment retains preference in high-temperature applications.
- FRUITS:Waxed or breathable paper for produce protection and moisture management. Limited penetration compared to plastic net and tray alternatives.
SKU proliferation is heaviest in BAKERY PRODUCTS; substitution momentum from plastic is strongest in SANDWICHES.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian kraft pulp forests anchor the raw-material base for grease-resistant food wrapping grades, with integrated converters leveraging captive fiber supply to serve quick-service chains across multiple continents. The geographic distribution of demand tracks regulatory enforcement intensity and quick-service restaurant density.
United States
California and New York quick-service chains are standardizing fluorochemical-free paper wraps to comply with SB 54 recycling mandates and pending EPA per- and polyfluoroalkyl substance restrictions. FDA food-contact substance notifications govern migration limits for oil-barrier coatings. Chicago and Dallas-Fort Worth metropolitan areas concentrate commissary operations replacing in-store wrapping with pre-portioned branded sheets.
Germany
Retail and hospitality chains across Bavaria and North Rhine-Westphalia source certified compostable wrapping solutions from domestic packaging converters. The national packaging ordinance enforces extended producer responsibility fees that favor recyclable substrates. Hamburg and Berlin serve as distribution hubs for central European quick-service restaurant networks converting sandwich packaging to paper-based alternatives.
China
Yangtze River Delta bakery and protein processors are adopting breathable kraft substrates for domestic foodservice distribution. SAMR food-contact material standards and GB technical regulations govern coating safety for oil-resistant grades. Shanghai and Suzhou industrial clusters house converters supplying quick-service chains with 30–50 gsm greaseproof sheets for sandwich applications.
France
EU Single-Use Plastics Directive compliance is driving Paris and Lyon quick-service operators to certified compostable paper wraps for sandwich and bakery formats. ECHA proposals on persistent organic pollutants are tightening acceptable coating chemistries for food-contact materials. Île-de-France packaging distributors are pre-qualifying substrates for national restaurant chains facing mandated plastic reduction targets.
India
Maharashtra and Gujarat food manufacturers are expanding centralized commissary production of pre-wrapped sandwich portions for retail distribution. FSSAI food safety standards govern packaging material compliance for domestic and export-oriented processors. Mumbai and Ahmedabad converters are scaling kraft pulp capacity to serve quick-service chains abandoning plastic clamshells.
Food Wrapping Paper Market Vendor Landscape
Global majors compete with regional champions across integrated pulp supply and coating technology dimensions. The market structure shows tiered concentration where Scandinavian forestry-integrated players hold upstream advantages while North American containerboard specialists compete on repurposed linerboard scale. Three archetypes dominate: captive pulp owners with backward integration into sustainable forestry, diversified packaging conglomerates with multi-material portfolios, and specialty converters focused on certified compostable grades. Capacity reconfiguration and coating chemistry reformulation represent the dominant competitive moves as fluorochemical phase-outs accelerate.
Among forestry-integrated players, Huhtamaki Oyj and Mondi Plc exemplify the upstream-control archetype through European mill networks securing kraft pulp for greaseproof grades. WestRock Company occupies a position representing North American scale advantages in containerboard repurposing. These three anchors illustrate how competitive positioning stratifies between fiber-security specialists and volume-driven substrate suppliers.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Mondi Plc |
| Georgia-Pacific LLC |
| International Paper Company |
| WestRock Company |
| Ardagh Group |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
California SB 54 recycling mandates gate qualified supply and premium-tier pricing access, as only certified compostable paper wraps meeting the state's 65% recycling threshold command contract premiums from quick-service chains operating under fixed-price foodservice agreements.
Pricing Analysis
Embedded compliance documentation and migration testing certificates are bundled into base pricing for food-contact grades, while unbundled after-sales technical support and reformulation advisory services create secondary revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates fluorochemical-free certified compostable grades from conventional kraft substrates and generic unbleached alternatives. Price differentiation hinges on FDA food-contact substance notification tier and EU Framework Regulation EC 1935/2004 compliance depth. Cost compression in standard-grade segments is intensifying because pulp price volatility compresses converter margins on fixed-price hospitality contracts. Retail channel procurement teams exhibit highest price sensitivity, while centralized commissary operators at multi-unit restaurant chains prioritize specification compliance over unit cost.
Supply Chain Analysis
Certification and qualification gating through FDA food-contact substance notifications and EU Framework Regulation EC 1935/2004 migration testing creates supply bottlenecks that favor integrated converters with in-house analytical capabilities. Fiber supply concentrates in Finland, Sweden, and Germany, where captive Scandinavian forestry operations anchor kraft pulp availability for greaseproof grades. Raw material dependencies rest on bleached and unbleached kraft pulp, fluorochemical-free barrier coatings, and vegetable-based wax formulations. Single-source vulnerability in specialized coating chemistries intensifies as pending EPA rules and ECHA proposals force reformulation cycles. Distribution runs through packaging distributors serving national quick-service chains with approved vendor lists, replacing fragmented local supply arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Migration testing capacity constraints prop pricing power for integrated converters, as bottlenecked FDA food-contact substance notification approvals delay qualification cycles and concentrate volume with pre-certified suppliers.
For Market Incumbents: Anticipate fluorochemical coating phase-outs by accelerating bio-based barrier R&D partnerships and securing captive pulp supply through Scandinavian forestry acquisitions. Backward integration into sustainable fiber operations defends margin position against virgin pulp price volatility. Pre-certify substrate portfolios for California SB 54 compliance to lock in multi-year quick-service contracts before regulatory deadlines force competitor requalification. For New Entrants and Emerging Players: Capture underpenetrated volume in centralized commissary conversion, where food manufacturers replacing in-store wrapping with pre-portioned branded sheets lack qualified domestic suppliers in India and China. Target Maharashtra and Gujarat food manufacturers with FSSAI-compliant kraft substrates for pre-wrapped sandwich portions. Lead with certified compostable positioning and embedded compliance documentation to bypass lengthy supplier qualification cycles. For Investors and Strategic Acquirers: ECHA proposals tightening persistent organic pollutant restrictions are the leading indicator that coating chemistry reformulation capabilities will command acquisition premiums. Five-to-ten-year viability favors converters with integrated pulp supply and in-house migration testing infrastructure. Target specialty converters focused on certified home-compostable grades with established EU Single-Use Plastics Directive compliance track records. Monitor EPA per- and polyfluoroalkyl substance rulemaking as the inflection signal for accelerated industry consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Forestry | Captive Scandinavian kraft pulp supply secures fiber for greaseproof grades amid price volatility. |
| Bio-Based Barrier Coating Development | Plant-derived polymer integration opens premium positioning for certified home-compostable grades. |
| Pre-Certification Compliance Services | California SB 54 pre-qualification captures value from brands facing 65% recycling mandates. |
| Centralized Commissary Partnership | Food manufacturer conversion from in-store wrapping expands volume in underpenetrated channel. |
| Migration Testing Infrastructure Expansion | In-house FDA and EU Framework Regulation EC 1935/2004 analytical capacity accelerates reformulation cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with packaging converter plant managers, quick-service restaurant procurement directors, food manufacturing supply planners, and coating chemistry R&D leads. FDA food-contact substance notification databases, EU ECHA regulatory proposals, EPA rulemaking dockets, and national packaging ordinance filings provided compliance trajectory inputs. Bottom-up volume modeling across material type, end user, packaging size, and application segments triangulated against top-down macroeconomic indicators.
Granularity-level modeling deployed segment-specific pricing and volume assumptions across material chemistry tiers, end-use channel structures, format specifications, and regional regulatory clusters. CAGRs were derived from regression analysis of historical volume patterns and forward projection of substitution dynamics. Forecast inputs incorporated quick-service restaurant expansion trajectories, pulp price cycle assumptions, and coating chemistry reformulation timelines without specific year anchors.
The model holds under stable regulatory enforcement timelines and intact pulp supply chains; deviation in EPA per- and polyfluoroalkyl substance rulemaking acceleration or Scandinavian forestry disruption would shift volume and value trajectories. Forecasts reflect documented assumptions about substitution rates and qualification cycle durations. A model refresh is warranted upon material change in EU Single-Use Plastics Directive enforcement intensity or California SB 54 recycling rate verification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Air Fryer Paper Liners Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Cushioned Mailer Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Coated Duplex Board Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Coffee Filter Paper Market