
 Honeycomb Mailers Market | 2026-2036
Honeycomb Mailers Market Size, Share, and Industry Trends Forecast 2026-2036
Honeycomb Mailers Market Insights
E-commerce merchants are unwinding decades of plastic-bubble dominance in protective shipping as sustainability procurement criteria harden. DS Smith leverages its European recycled paperboard infrastructure to anchor supply for major online retailers. Ranpak competes through machine-dispensed honeycomb systems that eliminate pre-formed mailer inventory. Smurfit Westrock sustains manufacturing scale across integrated kraft paper mills and converting plants.
Honeycomb mailers are engineered paper-based protective envelopes incorporating a hexagonal-cell cushioning layer, typically formed from 80–150 gsm kraft paper through adhesive-bonded expansion processes that create crush-resistant void structures for fragile goods. Kraft paper dominates material type selection due to established recycling streams and fiber strength, while PLA coated paper occupies niche premium positioning where moisture resistance commands price premiums. Self-sealing mailers lead packaging style adoption in automated fulfillment lines, though expandable mailers capture faster growth in oversized or irregular electronics shipments.
REACH and the EU Green Deal shape material compliance pathways for European suppliers, while the EPA and state-level extended producer responsibility frameworks in California and New York govern US market access. FDA food-contact regulations and FSSC 22000 certification requirements influence honeycomb mailer adoption in food delivery and pharmaceutical transport segments. Stakeholders must monitor evolving single-use plastic bans and fiber sourcing certification standards to anticipate which substrate investments will retain market access across major economies.
Market Dynamics
E-commerce fulfillment networks are dismantling plastic-bubble infrastructure at scale as the EU Packaging and Packaging Waste Regulation mandates recyclable substrates for cross-border shipments. This regulatory-compression dynamic is redrawing supplier relationships and capital allocation across protective packaging value chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclable substrates accelerate paper-based protective format adoption across German and French fulfillment networks.
- Machine-dispensed honeycomb systems:On-demand forming technology eliminates pre-formed mailer inventory carrying costs for mid-size e-commerce merchants.
- Cross-border e-commerce parcel volumes:Sustained expansion in Germany-DHL and Amazon fulfillment corridors standardizes honeycomb protective formats as default specification.
Market Restraints
- Kraft paper input cost volatility:Pulp price swings compress converter margins and destabilize long-term contract pricing with fulfillment networks.
- Moisture sensitivity of uncoated fiber:Technical performance gaps versus plastic alternatives restrict adoption in pharmaceutical cold-chain and frozen food delivery segments.
- Recycled fiber availability concentration:European recycled paperboard supply tightness creates bottleneck risk for converters dependent on post-consumer kraft streams.
Strategic Opportunities
- PLA-coated paper niche expansion:Premium moisture-resistant substrates command price premiums in electronics and pharmaceutical transport where FDA food-contact regulations apply.
- Expandable mailer formats:Irregular and oversized electronics shipments drive faster growth in adjustable-void protective solutions versus fixed-dimension self-sealing alternatives.
- FSSC 22000 certification pathways:Food safety certification unlocks honeycomb mailer adoption in meal-kit and specialty food delivery channels previously served by insulated plastic.
Industry Challenges
- Adhesive-bonding process engineering talent:Shortage of technicians skilled in hexagonal-cell expansion process optimization constrains quality consistency at scale.
- Automated fulfillment line integration:Retrofitting legacy packaging stations for honeycomb mailer handling requires capital-intensive conveyor and sealing system modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honeycomb Mailers Market |
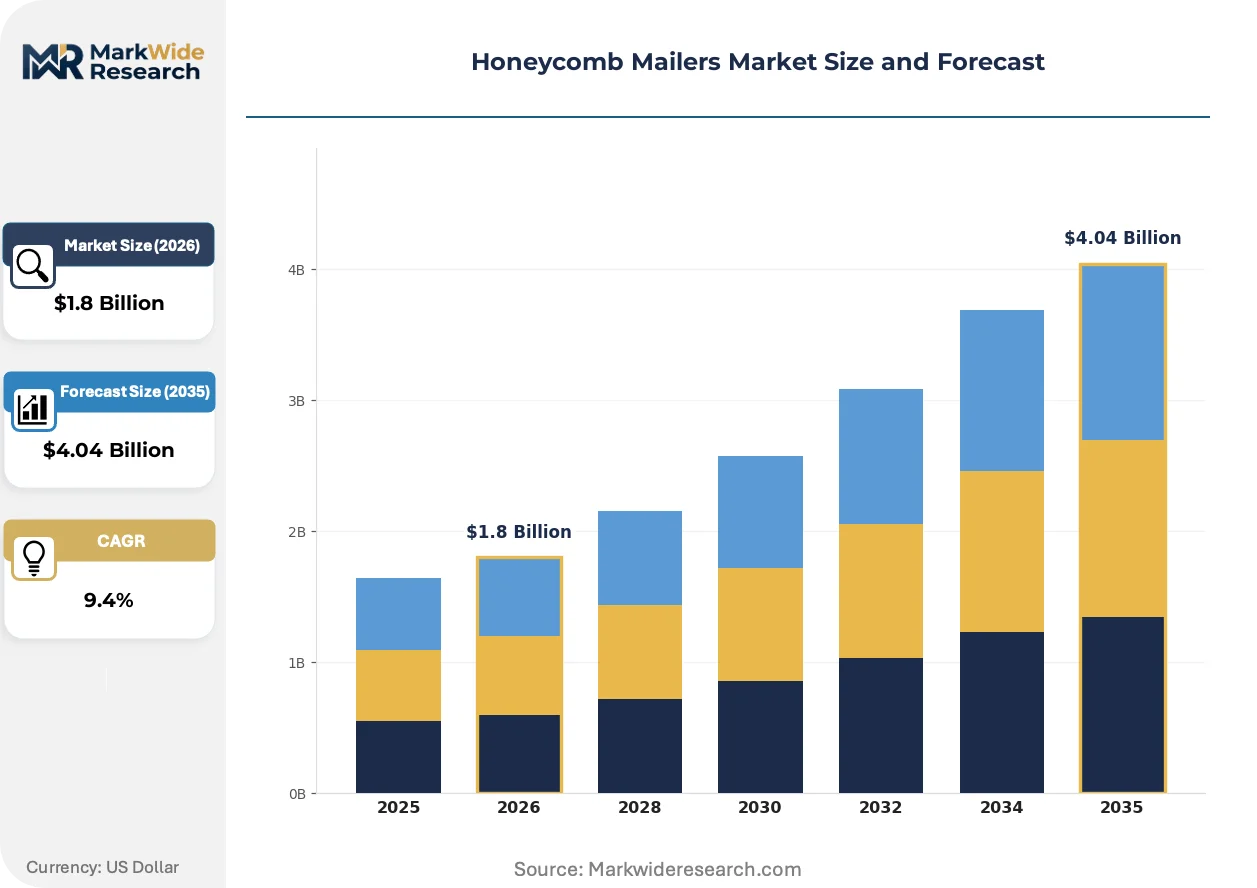
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Recycled Paper, Corrugated Cardboard, Virgin Paper, PLA Coated Paper Application: E-commerce Parcels, Electronics Packaging, Consumer Goods Shipping, Food Delivery, Pharmaceutical Transport End User Industry: Logistics Providers, Retail Merchants, Postal Services, Food Distributors, Pharmaceutical Companies Packaging Style: Flat Mailers, Expandable Mailers, Gusseted Mailers, Self-sealing Mailers, Printed Mailers |
| Companies Covered | Smurfit Westrock, DS Smith, Mondi, Pregis, PAC Worldwide, Ranpak, Sealed Air, Packsize, HUHTAMAKI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honeycomb Mailers Market Trends and Innovations
Active material science development and regulatory compliance automation are restructuring how protective packaging specifications get written and enforced. Technology trajectories are diverging between premium performance tiers and cost-optimized commodity supply.
Machine-dispensed honeycomb forming technology is bifurcating the protective packaging procurement model. On-site expansion systems convert flat kraft paper rolls into three-dimensional cushioning at the point of pack, eliminating finished-goods inventory and freight costs for high-velocity fulfillment centers. Major third-party logistics operators in Germany and the Netherlands are deploying these systems to compress working capital cycles and reduce warehouse square footage dedicated to protective materials storage.
REACH substance restrictions and the EU Green Deal circular economy action plan are tightening material compliance verification requirements for European suppliers. Chemical disclosure obligations and end-of-life recyclability certifications now gate market access for kraft paper converters serving cross-border e-commerce channels. German packaging compliance schemes and French extended producer responsibility frameworks are forcing substrate investments toward certified recyclable fiber streams.
Merchant sustainability scorecards are rewriting supplier selection criteria for protective packaging procurement. Large online retailers now weight carbon footprint metrics and circular material content percentages alongside unit cost in vendor qualification processes. This behavioral shift is most visible in German and UK fulfillment networks where procurement teams are consolidating supplier bases around converters with integrated recycled paperboard mills and third-party chain-of-custody certifications.
Honeycomb Mailers Market Segmentation
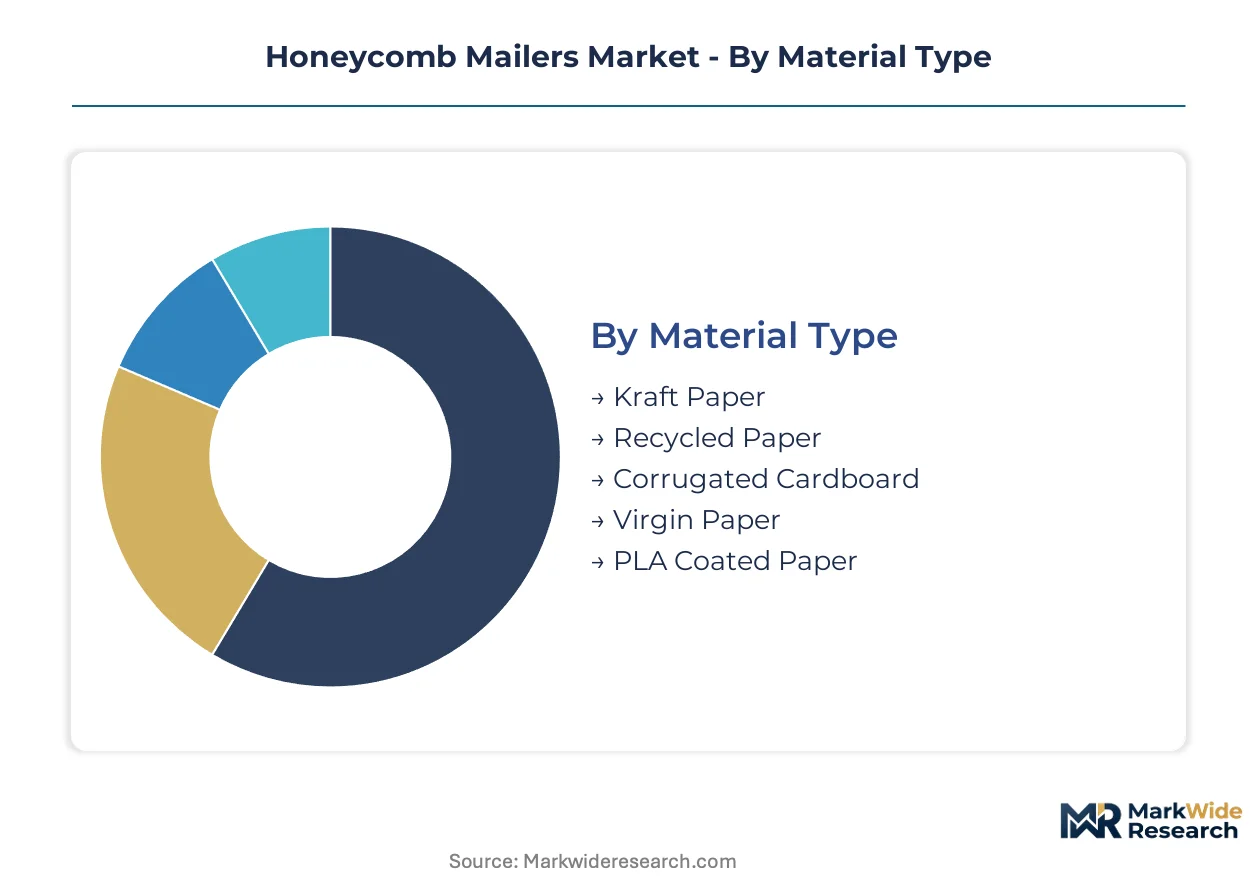
Material specifications and packaging formats in honeycomb mailers determine compliance pathways across EU, US, and Asian regulatory frameworks. End-use applications concentrate demand in e-commerce fulfillment corridors where automated handling requirements and sustainability procurement criteria intersect.
Material Type:
REACH substance restrictions and FDA food-contact regulations create divergent compliance burdens across substrate categories, reshaping converter investment priorities.
- Kraft Paper:Unbleached kraft fiber delivers 80–150 gsm basis weight with established recycling streams and fiber strength for hexagonal-cell expansion. German and French fulfillment networks standardize this substrate for cross-border e-commerce shipments under EU Packaging and Packaging Waste Regulation mandates.
- PLA Coated Paper:Polylactic acid barrier coatings provide moisture resistance for cold-chain applications where uncoated fiber fails. Electronics and pharmaceutical transport segments in the US accept price premiums to meet FDA food-contact regulations and FSSC 22000 certification requirements.
- Recycled Paper:Post-consumer fiber streams face supply tightness in European recycled paperboard markets.
- Corrugated Cardboard:Double-wall fluting alternatives compete in heavy-goods protective applications.
- Virgin Paper:Bleached pulp grades serve premium branding applications with printed surface requirements.
Established volume favors kraft paper; emerging adoption favors PLA coated paper.
Application:
Parcel velocity and handling automation intensity segment demand by fulfillment infrastructure compatibility.
- E-commerce Parcels:High-velocity automated sortation systems process self-sealing honeycomb formats at German DHL and Amazon fulfillment centers. Sustainability scorecards from major online retailers mandate recyclable substrates, displacing plastic bubble mailers at scale.
- Electronics Packaging:Static-dissipative coatings and precision-fit expandable formats protect fragile components during irregular-dimension shipments. Demand concentrates in Netherlands and German logistics corridors serving consumer electronics distribution.
- Consumer Goods Shipping:Mid-weight apparel and accessories drive standardized mailer specifications.
- Food Delivery:FSSC 22000 certification requirements gate entry for meal-kit and specialty food channels.
- Pharmaceutical Transport:Cold-chain moisture sensitivity limits uncoated fiber penetration.
Volume concentration sits with e-commerce parcels; steepest expansion trajectory appears in electronics packaging.
End User Industry:
Procurement scale and sustainability mandate enforcement intensity differentiate customer segments.
- Logistics Providers:Third-party operators in Germany and the Netherlands deploy machine-dispensed honeycomb systems to eliminate pre-formed mailer inventory. On-site expansion technology compresses working capital cycles and reduces warehouse square footage dedicated to protective materials storage.
- Retail Merchants:Large online retailers weight carbon footprint metrics and circular material content percentages alongside unit cost in vendor qualification processes. UK and German procurement teams consolidate supplier bases around converters with integrated recycled paperboard mills.
- Postal Services:National carriers specify standardized formats for interoperability.
- Food Distributors:Meal-kit channels require FSSC 22000 certified substrates.
- Pharmaceutical Companies:FDA compliance pathways favor moisture-resistant coated grades.
Contract scale favors logistics providers; sustainability mandate intensity favors retail merchants.
Packaging Style:
Dimensional adaptability and sealing automation compatibility determine format selection across fulfillment line configurations.
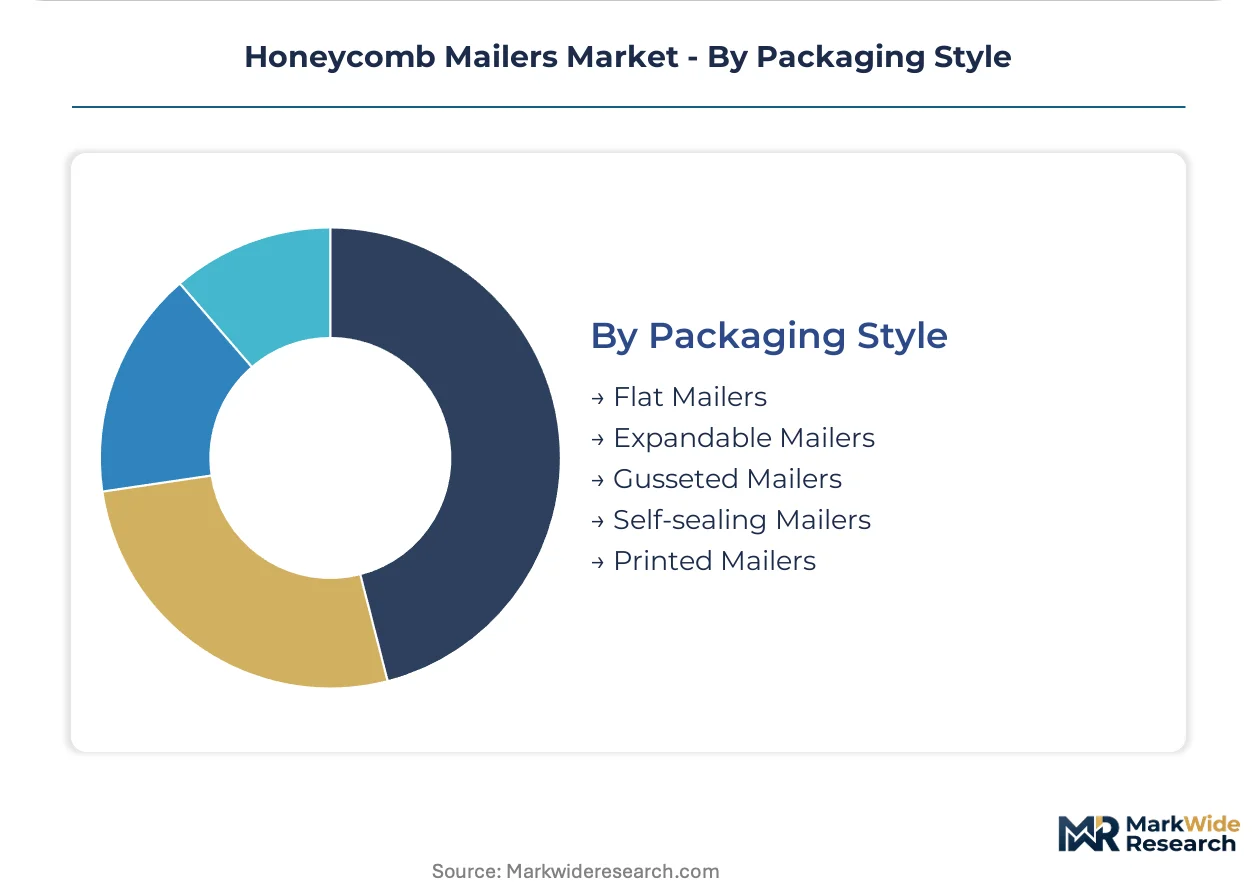
- Self-sealing Mailers:Pressure-sensitive adhesive strips enable single-operator packing at automated fulfillment stations. German and UK e-commerce networks standardize this format for high-velocity operations with minimal handling variation.
- Expandable Mailers:Adjustable-void structures accommodate irregular and oversized electronics shipments. Machine-dispensed forming systems at point-of-pack eliminate finished-goods inventory carrying costs for mid-size merchants.
- Flat Mailers:Fixed-dimension formats suit standardized document and apparel shipments.
- Gusseted Mailers:Side-expansion panels accommodate bulky soft goods.
- Printed Mailers:Surface branding capabilities serve premium unboxing experiences.
Automation penetration favors self-sealing mailers; dimensional flexibility gains favor expandable mailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics providers and retail merchants concentrate procurement power in Germany, the United States, China, and the Netherlands, where e-commerce fulfillment density and regulatory pressure on plastic substrates intersect most intensely.
Germany
DHL and Amazon fulfillment networks standardize honeycomb mailers for cross-border parcel flows. The EU Packaging and Packaging Waste Regulation mandates recyclable substrates, accelerating paper-based protective format adoption. Industrial concentration clusters in North Rhine-Westphalia and Bavaria, where converters with integrated recycled paperboard mills serve standardized procurement specifications.
United States
EPA and state-level extended producer responsibility frameworks in California and New York govern market access for protective packaging suppliers. FDA food-contact regulations shape substrate selection for meal-kit and pharmaceutical transport channels. E-commerce fulfillment density concentrates in the Pacific Northwest and Midwest corridor, where automated sortation systems process high volumes of self-sealing formats.
China
Domestic e-commerce parcel growth drives demand for cost-optimized protective formats in cross-border export channels. MIIT standards and GB packaging regulations establish technical compliance baselines for fiber-based protective materials. Manufacturing gravity centers on the Yangtze River Delta and Pearl River Delta, where kraft paper converters supply both domestic fulfillment networks and export-oriented merchants.
Netherlands
Third-party logistics operators deploy machine-dispensed honeycomb systems to eliminate pre-formed mailer inventory carrying costs. REACH substance restrictions and EU Green Deal circular economy requirements tighten material compliance verification for converters. Rotterdam and Amsterdam logistics corridors anchor deployment of on-site expansion technology for high-velocity fulfillment centers serving EU-wide distribution.
United Kingdom
Retail merchant procurement teams consolidate supplier bases around converters with third-party chain-of-custody certifications. Extended producer responsibility frameworks and plastic packaging tax mechanisms displace bubble mailer infrastructure. Fulfillment concentration in the Midlands and Southeast England drives standardization of recyclable protective formats for domestic and cross-border e-commerce shipments.
Honeycomb Mailers Market Competitive Landscape
Player mix skews toward integrated paperboard producers with captive fiber supply and specialized protective packaging converters with machine-dispensed technology portfolios. Market structure exhibits tiered consolidation, with scale-driven mill-integrated operators commanding standardized contract volumes while technology-focused specialists capture premium positioning through on-site forming systems. Two strategic archetypes dominate: integrated kraft paper producers with backward control over recycled fiber streams, and equipment-integrated solution providers bundling dispensing machinery with substrate supply. Competitive moves concentrate on capacity alignment with e-commerce fulfillment network expansion and certification pathway investments for food-contact and pharmaceutical segments.
Among integrated paperboard producers, Smurfit Westrock and DS Smith exemplify the scale-driven archetype with European mill networks and converting infrastructure. Ranpak occupies a position within the equipment-integrated tier, representing the machine-dispensed technology vector that eliminates pre-formed inventory for mid-size merchants. These three companies anchor the competitive landscape across distinct strategic vectors: fiber-integrated scale, equipment-enabled service models, and regulatory-certified substrate specialization.
| Leading Market Players |
|---|
| Smurfit Westrock |
| DS Smith |
| Mondi |
| Pregis |
| PAC Worldwide |
| Ranpak |
| Sealed Air |
| Packsize |
| HUHTAMAKI |
| Others |
Pricing and Supply Chain Analysis
Mill-integrated converters in Germany and the Netherlands leverage captive kraft pulp supply to anchor price floors across European fulfillment networks, compressing margin structures for non-integrated competitors dependent on spot-market fiber purchases. This scale asymmetry concentrates procurement power among operators with backward control over recycled paperboard streams.
Pricing Analysis
Cost-plus contracts with European pulp indexation dominate long-term agreements between converters and DHL-Amazon fulfillment networks, insulating buyers from spot volatility while squeezing converter margins during input price spikes. Price differentiation rests on FSSC 22000 certification tiers and PLA coating grades for pharmaceutical segments, with logistics providers exhibiting lowest sensitivity due to working-capital savings from machine-dispensed systems. Cost compression in standard kraft mailers is intensifying as Chinese converters penetrate cross-border e-commerce channels.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion ripple through European converter networks, elevating landed costs for Swedish and Finnish pulp imports. Supply concentrates in Germany, China, and the United States, with raw material dependencies centering on post-consumer kraft fiber, starch-based adhesives, and PLA barrier coatings. Single-source vulnerability in European recycled paperboard tightness threatens converter capacity utilization. Distribution runs through mill-direct fulfillment to major logistics operators and merchant converters serving mid-size e-commerce accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Honeycomb mailers function as a platform layer where machine-dispensed technology interoperability rewires procurement relationships between substrate suppliers and fulfillment networks, shifting value capture toward equipment-integrated service models.
For Market Incumbents: Compound scale advantages by locking in long-term fiber supply agreements with Nordic pulp producers before recycled paperboard tightness deepens. Defend against Ranpak-style equipment-integrated entrants by bundling certified substrate supply with on-site forming technology deployment in German and Dutch logistics corridors. Prioritize FSSC 22000 certification investments to gate food-delivery channel access.
For New Entrants and Emerging Players: Lead with PLA-coated paper specialization for pharmaceutical cold-chain segments where moisture sensitivity blocks uncoated fiber penetration. Target US meal-kit distributors and electronics fulfillment networks in the Pacific Northwest where FDA compliance requirements and sustainability procurement criteria intersect. Pursue equipment-as-a-service models that convert capital expenditure to operational expenditure for mid-size merchants.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-integrated solution providers with machine-dispensed technology deployments, as substrate supply contracts tether to multi-year service agreements. Long-term viability favors converters with captive recycled fiber supply and certification pathways for food-contact applications. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as the inflection signal for accelerated plastic displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Supply | Captive post-consumer kraft streams insulate German converters from European paperboard tightness. |
| Machine-Dispensed System Deployment | On-site forming technology eliminates inventory carrying costs for Dutch third-party logistics operators. |
| FSSC 22000 Certification Pathway | Food safety certification unlocks meal-kit channel adoption previously served by insulated plastic. |
| PLA Coating Capacity Addition | Moisture-resistant substrates command price premiums in FDA-regulated pharmaceutical transport segments. |
| Long-Term Supply Agreement with E-Commerce Platforms | Sustainability scorecard alignment secures standardized procurement specifications across German fulfillment networks. |
Research Methodology
A standing panel of procurement directors at major logistics operators, technical sales leads at kraft paper converters, sustainability officers at online retail platforms, and adhesive-bonding process engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance restriction updates, SEC disclosures by integrated paperboard producers, and customs data tracking kraft pulp trade flows. Bottom-up demand modeling across e-commerce parcel volumes triangulated against top-down converter capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled material type, packaging style, application segment, and end-user industry dimensions. CAGRs derived from segment-level growth drivers weighted by procurement intensity in German and US fulfillment corridors. Industry-specific inputs included pulp price indices, e-commerce parcel velocity data, and regulatory compliance cost estimates.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation enforcement and EPA state-level extended producer responsibility frameworks; material policy shifts would require re-modeling. Specific risks include accelerated single-use plastic bans, recycled fiber supply disruptions, and adhesive-bonding technician shortages. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Paper Bag Box Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Waxing Base Paper Market