
 Global Solid Board Market | 2026-2036
Global Solid Board Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solid Board Market Foresight
Recycled pulp is expanding its share in solid board furnish as virgin fiber costs pressure converter margins. Smurfit Westrock leverages integrated recycling infrastructure across European mills to sustain cost-advantaged supply to FMCG customers. Mondi Group anchors its position through specialty kraft board leadership in food-contact applications. Georgia-Pacific LLC competes via scale advantages in North American containerboard-to-solid board conversion lines.
Solid board denotes a paper-based material manufactured from layered pulp fibers compressed into rigid sheets with grammage typically ranging from 200 to 500 gsm, engineered for structural packaging and protective applications. Kraft board dominates industrial shipping applications where burst strength requirements exceed aesthetic specifications. Solid bleached board commands premium positioning in pharmaceutical and cosmetic packaging where surface purity and printability justify higher unit economics. Grayboard occupies mature volume pools in bookbinding and stationery where cost sensitivity limits innovation investment.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications jointly shape material compliance pathways for cross-border packaged goods. REACH chemical restrictions and ECHA substance evaluations further constrain coating and sizing chemistries used in premium grades. Stakeholders must monitor evolving extended producer responsibility schemes and bio-based content verification standards to anticipate sourcing and certification requirements.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing recycled fiber mandates upward while virgin pulp substitution compresses converter cost structures across premium packaging grades.
Growth Catalysts
- REACH chemical restrictions:ECHA substance evaluations are accelerating coating chemistry innovation in pharmaceutical solid board applications, creating compliant supply advantages for early-adopting converters.
- Cosmetic brand sustainability pledges:L'Oréal and Estée Lauder procurement teams are specifying solid bleached board with minimum 80% recycled content for secondary packaging across European product lines.
- Rhineland converter cluster density:Germany's packaging corridor concentrates finishing capacity within 150 kilometers of major FMCG brand headquarters, compressing logistics costs and sample turnaround times.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing 40% annually across European spot markets, eroding margin predictability for recycled-content board producers.
- Nordic pulp mill concentration:Four integrated groups control 70% of bleached kraft pulp supply to solid board furnish, creating bottleneck risk during maintenance cycles or energy price spikes.
- Plastic barrier substitution limits:Polyethylene extrusion coatings face ECHA microplastic restrictions that currently lack viable bio-based alternatives at commercial scale.
Strategic Opportunities
- India pharmaceutical export packaging:CDSCO and DGFT alignment on EU-equivalent material certifications is opening solid bleached board demand from Mumbai and Hyderabad formulation hubs.
- Digital print convergence with barrier coatings:Inkjet primers compatible with grease-resistant sizing chemistries are enabling short-run customization for regional food brands.
- Extended producer responsibility schemes:France's Citeo and Germany's ZSVR fee structures reward higher recycled content, tilting procurement toward certified circular board grades.
Industry Challenges
- Food-contact notification timelines:FDA substance notifications for novel sizing chemistries average 18-24 months, delaying premium grade launches in North American markets.
- Legacy calendering equipment retrofit costs:Converting lines built for 300 gsm containerboard require seven-figure capital outlays to handle 500 gsm solid board without web breaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solid Board Market |
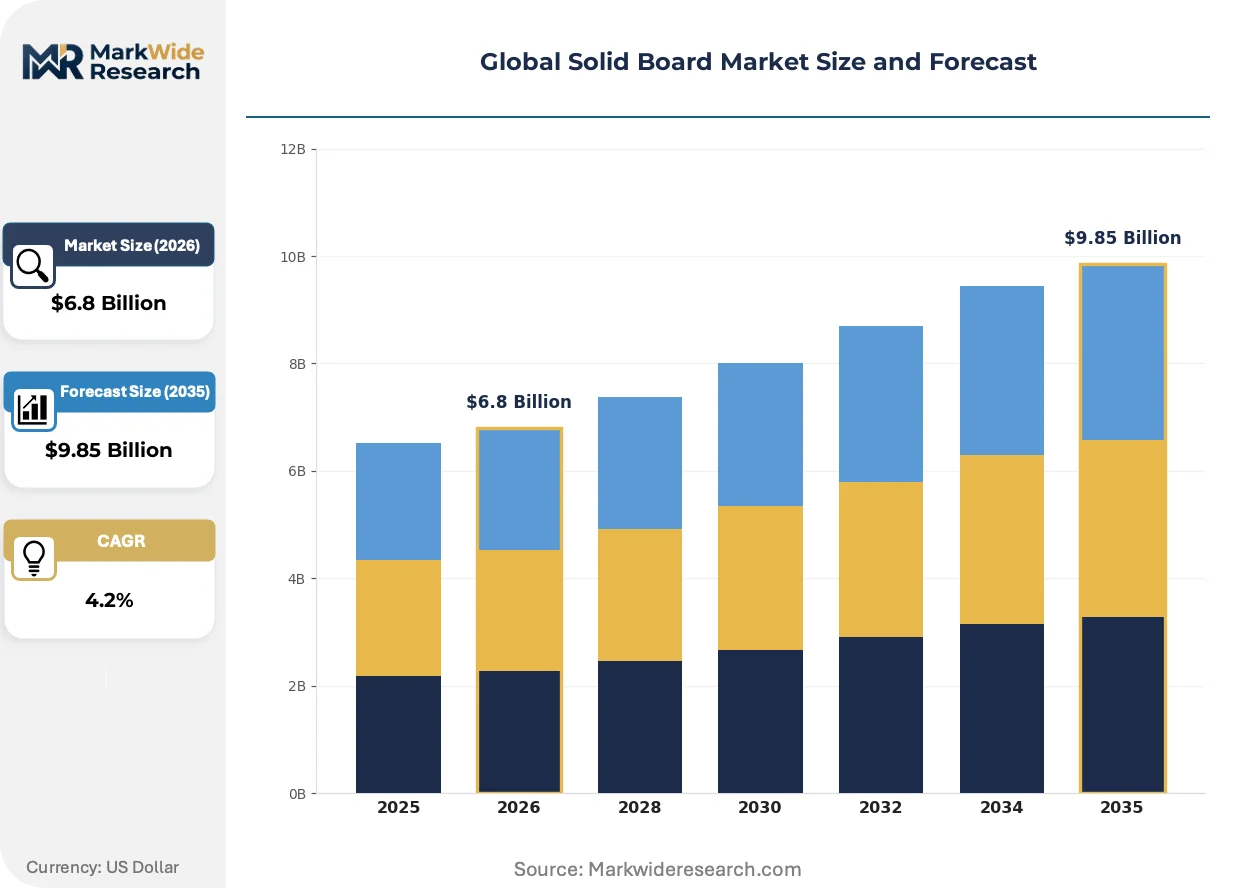
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grayboard, White Lined Chipboard, Kraft Board, Solid Bleached Board, Duplex Board Application: Packaging Boxes, Point of Sale Displays, Book Covers, Electrical Items, Cosmetics Cases End User Industry: Food & Beverage, Pharmaceuticals, Personal Care, Electronics, Home Furnishing Distribution Channel: Direct Sales, Distributors, E-Commerce, Wholesale Suppliers, Retail Chains |
| Companies Covered | International Paper Company, Mayr-Melnhof Karton AG, Smurfit Westrock, Mondi Group, DS Smith Packaging Limited, Stora Enso, Billerud, Rengo Co. Ltd, Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solid Board Market Shifts & Advancements
Digital manufacturing and regulatory chemistry constraints are reshaping how solid board converters configure production assets and specify raw material furnish.
Water-based barrier coatings are decentralizing the geographic distribution of food-contact solid board production. Smaller regional converters in Poland and the Czech Republic are adopting these chemistries to bypass centralized PE extrusion capacity. This technology is decentralizing supply patterns that previously concentrated premium grades near major coating lines.
REACH microplastic restrictions are eliminating conventional extruded polyethylene barriers from cosmetic and food packaging by 2030. ECHA restriction proposals force converters to qualify bio-based alternatives or lose access to premium segments. German pharmaceutical packagers are accelerating trials of polysaccharide-based grease barriers to maintain EU market access.
Brand procurement teams are consolidating supplier panels around certified circular material traceability. Unilever and Nestlé packaging directors now require mass-balance documentation from solid board vendors, displacing spot-market purchasing. This consolidation is most visible in the Netherlands and Belgium where brand headquarters density enables direct supplier auditing.
Global Solid Board Market Segmentation
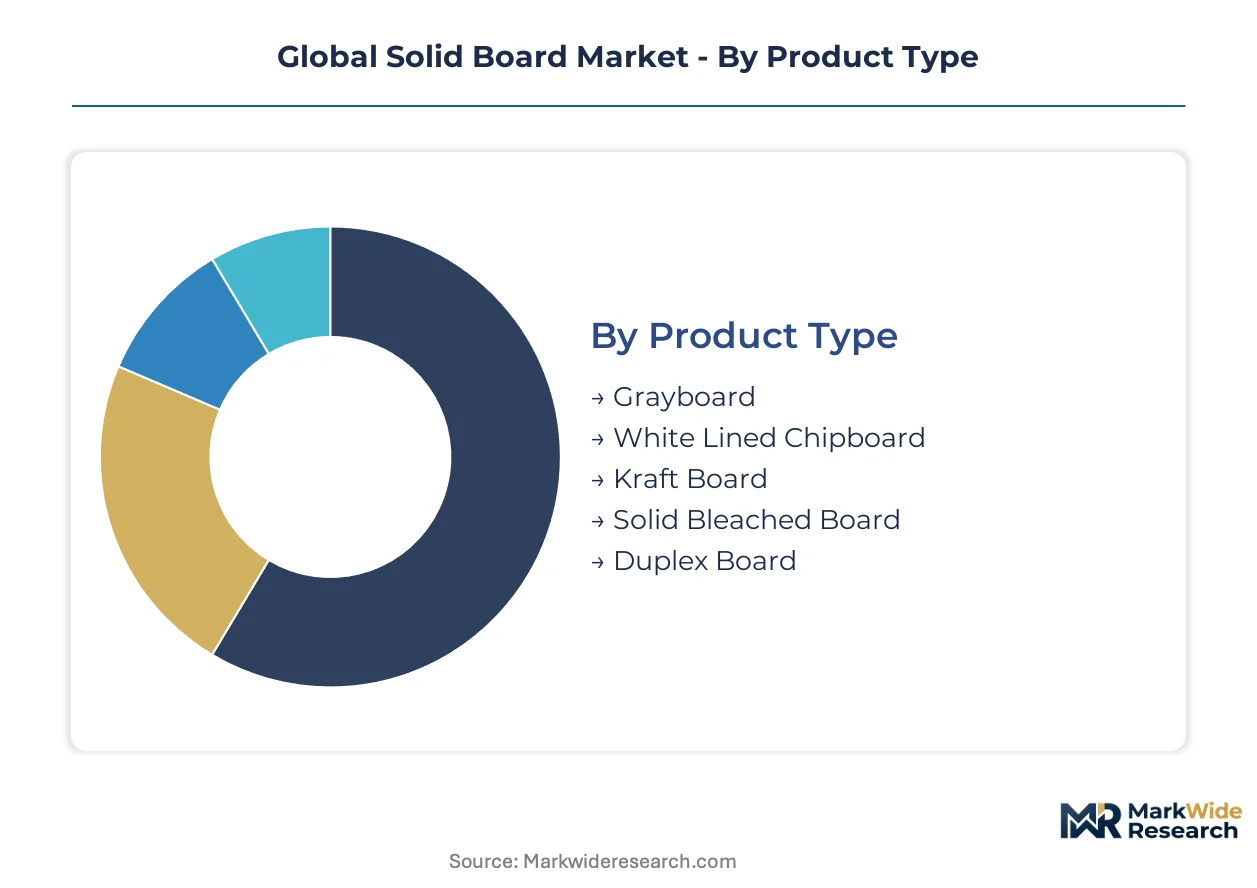
Solid board segmentation reflects divergent capital requirements across furnish types and the geographic clustering of converter capacity. Understanding these splits reveals where margin compression hits hardest and where specialty premiums persist.
Product Type:
Capital intensity varies dramatically across furnish grades, with bleached kraft pulping and multi-layer coating lines demanding the heaviest upfront investment.
- Solid Bleached Board:Manufactured from bleached chemical pulp with clay-coated surfaces achieving 150-400 gsm, this grade commands pharmaceutical and cosmetic applications where FDA food-contact notifications and ECHA REACH compliance create regulatory moats. Germany's Rhineland cluster concentrates finishing capacity for L'Oréal and Estée Lauder procurement teams specifying minimum 80% recycled content.
- Kraft Board:Unbleached sulfate pulp construction delivers burst strength exceeding 3.5 MPa for industrial shipping applications. Demand concentrates in German automotive component packaging and Dutch agricultural export logistics where structural rigidity outweighs surface aesthetics.
- Grayboard:Recycled fiber furnish with gray backing serves bookbinding and stationery markets where cost sensitivity limits coating investment.
- White Lined Chipboard:Grayboard core with white top liner targets consumer goods secondary packaging balancing printability against unit economics.
- Duplex Board:Two-ply construction with coated white face and gray reverse serves folding carton applications in India's pharmaceutical export sector.
Most installed capacity flows through Kraft Board. Expansion is steepest in Solid Bleached Board.
Application:
Application mix tracks directly to end-use durability requirements and print sophistication needs.
- Packaging Boxes:Structural containers ranging from 250-500 gsm dominate food-contact and industrial logistics, with water-based barrier coatings enabling regional Polish and Czech converters to bypass centralized PE extrusion capacity.
- Cosmetics Cases:Rigid set-up boxes with foil stamping and embossing surfaces serve premium fragrance and skincare launches where Unilever and Nestlé procurement teams now require mass-balance documentation.
- Point of Sale Displays:Temporary retail fixtures prioritize cost-minimization over longevity.
- Book Covers:Grayboard-backed cases occupy mature educational publishing demand pools.
- Electrical Items:Anti-static coatings and dielectric properties define specification requirements.
Volume concentrates in Packaging Boxes. Cosmetics Cases are gaining share fastest.
End User Industry:
Industry verticals impose distinct certification burdens that filter supplier eligibility.
- Pharmaceuticals:FDA substance notifications and EMA compliance documentation govern primary and secondary packaging for CDSCO-aligned Indian export hubs in Mumbai and Hyderabad, where solid bleached board demand is accelerating.
- Food & Beverage:EFSA migration limits and FDA food-contact substance notifications constrain coating chemistry selection, with France's Citeo and Germany's ZSVR extended producer responsibility schemes rewarding certified circular grades.
- Personal Care:Brand sustainability pledges drive recycled content minimums.
- Electronics:Anti-static and moisture barrier specifications dominate.
- Home Furnishing:Cost-driven furniture backing applications.
Food & Beverage consumes the most tonnage. Pharmaceuticals shows the steepest expansion trajectory.
Distribution Channel:
Channel structure reflects customer scale and specification complexity.
- Direct Sales:Converter-to-brand relationships dominate pharmaceutical and cosmetic procurement where technical service and certification documentation requirements exceed distributor capabilities. Germany's ZSVR and France's Citeo fee structures require direct mass-balance verification.
- Distributors:Inventory pooling serves mid-tier converters with predictable grayboard and kraft board needs across Benelux packaging corridors.
- E-Commerce:Sample and short-run fulfillment for digital print convergence trials.
- Wholesale Suppliers:Volume aggregation for commodity grades.
- Retail Chains:Stationery and craft segment access.
Direct Sales channels handle the most volume. E-Commerce is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland packaging corridor anchors converter capacity for European pharmaceutical and cosmetic brands. Recycled fiber mandates from Brussels and cost pressures on virgin pulp are redrawing procurement geography across the analysis window.
Germany
Automotive component packagers and FMCG brand headquarters cluster in the Rhineland corridor between Cologne and Düsseldorf. The ZSVR extended producer responsibility scheme rewards mass-balance certified circular grades. Smurfit Westrock and Mayr-Melnhof Karton AG operate integrated mills feeding converter networks within 150 kilometers of L'Oréal and Estée Lauder procurement teams.
United States
FDA food-contact substance notifications govern coating chemistry selection for pharmaceutical and food-contact solid board grades. Georgia-Pacific LLC leverages scale advantages in containerboard-to-solid board conversion lines across southeastern mill networks. The EPA oversees chemical safety for water-based barrier coatings displacing conventional PE extrusion.
India
CDSCO alignment with EU-equivalent material certifications is accelerating solid bleached board demand from Mumbai and Hyderabad formulation hubs. The DGFT facilitates export packaging compliance for pharmaceutical exporters targeting European markets. Domestic converters are qualifying water-based barrier chemistries to serve regional food brands.
France
Citeo fee structures under extended producer responsibility schemes tilt procurement toward certified circular board grades. Cosmetic brand sustainability pledges from L'Oréal procurement teams specify minimum recycled content thresholds. The ANSM oversees pharmaceutical packaging material compliance for domestic and export markets.
Poland
Regional converters are adopting water-based barrier coatings to bypass centralized PE extrusion capacity concentrated in western Europe. ECHA REACH restrictions on microplastics are eliminating conventional extruded polyethylene barriers from cosmetic and food packaging by 2030. Warsaw and Łódź packaging corridors serve as lower-cost finishing alternatives to German clusters.
Global Solid Board Market Competitive Landscape
Global majors compete with regional champions across furnish integration and converter network density. The vendor base separates into three tiers: integrated pulp-to-board operators with captive recycling infrastructure, specialty kraft board specialists serving food-contact applications, and regional converters leveraging digital print convergence for short-run customization. Consolidation pressures favor backward integration into OCC collection networks and coating chemistry qualification. Strategic moves center on M&A for recycling assets and capacity expansion in water-based barrier coating lines.
Within the integrated operator tier, Smurfit Westrock and Mondi Group exemplify archetypes of furnish-advantaged supply to FMCG customers. Smurfit Westrock leverages European mill networks with captive recycling infrastructure. Mondi Group anchors specialty positioning through kraft board leadership in food-contact applications. Mayr-Melnhof Karton AG represents the regional champion model with concentrated converter relationships in Central European packaging corridors.
| Leading Market Players |
|---|
| International Paper Company |
| Mayr-Melnhof Karton AG |
| Smurfit Westrock |
| Mondi Group |
| DS Smith Packaging Limited |
| Stora Enso |
| Billerud |
| Rengo Co. Ltd |
| Georgia-Pacific LLC |
| Others |
Supply & Pricing Matrix
Family-owned European mid-caps anchor converter capacity in Germany's Rhineland corridor, transmitting OCC cost volatility directly into contract renegotiations with FMCG procurement teams. Their concentrated mill ownership patterns enforce pricing discipline across bleached kraft grades while fragmenting negotiation leverage in grayboard commoditized tiers.
Pricing Analysis
Input-cost pass-through from Nordic pulp mills governs solid bleached board quotations, with bleached chemical pulp swings transmitted quarterly into converter contracts. Three-tier pricing structure across pharmaceutical-grade certified, food-contact standard, and industrial economy levels differentiates by ECHA REACH compliance tier and FDA notification status. Pricing pressure stems from OCC spot volatility eroding recycled-content margins. Pharmaceutical buyers show least price sensitivity; bookbinding grayboard purchasers compress suppliers most aggressively.
Supply Chain Analysis
Bleached kraft pulp supply rests on Finnish and Swedish integrated mill networks feeding furnish to Rhineland converters. OCC feedstock draws from German municipal collection systems and Benelux industrial waste streams; coating chemistries source from German and Swiss specialty chemical producers. Single-source vulnerability concentrates in Nordic pulp concentration where four groups control majority supply. Distribution runs through converter-to-brand direct sales for certified grades, with distributors pooling commodity grayboard inventory across Central European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Solid Board Market compounds steadily as regulatory mandates for recycled content create structural demand floors. Extended producer responsibility schemes in France and Germany institutionalize premium pricing for mass-balance certified grades.
For Market Incumbents: Hedge against OCC volatility through captive recycling infrastructure investments in Poland and Czech Republic collection networks. Defend pharmaceutical-grade positioning by accelerating FDA food-contact substance notifications for novel water-based barrier chemistries before ECHA microplastic restrictions eliminate PE extrusion alternatives. For New Entrants and Emerging Players: Launch via digital print convergence partnerships serving regional Polish and Czech food brands seeking short-run customization with grease-resistant sizing. Target India's pharmaceutical export packaging corridor where CDSCO-EU alignment creates certification demand unmet by domestic converter capacity; qualify water-based barrier coatings to bypass centralized western European PE extrusion bottlenecks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters with underutilized calendering capacity capable of 500 gsm solid board handling. Five-to-ten-year viability favors assets with backward integration into OCC collection and coating chemistry qualification pipelines. Watch ECHA restriction timeline acceleration as inflection signal for bio-based barrier coating adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Captive feedstock supply insulates margin from spot volatility in German and Benelux markets. |
| Water-Based Barrier Coating Qualification | ECHA microplastic restrictions by 2030 eliminate PE extrusion alternatives for food-contact grades. |
| Digital Print Convergence Partnership | Inkjet primer compatibility with grease-resistant sizing unlocks short-run regional food brand demand. |
| CDSCO-Aligned Certification Investment | EU-equivalent material documentation opens pharmaceutical export packaging from Mumbai and Hyderabad hubs. |
| Mass-Balance Certification Program | France's Citeo and Germany's ZSVR fee structures reward verified circular content with procurement preference. |
Research Methodology
Direct dialogue with solid board mill operations managers, pharmaceutical packaging procurement directors at L'Oréal and Estée Lauder, FMCG sustainability leads at Unilever and Nestlé, and Rhineland converter technical directors grounded qualitative findings. Secondary validation drew from ECHA restriction proposals, FDA food-contact substance notification databases, EU Packaging and Packaging Waste Regulation impact assessments, and Citeo/ZSVR extended producer responsibility fee schedules. Bottom-up capacity modeling triangulated against top-down demand segmentation.
Segmentation outputs across product type (solid bleached board, kraft board, grayboard, white lined chipboard, duplex board), application (packaging boxes, cosmetics cases, point of sale displays), end-use industry (pharmaceuticals, food and beverage, personal care), and distribution channel (direct sales, distributors, e-commerce) fed analytical framework construction across the projection horizon. CAGRs derived from furnish cost trajectory modeling and regulatory mandate implementation schedules. Forecast inputs incorporated OCC price volatility bands and ECHA restriction timeline scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA microplastic restriction enforcement or Nordic pulp mill supply disruptions. Projections reflect assumptions regarding recycled content mandate compliance timelines and water-based barrier coating commercial scale-up rates. A small set of named triggers—ECHA restriction acceleration, FDA notification backlog resolution, India CDSCO-EU alignment completion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Japan Paper Packaging Market