
 Impregnated Paper Market | 2026-2036
Impregnated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Impregnated Paper Market Foresight
Modular surfacing kits that bundle impregnated paper layers with pre-cut substrate panels is realigning buyer choice across the furniture and interior fit-out sectors. Ahlstrom-Munksjö leverages its integrated pulp-to-paper operations to control resin saturation consistency across specialty grades. Schattdecor AG anchors European decorative paper supply through dedicated print and impregnation lines serving laminate flooring producers. Koehler Paper Group competes via thermal transfer and electrical insulation papers where phenolic resin loading meets IEC standards.
Impregnated paper consists of a cellulose base sheet saturated with thermosetting resins such as melamine, phenol-formaldehyde, or urea-formaldehyde, then cured under heat and pressure to create a hard, wear-resistant surface layer. The resin loading typically ranges from 30% to 60% by weight depending on the end-use performance requirement, with higher phenolic content specified for electrical insulation applications. Decorative paper and melamine paper lead product type volumes due to laminate flooring and furniture OEM demand, while phenolic paper captures premium margin pools in electrical insulation for transformers and motors. Rolls dominate form factor shipments for continuous press operations, though custom-sized sheets gain traction in automated furniture manufacturing lines seeking reduced cutting waste.
REACH in Europe restricts formaldehyde emissions and hazardous substance content in resin formulations, while China's GB standards enforce emission class limits for interior building materials. The EU F-Gas Regulation indirectly pressures manufacturers by limiting fluorinated compounds used in certain coating adjuncts. Stakeholders must monitor evolving resin chemistry restrictions and certification requirements across multiple jurisdictions to maintain product access and avoid reformulation costs.
Market Dynamics
Resin chemistry standardization across China, Germany, and the United States is compressing formulation flexibility while elevating compliance costs for cross-border suppliers. REACH formaldehyde limits and China's GB emission classes now dictate upstream R&D allocation.
Growth Catalysts
- GB Standards Enforcement:China's mandatory emission class limits for interior building materials are accelerating melamine-impregnated paper substitution for untreated decorative surfaces in furniture manufacturing.
- Modular Surfacing Kits:Pre-bundled impregnated paper layers with substrate panels are capturing specification share from standalone decorative paper procurement in European interior fit-out projects.
- Electrical Insulation Demand:Phenolic resin-impregnated papers meeting IEC thermal standards are displacing film-based insulation in transformer and motor rebuild programs across industrial maintenance channels.
Market Restraints
- Formaldehyde Input Volatility:Urea-formaldehyde resin costs fluctuate with methanol and natural gas pricing, squeezing margin predictability for decorative paper grades.
- Specialty Pulp Concentration:Alpha-cellulose supply for electrical insulation papers concentrates in Nordic and Canadian pulp operations, creating geographic single-source exposure.
- Substitution by Digital Printing:Direct-to-substrate UV printing is capturing short-run decorative applications previously served by melamine-impregnated overlay papers.
Strategic Opportunities
- India Building Materials Code:BIS adoption of stricter formaldehyde limits for plywood and particleboard creates first-mover positioning for compliant melamine paper suppliers.
- Bio-Based Resin Convergence:Lignin-derived thermosetting resins paired with cellulose substrates offer carbon-accounting advantages for LEED-certified commercial construction specifications.
- Automated Furniture Lines:Custom-sized sheet formats replacing standard rolls reduce cutting waste and align with robotic panel processing investments by German and Italian OEMs.
Industry Challenges
- Resin Formulation Talent Scarcity:REACH-compliant low-emission chemistry expertise concentrates among senior chemists at established European compounders, constraining new entrant R&D velocity.
- Continuous Press Retrofit Costs:Converting roll-fed lines to handle precision-cut sheet formats requires capital outlay that mid-tier laminate flooring producers defer amid margin pressure.
- Multi-Jurisdiction Certification Lag:Simultaneous GB, REACH, and CARB compliance testing extends product launch timelines by 8-14 months for decorative paper innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impregnated Paper Market |
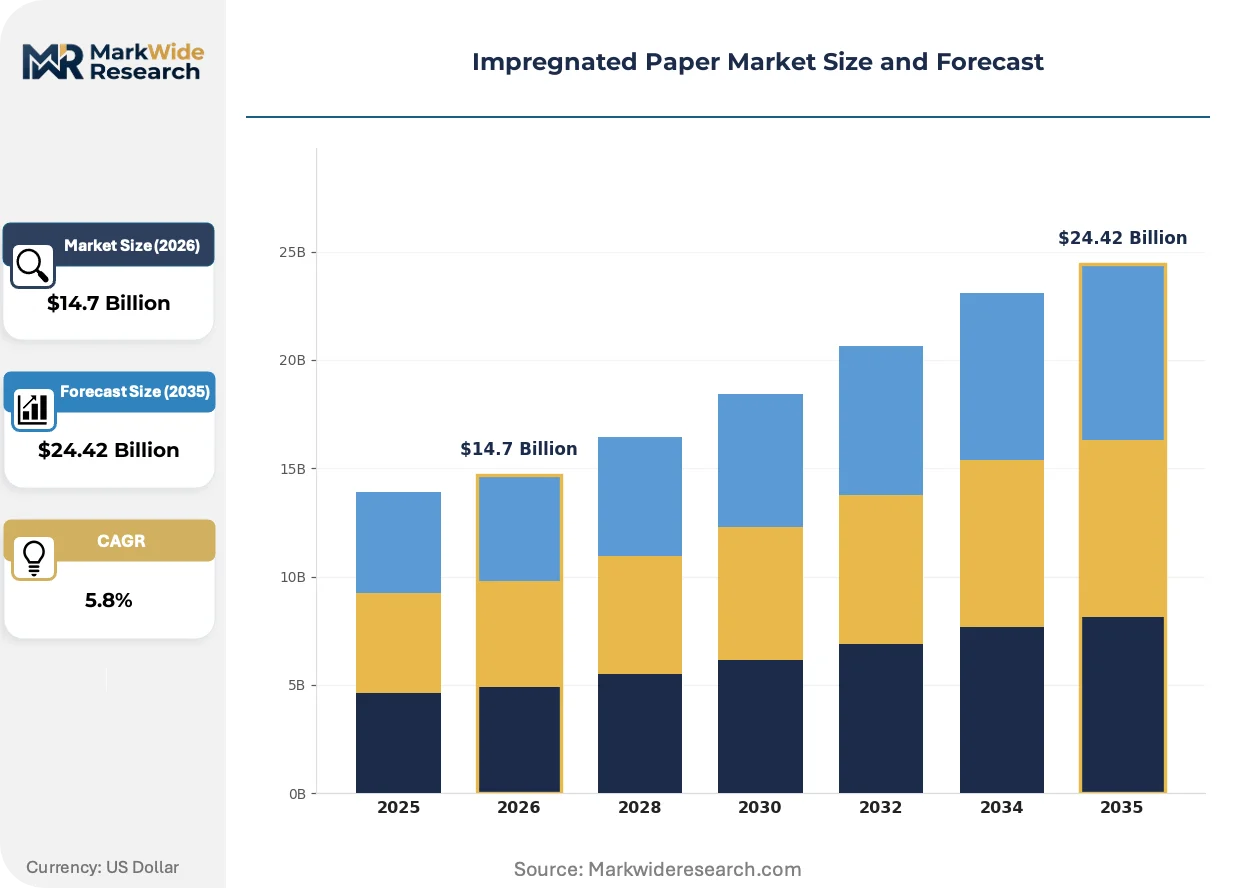
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Paper, Laminated Paper, Phenolic Paper, Melamine Paper Application: Furniture, Wall Panels, Flooring, Electrical Insulation End User: Construction, Automotive, Electronics, Furniture Manufacturing Form: Sheets, Rolls, Custom Sizes, Coated |
| Companies Covered | Ahlstrom-Munksjö, Surteco Group SE, Schattdecor AG, Starwood, Dekodur GmbH, Impress Surfaces GmbH, Felix Schoeller Group, Koehler Paper Group, Awa Paper Mfg. Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impregnated Paper Market Shifts & Advancements
Digital workflow integration between print design studios and impregnation lines is collapsing traditional sample-to-production lead times. Real-time color matching and resin saturation control now differentiate operational performance.
Near-infrared spectroscopy for resin weight monitoring is converging with closed-loop press control systems. Laminate flooring producers in Germany and China are installing inline sensors at pilot scale. This convergence is compressing quality variance and reducing off-spec batch rates in continuous press operations.
REACH authorization requirements for formaldehyde-releasing substances are tightening resin disclosure obligations across the EU supply chain. Impregnators must now document resin composition down to sub-component CAS levels. Decorative paper grades for kitchen and bathroom applications face the steepest compliance cost escalation as ECHA evaluates additional substance restrictions.
Furniture OEM procurement teams are consolidating supplier panels and demanding mill-direct relationships bypassing regional distributors. Italian and Polish kitchen cabinet manufacturers now specify volume commitments with penalty clauses for specification drift. This consolidation is visible most acutely in engineered wood panel supply chains serving European retail chains.
Impregnated Paper Market Segmentation
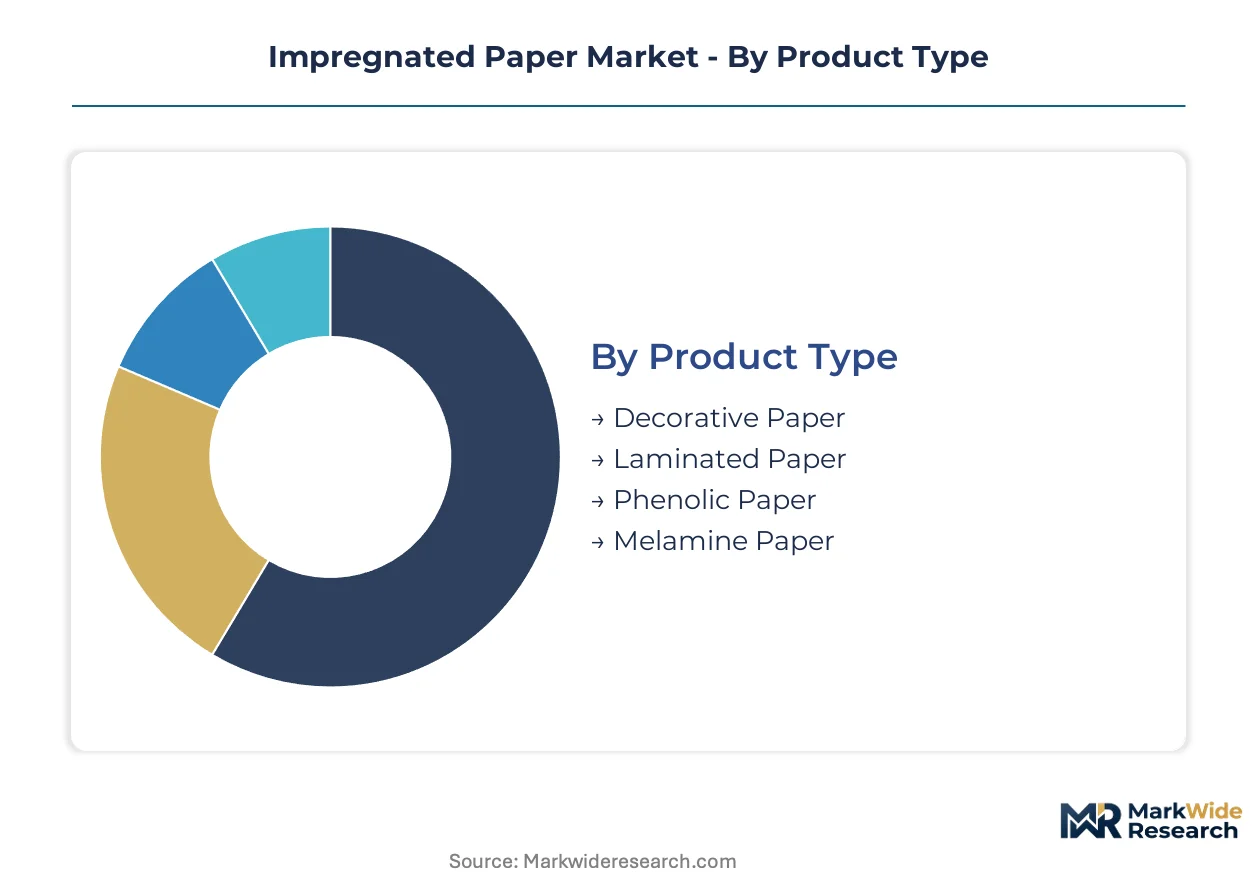
Impregnated paper buyers segment procurement by performance grade, regulatory compliance tier, and manufacturing integration depth. Specification divergence between laminate flooring producers and electrical insulation OEMs creates distinct demand clusters with incompatible resin chemistry requirements.
Product Type:
Buyers in this category differentiate by surface durability requirements and emission compliance thresholds rather than base paper weight alone.
- Melamine Paper:Saturated with melamine-formaldehyde resin at 40-60% loading by weight, this grade delivers scratch-resistant surfaces for high-traffic flooring applications. Demand concentrates among Chinese laminate flooring producers serving domestic retail chains as GB emission class enforcement accelerates substitution for untreated decorative overlays. REACH-compliant low-emission formulations command 15-20% procurement premiums from German kitchen cabinet manufacturers.
- Decorative Paper:Base sheets printed with wood grain or solid-color designs before melamine saturation, typically specified at 30-45% resin loading for furniture and wall panel applications. Italian and Polish engineered wood panel producers dominate volume procurement, with Ahlstrom-Munksjö and Schattdecor AG controlling mill-direct supply relationships. Digital print-to-impregnation workflow integration is collapsing sample-to-production lead times from weeks to days.
- Phenolic Paper:High-phenolic resin content (50-65% by weight) meets IEC thermal endurance standards for transformer and motor insulation. Alpha-cellulose pulp sourcing from Nordic and Canadian operations creates geographic supply concentration.
- Laminated Paper:Multi-layer constructions bonding impregnated papers to substrate cores under heat and pressure, specified where dimensional stability exceeds single-layer performance.
Melamine paper leads volumes today; phenolic paper is gaining share fastest on electrical infrastructure replacement cycles.
Application:
End-use specification intensity varies by wear exposure and regulatory scrutiny, with flooring and electrical applications commanding the tightest resin chemistry tolerances.
- Flooring:Melamine-impregnated overlay papers bonded to HDF cores create wear layers rated AC3-AC5 under EN 13329. German and Chinese producers operate continuous press lines consuming roll formats exclusively. Real-time resin weight monitoring via near-infrared spectroscopy is differentiating operational performance at pilot installations.
- Electrical Insulation:Phenolic resin-impregnated papers meeting IEC 60864 thermal class requirements displace film-based insulation in transformer rebuild programs. Motor rewind shops and industrial maintenance channels specify thickness tolerances of ±0.02mm for slot liner applications.
- Furniture:Decorative melamine papers for engineered wood panels face formaldehyde emission scrutiny under CARB ATCM and GB standards. Kitchen and bathroom applications encounter the steepest compliance cost escalation as ECHA evaluates additional REACH substance restrictions.
- Wall Panels:Lower resin loading specifications (30-40% by weight) serve interior fit-out applications where abrasion resistance requirements moderate.
Flooring dominates current procurement volumes; electrical insulation shows the steepest expansion trajectory on grid infrastructure investment.
End User:
Customer sophistication spans from commodity volume buyers to specification engineers demanding sub-component CAS-level resin documentation.
- Furniture Manufacturing:OEM procurement teams consolidate supplier panels and impose volume commitments with penalty clauses for specification drift. Italian kitchen cabinet producers now specify mill-direct relationships bypassing regional distributors.
- Construction:Modular surfacing kits bundling impregnated paper layers with pre-cut substrate panels capture specification share from standalone decorative paper procurement in European interior fit-out projects.
- Electronics:Transformer and motor OEMs specify phenolic insulation papers with documented thermal endurance under IEC standards, requiring sub-component CAS-level resin disclosure under REACH authorization requirements.
- Automotive:Limited penetration in interior trim applications where thermoplastic alternatives dominate on weight and recyclability metrics.
Furniture manufacturing anchors demand today; construction end-use is expanding most quickly on modular kit specification.
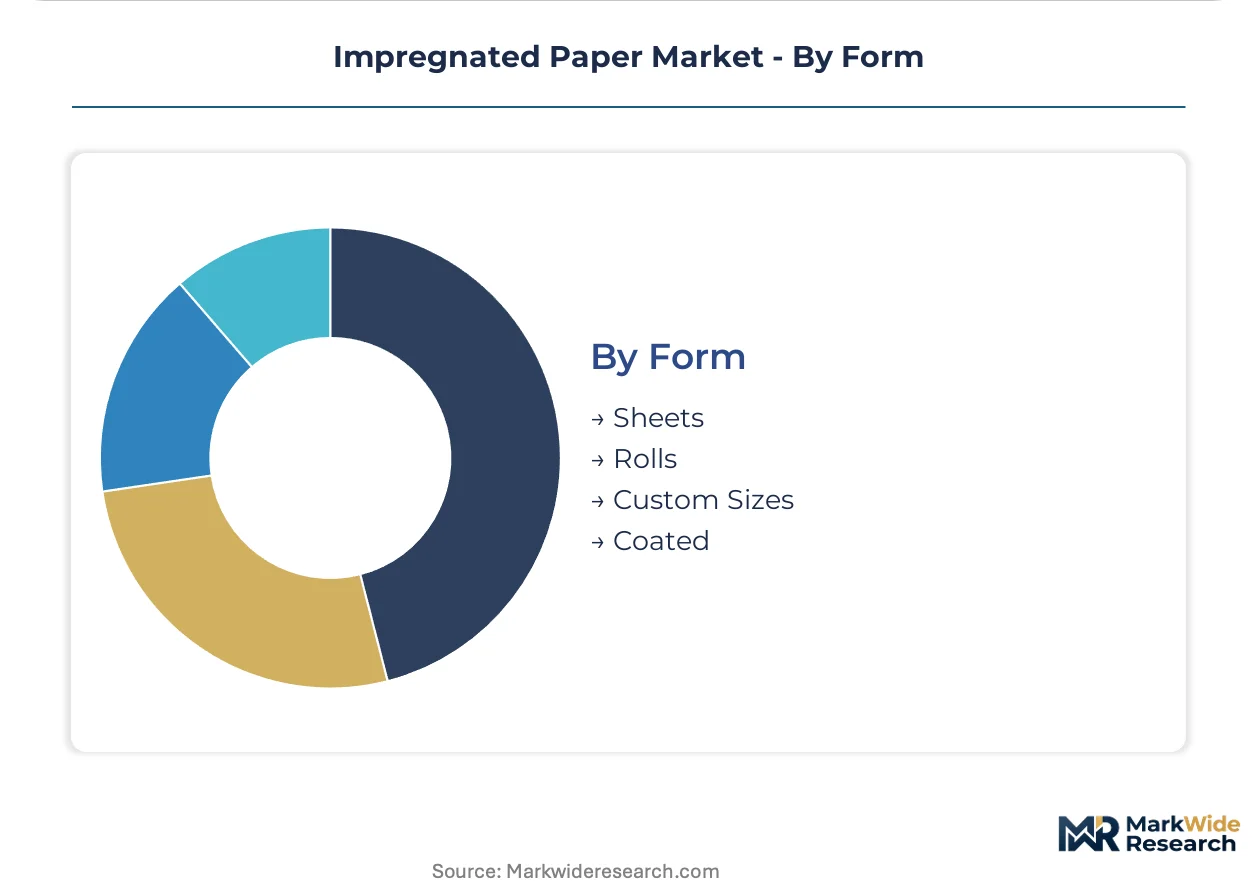
Form:
Manufacturing automation investments are shifting format preferences from continuous rolls toward precision-cut sheets in furniture supply chains.
- Rolls:Standard format for continuous press operations in laminate flooring production, with widths matched to press platen dimensions. German and Chinese producers maintain roll-fed lines as baseline configuration.
- Sheets:Custom dimensions reducing cutting waste align with robotic panel processing investments by German and Italian furniture OEMs. Format conversion requires capital outlay that mid-tier producers defer amid margin pressure.
- Custom Sizes:Automated furniture manufacturing lines specify tolerances of ±1mm for robotic gripping and placement operations.
- Coated:Pre-finished surfaces with cured resin layers delivered ready for direct lamination, compressing downstream processing steps.
Rolls maintain volume leadership today; custom sheet formats are climbing the fastest on automation investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The impregnated paper industry traces its industrial-scale origins to German laminate flooring clusters that pioneered continuous press saturation lines. Production expertise subsequently diffused to China through technology licensing agreements in the 1990s. Today manufacturing concentrates in five countries that collectively host over 80% of global decorative and electrical insulation paper capacity.
China
Domestic laminate flooring producers drive melamine paper consumption as GB emission class enforcement accelerates substitution for untreated decorative surfaces. MIIT mandates stricter formaldehyde limits under evolving GB standards for interior building materials. Manufacturing clusters in Jiangsu and Zhejiang provinces supply engineered wood panel producers serving retail chains across the Yangtze River Delta.
Germany
Kitchen cabinet OEMs and laminate flooring producers anchor European demand for REACH-compliant low-emission decorative papers. ECHA authorization requirements for formaldehyde-releasing substances tighten resin disclosure obligations across the supply chain. Industrial concentrations in North Rhine-Westphalia and Bavaria operate continuous press lines with real-time resin weight monitoring at pilot scale.
United States
Furniture manufacturers and electrical equipment rebuilders sustain phenolic and melamine paper procurement despite import competition. EPA and CARB ATCM regulate formaldehyde emissions from composite wood products, affecting decorative paper specification. Manufacturing activity clusters in the Southeast and Great Lakes regions serve regional laminate flooring and transformer maintenance channels.
India
Plywood and particleboard producers anticipate BIS adoption of stricter formaldehyde limits, creating positioning opportunities for compliant melamine paper suppliers. The Bureau of Indian Standards is evaluating emission class harmonization with international norms. Gujarat and Maharashtra host emerging engineered wood panel capacity targeting domestic furniture and construction applications.
Japan
Electrical insulation paper demand from transformer OEMs and motor rewind shops sustains phenolic resin-impregnated grades meeting JIS standards. METI oversees industrial material specifications affecting resin chemistry requirements. Manufacturing activity concentrates in the Chubu region around Nagoya, serving domestic electrical equipment producers and export markets.
Impregnated Paper Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-paper specialists with captive resin formulation capabilities. Three tiers have crystallized: multinational paper groups controlling saturation consistency across specialty grades, dedicated decorative print and impregnation houses serving laminate flooring clusters, and regional electrical insulation specialists meeting IEC thermal standards. Dominant competitive moves include backward integration into alpha-cellulose pulp sourcing and technology licensing for continuous press automation.
Among European integrated specialists, Ahlstrom-Munksjö and Koehler Paper Group occupy positions spanning decorative and technical grades. Schattdecor AG exemplifies the dedicated decorative paper archetype with concentrated exposure to laminate flooring supply chains. These three anchors represent distinct strategic postures: pulp integration, technical certification, and sector-specific print-to-impregnation workflow control.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| Surteco Group SE |
| Schattdecor AG |
| Starwood |
| Dekodur GmbH |
| Impress Surfaces GmbH |
| Felix Schoeller Group |
| Koehler Paper Group |
| Awa Paper Mfg. Co., Ltd |
| Others |
Supply & Pricing Matrix
Backward integration into captive pulp operations anchors supply security for Ahlstrom-Munksjö and Koehler Paper Group while insulating their pricing power from alpha-cellulose spot volatility. This upstream control allows integrated producers to maintain margin stability when urea-formaldehyde resin costs fluctuate with methanol pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant low-emission grades from commodity melamine papers and generic decorative overlays. Price differentiation hinges on certification tier and volume scale, with German kitchen cabinet OEMs paying procurement premiums for documented CAS-level resin disclosure. Cost compression in standard-grade decorative papers is intensifying because Chinese laminate flooring producers consolidate supplier panels and impose penalty clauses for specification drift. Furniture manufacturing procurement teams show highest price sensitivity, while electrical insulation OEMs prioritize thermal endurance certification over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from transformer OEMs and laminate flooring producers mandate multi-supplier qualification for phenolic resin and melamine paper grades, constraining single-source concentration risk. Geographic supply concentration centers on China, Germany, and the United States, with alpha-cellulose pulp drawing from Nordic and Canadian operations. Raw material dependencies rest on thermosetting resins, specialty cellulose pulps, and printing ink formulations. Single-source vulnerability in alpha-cellulose supply creates geographic exposure. Distribution runs through mill-direct relationships for large-volume furniture and flooring producers, with regional distributors serving mid-tier laminate manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The impregnated paper market represents a late-cycle quality story as GB standards enforcement and REACH authorization requirements shift procurement toward premium low-emission grades with documented resin chemistry.
For Market Incumbents: Lock in backward integration into alpha-cellulose pulp sourcing to secure supply continuity for electrical insulation grades. Expand capacity for custom-sized sheet formats in Germany and Italy to capture robotic panel processing investments. Defend against digital-to-substrate UV printing substitution by collapsing print-to-impregnation lead times through real-time color matching systems.
For New Entrants and Emerging Players: Modular surfacing kit distributors offer channel access to European interior fit-out projects seeking pre-bundled impregnated paper layers with substrate panels. Target India's plywood and particleboard producers anticipating BIS formaldehyde limit adoption, where compliant melamine paper supply remains underdeveloped. Pursue bio-based resin partnerships with lignin-derived thermosetting suppliers to position for LEED-certified commercial construction specifications.
For Investors and Strategic Acquirers: Roll-up economics work for regional electrical insulation specialists because IEC thermal certification expertise concentrates among established European compounders with limited succession planning. Five-to-ten year viability hinges on grid infrastructure replacement cycles sustaining transformer and motor rebuild demand. Watch for continuous press retrofit adoption rates among mid-tier laminate flooring producers as capital deployment signals for sheet-format transition momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Cellulose Pulp | Captive Nordic and Canadian pulp sourcing insulates phenolic paper margins from geographic single-source exposure. |
| Continuous Press Retrofit for Sheet Formats | Precision-cut sheet capability aligns with robotic panel processing investments by German and Italian furniture OEMs. |
| REACH-Compliant Low-Emission Resin Development | ECHA authorization requirements for formaldehyde-releasing substances elevate disclosure obligations for kitchen and bathroom applications. |
| Modular Surfacing Kit Partnership | Pre-bundled impregnated paper layers with substrate panels capture specification share from standalone decorative paper procurement. |
| Bio-Based Resin Certification Investment | Lignin-derived thermosetting resins paired with cellulose substrates offer carbon-accounting advantages for LEED specifications. |
Research Methodology
Multiple input streams — primary interviews with resin formulation chemists, laminate flooring procurement directors, and electrical insulation OEM specification engineers; secondary validation through MIIT GB standard filings, ECHA authorization documentation, and IEC thermal endurance test records; plus customs and trade data for alpha-cellulose pulp movements — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, application intensity, end-user sophistication, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by resin loading specifications and compliance tier premiums. Forecast inputs incorporated continuous press automation adoption curves and multi-jurisdiction certification lag timelines for decorative paper innovators.
Revisions become necessary when formaldehyde emission regulations tighten beyond modeled GB or REACH thresholds, when alpha-cellulose pulp supply disruptions emerge from Nordic or Canadian operations, or when digital-to-substrate UV printing penetration accelerates in short-run decorative applications. Deviation in any trigger would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
EMEA Corrugated Board Packaging Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market