
 Paper Tubes Market | 2026-2036
Paper Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Tubes Market Analytics
Food-grade spiral-wound specifications is redrawing competitive benchmarks across the Paper Tubes Market. Sonoco Products Company leverages captive paperboard mills to control fiber sourcing costs across North American operations. Smurfit Kappa Group anchors European volume through integrated corrugated and tube converting networks. Greif, Inc. competes on industrial drum-to-tube bundling contracts with chemical and adhesive clients.
Paper tubes are cylindrical structures formed from layered Kraft paperboard, bonded with starch or PVA adhesives, and finished with precise inner/outer diameter tolerances for load-bearing or protective functions. Spiral-wound tubes dominate packaging applications due to superior crush resistance and continuous manufacturing economies, while straight-wound variants sustain demand in construction formwork and concrete column casting where axial strength governs specification. Custom configurations occupy premium margin pools as brand owners specify printed exteriors, die-cut windows, and moisture barriers for retail cosmetics and spirits packaging.
The EPA guides recycled content claims under Comprehensive Procurement Guidelines, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that elevate recyclable mono-material designs above composite alternatives. India's BIS certification for paper-based packaging materials shapes export readiness for converters supplying pharmaceutical coil winding and textile yarn carriers. Stakeholders must monitor how California's extended producer responsibility implementation and pending EU harmonized recyclability testing protocols will recalibrate specification investments and regional sourcing footprints.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing specification timelines for converters, forcing rapid migration from solvent-based adhesives to water-bonded fiber constructions across European operations.
Growth Catalysts
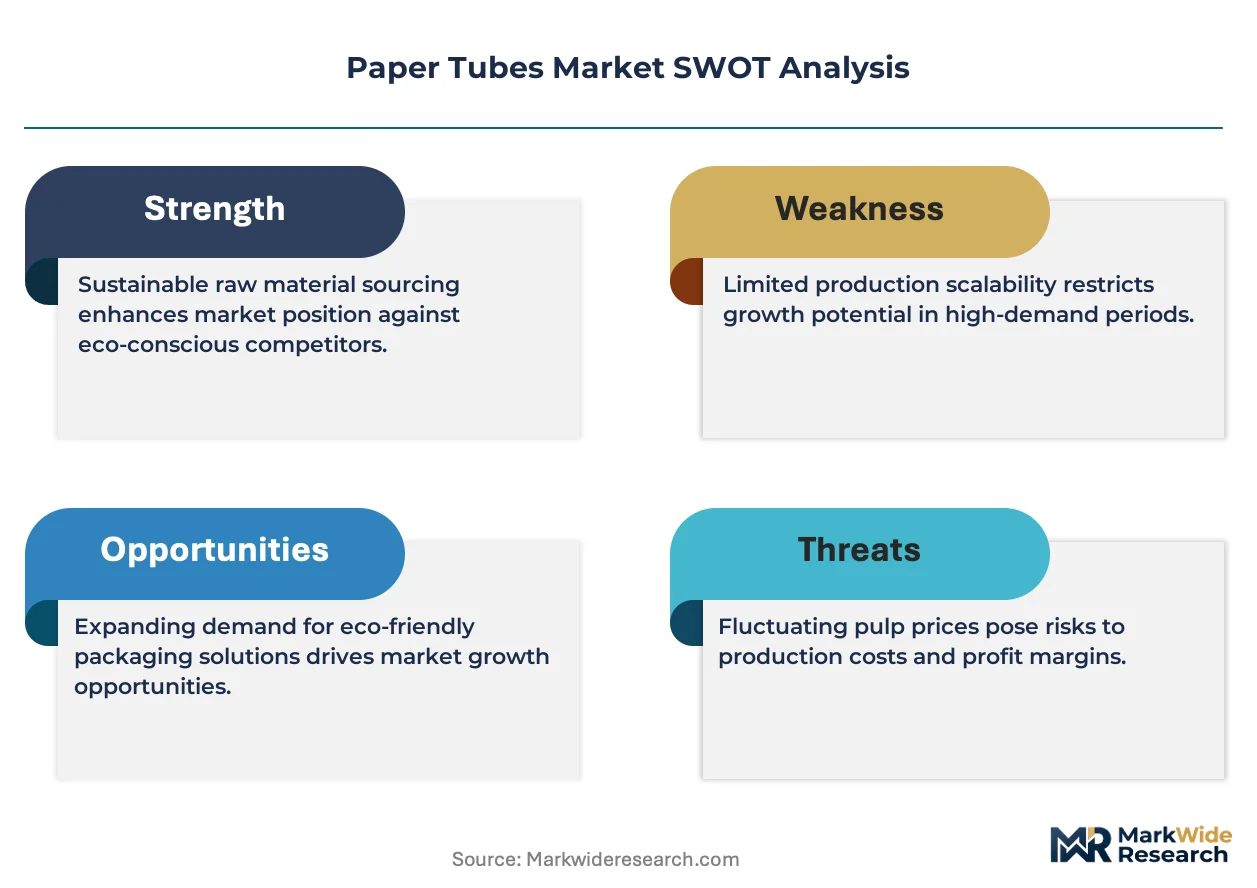
- E-commerce fulfillment surge:Spiral-wound shipping cores and protective sleeves now absorb unprecedented volumes from automated warehouse networks in Germany and the Netherlands.
- REACH chemical restrictions:Adhesive reformulation mandates are accelerating adoption of starch and PVA bonding systems that qualify for mono-material recyclability certification.
- Automotive just-in-time packaging:German parts distributors have standardized paper-based protective tubes for precision component delivery, creating specification lock-in across tier-one supply chains.
Market Restraints
- Kraft pulp price volatility:Fiber input costs swing with Nordic softwood supply disruptions, squeezing converter margins on fixed-price annual contracts.
- Recycling infrastructure gaps:Post-consumer fiber collection rates vary sharply between German municipal systems and Eastern European waste networks, fragmenting feedstock quality.
- Rigid plastic substitution:Polypropylene cores retain cost advantages in high-moisture textile yarn winding applications where paper fiber swells.
Strategic Opportunities
- Indian pharmaceutical coil winding:BIS certification requirements for export-ready packaging materials create a specification barrier that certified European converters can leverage.
- Water-based barrier coatings:Convergence of nanocellulose deposition and thermal treatment technologies enables grease-resistant food-grade tubes without plastic lamination.
- California EPR implementation:Extended producer responsibility rules taking effect in 2027 will favor domestic converters with verified post-consumer fiber content and closed-loop collection partnerships.
Industry Challenges
- Adhesive chemist scarcity:Formulation expertise for water-based bonding systems that meet food-contact migration limits commands premium salaries and extends R&D timelines.
- ISO 9001 transition complexity:Certification body backlogs and revised quality management standards are delaying supplier approval for automotive tier-one contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Tubes Market |
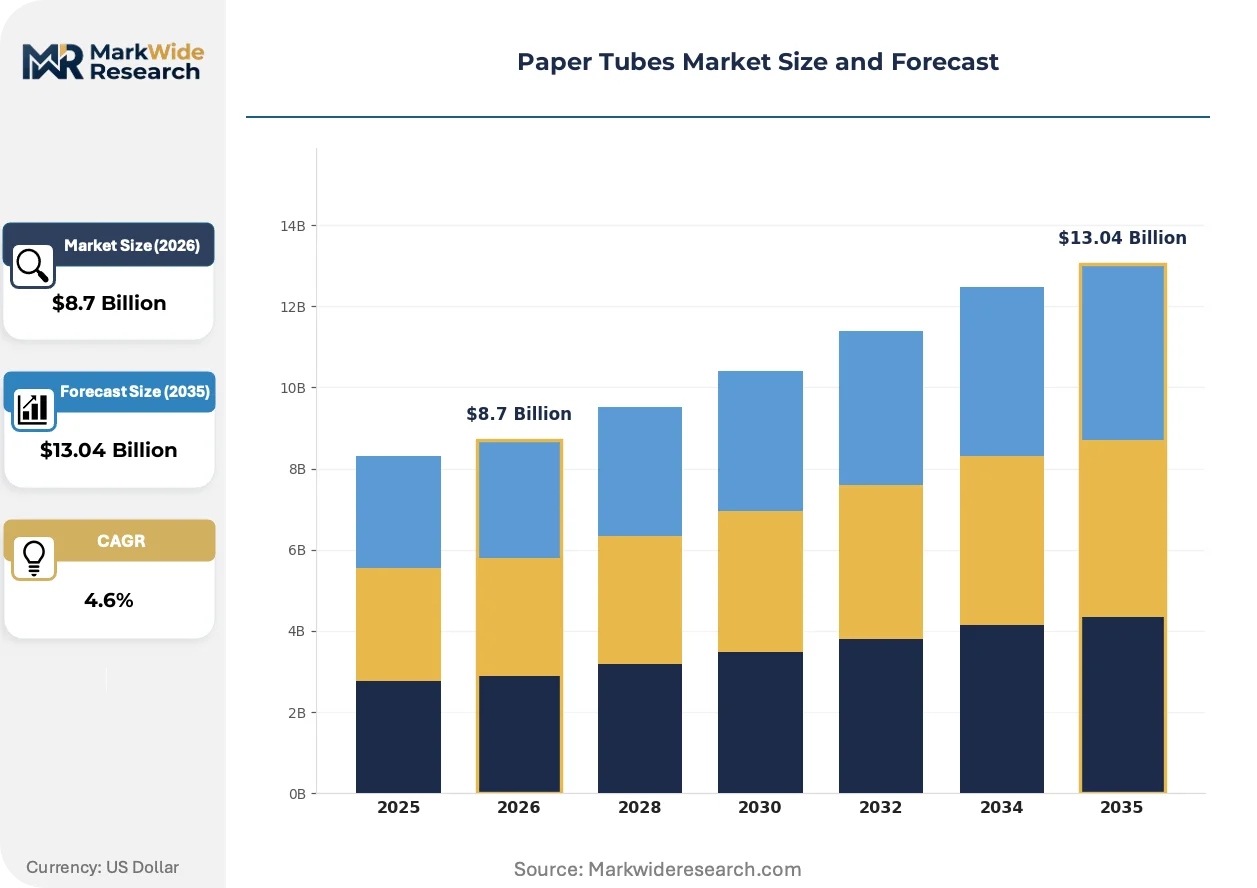
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiral-Wound, Straight-Wound, Convolute, Custom Application: Packaging, Crafts, Construction, Industrial Size: Small, Medium, Large, Extra Large End User: Retail, Wholesale, E-Commerce, Manufacturing |
| Companies Covered | Valk Industries, Inc., Western Container Corporation, Sonoco Products Company, Heartland Products Group, Ace Paper Tube Corp., Smurfit Kappa Group, CBT Manufacturing, Chicago Mailing Tube Co., Greif, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Tubes Market Evolving Landscape
Active investment in fiber engineering and adhesive chemistry is compressing performance gaps between paper tubes and incumbent plastic alternatives across moisture-sensitive applications.
Nanocellulose-reinforced Kraft laminates are supplanting conventional multi-ply constructions in spirits and cosmetics packaging where surface smoothness governs print registration quality. Premium brand owners in France and Italy are specifying these substrates for limited-edition releases. The shift is compressing demand for standard-grade tubes in favor of engineered fiber configurations with calibrated density gradients.
EPA Comprehensive Procurement Guidelines are tightening recycled content verification requirements for federal supply contracts, compelling converters to deploy mass-balance accounting systems traceable to municipal recovery facilities. Paper tube suppliers to defense and institutional foodservice channels face audit intensity comparable to pharmaceutical packaging. The burden falls heaviest on mid-cap converters lacking captive pulp operations.
Brand owners now specify printed exteriors and die-cut windows as standard rather than premium options, collapsing the traditional three-tier specification structure. Procurement teams at European cosmetics houses bundle tube orders with corrugated outer packaging to secure volume discounts from integrated converters. The practice is most advanced in Germany, where Smurfit Kappa and Sonoco operate combined tube-and-box production lines.
Paper Tubes Market Segmentation
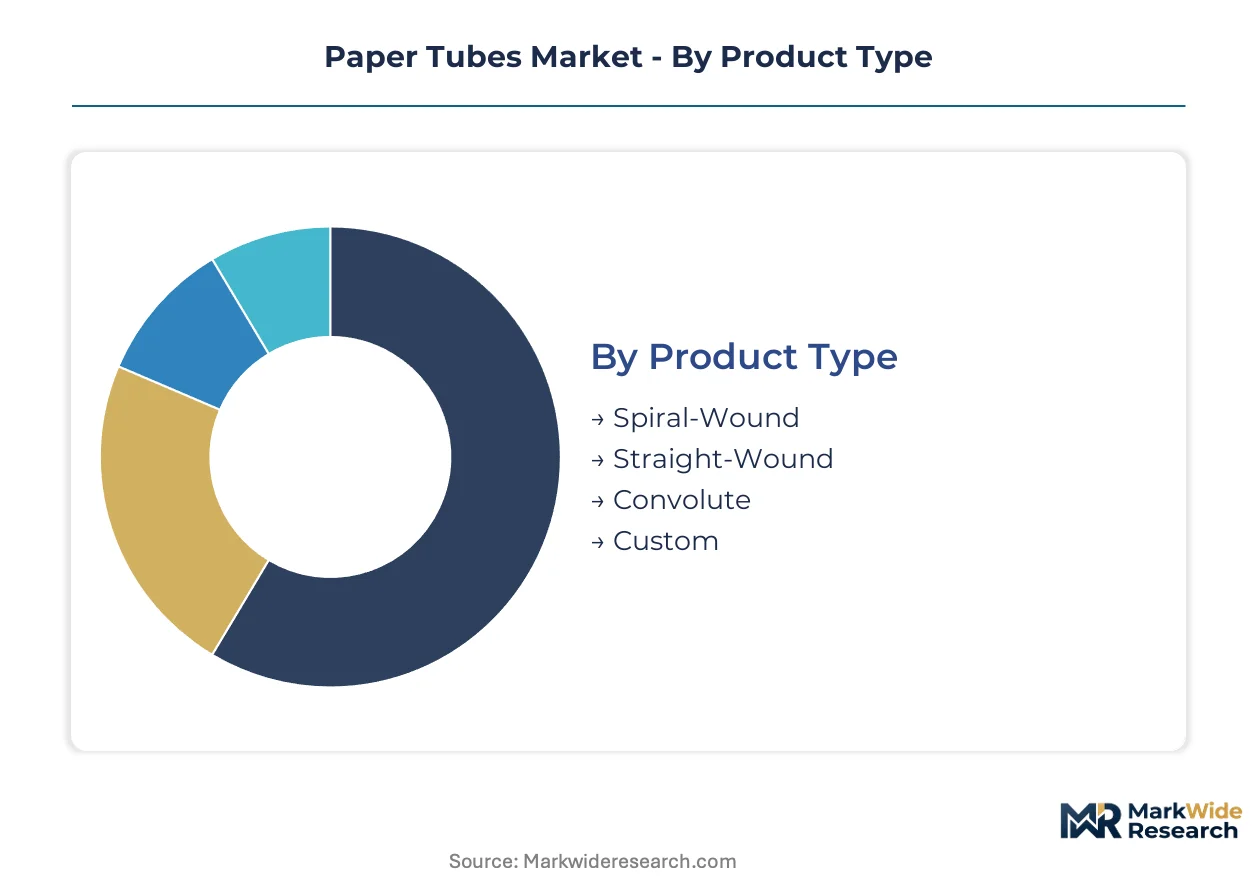
Paper tube specification diversity creates distinct margin architectures across manufacturing tiers. Converters align capacity investments to segment-specific tolerance requirements and volume predictability.
Product Type:
Margin pools concentrate in engineered configurations where fiber layering precision commands specification premiums.
- Spiral-Wound:Continuous helical winding of Kraft paperboard around a mandrel produces superior crush resistance and diameter consistency. German automotive parts distributors have standardized these tubes for just-in-time protective packaging, locking in multi-year supply agreements with REACH-compliant converters.
- Straight-Wound:Parallel fiber orientation along the tube axis maximizes axial load-bearing capacity for concrete formwork and construction casting applications. Demand concentrates in German and Dutch infrastructure projects where dimensional stability governs specification acceptance.
- Convolute:Diagonal fiber interlocking creates enhanced torsional strength for textile yarn winding and coil winding applications. BIS certification requirements in India shape export-ready production standards.
- Custom:Engineered configurations with printed exteriors, die-cut windows, and moisture barriers serve premium cosmetics and spirits packaging segments. Nanocellulose-reinforced substrates are displacing conventional multi-ply constructions in French and Italian limited-edition releases.
Spiral-Wound holds installed capacity. Custom is rotating up the share rankings.
Application:
Application-driven cost tiers separate commodity fulfillment from certified industrial supply.
- Packaging:Protective sleeves and shipping cores absorb unprecedented volumes from automated e-commerce fulfillment networks in Germany and the Netherlands. Water-based adhesive migration from solvent systems accelerates under EU Packaging and Packaging Waste Regulation timelines.
- Crafts:Hobby and educational supply channels demand consistent dimensional tolerances at price-sensitive volume tiers. German and French retail distributors bundle tube orders with corrugated outer packaging to secure integrated converter discounts.
- Construction:Concrete column casting and formwork applications specify straight-wound axial strength grades. Nordic softwood pulp price volatility squeezes converter margins on fixed-price annual contracts.
- Industrial:Chemical drum-to-tube bundling and adhesive packaging require industrial-grade tolerance certification. ISO 9001 transition complexity delays supplier approval for automotive tier-one contracts.
Packaging dominates volume throughput. Industrial is climbing the fastest on specification value.
Size:
Size-based customer stratification maps directly to equipment utilization and changeover economics.
- Small:Precision diameters for pharmaceutical coil winding and textile yarn carriers. India's BIS certification creates specification barriers for export-ready converters.
- Medium:Standard shipping cores for corrugated board and film winding. E-commerce fulfillment surge concentrates demand in automated warehouse networks.
- Large:Protective sleeves for automotive components and industrial parts. German tier-one supply chains have standardized paper-based protective packaging.
- Extra Large:Specialized formwork and heavy-duty industrial applications. Post-consumer fiber collection rate gaps between German municipal systems and Eastern European networks fragment feedstock quality.
Medium holds installed capacity. Small is gaining share fastest on precision premium capture.
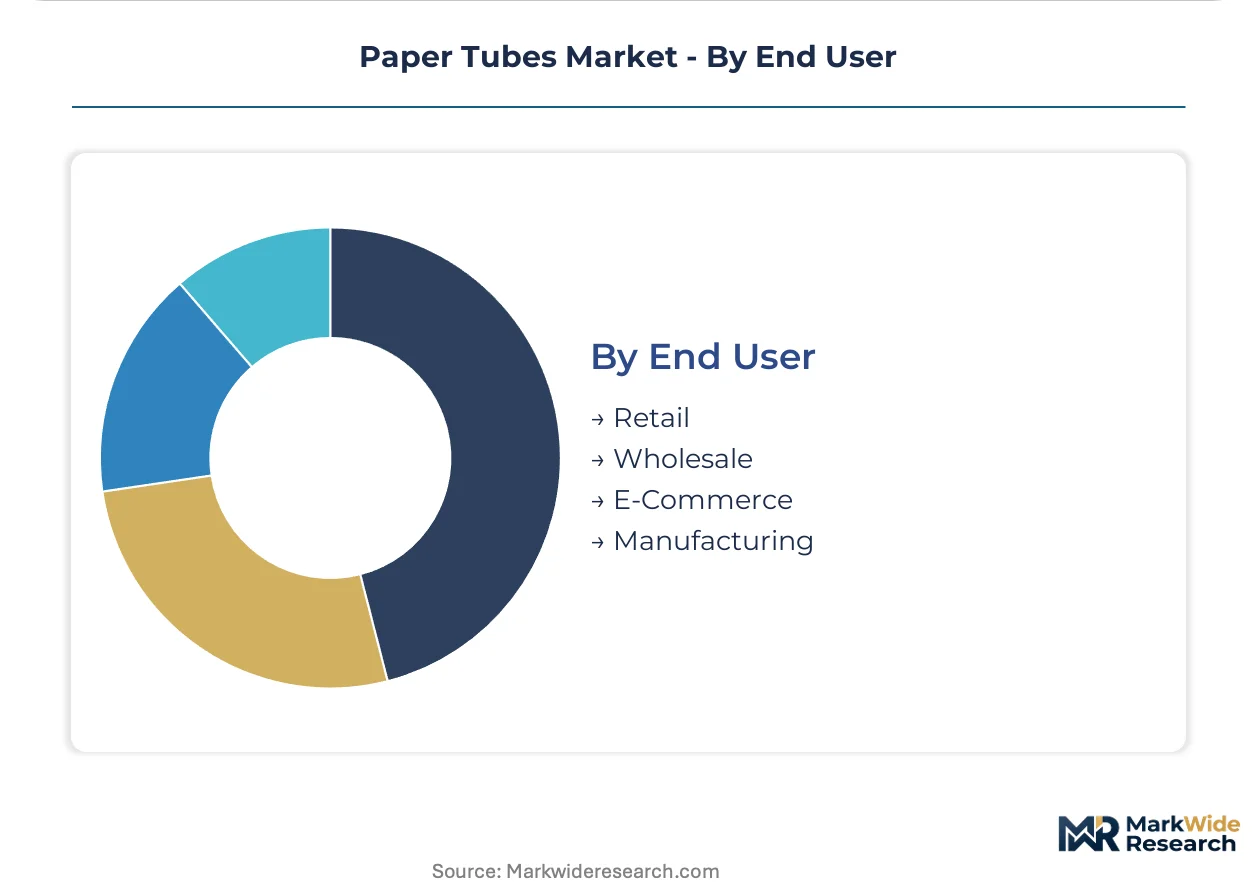
End User:
End-user procurement patterns separate spot-market buyers from strategic partnership accounts.
- Retail:Brand owners specify printed exteriors and die-cut windows as standard requirements, collapsing traditional three-tier specification structures. Premium cosmetics houses in France and Italy drive nanocellulose substrate adoption.
- Wholesale:Volume bundling with corrugated packaging secures preferential pricing from integrated converters. Smurfit Kappa and Sonoco operate combined tube-and-box production lines in Germany.
- E-Commerce:Automated fulfillment networks demand consistent crush resistance and dimensional stability at scale. California's extended producer responsibility implementation favors domestic converters with verified post-consumer fiber content.
- Manufacturing:Industrial drum-to-tube bundling contracts require captive paperboard mill integration to control fiber sourcing costs. EPA Comprehensive Procurement Guidelines tighten recycled content verification for federal supply contracts.
Manufacturing holds installed capacity. E-Commerce is expanding most quickly on fulfillment automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands absorb premium-priced REACH-compliant tubes for automotive supply chains, while Indian and Chinese converters compete on fiber cost arbitrage for export-grade pharmaceutical carriers. Price elasticity varies sharply between specification-locked industrial contracts and spot-market craft supply channels.
Germany
Automotive parts distributors have standardized paper-based protective tubes for just-in-time delivery systems, locking in multi-year supply agreements. REACH chemical restrictions mandate adhesive reformulation to starch and PVA bonding systems. Stuttgart and Munich industrial corridors host integrated converters operating combined tube-and-box production lines.
United States
E-commerce fulfillment networks in California and Texas demand crush-resistant shipping cores at unprecedented scale. EPA Comprehensive Procurement Guidelines tighten recycled content verification for federal supply contracts. Chicago and Dallas-Fort Worth warehouse clusters favor domestic converters with verified post-consumer fiber partnerships ahead of 2027 extended producer responsibility implementation.
India
Pharmaceutical coil winding and textile yarn carrier exports drive precision small-diameter tube demand. BIS certification requirements create specification barriers that certified European converters leverage for premium positioning. Gujarat and Maharashtra industrial zones concentrate export-ready production facilities serving regulated markets.
France
Premium cosmetics houses specify nanocellulose-reinforced substrates for limited-edition spirits packaging. EU Packaging and Packaging Waste Regulation timelines compress migration from solvent-based adhesives to water-bonded constructions. Lyon and Paris packaging clusters lead engineered fiber configuration adoption for surface smoothness-critical applications.
China
Construction formwork applications sustain straight-wound axial strength grade demand for infrastructure projects. Dual carbon goals and national GB standards shape fiber sourcing compliance requirements. Yangtze River Delta manufacturing hubs balance domestic construction supply with export-grade pharmaceutical carrier production.
Paper Tubes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Paper Tubes Market. Integrated multinational converters with captive paperboard mills control fiber sourcing economics, while regional specialists compete on changeover flexibility and custom specification turnaround. Three archetypes dominate: scale-driven integrated producers, mid-cap precision specialists, and commodity-grade regional fabricators. Capacity expansion and adhesive chemistry partnerships represent the dominant competitive moves as converters respond to REACH and EPA compliance timelines.
Among North American fabricators, Sonoco Products Company and Western Container Corporation exemplify the integrated scale archetype, while Smurfit Kappa Group anchors European volume through combined tube-and-box production networks. Greif, Inc. occupies a position within the industrial bundling segment where drum-to-tube contract structures favor backward integration into fiber supply.
| Leading Market Players |
|---|
| Valk Industries, Inc. |
| Western Container Corporation |
| Sonoco Products Company |
| Heartland Products Group |
| Ace Paper Tube Corp. |
| Smurfit Kappa Group |
| CBT Manufacturing |
| Chicago Mailing Tube Co. |
| Greif, Inc. |
| Others |
Value Network & Pricing Analysis
Water-based adhesive substitution for solvent-based bonding systems simultaneously redraws supply geography toward REACH-compliant European converters and compresses pricing economics for legacy solvent-dependent fabricators. This input transition concentrates procurement power with German and Dutch integrated producers while fragmenting margin pools for Eastern European competitors facing reformulation cost burdens.
Pricing Analysis
After-sales specification support and multi-year automotive bundling contracts drive lifetime value capture for integrated converters. Three-tier pricing structure across premium REACH-certified, standard industrial-grade, and economy craft-supply levels separates specification-locked automotive tier-one contracts from spot-market hobby channels. Cost compression in standard-grade spiral-wound tubes is intensifying because Nordic softwood pulp volatility squeezes fixed-price annual contracts. E-commerce fulfillment buyers exhibit highest price sensitivity due to volume scale and automated procurement systems, while pharmaceutical coil-winding clients prioritize BIS certification compliance over unit cost.
Supply Chain Analysis
Just-in-time delivery preferences among German automotive parts distributors favor regional converter proximity over lowest-cost global sourcing. Supply concentrates in Germany, the Netherlands, and India, with fiber input draws from Nordic softwood pulp operations and post-consumer collection networks. Raw material dependencies rest on Kraft paperboard, starch and PVA adhesives, and nanocellulose deposition chemistries. Single-source vulnerability runs through concentrated Nordic pulp supply disruptions. Distribution runs through integrated tube-and-box production networks and specialized industrial bundling channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Paper Tubes Market is recovering from cyclical fiber cost compression as e-commerce fulfillment volumes and automotive just-in-time standardization rebuild converter utilization rates.
For Market Incumbents: Fortify specification lock-in with German automotive tier-one supply chains through captive paperboard mill integration and REACH-compliant adhesive chemistry partnerships. Capacity addition in Stuttgart and Munich industrial corridors anchors multi-year protective packaging contracts against emerging Asian export-grade competitors. For New Entrants and Emerging Players: Differentiate on water-based barrier coating technology for grease-resistant food-grade applications where nanocellulose deposition commands premium positioning. White-space targets include Indian pharmaceutical coil-winding exports requiring BIS certification and California EPR-compliant post-consumer fiber partnerships ahead of implementation timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap precision specialists holding ISO 9001 certification backlogs and limited captive fiber supply. Long-term viability over a 5-10 year window favors converters with verified closed-loop collection partnerships and mass-balance accounting systems traceable to municipal recovery facilities. The signal to watch is California extended producer responsibility enforcement intensity as an inflection indicator for domestic converter valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | Captive paperboard mill control insulates Sonoco and Smurfit Kappa from Nordic pulp price volatility. |
| Water-Based Adhesive Reformulation | REACH-compliant starch and PVA bonding systems qualify converters for EU mono-material recyclability certification. |
| Combined Tube-and-Box Production Lines | Integrated corrugated and tube converting networks in Germany secure volume bundling discounts from cosmetics houses. |
| BIS Certification Investment | Indian pharmaceutical coil-winding export readiness creates specification barriers that certified European converters leverage. |
| Post-Consumer Fiber Partnerships | Closed-loop collection agreements with California municipal systems position domestic converters for EPR implementation. |
Research Methodology
Cross-validation between primary interviews with tube converting plant managers, automotive procurement leads at tier-one suppliers, adhesive R&D directors, and e-commerce fulfillment channel partners anchors the qualitative findings against secondary validation from customs and trade data, SEC filings of integrated packaging multinationals, EPA Comprehensive Procurement Guidelines documentation, and EU REACH regulatory submissions. Bottom-up capacity utilization surveys and top-down fiber consumption estimates complete the triangulation.
Sensitivity analysis around Nordic softwood pulp price scenarios and REACH compliance timeline assumptions stress-tests the analytical framework. Segmentation dimensions modeled include product type tier, application end-use, diameter size class, and geographic regulatory cluster. CAGRs were derived from trend-line extrapolation of historical volume data adjusted for specification shift impacts. Industry-specific forecast inputs incorporate e-commerce fulfillment automation penetration rates and automotive just-in-time packaging standardization adoption curves.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation implementation and California extended producer responsibility regimes; material policy shifts would require re-modeling. Revision becomes warranted when Kraft pulp price volatility crosses margin compression thresholds for fixed-price contract converters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Germany Honeycomb Paper Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
MMA Film & Sheet Market