
 Knee Cartilage Repair Market | 2026-2036
Knee Cartilage Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Cartilage Repair Market Intelligence
Multi-source procurement of biologic graft materials is recalibrating supply chain economics across the knee cartilage repair sector. Stryker Corporation leverages its arthroscopy platform dominance to bundle instruments with consumable graft solutions. Arthrex sustains competitive intensity through specialized suture anchor and scaffold portfolios. Smith & Nephew anchors European market presence with differentiated allograft distribution networks.
Knee cartilage repair encompasses surgical and biologic interventions that restore articular hyaline cartilage, typically involving chondrocyte harvesting, scaffold seeding, or microfracture stimulation of subchondral bone to regenerate load-bearing joint surfaces. Autologous chondrocyte implantation retains premium positioning due to durable clinical outcomes in focal defects, though cell-based therapy segments are gaining traction as one-stage procedures reduce surgical burden. Synthetic scaffolds occupy a maturing niche where polylactic acid and collagen-based matrices compete on degradation kinetics and porosity parameters.
FDA premarket notification requirements and the EU MDR's clinical evaluation standards shape product development timelines and market access costs for implantable biologics. Health Canada's PMRA and Japan's PMDA impose additional jurisdiction-specific quality management obligations on manufacturers seeking multi-regional distribution. Stakeholders must monitor evolving reimbursement thresholds for cell-based therapies versus mechanical debridement as health technology assessment bodies recalibrate value frameworks.
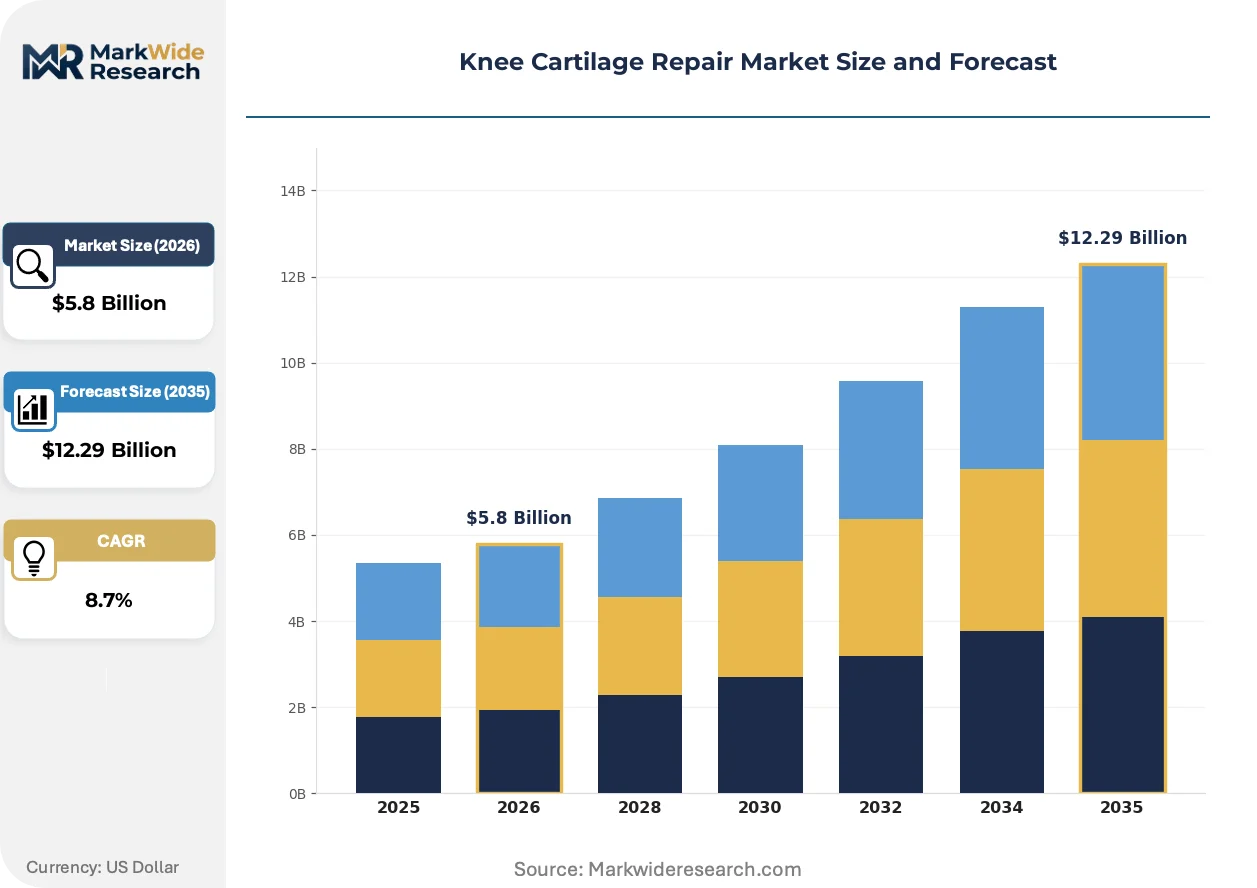
Market Dynamics
Biologic graft material scarcity is concentrating procurement power among integrated arthroscopy platform holders, reshaping competitive positioning across cell-based and scaffold-based repair modalities.
Growth Catalysts
- EU MDR Clinical Evidence Requirements:Tighter evidentiary standards for implantable biologics are filtering out marginal competitors and elevating premium-positioned products with robust clinical data packages.
- Sports Medicine Clinic Expansion:Specialized orthopedic centers in the United States and Germany are expanding procedure volumes through dedicated cartilage restoration programs.
- One-Stage Cell Therapy:Reduced surgical burden compared to two-stage autologous chondrocyte implantation is accelerating patient throughput and facility capacity utilization.
Market Restraints
- Allograft Supply Concentration:Tissue bank networks in the United States control critical biologic material flows, creating single-source vulnerability for European and Asian manufacturers.
- FDA 510(k) Pathway Friction:Evolving substantial equivalence standards for scaffold-cells combinations are extending premarket notification timelines and inflating regulatory compliance costs.
- Mechanical Debridement Substitution:Low-cost arthroscopic debridement procedures retain strong payer preference for older patient cohorts, compressing reimbursement ceilings for advanced biologic interventions.
Strategic Opportunities
- Japan PMDA Accelerated Review:Regenerative medicine product designation pathways offer expedited market access for cell-based therapies addressing focal chondral defects.
- Synthetic Scaffold Convergence:Polylactic acid and collagen matrix hybridization is opening performance gaps against pure biologic grafts in load-bearing applications.
- Direct-to-Provider Distribution:Bypassing traditional implant distributors through hospital system contracting is capturing margin previously allocated to intermediary logistics layers.
Industry Challenges
- Cell Processing Facility Capex:GMP-compliant cleanroom infrastructure for autologous chondrocyte expansion requires substantial capital deployment with extended depreciation horizons.
- Health Technology Assessment Alignment:Divergent value frameworks across Germany's IQWiG, England's NICE, and Japan's Chuikyo create fragmented evidence generation requirements for multi-regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Cartilage Repair Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Chondrocyte Implantation, Microfracture, Osteochondral Autograft Transfer, Synthetic Scaffolds, Cell-Based Therapy Therapy Area: Focal Cartilage Defects, Osteoarthritis, Traumatic Injuries, Degenerative Cartilage Loss, Meniscal Tears End User: Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Facilities, Specialized Cartilage Repair Centers, Sports Medicine Clinics Delivery Mode: Arthroscopic Surgery, Open Surgery, Minimally Invasive Techniques, Injectable Biologics, Scaffold Implantation |
| Companies Covered | Stryker Corporation, Arthrex, Smith & Nephew, B. Braun Melsungen, Anika Therapeutics, Vericel Corporation, DePuy Synthes, Johnson & Johnson, Zimmer Biomet Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Cartilage Repair Market Strategic Shifts & Innovations
Arthroscopic delivery systems are reshaping how biologic grafts reach defect sites, compressing the boundary between instrumentation and implantable therapy.
Matrix-induced autologous chondrocyte implantation is consolidating the cell-based therapy landscape by combining chondrocyte seeding with collagen scaffolds in a single operative session. Sports medicine surgeons in Germany and Japan are adopting this approach at accelerating rates for focal femoral condyle defects. The technology is consolidating procedure volumes previously split between microfracture and two-stage autologous implantation into unified facility workflows.
EU MDR's clinical evaluation report requirements are extending post-market surveillance obligations for scaffold-based implants beyond legacy medical device directive timelines. Manufacturers must now generate ongoing clinical data through registry participation or prospective studies to maintain CE marking validity. Knee cartilage repair products with limited long-term follow-up face disproportionate compliance burdens compared to established mechanical implants.
Hospital value analysis committees are compressing vendor selection cycles from annual to quarterly review intervals, displacing traditional surgeon-driven preference with aggregated purchasing metrics. Integrated delivery networks in the United States are centralizing biologic graft procurement through system-wide formularies. This pattern is most visible in metropolitan hospital clusters where orthopedic service line consolidation has concentrated buying power.
Knee Cartilage Repair Market Segmentation
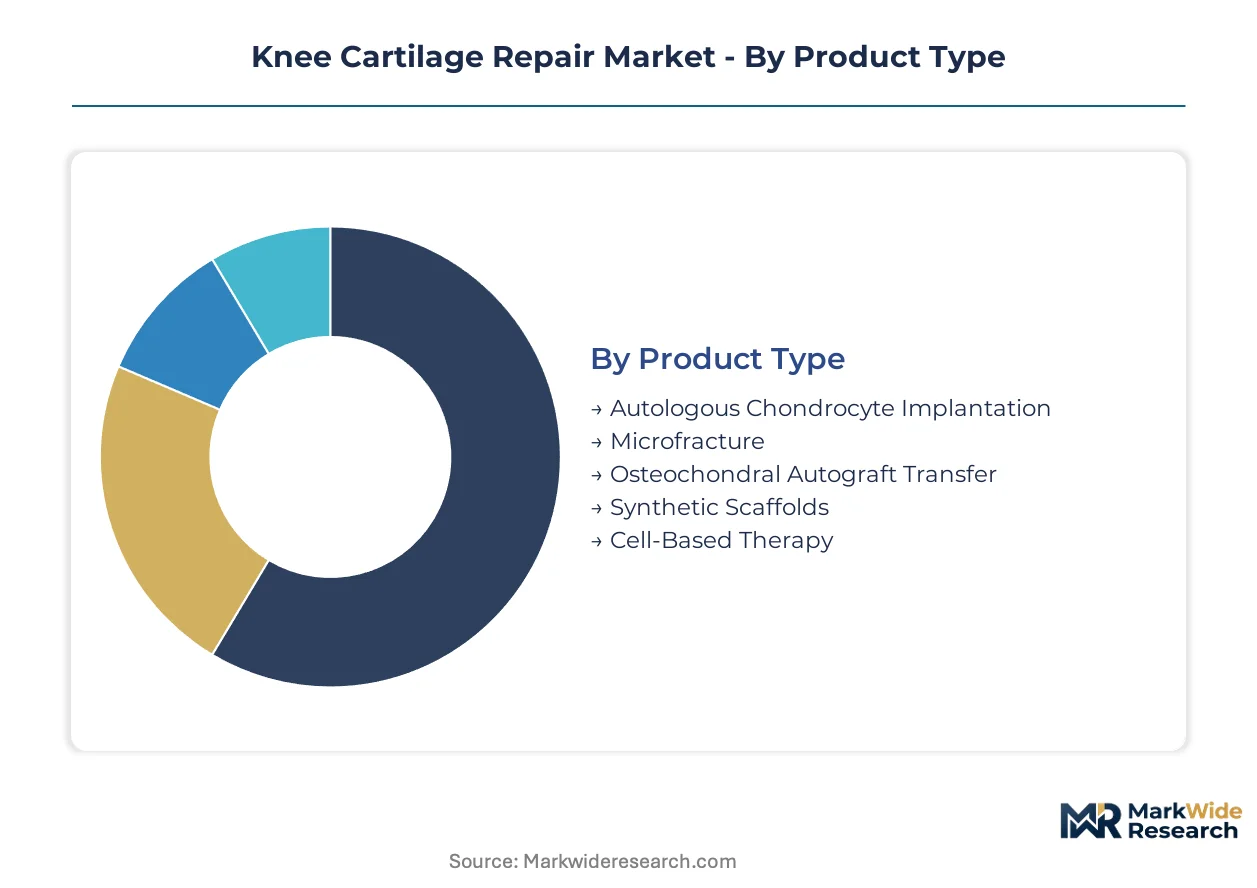
Segmentation in knee cartilage repair reveals how procedure economics, patient acuity, and facility capabilities fragment demand across distinct commercial pockets. Technology maturity and reimbursement thresholds create divergent growth trajectories within each dimension.
Product Type:
Cost tier and surgical invasiveness separate patient populations across product categories, with premium biologics commanding distinct facility requirements.
- Autologous Chondrocyte Implantation:Two-stage procedure involving chondrocyte harvest, ex vivo expansion, and reimplantation beneath a periosteal or synthetic cover. Demand concentrates in Germany and Japan where specialized cell processing facilities and favorable reimbursement codes sustain procedural volumes. Cell handling complexity limits adoption to tertiary orthopedic centers with GMP-compliant infrastructure.
- Cell-Based Therapy:One-stage approaches using allogeneic or point-of-care processed cells eliminate the expansion interval. United States sports medicine clinics are adopting these procedures for accelerated patient throughput, though FDA regulatory pathways for cell-scaffold combinations remain under refinement.
- Microfracture:Subchondral bone perforation stimulating marrow-derived repair tissue. Cost-conscious payers in United States hospital systems favor this for older patient cohorts.
- Osteochondral Autograft Transfer:Cylindrical graft harvesting from non-weight-bearing surfaces. High-volume orthopedic clinics in Germany apply this for small focal defects in younger patients.
- Synthetic Scaffolds:Polylactic acid and collagen-based matrices providing structural support without biologic sourcing constraints. Japanese manufacturers are advancing hybrid degradation profiles.
Volume sits with microfracture; growth tilts toward cell-based therapy.
Therapy Area:
Patient age and defect etiology determine procedure selection, with traumatic cases accessing premium interventions denied to degenerative cohorts.
- Focal Cartilage Defects:Isolated chondral lesions in younger patients with preserved joint architecture. Sports medicine clinics in the United States and Germany drive procedural concentration here, as durable repair justifies biologic investment.
- Traumatic Injuries:Acute cartilage damage from sports or occupational incidents. Japanese orthopedic centers report rising volumes from skiing and martial arts participation.
- Osteoarthritis:Diffuse cartilage loss in older populations. Mechanical debridement dominates due to payer resistance toward biologic costs.
- Degenerative Cartilage Loss:Progressive joint surface erosion. Rehabilitation facilities manage these cases conservatively.
- Meniscal Tears:Associated cartilage damage requiring concomitant repair. Ambulatory surgical centers bundle meniscal and chondral procedures.
Procedure concentration favors focal defects; steepest expansion trajectory appears in traumatic injury repair.
End User:
Capital intensity and surgeon specialization stratify facility types, with integrated delivery networks centralizing procurement through system-wide formularies.
- Orthopedic Clinics:General musculoskeletal practices handling volume debridement and basic arthroscopy. United States metropolitan clusters dominate.
- Sports Medicine Clinics:Dedicated cartilage restoration programs with fellowship-trained surgeons. Germany's Ruhr region and Japan's Kanto corridor host concentrated capacity.
- Specialized Cartilage Repair Centers:Tertiary facilities with cell processing laboratories. These command premium reimbursement through outcomes data.
- Ambulatory Surgical Centers:Same-day discharge for microfracture and simple scaffold implantation. United States Medicare site-of-service differentials drive migration.
- Rehabilitation Facilities:Post-operative recovery and conservative management. These rarely initiate biologic interventions.
Revenue aggregates at specialized centers; patient volume is shifting fastest toward ambulatory surgical centers.
Delivery Mode:
Instrumentation and biologic integration are compressing distinctions between surgical technique and implantable therapy.
- Arthroscopic Surgery:Minimally invasive visualization and instrument access through small portals. Stryker and Arthrex platform dominance bundles instrument systems with consumable graft solutions.
- Scaffold Implantation:Matrix delivery requiring arthroscopic or mini-open approaches. EU MDR clinical evaluation requirements extend post-market surveillance for these implants.
- Minimally Invasive Techniques:Reduced-portal approaches preserving soft tissue envelope. German surgeons lead adoption rates.
- Open Surgery:Direct visualization for large defects or revision cases. Declining share except in complex reconstructions.
- Injectable Biologics:Cell or matrix suspension delivery without arthroscopy. PMDA accelerated review pathways may expedite Japanese market entry.
Procedure volume rests with arthroscopic platforms; technology investment is flowing fastest into injectable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Human allograft tissue availability concentrates procurement power among United States tissue banks, reshaping facility economics for European and Asian manufacturers dependent on imported biologic materials.
United States
FDA 510(k) clearance pathways for scaffold-cell combinations are extending premarket timelines while Medicare site-of-service differentials accelerate ambulatory surgical center migration. Sports medicine clinics in metropolitan hospital clusters are consolidating biologic graft procurement through system-wide formularies. The FDA's evolving substantial equivalence standards are elevating compliance costs for implantable biologics seeking market access.
Germany
IQWiG health technology assessments favor durable clinical outcomes in focal defect repair, sustaining reimbursement premiums for autologous chondrocyte implantation. The EU MDR's clinical evaluation report requirements extend post-market surveillance obligations for scaffold-based implants beyond legacy directive timelines. The Ruhr region hosts concentrated cartilage restoration capacity where specialized cell processing facilities command premium reimbursement through outcomes data.
Japan
PMDA accelerated review pathways for regenerative medicine products are expediting market entry for cell-based therapies addressing focal chondral defects. Aging demographics and active lifestyle preservation among skiing and martial arts participants drive procedural volumes. The Kanto corridor maintains specialized orthopedic centers where fellowship-trained surgeons perform matrix-induced autologous chondrocyte implantation at accelerating rates.
United Kingdom
NICE value frameworks compress reimbursement ceilings for advanced biologic interventions relative to mechanical debridement in older patient cohorts. The NHS's centralized procurement mechanisms are displacing surgeon-driven vendor selection with aggregated purchasing metrics. London's metropolitan hospital clusters are centralizing orthopedic service line consolidation through integrated delivery network formularies.
Switzerland
Swissmedic's quality management obligations for multi-regional distribution align with EU MDR standards while maintaining jurisdiction-specific device registration requirements. Premium private healthcare infrastructure supports out-of-pocket payment for one-stage cell therapy procedures. The Zurich-Basel corridor accommodates specialized cartilage repair centers with GMP-compliant cleanroom infrastructure for autologous chondrocyte expansion.
Knee Cartilage Repair Market Key Industry Players
Global majors compete with regional champions across arthroscopy platform integration and biologic graft distribution networks. Market structure tilts toward consolidation among integrated instrument-implant bundlers, with tiered competitive layers separating platform holders from specialized scaffold suppliers. Three archetypes dominate: diversified orthopedic conglomerates with arthroscopy dominance, cell therapy specialists with GMP processing capabilities, and allograft distributors with tissue bank relationships. M&A activity concentrates on acquiring cell processing facilities, while strategic partnerships target synthetic scaffold hybridization technologies.
Within the diversified orthopedic tier, Stryker Corporation and Arthrex exemplify platform-centric competitive positioning through instrument-consumable bundling. Smith & Nephew occupies a position among European-anchored allograft distributors with differentiated tissue network access. Zimmer Biomet Holdings sits within the reconstructive surgery conglomerate archetype, while Vericel Corporation represents the cell therapy specialist category with autologous chondrocyte processing focus.
| Leading Market Players |
|---|
| Stryker Corporation |
| Arthrex |
| Smith & Nephew |
| B. Braun Melsungen |
| Anika Therapeutics |
| Vericel Corporation |
| DePuy Synthes |
| Johnson & Johnson |
| Zimmer Biomet Holdings |
| Others |
Cost & Logistics Intelligence
Hospital value analysis committees in United States metropolitan clusters are compressing vendor selection cycles to quarterly intervals, forcing manufacturers to unbundle service components and absorb logistics costs previously passed through to facility buyers. This procurement consolidation is reshaping how arthroscopy platform holders and biologic graft suppliers structure commercial terms across cell-based and scaffold-based repair modalities.
Pricing Analysis
Warranty and clinical outcomes data bundling separates premium autologous chondrocyte implantation from unbundled microfracture procedures, with cell-based therapy occupying a mid-tier position where processing facility certification drives differentiation. Price stratification across premium, standard, and economy tiers reflects GMP compliance grade and surgeon training depth rather than material costs alone. Pricing pressure stems from Medicare site-of-service differentials favoring ambulatory surgical centers over hospital-based procedures. Sports medicine clinics demonstrate lowest price sensitivity due to outcomes-based reimbursement contracts, while general orthopedic clinics face acute margin compression from mechanical debridement substitution.
Supply Chain Analysis
Dual-sourcing mandates from European and Japanese manufacturers are accelerating qualification of secondary tissue bank relationships beyond dominant United States suppliers, though allograft procurement still draws from American tissue networks. Raw material dependencies center on human donor tissue, polylactic acid polymers, and collagen matrices sourced through specialized chemical suppliers. Single-source vulnerability in biologic graft flows creates structural risk for manufacturers lacking captive tissue processing capabilities. Distribution runs through integrated delivery network formularies in United States metropolitan clusters and specialized orthopedic distributors in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evaluation requirements are erecting a cost-of-compliance barrier that favors incumbent manufacturers with established post-market surveillance infrastructure and registry participation capabilities, filtering out marginal competitors unable to sustain ongoing evidence generation obligations.
For Market Incumbents: Deepen GMP-compliant cell processing facility footprints in Germany and Japan to defend against emerging one-stage cell therapy specialists threatening two-stage autologous chondrocyte implantation volumes. Prioritize backward integration into tissue bank relationships to mitigate allograft supply concentration risk from United States sources. Consolidate arthroscopy platform bundling advantages as hospital systems centralize procurement through system-wide formularies. For New Entrants and Emerging Players: Injectable biologic formats offer a technology-first wedge into Japanese orthopedic centers leveraging PMDA accelerated review pathways for regenerative medicine products. Target ambulatory surgical center migration in United States metropolitan clusters where site-of-service differentials create white-space for same-day discharge procedures. Pursue direct-to-provider distribution contracting to bypass traditional implant distributor margin layers. For Investors and Strategic Acquirers: The window for entry favors cell therapy specialists with GMP processing capabilities and established surgeon training networks over pure scaffold manufacturers facing EU MDR compliance burdens. Long-term viability hinges on outcomes data differentiation as health technology assessment bodies tighten value frameworks. Watch Japan's Chuikyo reimbursement decisions for cell-based therapies as the inflection indicator for Asia-Pacific market expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evaluation requirements extend post-market surveillance timelines for scaffold-based implants beyond legacy directive periods. |
| Hospital System Partnership | Integrated delivery network formularies in United States metropolitan clusters centralize biologic graft procurement through aggregated purchasing metrics. |
| Reimbursement Strategy | Germany's IQWiG and Japan's Chuikyo value frameworks determine premium positioning for autologous chondrocyte implantation versus mechanical debridement. |
| Manufacturing Scale-Up | GMP-compliant cleanroom infrastructure for autologous chondrocyte expansion requires substantial capital deployment with extended depreciation horizons. |
| Regulatory Approval Pathway | FDA 510(k) substantial equivalence standards for scaffold-cell combinations are extending premarket notification timelines and elevating compliance costs. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR clinical evaluation reports, and hospital procurement databases, complemented by interviews with orthopedic surgeons, GPO contracts managers, and biomedical engineers at specialized cartilage repair centers. Secondary validation drew from CMS Medicare reimbursement data, Japanese Ministry of Health procedural volume statistics, and German IQWiG health technology assessment documentation. Bottom-up facility capacity modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation outputs reflect procedure economics modeled by product type, therapy area, end-user facility tier, and delivery mode across the projection horizon. CAGRs were derived from facility throughput assumptions, reimbursement code evolution, and regulatory pathway timelines. Industry-specific forecast inputs incorporated arthroscopy platform installation bases, cell processing laboratory capacity expansion, and tissue bank network consolidation patterns.
Several conditions sit outside the modeled scope, including unforeseen regulatory pathway reversals, abrupt reimbursement code eliminations, and biologic graft material contamination events. Forecasts reflect assumptions about EU MDR implementation consistency, PMDA accelerated review pathway continuity, and Medicare site-of-service differential stability. Deviation in health technology assessment value framework recalibrations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Orthobiologics Market
Orthopedic Devices
Knee Arthrodesis Implant Market