
 Orthopedic Prosthetic Devices Market | 2026-2036
Orthopedic Prosthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Prosthetic Devices Market Outlook
Microprocessor-enabled prosthetic specifications is unwinding legacy mechanical designs across the industry. Össur hf. leverages its Icelandic R&D base to dominate advanced bionic knee systems. Ottobock SE & Co. KGaA anchors European supply through vertically integrated manufacturing in Duderstadt. Stryker Corporation competes in hospital channel contracts with integrated orthopedic-to-prosthetic care pathways.
Orthopedic prosthetic devices are electromechanical or passive artificial limbs engineered from carbon fiber composites, titanium alloys, or thermoplastic polymers to replace missing extremities and restore ambulatory or manipulative function. Lower limb prosthetics command the largest revenue pool due to weight-bearing biomechanical demands and Medicare reimbursement centrality, while exoskeletons represent the fastest-expanding category as spinal cord injury rehabilitation protocols adopt powered gait assistance. Sports applications in upper limb myoelectric systems concentrate margin pools among specialized titanium and carbon fiber configurations for competitive athletes.
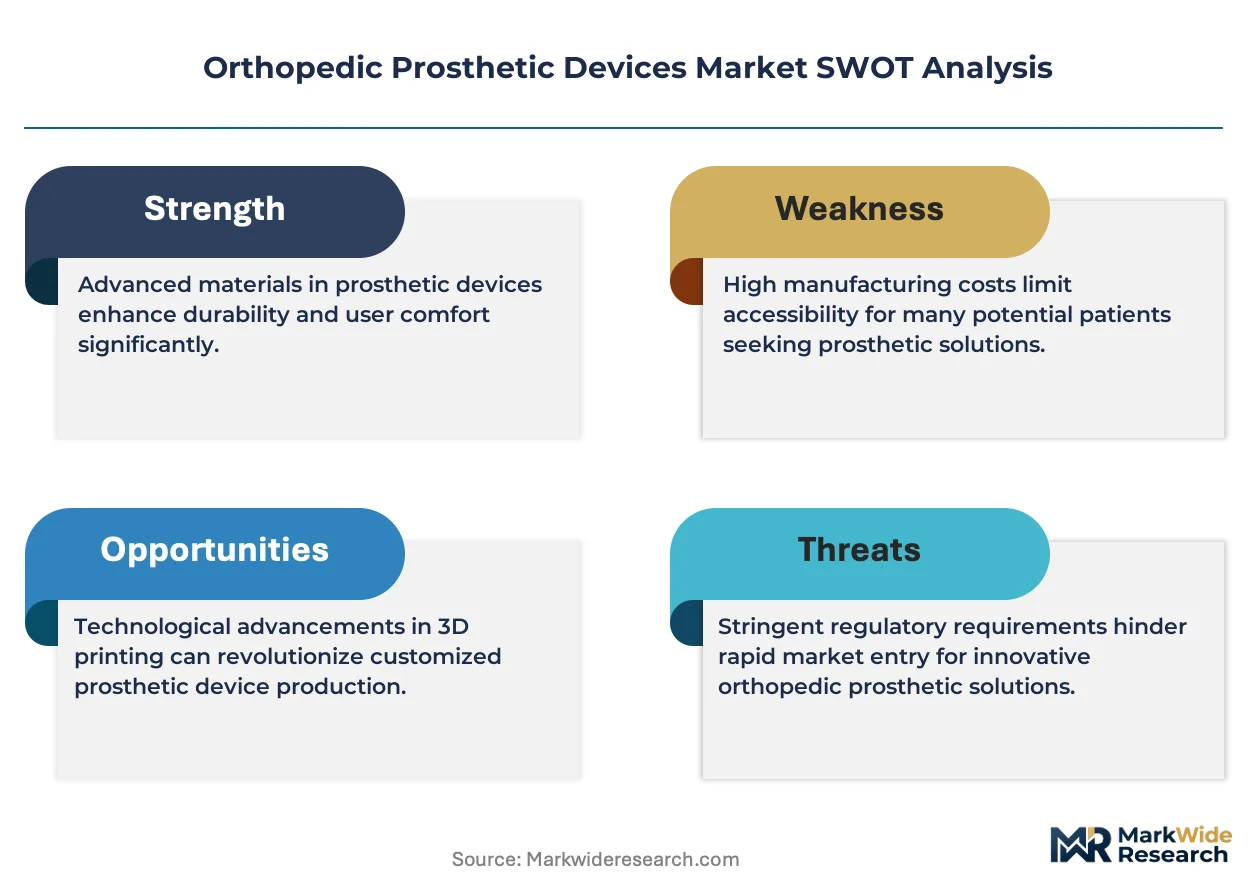
The FDA regulates these devices under 510(k) and De Novo pathways requiring clinical validation of microprocessor safety algorithms, while the EU MDR mandates notified body conformity assessment for Class IIa and above limb prostheses. Japan's PMDA enforces JIS standards compatibility for imported components, creating tiered market access friction. Stakeholders must monitor reimbursement code revisions by CMS and national health authorities as powered and osseointegrated systems challenge existing fee schedules.
Market Dynamics
Microprocessor-controlled lower limb systems are compressing reimbursement timelines as CMS and private payers demand real-world mobility outcome data before extending coverage codes to powered prosthetic categories.
Growth Catalysts
- EU Medical Device Regulation:MDR Class IIa conformity assessment for limb prostheses is accelerating documentation standards that favor manufacturers with established clinical validation pipelines.
- Carbon fiber composite fabrication:Automated layup processes are reducing per-unit material costs while improving strength-to-weight ratios in transtibial socket systems.
- Germany:Federal reimbursement frameworks for osseointegrated implants are expanding eligible patient populations beyond traditional socket-based candidates.
Market Restraints
- Titanium alloy supply concentration:Sponge production bottlenecks in Russia and China are creating input cost volatility for knee and ankle component manufacturers.
- FDA 510(k) pathway friction:Microprocessor safety algorithm validation requirements are extending clearance timelines for novel powered knee systems by 12-18 months.
- Passive mechanical substitutes:Polycentric knee mechanisms retain cost advantages in emerging markets where reimbursement depth cannot support bionic systems.
Strategic Opportunities
- Japan:PMDA JIS standards alignment for imported components creates first-mover advantages for manufacturers establishing local technical file repositories.
- Sports medicine applications:Myoelectric upper limb configurations for competitive athletes command margin premiums through specialized titanium and carbon fiber specifications.
- Telehealth integration:Remote prosthetic tuning protocols are opening rural access channels previously constrained by certified prosthetist density.
Industry Challenges
- Prosthetist training capacity:Microprocessor system programming competencies are concentrating among specialists in major metropolitan rehabilitation centers.
- CMS code alignment:Existing fee schedules lack granularity for distinguishing powered from passive components, compressing achievable reimbursement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Prosthetic Devices Market |
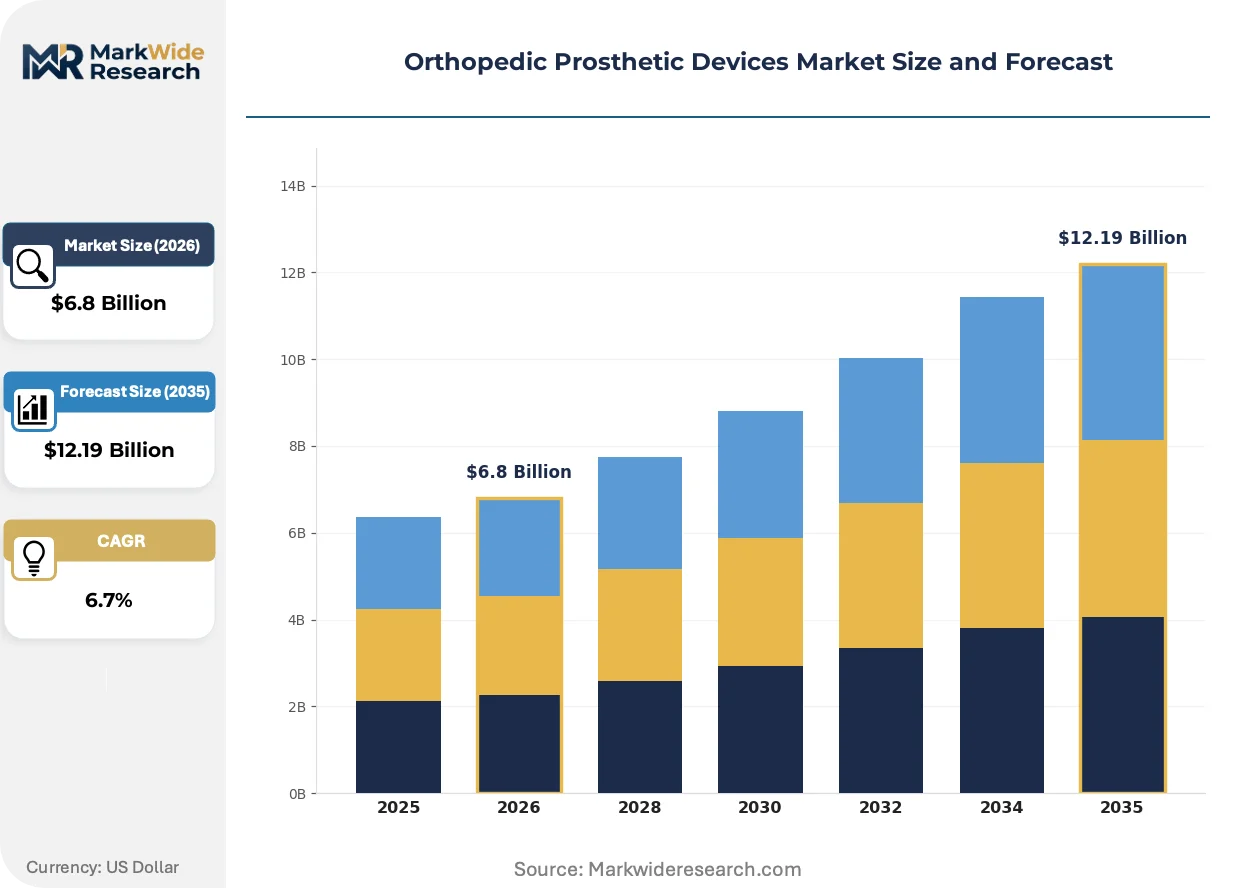
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lower Limb, Upper Limb, Exoskeletons, Modular Systems Material: Carbon Fiber, Titanium, Thermoplastics, Wood Application: Rehabilitation, Sports, Aesthetics, Biomechanics End User: Hospitals, Rehabilitation Centers, Home Care, NGOs |
| Companies Covered | Össur hf., Ottobock SE & Co. KGaA, Zimmer Biomet, Stryker Corporation, Blatchford Group, DePuy Synthes, Hanger Inc., Fillauer LLC, WillowWood Global LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Prosthetic Devices Market Strategic Shifts
Electromechanical convergence is rewriting competitive boundaries between traditional prosthetic manufacturers and robotics specialists. Three developments are compressing product cycles and reshaping buyer expectations.
Magnetorheological fluid dampers in ankle-foot systems are displacing hydraulic resistance mechanisms across Medicare-funded transtibial fittings. Veterans Affairs procurement channels are prioritizing these configurations for fall-risk reduction. The technology is compressing maintenance intervals while expanding ambulatory terrain adaptability.
MDR notified body capacity constraints are forcing manufacturers to consolidate technical documentation across multiple product families. Small-to-mid prosthetic firms are outsourcing quality management system maintenance to specialized regulatory consultancies. Knee and ankle component suppliers with pre-2021 MDD certificates face the steepest conformity assessment backlogs.
Hospital system procurement consolidation is compressing vendor panels for microprocessor limb systems. Integrated delivery networks in the United States are demanding episode-of-care pricing that bundles pre-operative assessment through post-delivery adjustments. This model is displacing traditional fee-for-service relationships between prosthetic clinics and referral sources.
Orthopedic Prosthetic Devices Market Segmentation
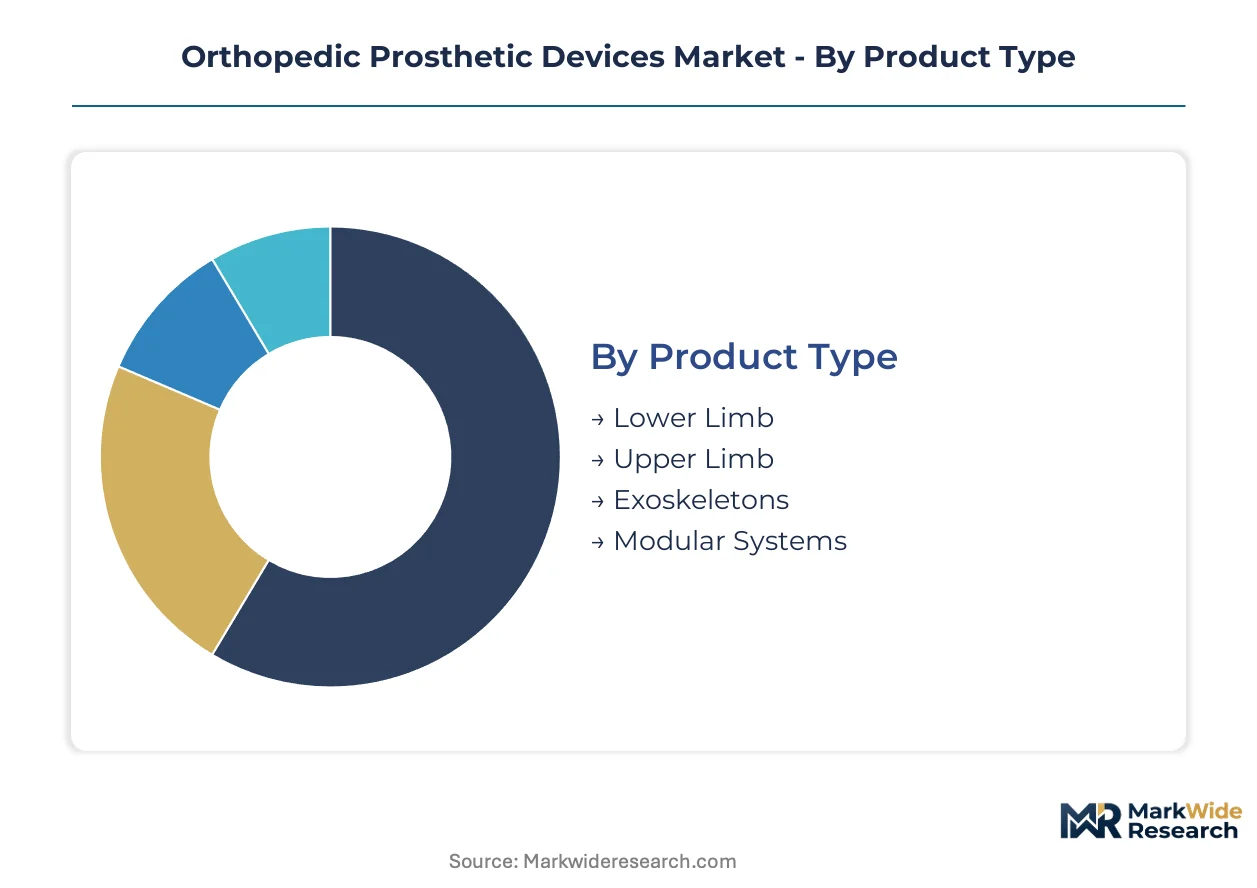
Orthopedic prosthetic device segmentation reveals distinct procurement patterns across clinical and non-clinical channels. Channel concentration varies sharply by product complexity, reimbursement eligibility, and prosthetist training requirements.
Product Type:
Channel distribution splits sharply between hospital-integrated procurement for complex systems and independent clinic dispensing for standard configurations.
- Lower Limb:Transtibial and transfemoral configurations incorporate microprocessor knees and carbon fiber energy-storing feet. Demand concentrates in Medicare-funded trauma centers and Veterans Affairs rehabilitation hospitals where weight-bearing biomechanics drive specification requirements.
- Upper Limb:Myoelectric and body-powered systems employ surface electrode arrays or cable harness mechanisms. Sports medicine channels in Germany and the United States absorb premium titanium variants for competitive athlete fittings.
- Exoskeletons:Powered gait assistance systems for spinal cord injury rehabilitation flow through hospital episode-of-care contracts.
- Modular Systems:Interchangeable socket and pylon components enable rapid configuration adjustments in prosthetist workshop settings.
Lower limb dominates installed base. Exoskeletons are where expansion concentrates.
Material:
Cost tier stratification separates aerospace-grade composites from commodity polymers in reimbursement-sensitive markets.
- Carbon Fiber:Automated layup manufacturing delivers strength-to-weight ratios essential for transtibial socket fabrication. Germany and Japan lead procurement of aerospace-grade pre-preg configurations for competitive mobility applications.
- Titanium:Vacuum arc remelt processing yields fatigue-resistant knee and ankle components. Supply concentration in Russian and Chinese sponge production creates input cost volatility for European manufacturers.
- Thermoplastics:Polypropylene and polyethylene socket liners dominate volume production in emerging markets.
- Wood:Laminated maple and willow constructions persist in low-cost passive limb segments.
Carbon fiber commands premium pricing tiers. Thermoplastics anchor volume manufacturing.
Application:
Customer type divergence separates institutional procurement protocols from individual aesthetic preferences.
- Rehabilitation:Post-amputation functional restoration protocols specify microprocessor-controlled systems with fall-risk reduction algorithms. CMS reimbursement codes concentrate demand in United States hospital outpatient departments.
- Sports:Specialized titanium and carbon fiber configurations for competitive athletics command margin premiums through direct-to-athlete channels.
- Aesthetics:Silicone cosmetic gloves and passive limb covers serve self-pay patients outside reimbursement frameworks.
- Biomechanics:Research-grade motion capture integration supports academic and clinical gait analysis laboratories.
Rehabilitation absorbs institutional procurement volume. Sports applications generate margin expansion.
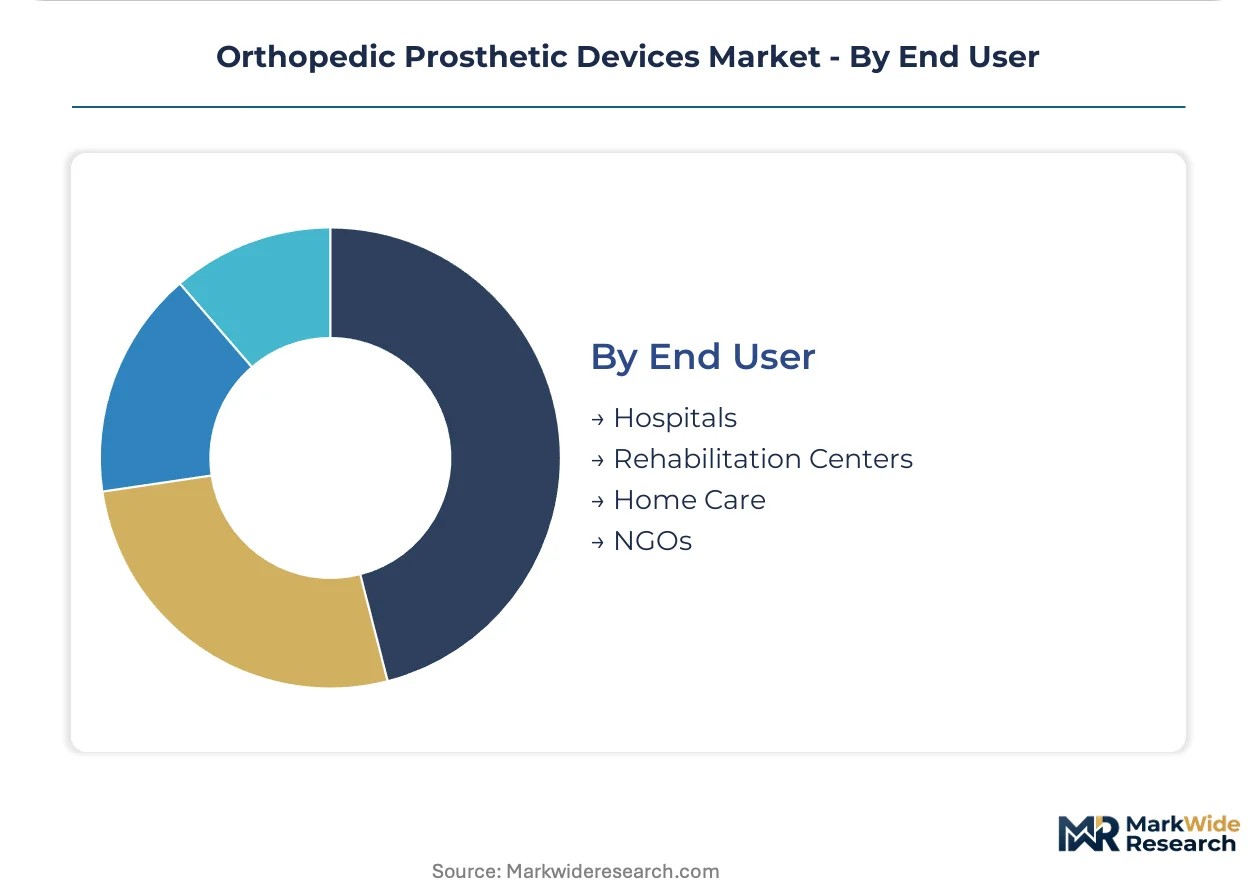
End User:
Procurement authority concentration shapes vendor contracting strategies across facility types.
- Hospitals:Integrated delivery networks bundle pre-operative assessment through prosthetic delivery under episode-of-care pricing models. United States health systems are consolidating vendor panels for microprocessor limb categories.
- Rehabilitation Centers:Specialized prosthetist density determines regional access to microprocessor programming capabilities in major metropolitan clusters.
- Home Care:Remote tuning protocols and direct-to-patient shipping expand rural access beyond certified prosthetist availability.
- NGOs:Donor-funded distribution channels deploy passive mechanical systems in low-resource settings.
Hospitals control complex system procurement. Home care channels are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prosthetic device manufacturing clusters in Germany, the United States, and Japan concentrate advanced carbon fiber fabrication and microprocessor system integration. Icelandic R&D operations feed component supply into European assembly networks. Supply chain nodes for titanium alloy processing face input volatility from concentrated sponge sources.
United States
Veterans Affairs procurement channels absorb volume for microprocessor lower limb systems with fall-risk algorithms. FDA 510(k) clearance pathways demand extended clinical validation timelines for powered knee mechanisms. Rehabilitation hospital clusters in Baltimore and Chicago anchor prosthetist training capacity for complex system programming.
Germany
Federal reimbursement frameworks for osseointegrated implants expand eligible patient populations beyond socket-based fittings. EU MDR Class IIa conformity assessment mandates notified body documentation that favors established clinical validation pipelines. The Duderstadt manufacturing corridor concentrates vertically integrated production of knee and ankle components.
Japan
Aging demographics concentrate demand in metropolitan rehabilitation centers with certified prosthetist density. PMDA enforces JIS standards compatibility for imported components, creating technical file repository requirements. The Kanto region around Tokyo anchors academic gait analysis laboratories driving research-grade procurement.
United Kingdom
NHS England procurement consolidation compresses vendor panels for microprocessor limb categories. MHRA post-Brexit regulatory alignment maintains CE marking recognition with additional UKCA conformity routes. London and Manchester rehabilitation centers concentrate specialized fitting capacity for complex transfemoral configurations.
China
Domestic manufacturers scale thermoplastic socket production for volume-tier rehabilitation markets. NMPA medical device registration requirements extend clearance timelines for imported microprocessor systems. The Yangtze River Delta clusters carbon fiber pre-preg fabrication for regional component supply.
Orthopedic Prosthetic Devices Market Competitive Environment
Concentration sits with diversified orthopedic conglomerates and specialized prosthetic manufacturers. The vendor base splits between integrated hospital channel contractors and independent clinic suppliers. Two strategic archetypes dominate: vertically integrated fabricators controlling carbon fiber layup through final assembly, and technology licensors sourcing microprocessor modules from robotics specialists. Competitive moves center on episode-of-care pricing negotiations with integrated delivery networks and regulatory consultancy outsourcing for MDR technical documentation.
Among Icelandic and German fabricators, Össur hf. and Ottobock SE & Co. KGaA exemplify the vertically integrated archetype with captive R&D and manufacturing operations. Stryker Corporation occupies a position bridging orthopedic implant portfolios into prosthetic care pathway contracts. These three anchors represent distinct competitive vectors: Nordic technology specialization, Central European manufacturing scale, and American hospital system integration.
| Leading Market Players |
|---|
| Össur hf. |
| Ottobock SE & Co. KGaA |
| Zimmer Biomet |
| Stryker Corporation |
| Blatchford Group |
| DePuy Synthes |
| Hanger Inc. |
| Fillauer LLC |
| WillowWood Global LLC |
| Others |
Value Chain & Pricing Dynamics
Ninety-day carbon fiber pre-preg inventory cycles in German fabrication facilities concentrate pricing power with aerospace-grade suppliers, while titanium sponge lead times stretching to six months force knee component manufacturers into long-term offtake commitments that lock in cost structures across reimbursement tiers.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across microprocessor limb categories, with powered knee systems commanding premium positioning against passive mechanical alternatives. Three-tier pricing structure across premium bionic, standard microprocessor, and economy passive levels separates reimbursement-eligible hospital procurements from self-pay aesthetic fittings. Pricing pressure stems from CMS code granularity gaps that compress margins on powered components. Price-sensitive buyers cluster in emerging markets where thermoplastic socket systems dominate, while Veterans Affairs and German federal insurers show lowest sensitivity to premium configurations.
Supply Chain Analysis
China and Russia anchor titanium sponge production for knee and ankle alloy feedstock, while Germany and Iceland concentrate carbon fiber layup and final microprocessor assembly. The industry draws from vacuum arc remelt processing, automated pre-preg fabrication, and surface electrode array manufacturing as core input streams. Single-source vulnerability in Russian sponge supply creates exposure to export restriction cascades. Distribution runs through hospital-integrated delivery networks in the United States and specialized prosthetist workshop channels in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic prosthetic device procurement is recovering from reimbursement compression cycles, with Medicare code expansion for powered systems serving as the cyclical anchor.
For Market Incumbents: Secure MDR technical documentation pipelines ahead of notified body capacity constraints, and deepen backward integration into carbon fiber pre-preg fabrication to offset aerospace-grade material cost volatility. Passive mechanical substitutes from Asian manufacturers threaten volume-tier margins, making certification investment in Class IIa conformity the critical defensive lever. For New Entrants and Emerging Players: FDA De Novo fast-track pathways for novel powered ankle mechanisms open white-space entry around fall-risk algorithm validation, with rural telehealth tuning protocols representing the most penetrable channel. Sports medicine myoelectric configurations for competitive athletes offer margin-rich positioning outside reimbursement complexity. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-elasticity play because aging populations in Japan, Germany, and the United States guarantee sustained demand compression regardless of cyclical reimbursement friction. Acquisition targets should display captive R&D in magnetorheological damping or osseointegrated fixation. The signal to watch is CMS code granularity revisions distinguishing powered from passive component reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class IIa Conformity Investment | Notified body documentation consolidation accelerates market access for multi-product families. |
| Episode-of-Care Pricing Negotiation | Hospital system bundling from pre-operative assessment through post-delivery adjustments displaces fee-for-service relationships. |
| Telehealth Integration Development | Remote prosthetic tuning protocols expand rural access beyond certified prosthetist density constraints. |
| Osseointegrated Implant Reimbursement Strategy | German federal framework expansion creates transferable precedent for eligible patient population growth. |
| Magnetorheological Damper Product Launch | Veterans Affairs procurement prioritization for fall-risk reduction compresses maintenance intervals. |
Study Parameters
Cross-validation between prosthetist workshop interviews and hospital procurement database analysis anchors the qualitative findings, combining primary discussions with certified prosthetists, biomedical engineers, GPO contracts managers, and rehabilitation center administrators against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement codes, EU MDR notified body registries, and hospital supply chain disclosures. Bottom-up prosthetic clinic volume estimates and top-down national health expenditure aggregates complete the triangulation.
Sensitivity analysis across carbon fiber cost scenarios, titanium sponge price bands, and reimbursement code revision timelines tests forecast robustness over the projection horizon. Segmentation dimensions span product type complexity, material grade tier, application channel, and end-user procurement authority. CAGRs derive from installed base attrition rates and new amputee fitting volumes, with microprocessor adoption curves and exoskeleton rehabilitation protocol penetration serving as industry-specific demand drivers.
Underlying assumptions cover stable Medicare funding levels and MDR notified body capacity normalization, with deviation risk concentrated in titanium export restrictions and CMS code granularity delays. Recalibration cycles align with material shifts in reimbursement policy and raw material supply geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Intramedullary Nails Market
Orthopedic Devices
Small Bone and Joint Orthopedic Devices Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Scoliosis Treatment Market