
 Global Orthopedic Implant Market | 2026-2036
Global Orthopedic Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Implant Market Foresight
Additive manufacturing is fragmenting traditional forging and casting workflows across orthopedic implant production. Stryker Corporation leverages titanium powder-bed fusion to consolidate complex geometries into single-build acetabular cups. Zimmer Biomet anchors its competitive position through proprietary porous titanium structures that enhance osseointegration. Smith+Nephew differentiates via its advanced bearing surface technologies for joint replacement applications.
Orthopedic implants are load-bearing medical devices typically fabricated from biocompatible alloys such as titanium Ti-6Al-4V ELI, cobalt-chrome-molybdenum, or ultra-high molecular weight polyethylene, designed to restore skeletal function through arthroplasty, osteosynthesis, or spinal stabilization. Joint Replacement dominates value generation due to high procedure volumes and premium pricing for bearing surface innovations, while Spinal Implants represent the fastest-expanding category driven by minimally invasive fusion techniques and expandable cage designs. Trauma Surgery applications sustain steady demand through emergency department admission patterns and aging-related fragility fractures.
The FDA's 510(k) and PMA pathways govern US market access, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for implantable devices through its enhanced notified body oversight. China's NMPA has accelerated review timelines for domestically manufactured orthopedic innovations under its priority review channels. Stakeholders must monitor how real-world evidence mandates and value-based procurement frameworks reshape reimbursement dynamics across major markets.
Market Dynamics
Additive manufacturing workflows are compressing production timelines for complex implant geometries while simultaneously fragmenting the supplier base away from traditional forging houses toward specialized metal powder processors and precision printing service providers.
Growth Catalysts
- Aging Demographics:The United States, Germany, and Japan sustain procedure volumes through expanding Medicare coverage and private reimbursement infrastructure for joint replacement surgeries.
- FDA 510(k) Breakthrough Pathway:Accelerated clearance timelines for novel implant designs reduce commercialization lag between prototype validation and market entry.
- Titanium Powder-Bed Fusion:This additive process consolidates previously machined acetabular cup assemblies into single-build components, trimming production steps and material waste.
Market Restraints
- Titanium Powder Supply Concentration:Spherical Ti-6Al-4V ELI powder production concentrates among a handful of gas atomization specialists, creating input cost volatility and qualification bottlenecks.
- EU MDR Clinical Evidence Requirements:Stricter notified body oversight for implantable devices extends certification timelines and elevates documentation burdens for manufacturers seeking CE marking.
- Bearing Surface Wear Limitations:Conventional ultra-high molecular weight polyethylene exhibits oxidative degradation under gamma sterilization, constraining implant longevity in younger, active patients.
Strategic Opportunities
- India's Priority Review Channels:CDSCO has accelerated orthopedic implant approvals for domestically manufactured innovations, opening access to a surgical volume expansion corridor.
- Patient-Specific Instrumentation Convergence:Preoperative CT-to-implant matching software combined with robotic surgical systems enables customized alignment protocols.
- Ambulatory Surgery Center Channel:Minimally invasive fusion techniques and short-stay joint protocols are shifting spinal and arthroplasty procedures away from inpatient hospital settings.
Industry Challenges
- Biocompatibility Certification Complexity:ISO 10993 cytotoxicity and sensitization testing requirements for novel porous titanium structures extend validation cycles.
- Additive Manufacturing Skill Scarcity:Qualified technicians for laser powder-bed fusion parameter optimization and post-process hot isostatic pressing remain concentrated among a narrow specialist labor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Implant Market |
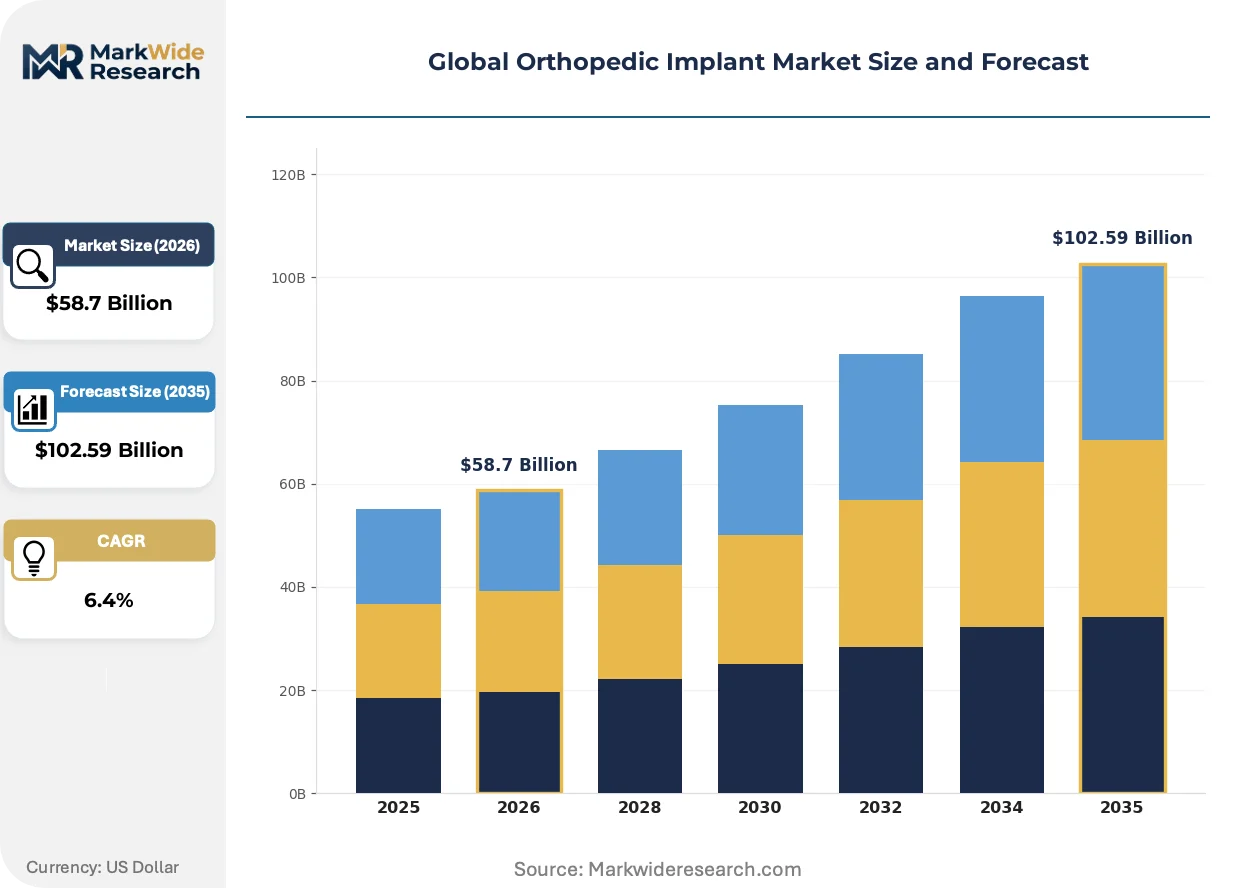
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Joint Replacement, Bone Plates, Screws & Nails, Spinal Implants, Dental Implants, Connectors Material: Titanium, Stainless Steel, Cobalt Chrome, Polyethylene, Ceramic, PEEK Application: Fracture Repair, Spinal Fusion, Joint Reconstruction, Dental Restoration, Trauma Surgery, Sports Injuries End User: Orthopedic Clinics, Ambulatory Surgical Centers, Specialty Hospitals, Rehabilitation Centers, Trauma Centers, Dental Clinics |
| Companies Covered | Smith+Nephew, Arthrex, Stryker Corporation, Enovis, Globus Medical, DePuy Synthes, Medtronic, Orthofix Medical, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Implant Market Shifts & Advancements
Orthopedic implant production is undergoing a platform shift from subtractive machining toward layer-by-layer consolidation, while regulatory frameworks and procurement channels recalibrate around real-world performance data.
Titanium powder-bed fusion is collapsing the traditional multi-step acetabular cup supply chain. Specialty hospitals and high-volume orthopedic service lines are adopting these consolidated geometries at accelerating pace. The structural consequence compresses supplier tiers from forging houses, machine shops, and assembly operations into direct printer-to-sterile-pack workflows.
China's NMPA priority review channels are compressing domestic orthopedic innovation timelines. Domestic manufacturers gain accelerated market access relative to imported device timelines. Joint replacement and spinal implant categories see the most pronounced filing advantages under this framework.
Hospital procurement committees are consolidating vendor relationships around single-source implant platforms with bundled instrument and disposable agreements. Independent distributors and manufacturer-direct sales forces are losing share to integrated delivery network contracting offices. This concentration is most visible in United States metropolitan hospital systems with captive ambulatory surgery center networks.
Global Orthopedic Implant Market Segmentation
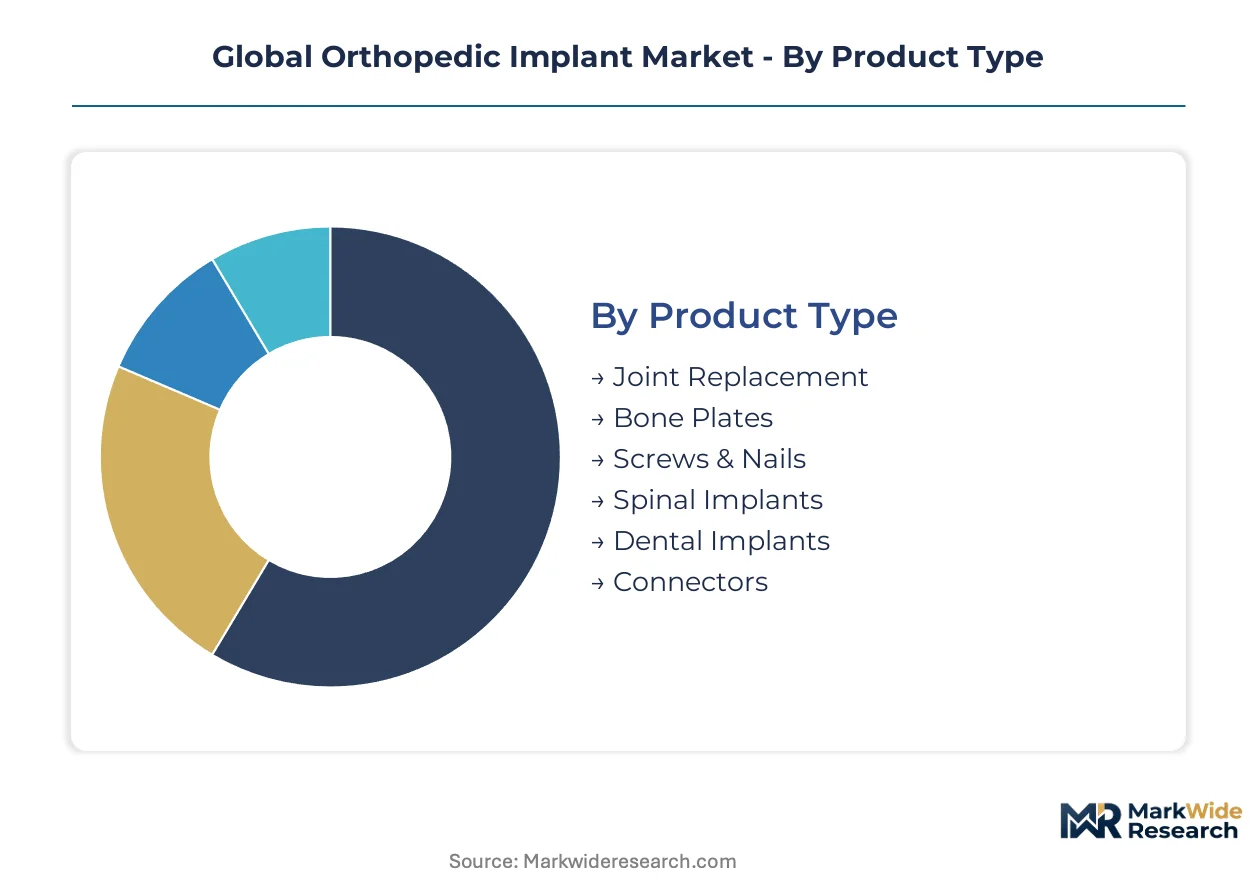
Orthopedic implant segmentation reveals divergent service intensity requirements across product categories. Joint replacement systems demand extensive instrument sterilization logistics and revision surgery protocols, while trauma hardware operates through emergency procurement channels with minimal preoperative planning support.
Product Type:
After-sales service intensity varies dramatically across implant categories, with complex systems requiring multi-year instrument maintenance contracts and single-use trauma devices needing minimal technical support.
- Joint Replacement:Bearing surface assemblies combining metal femoral heads with polyethylene or ceramic inserts demand precision balancing and wear monitoring protocols. Demand concentrates in the United States through Medicare-funded arthroplasty programs, where specialty hospitals bundle lifetime implant tracking with surgical warranties.
- Spinal Implants:Expandable cages and pedicle screw systems incorporate titanium porous structures for osseointegration. Germany's statutory health insurance system sustains procedure volumes for degenerative disc disease interventions, though EU MDR clinical evidence requirements extend certification timelines for novel fusion devices.
- Bone Plates:Anatomically contoured titanium and stainless steel constructs for fracture stabilization.
- Screws & Nails:Intramedullary and cortical fixation hardware for long-bone and small-fragment applications.
- Dental Implants:Titanium root-form fixtures and abutment systems for prosthetic restoration.
- Connectors:Modular linking components for external fixation and spinal rod assemblies.
Joint Replacement holds the largest share; momentum sits with Spinal Implants.
Material:
Cost tier stratification separates premium titanium and ceramic formulations from standard stainless steel and polyethylene alternatives, with PEEK emerging as a mid-tier specialty option.
- Titanium:Ti-6Al-4V ELI alloy dominates load-bearing applications through superior strength-to-weight ratio and biocompatibility. Powder-bed fusion additive manufacturing is consolidating acetabular cup production in the United States, though spherical powder supply concentration among gas atomization specialists creates input volatility.
- Polyethylene:Ultra-high molecular weight formulations serve as bearing surfaces in joint replacement, with cross-linked variants reducing wear debris generation. Japan's aging population sustains demand for polyethylene liners in hip and knee arthroplasty, though oxidative degradation under gamma sterilization constrains implant longevity in younger patients.
- Stainless Steel:316L grade for temporary fracture fixation and cost-sensitive trauma applications.
- Cobalt Chrome:Molybdenum-containing alloys for femoral heads and bearing surfaces.
- Ceramic:Alumina and zirconia formulations for wear-resistant bearing couples.
- PEEK:Polyetheretherketone polymer for spinal cages and trauma plates requiring radiolucency.
Titanium captures premium volume; PEEK is climbing the fastest.
Application:
Application segmentation tracks patient acuity and reimbursement pathway differences, from emergency trauma admissions to elective joint reconstruction scheduling.
- Fracture Repair:Osteosynthesis procedures for traumatic and fragility fractures.
- Spinal Fusion:Interbody and posterolateral fusion techniques for degenerative conditions.
- Joint Reconstruction:Arthroplasty interventions for end-stage osteoarthritis and rheumatoid arthritis.
- Dental Restoration:Implant-supported prosthetics for edentulous and partially dentate patients.
- Trauma Surgery:Emergency orthopedic interventions for polytrauma and open fractures.
- Sports Injuries:Ligament reconstruction and cartilage repair procedures in active populations.
Joint Reconstruction leads procedure value; Spinal Fusion shows steepest expansion trajectory.
End User:
Customer type determines procurement complexity, with integrated delivery networks consolidating vendor relationships around single-source platforms.
- Specialty Hospitals:Dedicated orthopedic service lines with captive ambulatory surgery center networks.
- Ambulatory Surgical Centers:Short-stay joint and spinal procedures shifting away from inpatient settings.
- Orthopedic Clinics:Outpatient consultation and minor procedure facilities.
- Trauma Centers:Level I and II emergency departments with 24-hour orthopedic coverage.
- Rehabilitation Centers:Post-acute care and prosthetic fitting facilities.
- Dental Clinics:Private practice and group settings for implant placement and restoration.
Specialty Hospitals dominate implant procurement volume; Ambulatory Surgical Centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty hospitals and integrated delivery networks concentrate implant procurement in markets with mature private reimbursement infrastructure and aging patient populations. The United States, Germany, and Japan sustain the highest procedure volumes through dedicated orthopedic service lines. China's domestic manufacturing base is capturing share via accelerated regulatory pathways.
United States
Medicare-funded arthroplasty programs and captive ambulatory surgery center networks drive implant consumption. The FDA's 510(k) breakthrough pathway compresses clearance timelines for novel designs. The Midwest surgical corridor spanning Ohio and Indiana hosts concentrated distribution hubs serving integrated delivery networks.
Germany
Statutory health insurance sustains spinal fusion and joint replacement volumes through comprehensive procedure coverage. EU MDR notified body oversight extends certification timelines for implantable devices. The Baden-Württemberg medical technology cluster around Tübingen and Stuttgart anchors precision manufacturing for porous titanium structures.
China
Domestic surgical volume expansion and priority review channels accelerate market access for locally manufactured innovations. NMPA has compressed review timelines for orthopedic implants under domestic manufacturer preference programs. The Suzhou industrial park concentration hosts additive manufacturing service providers supplying acetabular cup geometries.
Japan
Aging demographics and universal health coverage sustain polyethylene liner demand for hip and knee arthroplasty. PMDA maintains rigorous clinical evidence standards for bearing surface innovations. The Kansai manufacturing belt around Osaka retains specialized forging capacity for cobalt-chrome femoral heads.
India
CDSCO priority review channels for domestically manufactured implants open access to surgical volume expansion corridors. Central government procurement frameworks and private hospital chain consolidation reshape vendor selection criteria. The Maharashtra medical device cluster around Mumbai-Pune hosts trauma hardware assembly operations.
Global Orthopedic Implant Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments. Consolidated integrated delivery network contracting favors platform vendors with bundled instrument and disposable agreements. Three archetypes dominate: diversified conglomerates with full orthopedic portfolios, mid-cap specialists with additive manufacturing capabilities, and regional trauma hardware suppliers. Competitive moves center on backward integration into titanium powder supply and patient-specific instrumentation software licensing.
Within the diversified conglomerate tier, Stryker Corporation and Zimmer Biomet occupy positions anchoring premium joint replacement platforms. Smith+Nephew exemplifies the bearing surface specialist archetype through differentiated material science positioning. These three entities represent the channel-control end of the competitive spectrum where procurement consolidation most directly rewards scale.
| Leading Market Players |
|---|
| Smith+Nephew |
| Arthrex |
| Stryker Corporation |
| Enovis |
| Globus Medical |
| DePuy Synthes |
| Medtronic |
| Orthofix Medical |
| Zimmer Biomet |
| Others |
Supply & Pricing Matrix
The Suzhou industrial park concentration shapes downstream pricing power through captive additive manufacturing capacity for acetabular cup geometries. Powder-bed fusion service providers in this cluster command premium positioning when spherical Ti-6Al-4V ELI supply tightens among gas atomization specialists.
Pricing Analysis
Cost-plus contracts with titanium powder indexation dominate procurement between OEMs and forging houses. Three-tier pricing structure across premium porous titanium, standard machined constructs, and economy stainless steel trauma hardware separates segments by osseointegration performance and sterilization logistics intensity. Price differentiation hinges on FDA breakthrough device designation and bundled instrument service agreements. Cost compression in standard joint replacement tiers is intensifying because integrated delivery networks are consolidating vendor relationships around single-source platforms.
Supply Chain Analysis
Export-control scrutiny over laser powder-bed fusion parameter sets and hot isostatic pressing specifications constrains technology transfer to emerging manufacturing hubs. Spherical titanium powder production concentrates in the United States, Germany, and China, while precision machining capacity clusters in Japan and Switzerland. Raw material flows draw from cobalt-chrome-molybdenum alloy stock, ultra-high molecular weight polyethylene resin, and ceramic bearing blanks. Single-source vulnerability sits with gas atomization specialists qualified to medical-grade powder specifications. Distribution runs through integrated delivery network contracting offices and GPO procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic implant procurement is shifting toward platform economics as hospital systems consolidate around interoperable instrument trays and patient-specific instrumentation software ecosystems.
For Market Incumbents: Pre-empt additive manufacturing talent scarcity by acquiring qualified laser parameter optimization specialists in the Baden-Württemberg cluster. Backward integration into spherical powder supply insulates against input volatility from gas atomization bottlenecks. Lock in multi-year GPO contracts before EU MDR clinical evidence requirements extend competitor certification timelines.
For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO priority review corridor for domestically manufactured trauma hardware. Target ambulatory surgery center channels with short-stay joint protocol instruments that bypass integrated delivery network contracting concentration. Lead with robotic surgical system compatibility and preoperative CT-to-implant matching software licensing.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement concentration rewards scale in instrument sterilization logistics and revision surgery protocol infrastructure. Target mid-cap specialists with captive additive manufacturing capabilities and NMPA domestic manufacturer preference positioning. Watch for inflection when real-world evidence mandates reshape reimbursement dynamics across Medicare and statutory health insurance systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Titanium Powder Supply Integration | Captive spherical Ti-6Al-4V ELI production insulates OEMs from gas atomization specialist bottlenecks. |
| Patient-Specific Instrumentation Software Licensing | CT-to-implant matching platforms lock hospital systems into proprietary alignment protocols. |
| FDA Breakthrough Device Pathway Submission | Accelerated 510(k) clearance compresses commercialization lag for novel porous titanium structures. |
| Ambulatory Surgery Center Channel Development | Short-stay joint protocols shift procedure volumes away from inpatient hospital contracting offices. |
| EU MDR Clinical Evidence Investment | Enhanced notified body documentation secures CE marking ahead of competitors facing certification delays. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare procedure databases, and hospital procurement contract repositories. Bottom-up demand modeling from procedure volumes and implant ASPs triangulated against top-down market sizing from manufacturer revenue disclosures.
Forecast inputs span joint replacement bearing surface innovations, spinal fusion cage expansion rates, and trauma hardware emergency admission patterns across the analysis window. Segmentation dimensions include product type, material grade tier, application acuity, and end-user procurement complexity. CAGRs were derived from trend extrapolation of Medicare-funded arthroplasty volumes, statutory health insurance coverage expansion, and additive manufacturing adoption curves in acetabular cup production.
Stress conditions across titanium powder supply disruptions, EU MDR certification timeline extensions, and integrated delivery network vendor consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement stability and regulatory pathway predictability. Material shifts in real-world evidence mandates or value-based procurement framework adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Patient Lifts Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
3D Medical Implant Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market