
 Pediatrics Orthotics Market | 2026-2036
Pediatrics Orthotics Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatrics Orthotics Market Analytics
3D scanning and additive manufacturing is reconfiguring how pediatric orthoses achieve anatomical precision at reduced production cycles. Ottobock leverages polymer science expertise to sustain leadership in dynamic ankle-foot systems for ambulatory children. Össur anchors its position through carbon-composite fabrication that reduces device weight without sacrificing structural load capacity. Boston Orthotics & Prosthetics specializes in scoliosis bracing protocols that dominate the Northeastern United States referral network.
Pediatrics orthotics encompass custom-fitted external mechanical devices engineered to correct, support, or compensate for musculoskeletal deformities in patients from infancy through adolescence, typically fabricated from thermoplastic polymers with activation temperatures between 60-80°C for vacuum-forming over positive molds. These devices serve to maintain joint alignment, distribute biomechanical loads, and enable developmental motor progression in conditions where neuromuscular control remains impaired. Application segmentation shows cerebral palsy representing the most established clinical pathway, while muscular dystrophy applications are expanding fastest as earlier genetic diagnosis extends intervention windows. Material segmentation reveals thermoplastics occupying the highest volume share due to reworkability and radiolucency, though composite materials are capturing margin pools in high-performance athletic and dynamic gait applications.
FDA Center for Devices and Radiological Health oversees pediatric orthotic classification through 510(k) pathways, while ISO 13485 quality management standards govern manufacturing consistency across international supply chains. State-level Medicaid Early and Periodic Screening, Diagnostic and Treatment benefit programs shape reimbursement access for low-income pediatric populations in the United States. Stakeholders must monitor how FDA breakthrough device designation criteria evolve for pediatric-specific innovations and whether composite material qualification standards tighten under proposed biocompatibility revisions.
Market Dynamics
3D printing is compressing orthotic fabrication cycles from weeks to days while FDA pediatric device guidance accelerates approval pathways for anatomically adaptive designs.
Growth Catalysts
- Medicaid EPSDT Expansion:State-level Early and Periodic Screening, Diagnostic and Treatment benefit programs in the United States are extending orthotic coverage to low-income pediatric populations previously excluded from specialized intervention.
- Carbon-Composite Lightweighting:Advanced carbon-fiber fabrication techniques are reducing device mass by 40-60% without structural compromise, enabling ambulatory children with muscular dystrophy to sustain gait function longer.
- Genetic Diagnostic Velocity:Earlier identification of neuromuscular conditions through newborn screening panels is compressing intervention windows and expanding addressable patient cohorts.
Market Restraints
- Thermoplastic Input Volatility:Polypropylene and polyethylene resin prices fluctuate with petrochemical feedstock costs, squeezing margins for vacuum-forming fabricators serving high-volume pediatric clinics.
- Specialized Clinician Concentration:Pediatric orthotist certification programs graduate fewer than 200 specialists annually in the United States, creating referral bottlenecks in rural and secondary markets.
- Reimbursement Coding Complexity:HCPCS Level II code fragmentation across prefabricated versus custom-fitted categories creates claim denial risk and administrative burden for dispensing practices.
Strategic Opportunities
- Home-Based 3D Scanning:Smartphone-integrated photogrammetry applications are enabling remote limb measurement capture, opening rural and ex-urban patient populations previously requiring multi-hour travel to tertiary centers.
- Sports Medicine Crossover:Dynamic ankle-foot orthosis designs proven in cerebral palsy gait correction are migrating to pediatric athletic injury rehabilitation, creating premium-priced performance segments.
- ISO 13485-Certified Contract Manufacturing:Quality-managed fabrication partnerships allow device companies to scale production without capital-intensive in-house molding infrastructure.
Industry Challenges
- Biomechanical Modeling Talent Scarcity:Computational design expertise combining musculoskeletal simulation with additive manufacturing parameter optimization remains concentrated in academic medical centers.
- Legacy CAD System Integration:Established patient management databases in children's hospitals resist interoperability with cloud-native 3D modeling platforms, forcing parallel workflow maintenance.
- Multi-Site Clinical Validation Burden:Pediatric device trials require IRB approval across geographically dispersed investigational sites, extending time-to-market for novel orthotic mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatrics Orthotics Market |
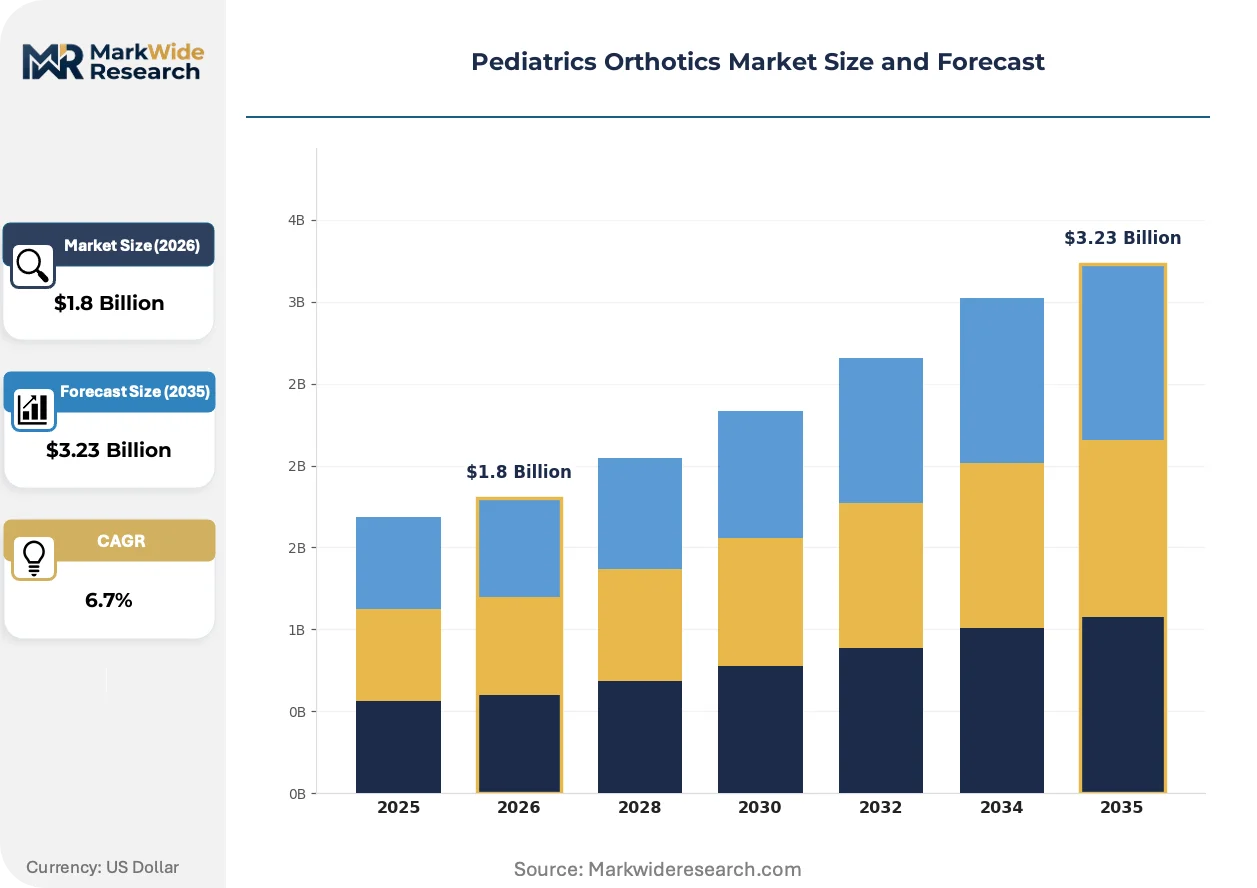
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foot Orthoses, Knee Orthoses, Ankle Foot Orthoses, Hip Abduction Orthoses Application: Cerebral Palsy, Spina Bifida, Down Syndrome, Muscular Dystrophy End User: Pediatric Clinics, Hospitals, Home Care Settings, Rehabilitation Centers Material: Thermoplastics, Foam, Metal, Composite Materials |
| Companies Covered | Ottobock, Össur, Hanger Clinic, DJO Global, Fillauer LLC, Boston Orthotics & Prosthetics, Becker Orthopedic, Breg, Allard USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatrics Orthotics Market Evolving Landscape
Digital fabrication workflows are displacing plaster-casting orthodoxy while regulatory frameworks adapt to patient-specific device classification. Material science advances and care model restructuring are simultaneously reshaping product architecture and service delivery.
Structured light scanning paired with generative design algorithms is digitizing how pediatric orthoses achieve anatomical conformity. Children's hospitals in the United States are deploying intraoral and limb scanners at point-of-care, eliminating shipping delays for positive molds. This convergence is digitizing supply chain geography by enabling distributed fabrication nodes near patient concentrations rather than centralized manufacturing.
FDA breakthrough device designation criteria for pediatric populations are tightening evidentiary standards for novel orthotic mechanisms. The Center for Devices and Radiological Health now requires longitudinal gait analysis data for dynamic systems seeking expedited review. Small-to-mid-sized orthotic manufacturers are responding by pre-submission engagement with FDA pediatric device consortia to align clinical trial endpoints.
Parents of children with cerebral palsy are increasingly demanding device transparency through embedded pressure sensors and smartphone-connected usage monitoring. This behavioral shift is unbundling traditional orthotic dispensing models by separating hardware provision from ongoing gait optimization services. The Northeastern United States referral networks are piloting subscription-based adjustment programs replacing single-transaction brace fittings.
Pediatrics Orthotics Market Segmentation
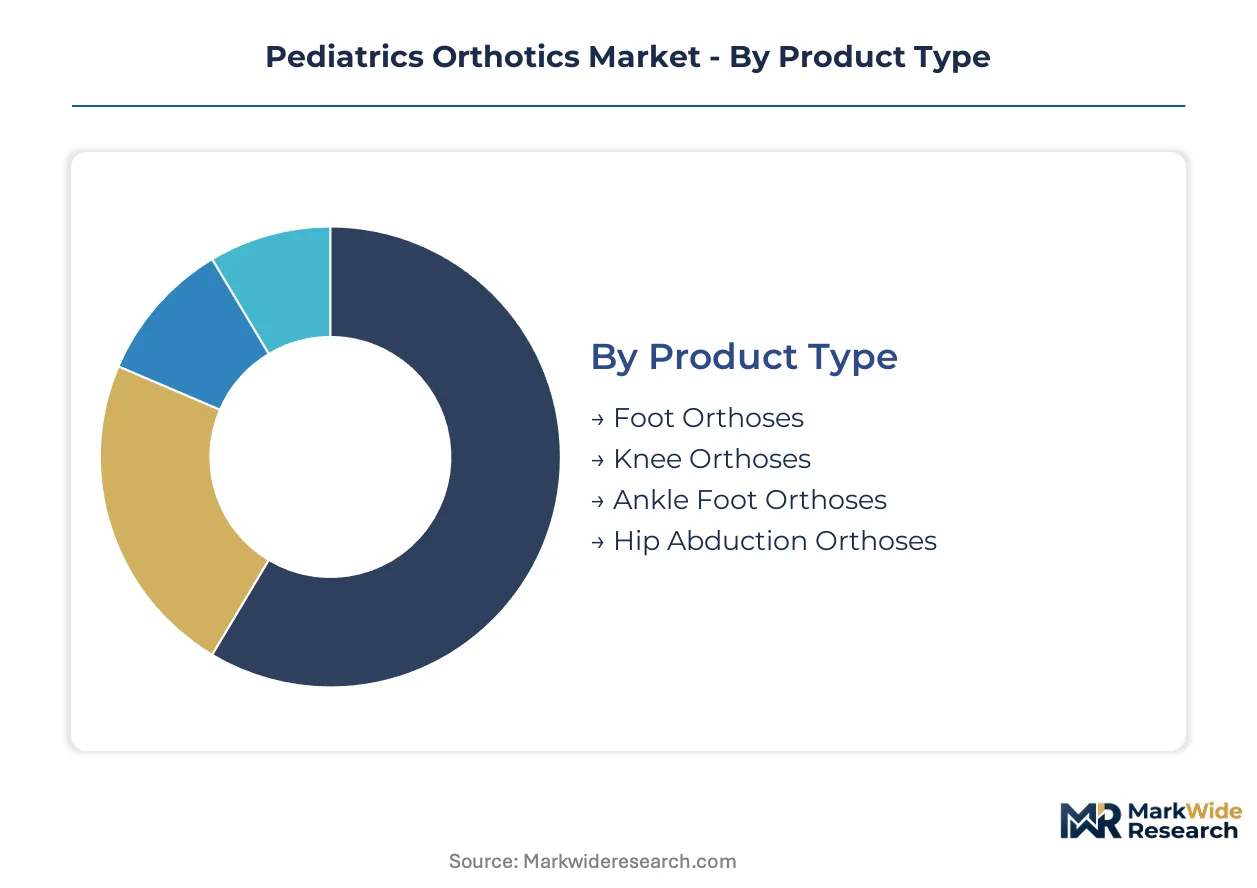
Pediatric orthotics segmentation reveals how clinical requirements, fabrication economics, and care delivery models intersect. Product architecture, patient condition severity, and material selection each create distinct competitive arenas with specialized regulatory and reimbursement profiles.
Product Type:
Application severity and ambulatory status determine which anatomical segments require mechanical intervention.
- Ankle Foot Orthoses:Dynamic systems incorporating articulated joints and plantarflexion resistance modulate ground reaction forces during hemiplegic gait. Demand concentrates in United States children's hospitals where cerebral palsy referral networks channel complex cases toward certified orthotists.
- Knee Orthoses:Hinged or locked configurations stabilize genu recurvatum or flexion contractures in neuromuscular conditions. Medicaid EPSDT coverage expansion in low-income United States counties is extending access to previously underserved ambulatory pediatric populations.
- Foot Orthoses:Custom-contoured insoles address pes planus and rotational malalignment in developmental conditions.
- Hip Abduction Orthoses:Pavlik harness derivatives and dynamic abduction systems manage hip dysplasia in infants.
Ankle Foot Orthoses commands the established base. The steepest expansion runs through Knee Orthoses as earlier muscular dystrophy diagnosis extends intervention windows.
Application:
Condition-specific biomechanical deficits shape device specification complexity and replacement frequency.
- Cerebral Palsy:Spastic diplegia and hemiplegia variants generate sustained demand for multi-joint systems with adjustable tone management. United States specialized children's hospitals drive prescription volume through comprehensive gait analysis laboratories.
- Muscular Dystrophy:Progressive weakness patterns require iterative device modification as ambulatory function declines. Genetic diagnostic velocity is compressing identification timelines and expanding addressable cohorts through newborn screening panel expansion.
- Spina Bifida:Myelomeningocele-related paralysis necessitates stance-control knee mechanisms and reciprocating gait orthoses.
- Down Syndrome:Hypotonia and ligamentous laxity drive preventive bracing protocols during motor milestone acquisition.
Cerebral Palsy retains the largest installed base. Muscular Dystrophy is gaining share fastest as earlier intervention protocols reshape treatment paradigms.
End User:
Care setting determines who controls device selection, fitting protocols, and ongoing adjustment responsibility.
- Pediatric Clinics:Dedicated orthotic practices with certified pediatric specialists manage complex multi-joint prescriptions. United States metropolitan referral networks concentrate expertise in academic medical center affiliates.
- Hospitals:Inpatient rehabilitation units and outpatient surgical centers handle post-operative immobilization and acute trauma bracing. Discharge planning protocols increasingly embed orthotic procurement within bundled episode frameworks.
- Rehabilitation Centers:Long-term therapy facilities coordinate device optimization with physical therapy milestones.
- Home Care Settings:Remote monitoring and telehealth fitting are emerging as pandemic-accelerated alternatives for stable, low-complexity prescriptions.
Pediatric Clinics anchor premium-complexity volume. Hospitals are capturing share fastest through integrated episode-of-care contracts.
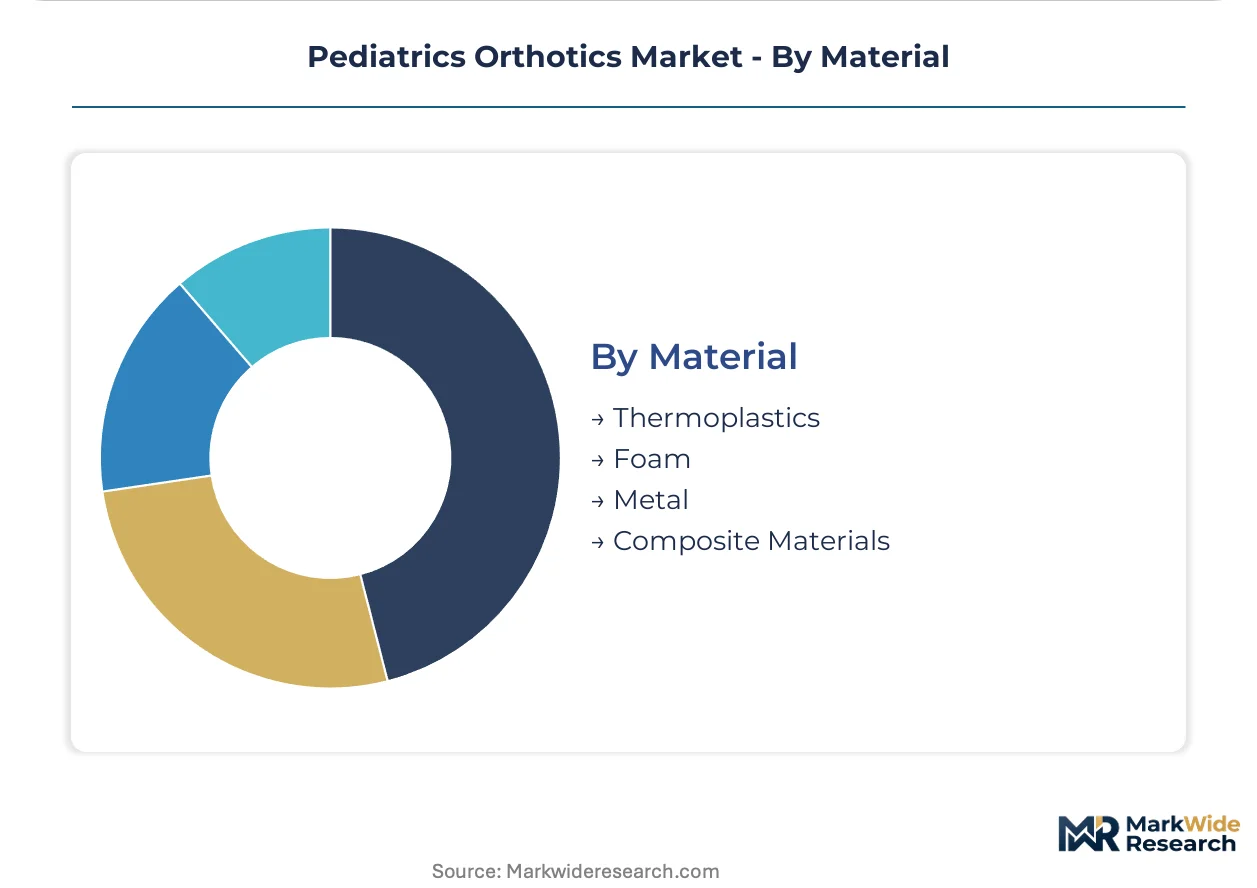
Material:
Fabrication substrate selection trades off reworkability, weight reduction, and structural performance against reimbursement constraints.
- Thermoplastics:Polypropylene and polyethylene formulations enable vacuum-forming over positive molds with 60-80°C activation temperatures. United States high-volume pediatric clinics favor reworkability for rapid growth-related device modifications.
- Composite Materials:Carbon-fiber layups and resin systems achieve 40-60% mass reduction versus thermoplastic equivalents. Muscular dystrophy applications in United States tertiary centers prioritize weight minimization to sustain ambulatory function.
- Foam:Open-cell and viscoelastic formulations provide interface cushioning and pressure redistribution.
- Metal:Aluminum and stainless steel components reinforce structural joints in high-load dynamic systems.
Thermoplastics dominate prescription volume. Composite Materials are climbing the fastest as performance requirements intensify in progressive neuromuscular conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German carbon-composite fabricators export precision-milled orthotic components to United States children's hospitals, establishing a transatlantic supply corridor for high-performance pediatric gait systems.
United States
Medicaid EPSDT programs in Texas and Florida extend orthotic coverage to low-income pediatric populations previously excluded from specialized intervention. FDA Center for Devices and Radiological Health oversees 510(k) clearance pathways for anatomically adaptive designs. Philadelphia's Shriners Hospitals for Children anchors the Northeastern referral network for complex cerebral palsy prescriptions.
Germany
Polymer science expertise concentrated in Lower Saxony drives thermoplastic formulation innovation for vacuum-forming applications. BfArM medical device regulations align with MDR requirements for pediatric-specific biocompatibility standards. Ottobock's headquarters operations in Duderstadt sustain leadership in dynamic ankle-foot system development.
Japan
Aging demographics and declining birth rates compress domestic pediatric volumes while export-oriented fabrication grows. PMDA streamlined review pathways accelerate approval for 3D-printed custom devices. Osaka's medical device manufacturing cluster specializes in lightweight composite materials for muscular dystrophy applications.
United Kingdom
NHS England specialized commissioning frameworks consolidate complex orthotic referrals to designated pediatric centers. MHRA post-Brexit regulatory autonomy maintains alignment with ISO 13485 quality management standards. London's Great Ormond Street Hospital drives prescription volume through integrated gait analysis laboratories.
Australia
TGA medical device regulations govern importation of custom-fitted orthoses from Asian manufacturing partners. National Disability Insurance Scheme funding expansions broaden access to multi-joint systems for progressive neuromuscular conditions. Melbourne's Royal Children's Hospital anchors southeastern prescription networks.
Pediatrics Orthotics Market Competitive Landscape
On the supply side, the industry is tiered between multinational polymer specialists, regional fabrication networks, and emerging digital-native entrants. Consolidation pressures concentrate around carbon-composite lightweighting capabilities and FDA breakthrough device designation attainment. Three archetypes dominate: integrated polymer science conglomerates, certified orthotic clinic chains, and contract manufacturing platforms. Competitive moves center on strategic partnerships with children's hospitals and geographic expansion into Medicaid-expansion states.
Among integrated specialists, Ottobock and Össur exemplify the polymer science conglomerate archetype, while Boston Orthotics & Prosthetics occupies a position within the regional certified-fabricator tier. These anchors represent contrasting strategic positions—multinational material science depth versus concentrated referral network dominance.
| Leading Market Players |
|---|
| Ottobock |
| Össur |
| Hanger Clinic |
| DJO Global |
| Fillauer LLC |
| Boston Orthotics & Prosthetics |
| Becker Orthopedic |
| Breg |
| Allard USA |
| Others |
Value Network & Pricing Analysis
German carbon-composite fabricators in Lower Saxony concentrate high-performance polymer expertise, anchoring margin pools in United States children's hospitals where Medicaid reimbursement rates shape procurement decisions for dynamic gait systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbon-fiber dynamic systems from thermoplastic vacuum-formed devices and prefabricated imports. Price differentiation rests on ISO 13485 certification grade and customization depth, with certified pediatric orthotists commanding premium fitting fees. Cost compression in standard thermoplastic segments is intensifying because resin feedstock volatility squeezes vacuum-forming fabricators serving high-volume Medicaid clinics. Rural pediatric populations exhibit highest price sensitivity, while tertiary children's hospitals prioritize performance metrics over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk for carbon-composite components in dynamic ankle-foot orthoses. Manufacturing concentrates in Germany, the United States, and China, with raw material dependencies spanning polypropylene resin, carbon-fiber prepregs, and medical-grade thermoplastic elastomers. Single-source vulnerability persists for specialized pediatric orthotist certification programs graduating fewer than 200 specialists annually. Distribution runs through children's hospital procurement committees, GPO contracts, and direct-to-clinic fabrication partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as Medicaid EPSDT expansion phases create predictable reimbursement waves, with state-level program rollouts in Texas and Florida driving demand cyclicality.
For Market Incumbents: Harden carbon-composite lightweighting capabilities against emerging digital-native entrants with cloud-native 3D modeling platforms. Deepen backward integration into polymer formulation to offset thermoplastic input volatility. Secure ISO 13485-certified contract manufacturing partnerships to scale without capital-intensive molding infrastructure.
For New Entrants and Emerging Players: Rural United States counties with Medicaid expansion present the most penetrable white-space, where smartphone-integrated photogrammetry eliminates multi-hour travel barriers to tertiary centers. Target home-based 3D scanning subscriptions for stable, low-complexity prescriptions. Pursue sports medicine crossover applications for dynamic ankle-foot designs proven in cerebral palsy gait correction.
For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturing platforms with FDA breakthrough device designation attainment and established children's hospital partnerships. Long-term viability hinges on software companion development for usage monitoring and gait optimization services. Watch for FDA pediatric device consortia pre-submission engagement volumes as inflection indicator for regulatory pathway efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review accelerates time-to-market for novel dynamic orthotic mechanisms in cerebral palsy applications. |
| Hospital System Partnership | Integrated episode-of-care contracts with Shriners Hospitals anchor Northeastern United States referral networks. |
| Software Companion Development | Embedded pressure sensors and smartphone-connected monitoring unbundle traditional dispensing models. |
| Reimbursement Strategy | HCPCS Level II code optimization reduces claim denial risk across prefabricated versus custom-fitted categories. |
| CE Marking Pathway | MDR-aligned biocompatibility standards enable German carbon-composite exports to United States children's hospitals. |
Research Methodology
Desk research of FDA 510(k) filings, ISO 13485 certification databases, and state Medicaid EPSDT program documentation preceded structured interviews with certified pediatric orthotists, children's hospital procurement managers, GPO contracts specialists, and biomedical engineers at tertiary referral centers. Secondary validation drew from CMS Medicare data, hospital procurement databases, and customs records of carbon-fiber component imports. Bottom-up prescription volume modeling and top-down market sizing triangulated across fabrication capacity estimates and reimbursement claim patterns.
Assumptions held Medicaid expansion timelines and FDA pediatric device guidance evolution within observed regulatory patterns, while carbon-composite lightweighting adoption curves and 3D printing penetration rates varied across scenarios. Segmentation modeling spanned product type, application severity, end-user setting, and material substrate dimensions. CAGRs derived from longitudinal gait analysis laboratory referral volumes and orthotist certification program graduation rates. Forecast inputs incorporated genetic diagnostic velocity for neuromuscular conditions and smartphone-integrated photogrammetry adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by polymer science conglomerates or rapid regulatory relaxation for 3D-printed custom devices would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Spine Devices Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market