
 Antibacterial Orthopedic Implant Market | 2026-2036
Antibacterial Orthopedic Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Antibacterial Orthopedic Implant Market Insights
The capital-intensity divergence between large-scale manufacturers and mid-tier specialists is unwinding competitive stability in antibacterial orthopedic implants. Johnson & Johnson leverages integrated supply chains across coating technologies and sterilization logistics. Zimmer Biomet anchors its position through concentrated R&D spending on antimicrobial polymer substrates. Stryker Corporation dominates trauma-focused implant portfolios with scaled manufacturing footprints in North America and Europe.
Antibacterial orthopedic implants integrate metallic or polymeric structures with antimicrobial agents such as silver ions, triclosan, or antibiotic-loaded matrices to inhibit biofilm formation during osseointegration. These devices typically achieve surface roughness parameters between 1-3 micrometers and elution profiles sustained over 72 hours to 28 days depending on coating architecture. Bioactive coatings and silver ion technology lead technology segments, with the former capturing mature margin pools in joint replacement and the latter expanding fastest in trauma surgery applications. Intramedullary nails and plates anchor product-type revenue, while biomaterials represent an emerging category driven by resorbable antibiotic matrices.
FDA 510(k) pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for antimicrobial claims. ISO 23317 standards for implant surface characterization and ASTM F1264 for intramedullary fixation devices establish baseline testing protocols that manufacturers must satisfy before regulatory submission. Stakeholders must monitor evolving EPA antimicrobial pesticide registrations for silver-based coatings and anticipate how FDA breakthrough device designations for infection-resistant implants will reshape competitive entry barriers.
Market Dynamics
Silver ion elution technology is compressing traditional antibiotic-loaded matrices by delivering sustained antimicrobial release without systemic toxicity, forcing coating specialists to recalibrate R&D roadmaps and sterilization protocols.
Growth Catalysts
- EU MDR conformity pathways:Streamlined antimicrobial device classifications in Germany and France accelerate time-to-market for silver-coated trauma implants. Manufacturers leverage notified body harmonization to consolidate multi-country approvals.
- Trauma surgery volumes:Emergency departments in the United States and United Kingdom report elevated open fracture admissions requiring immediate infection prophylaxis. Bioactive coating demand tracks directly to Level I trauma center expansion.
- Surface roughness engineering:Laser-textured titanium substrates between 1-3 micrometers enhance osseointegration while maintaining elution profiles. Orthopedic OEMs integrate this process into captive coating lines.
Market Restraints
- Silver price volatility:Precious metal supply concentration in Latin American mining districts creates input cost unpredictability. Coating manufacturers lack hedging instruments for ionic silver procurement.
- EPA antimicrobial registration:Silver-based coatings face dual jurisdiction between EPA pesticide authority and FDA device oversight. Registration timelines extend 18-24 months beyond standard 510(k) pathways.
- Resorbable polymer limitations:Antibiotic-loaded PLGA matrices exhibit burst release kinetics incompatible with 28-day elution targets. Trauma applications require mechanical stability that degradable scaffolds cannot guarantee.
Strategic Opportunities
- India trauma infrastructure:Government hospital modernization programs in Maharashtra and Tamil Nadu create first-mover positions for silver ion nail systems. Domestic manufacturing incentives reduce import duty exposure.
- Photocatalytic titanium dioxide:UV-activated antimicrobial surfaces converge with existing plasma electrolytic oxidation lines. Joint replacement OEMs pilot this convergence in German research hospitals.
- Direct-to-hospital coating services:Regional sterilization providers add antimicrobial surface treatment to implant refurbishment workflows. This channel bypasses traditional distributor markups in the United Kingdom.
Industry Challenges
- Biocompatibility testing capacity:ISO 23317 surface characterization requires specialized profilometry and cell culture facilities. Contract laboratories in the United States report 6-month queues for cytotoxicity validation.
- Cross-functional talent scarcity:Coating chemists with simultaneous expertise in orthopedic biomechanics and antimicrobial pharmacology command premium compensation. University programs in Germany and Switzerland produce insufficient graduates.
- Legacy sterilization integration:Ethylene oxide and gamma irradiation protocols degrade certain bioactive coatings. Hospitals must validate alternative terminal sterilization methods case-by-case.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibacterial Orthopedic Implant Market |
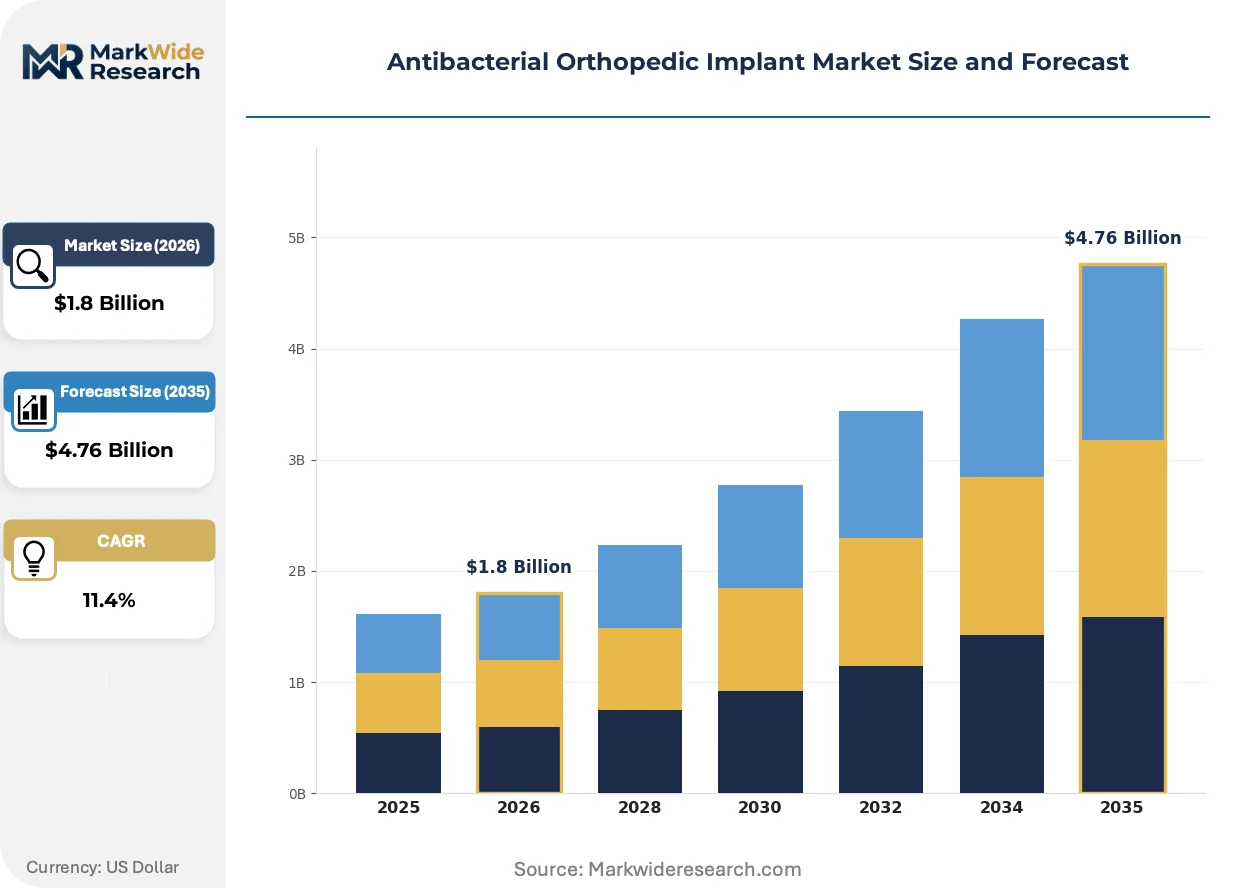
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intramedullary Nails, Plates, Screws, Biomaterials Technology: Bioactive Coatings, Silver Ion Technology, Antimicrobial Polymers, Antibiotic Embedded Implants End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Surgical Centers Application: Trauma Surgery, Joint Replacement, Spinal Surgery, Orthopedic Repair |
| Companies Covered | Johnson & Johnson, Zimmer Biomet, Medtronic, Smith & Nephew, Arthrex, Stryker Corporation, B. Braun, Conmed Corporation, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibacterial Orthopedic Implant Market Trends and Innovations
Antibacterial orthopedic implants are transitioning from passive antibiotic elution toward active surface modulation, with coating architectures now engineered for programmable release kinetics and mechanical property matching.
Photocatalytic titanium dioxide coatings is decomposing conventional silver ion dominance in joint replacement applications by enabling on-demand antimicrobial activation through intraoperative UV exposure. German university hospitals pilot this technology for revision arthroplasty cases. The shift is decomposing margin structures for coating specialists dependent on precious metal supply chains.
EPA antimicrobial pesticide registration overlaps with FDA 510(k) device clearance for silver-based orthopedic coatings, creating dual-track compliance burdens that favor vertically integrated manufacturers with dedicated regulatory affairs teams. Trauma-focused product lines face the steepest documentation requirements. Smaller coating houses in the United States are exiting the orthopedic segment rather than absorbing registration costs.
Hospital procurement committees now mandate infection rate guarantees as contract terms, displacing traditional unit-price negotiations for implant systems. Value analysis teams in the United Kingdom and United States weight 90-day readmission metrics above acquisition cost. This behavioral shift concentrates purchasing authority within integrated delivery networks that can track longitudinal outcomes.
Antibacterial Orthopedic Implant Market Segmentation
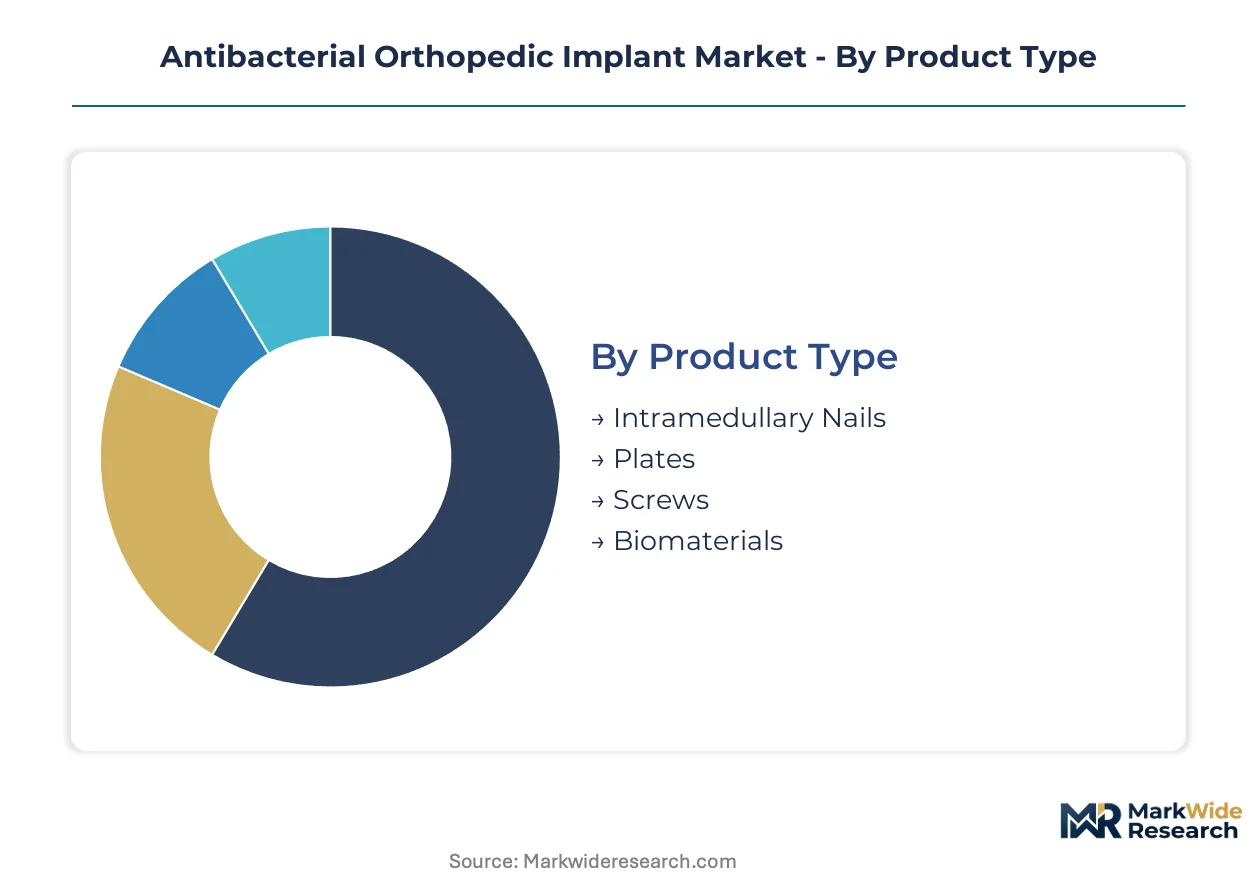
Segmentation in the antibacterial orthopedic implant market reflects divergent regulatory pathways and sterilization requirements across product architectures. Coating technologies face dual EPA-FDA jurisdiction while device geometries determine terminal sterilization compatibility and clinical evidence thresholds.
Product Type:
FDA 510(k) clearance timelines and EU MDR conformity assessments diverge sharply based on intramedullary versus surface-fixation geometries, with notified bodies applying stricter clinical evidence standards to load-bearing devices.
- Intramedullary Nails:Titanium or stainless steel rods with central canals permit antibiotic-loaded cement delivery alongside silver ion surface treatments. German Level I trauma centers and US academic medical centers drive specification for reamed and unreamed variants with elution profiles sustained beyond 72 hours.
- Plates:Compression and locking plate geometries integrate bioactive hydroxyapatite-silver composite coatings at 1-3 micrometer surface roughness. Demand concentrates in United Kingdom NHS trauma networks where infection rate guarantees now anchor procurement decisions.
- Screws:Cortical and cancellous screw thread designs accommodate thin-film antimicrobial deposition through plasma electrolytic oxidation.
- Biomaterials:Resorbable antibiotic matrices and collagen sponges face mechanical stability constraints in load-bearing applications.
Intramedullary nails handle the majority of throughput; biomaterials is expanding most quickly on share.
Technology:
Cost tier stratification separates precious metal-dependent coating chemistries from polymer-based alternatives, with silver price volatility compressing margins for mid-tier specialists lacking hedging instruments.
- Bioactive Coatings:Hydroxyapatite-tricalcium phosphate composites with ionic silver substitution achieve osteoconductivity alongside antimicrobial release. Joint replacement applications in German university hospitals favor this architecture for revision arthroplasty cases.
- Silver Ion Technology:Sustained-release ionic silver from zeolite or sol-gel matrices delivers broad-spectrum activity without systemic toxicity. Trauma surgery applications in United States emergency departments show steepest volume expansion amid open fracture protocol updates.
- Antimicrobial Polymers:Triclosan-integrated PMMA or PEEK substrates face regulatory scrutiny under EPA antimicrobial pesticide registration.
- Antibiotic Embedded Implants:Gentamicin or vancomycin-loaded bone cements and coatings exhibit burst release kinetics challenging 28-day elution targets.
Silver ion technology commands the dominant revenue position; bioactive coatings climb the fastest on volume contribution.
End User:
Customer type determines sterilization infrastructure requirements and outcome tracking capabilities, with integrated delivery networks capturing purchasing authority through longitudinal infection surveillance.
- Hospitals:Academic medical centers and community hospital systems with captive sterilization departments validate alternative terminal methods for bioactive-coated devices. United States and United Kingdom facilities lead procurement committee restructuring around 90-day readmission metrics.
- Orthopedic Clinics:Ambulatory surgery centers with limited sterilization capacity depend on pre-sterilized single-use implant systems.
- Rehabilitation Centers:Post-acute facilities focus on non-surgical infection management with limited implant exposure.
- Surgical Centers:Independent outpatient centers prioritize rapid inventory turnover and distributor-dependent logistics.
Hospitals absorb the dominant procurement volume; orthopedic clinics gain share fastest through ambulatory surgery expansion.
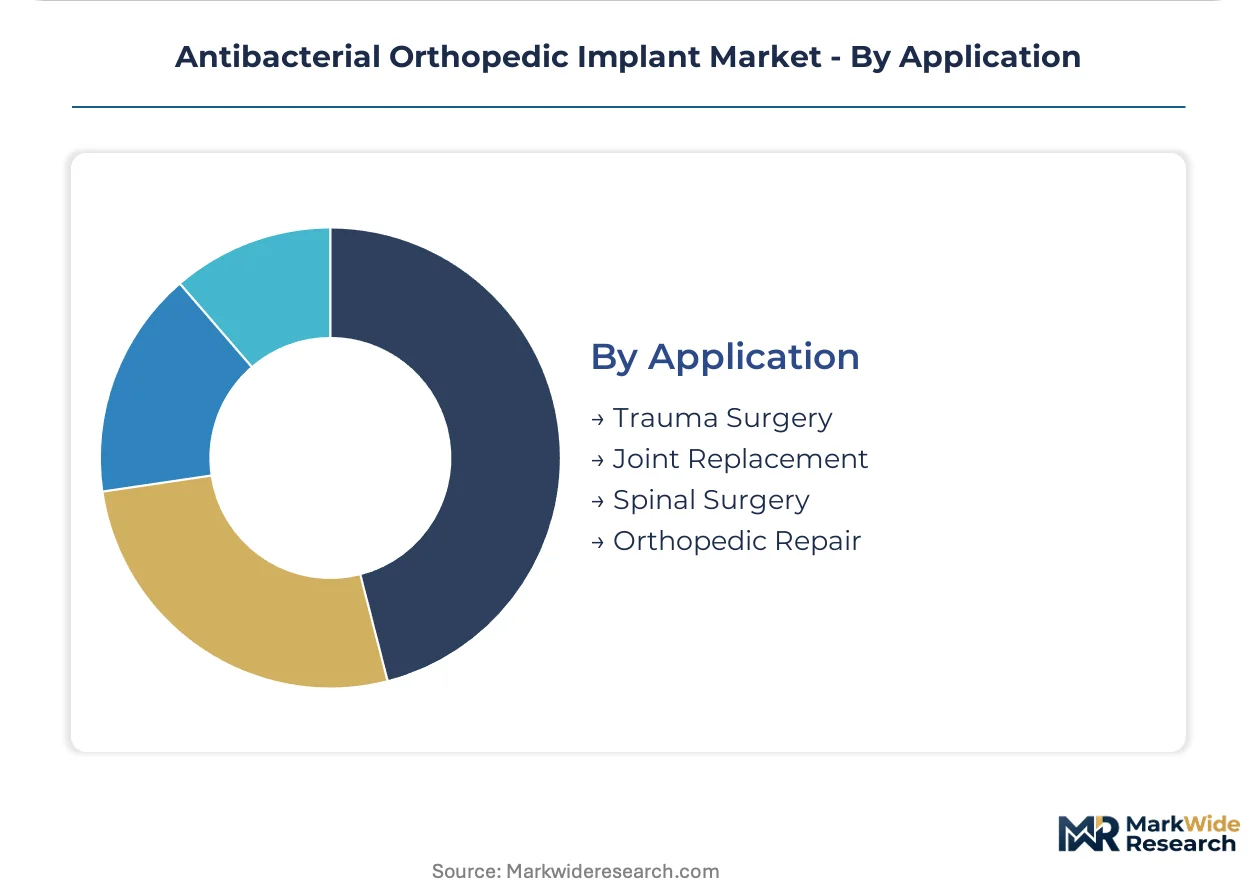
Application:
Volume concentration and margin structure diverge across surgical specialties, with trauma applications demanding immediate infection prophylaxis and joint replacement requiring long-term osseointegration assurance.
- Trauma Surgery:Open fracture fixation and polytrauma stabilization require immediate antimicrobial coverage with mechanical stability. United States emergency department admission volumes and United Kingdom major trauma center expansion anchor demand for silver ion nail and plate systems.
- Joint Replacement:Hip and knee arthroplasty revision cases drive bioactive coating specification for osteoconductive fixation. German research hospitals pilot photocatalytic titanium dioxide activation for infection-resistant revision protocols.
- Spinal Surgery:Pedicle screw and interbody fusion devices face stringent biocompatibility testing under ISO 23317 surface characterization standards.
- Orthopedic Repair:Sports medicine and soft tissue reconstruction applications favor resorbable antibiotic matrices with limited mechanical loading.
Trauma surgery handles the majority of unit volume; joint replacement captures the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in antibacterial orthopedic implants favor established manufacturing clusters in Germany and the United States against emerging production bases in India. Silver ion coating specialists in Switzerland and Austria supply precision components to trauma device assemblers across Western Europe. Chinese manufacturers concentrate on domestic hospital procurement while building coating capacity for Southeast Asian markets.
United States
FDA 510(k) antimicrobial device pathways and EPA silver pesticide registrations create dual compliance thresholds that concentrate production among integrated manufacturers. Level I trauma centers in Baltimore and Houston drive specification for silver ion nail systems with 28-day elution profiles. Johnson & Johnson and Stryker Corporation anchor supply chains through captive coating facilities in Massachusetts and Michigan.
Germany
EU MDR conformity assessments through notified bodies in Tüv Süd and BSI streamline multi-country approvals for trauma implant exporters. Bioactive coating demand tracks to university hospital networks in Munich and Berlin where photocatalytic titanium dioxide pilots proceed. Zimmer Biomet and B. Braun leverage sterilization logistics integration across Baden-Württemberg and North Rhine-Westphalia.
United Kingdom
NHS trauma network procurement mandates infection rate guarantees that displace unit-price contracting for implant systems. Major trauma center expansion in Birmingham and Manchester anchors demand for silver ion plate and screw portfolios. Smith & Nephew distributes through regional sterilization hubs that validate alternative terminal methods for bioactive-coated devices.
India
Government hospital modernization programs in Maharashtra and Tamil Nadu create first-mover positions for domestic silver ion nail manufacturing. CDSCO medical device regulations and PLI scheme incentives reduce import duty exposure for trauma infrastructure investments. Arthrex and regional coating specialists establish technical partnerships with hospital procurement committees in Mumbai and Chennai.
Switzerland
Swissmedic device oversight and precision coating expertise position Basel and Zurich clusters as component suppliers to European trauma OEMs. Silver ion technology specialists serve German and French manufacturers lacking in-house surface treatment capacity. Integra LifeSciences Corporation leverages Swiss research hospital relationships for bioactive coating validation protocols.
Antibacterial Orthopedic Implant Market Competitive Landscape
Concentration sits with diversified orthopedic conglomerates that control captive coating lines and sterilization logistics across multiple regulatory jurisdictions. Mid-tier trauma specialists compete through concentrated R&D spending on antimicrobial polymer substrates while lacking backward integration into precious metal supply chains. Two strategic archetypes dominate: integrated device-coating manufacturers with FDA-EPA dual registration capacity, and regional sterilization providers adding antimicrobial surface treatment to refurbishment workflows. Competitive moves center on M&A absorption of coating specialists and geographic expansion into Indian trauma infrastructure through technical licensing arrangements.
Among diversified orthopedic conglomerates, Johnson & Johnson, Zimmer Biomet, and Stryker Corporation exemplify the integrated archetype through captive supply chain control. Johnson & Johnson represents scale-driven coating technology integration. Zimmer Biomet occupies a position concentrated on antimicrobial substrate development. Stryker Corporation anchors trauma-focused manufacturing footprints across North American and European regulatory environments. These three entities sit within the premium tier where dual EPA-FDA registration capacity creates structural barriers for mid-tier competitors lacking dedicated regulatory affairs teams.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Zimmer Biomet |
| Medtronic |
| Smith & Nephew |
| Arthrex |
| Stryker Corporation |
| B. Braun |
| Conmed Corporation |
| Integra LifeSciences Corporation |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) antimicrobial device pathways and EPA silver pesticide registrations gate both supplier qualification and price differentiation simultaneously, concentrating procurement authority among integrated manufacturers with dedicated regulatory affairs teams while fragmenting pricing power across mid-tier coating specialists lacking dual-track compliance capacity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the antibacterial orthopedic implant market. Price differentiation hinges on FDA breakthrough device designation status and ISO 23317 surface characterization certification tier, with premium tiers capturing integrated sterilization logistics. Cost compression in standard-tier silver ion coatings is intensifying because Latin American precious metal supply concentration limits hedging instruments for mid-tier specialists. Ambulatory surgery centers exhibit highest price sensitivity due to limited sterilization infrastructure, while academic medical centers prioritize infection rate guarantees over unit acquisition cost.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Swiss and German precision coating clusters to North American trauma device assemblers elevate inbound logistics costs for silver ion component supply. Manufacturing concentrates in Germany, the United States, and Switzerland, with coating specialists in Basel and Zurich feeding German trauma OEMs. Raw material dependencies center on ionic silver from Latin American mining districts, titanium substrates from Japanese and Russian smelters, and antibiotic active pharmaceutical ingredients from Indian and Chinese manufacturers. Single-source vulnerability in precious metal ion supply creates structural risk. Distribution runs through integrated delivery networks with captive sterilization departments and regional GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates structural barriers: dual EPA-FDA registration requirements generate switching costs that cement incumbent positions and deter mid-tier competitors lacking dedicated compliance infrastructure.
For Market Incumbents: Secure dual EPA-FDA registration capacity as a defensive perimeter against emerging photocatalytic titanium dioxide substitutes. Deepen backward integration into ionic silver supply through offtake agreements with Latin American mining consortiums. Capacity addition in Indian domestic manufacturing under PLI scheme incentives protects against import duty exposure.
For New Entrants and Emerging Players: Direct-to-hospital coating services represent a service-layer gap where incumbents under-serve regional sterilization providers. Target United Kingdom NHS trauma networks where infection rate guarantee mandates displace traditional distributor markups. Penetrate through technical licensing arrangements with Maharashtra and Tamil Nadu government hospital modernization programs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with orthopedic coating divisions lacking standalone scale. Long-term viability frames around regulatory entrenchment durability and infection surveillance data network effects. Watch EPA antimicrobial pesticide registration timeline compression as inflection indicator for coating specialist consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for infection-resistant implants, creating first-mover advantage in trauma surgery. |
| EU MDR Conformity Pathway | Streamlines multi-country approvals through notified body harmonization in Germany and France. |
| Hospital System Partnership | Integrates infection rate guarantees into procurement contracts, displacing unit-price negotiations in NHS networks. |
| Backward Integration into Silver Supply | Reduces input cost unpredictability from Latin American precious metal concentration. |
| Photocatalytic Coating Development | Enables on-demand antimicrobial activation through intraoperative UV exposure in German research hospitals. |
Research Methodology
Cross-validation between primary interviews with hospital procurement committees, biomedical engineers, and GPO contracts managers and secondary sources including FDA 510(k) filings, EPA antimicrobial pesticide registrations, and hospital procurement databases anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing across coating technology, product geometry, and end-user facility type segments.
Sensitivity analysis frames the analytical approach across the projection horizon. Segmentation dimensions include coating architecture, device geometry, application specialty, and regulatory jurisdiction cluster. CAGRs derive from elution profile adoption curves and trauma surgery volume trajectories. Industry-specific inputs incorporate silver price volatility scenarios and EU MDR notified body capacity constraints.
Underlying assumptions cover sustained EPA-FDA dual jurisdiction continuity and trauma center expansion trajectories in target geographies, with deviation risk concentrated in precious metal supply disruptions and photocatalytic technology substitution velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
GCC Orthopedic Braces and Supports Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Smart Orthopedic Implants Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Europe Knee Cartilage Repair Market