
 Podiatry Laser Market | 2026-2036
Podiatry Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Podiatry Laser Market Analytics
Specialty medical device distribution is rewriting access patterns for podiatric laser systems. Fotona leverages its direct clinical training infrastructure to sustain premium placement across European and North American podiatry networks. Sciton competes through application-specific module design that extends platform utility from aesthetic dermatology into nail surgery procedures. Cynosure anchors its position via established reimbursement relationships that control hospital procurement cycles for capital equipment.
Podiatry lasers are solid-state or gas-based electromagnetic devices emitting coherent light at specific wavelengths—typically 810 nm to 10,600 nm—to achieve photothermal or photochemical tissue interaction in foot and ankle pathology. Diode lasers dominate current installation bases due to compact footprint and favorable operating costs for high-volume fungal nail protocols, while CO2 lasers retain margin concentration in precision nail matrix surgery where controlled ablation depth protects surrounding tissue. Nd:YAG platforms represent the fastest-growing product category as practitioners adopt dual-wavelength systems that combine superficial fungal penetration with deeper soft-tissue pain management capability.
FDA 510(k) premarket notification requirements govern laser classification and clinical indication claims in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking across European podiatry markets. These frameworks shape demand by determining which clinical applications manufacturers may promote and which settings—clinics versus hospitals—qualify for procurement. Stakeholders must monitor evolving reimbursement codes for laser-assisted procedures as payors recalibrate coverage policies between cosmetic and medically necessary indications.
Market Dynamics
FDA 510(k) clearance timelines and EU MDR conformity assessments are compressing product launch windows, forcing manufacturers to front-load clinical validation costs before commercialization. Dual-wavelength platform development now dominates R&D allocation as practices demand consolidated capital equipment.
Growth Catalysts
- Reimbursement code expansion:CMS coverage determinations for laser-assisted nail debridement in the United States are converting cosmetic cash-pay volumes into billable procedures.
- Diode laser efficiency gains:Solid-state cooling systems are reducing per-procedure operating costs below gas-laser baselines, accelerating clinic-level ROI.
- Integrated care models:Podiatry-dermatology joint practices in Germany and the United Kingdom are standardizing multi-wavelength platforms as shared capital assets.
Market Restraints
- Input cost volatility:Yttrium-aluminum-garnet crystal supply concentrates in Chinese processing facilities, exposing Nd:YAG laser manufacturers to export control friction.
- Technical limitation:Single-wavelength systems cannot address concurrent fungal infection and soft-tissue pain, restricting addressable case complexity.
- Regulatory friction:FDA 510(k) substantial equivalence requirements for new wavelength indications extend commercialization timelines by 12-18 months versus predicate devices.
Strategic Opportunities
- Underpenetrated geography:India's tier-2 cities lack dedicated podiatry infrastructure, creating first-mover positioning for portable diode systems under CDSCO oversight.
- Technology convergence:Combination platforms integrating 1064 nm Nd:YAG with 2940 nm Er:YAG wavelengths are capturing nail matrix surgery cases previously referred to hospital ORs.
- Distribution innovation:Direct-to-clinic leasing models bypass traditional medical device distributors, compressing customer acquisition costs in saturated North American markets.
Industry Challenges
- Certification timeline compression:EU MDR technical documentation requirements for Class IIb lasers are extending notified body review cycles, delaying CE marking.
- Talent scarcity:Certified laser safety officers with podiatric clinical training command premium compensation, constraining multi-site practice expansion.
- Capex intensity:Multi-wavelength platforms require $75,000-$150,000 upfront investment, limiting independent practitioner adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Podiatry Laser Market |
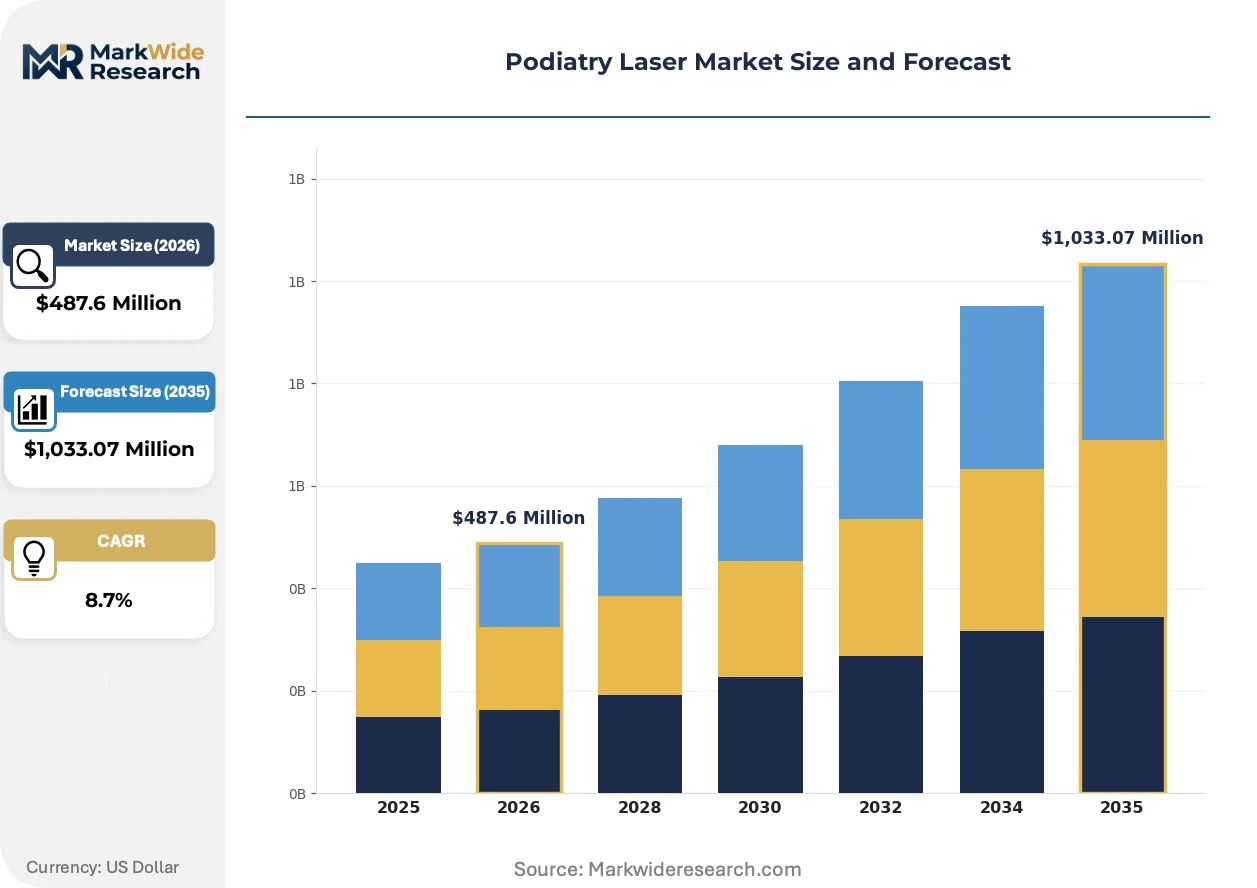
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Nd:YAG Lasers, CO2 Lasers, Erbium Lasers Application: Fungal Nail Treatment, Wound Healing, Pain Management, Nail Surgery End User: Clinics, Hospitals, Podiatry Practices, Dermatology Centers Technology: Low-Level Light Therapy, High-Intensity Laser Therapy, Pulsed Laser Technology, Continuous Wave Technology |
| Companies Covered | Fotona, Sciton, Intros Medical Laser, Theralase Technologies, Cutera, Lumenis, Cynosure, Aerolase, Biolase, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Podiatry Laser Market Evolving Landscape
Photothermal dosing algorithms and real-time tissue feedback systems are transforming treatment precision standards. Manufacturers now compete on software-enabled procedure customization rather than hardware specifications alone.
Er:YAG fractional delivery systems with integrated temperature monitoring are rendering obsolete CO2 lasers for nail matrix ablation. Academic medical centers in the United States are adopting these platforms for resident training programs. The technology is rendering obsolete legacy gas-based systems that lack sub-millimeter depth control.
EU MDR post-market surveillance requirements now mandate systematic clinical follow-up data for laser-assisted podiatric procedures. Manufacturers must establish notified body-approved quality management systems with annual safety reporting. German and French podiatry networks are consolidating procurement around MDR-certified suppliers, excluding legacy CE-marked devices without updated technical files.
Leasing arrangements with bundled maintenance and training are displacing outright equipment purchases in independent practice settings. Distributors in the United States are restructuring compensation around utilization-based fees rather than upfront margins. This shift is most visible in Texas and Florida markets where podiatry group practices exceed 20 sites.
Podiatry Laser Market Segmentation
Podiatry laser procurement patterns diverge sharply across clinical settings and technical specifications. Service intensity, reimbursement pathways, and capital constraints create distinct demand profiles that manufacturers must navigate through targeted platform configurations.
Product Type:
After-sales-service intensity varies dramatically across laser modalities, with gas-based systems demanding quarterly maintenance contracts while solid-state platforms require minimal field intervention.
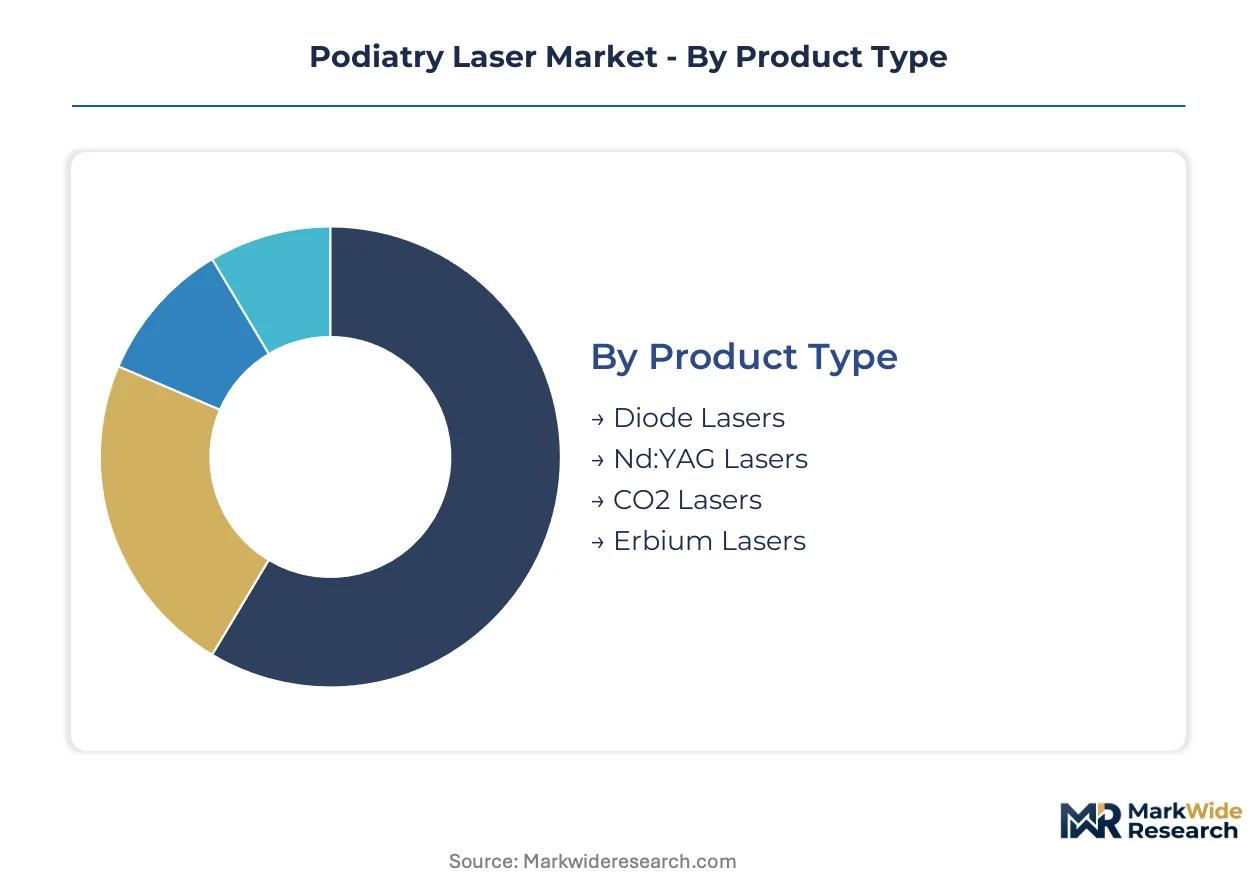
- Diode Lasers:Compact solid-state devices operating at 810-980 nm wavelengths deliver photothermal energy through fiber-optic delivery systems. Demand concentrates in United States independent podiatry practices where high-volume fungal nail protocols justify capital deployment through rapid procedure throughput. Diode systems dominate installation bases due to favorable operating costs and minimal cooling infrastructure requirements.
- Nd:YAG Lasers:Neodymium-doped yttrium-aluminum-garnet platforms emitting at 1064 nm achieve deeper tissue penetration for soft-tissue applications. German and United Kingdom podiatry-dermatology joint practices are standardizing dual-wavelength systems combining Nd:YAG with superficial modalities as shared capital assets.
- CO2 Lasers:Gas-based systems at 10,600 nm provide precise ablation for nail matrix surgery with controlled thermal damage zones.
- Erbium Lasers:Er:YAG platforms at 2940 nm offer water-specific absorption peaks enabling sub-millimeter tissue removal with minimal collateral heating.
Diode lasers hold the largest share; momentum sits with Nd:YAG platforms.
Application:
Procedure reimbursement status determines capital allocation priority across clinical indications, with billable services commanding equipment investment ahead of cosmetic cash-pay segments.
- Fungal Nail Treatment:Photothermal destruction of dermatophyte colonies through selective targeting of melanin-rich fungal structures. United States clinics drive volume as CMS coverage determinations convert cosmetic procedures into reimbursable medical services, expanding addressable patient populations.
- Pain Management:Low-level light therapy modulates inflammatory cascades and neural transmission in chronic foot and ankle conditions. Demand is climbing fastest in sports medicine affiliated podiatry practices seeking non-pharmacological alternatives to opioid protocols.
- Wound Healing:Photobiomodulation accelerates tissue repair through mitochondrial stimulation and angiogenic factor release.
- Nail Surgery:Laser-assisted matrix ablation and ingrown nail correction reduce postoperative morbidity versus conventional cold steel techniques.
Fungal nail treatment commands dominant volume; pain management is expanding most quickly.
End User:
Capital intensity thresholds and procurement autonomy create distinct customer archetypes with diverging platform preferences and financing expectations.
- Podiatry Practices:Independent single-specialty clinics with direct physician ownership and procedure-based revenue models. United States multi-site groups in Texas and Florida markets are consolidating procurement through leasing arrangements with bundled maintenance and training.
- Hospitals:Integrated health systems with centralized capital committees and established vendor relationships. Cynosure anchors position via reimbursement relationships controlling procurement cycles for capital equipment in United States hospital settings.
- Clinics:Ambulatory facilities with mixed specialty staffing and shared equipment utilization.
- Dermatology Centers:Skin-focused practices extending service portfolios into nail pathology through cross-trained providers.
Podiatry practices represent the largest installed base; hospitals show steepest expansion trajectory for multi-wavelength platforms.
Technology:
Energy delivery modalities determine clinical versatility and regulatory classification pathways, with pulsed systems commanding premium positioning for precision applications.
- High-Intensity Laser Therapy:Concentrated energy delivery achieving therapeutic photothermal thresholds for tissue ablation and surgical intervention. Academic medical centers in the United States are adopting these platforms for resident training programs in nail matrix surgery.
- Pulsed Laser Technology:Temporal energy modulation enabling thermal relaxation of target tissue while sparing adjacent structures. Demand concentrates in precision nail surgery applications where controlled ablation depth protects surrounding tissue.
- Low-Level Light Therapy:Sub-thermal photobiomodulation for inflammatory modulation and wound healing acceleration.
- Continuous Wave Technology:Sustained energy output for uniform tissue interaction in high-volume procedural settings.
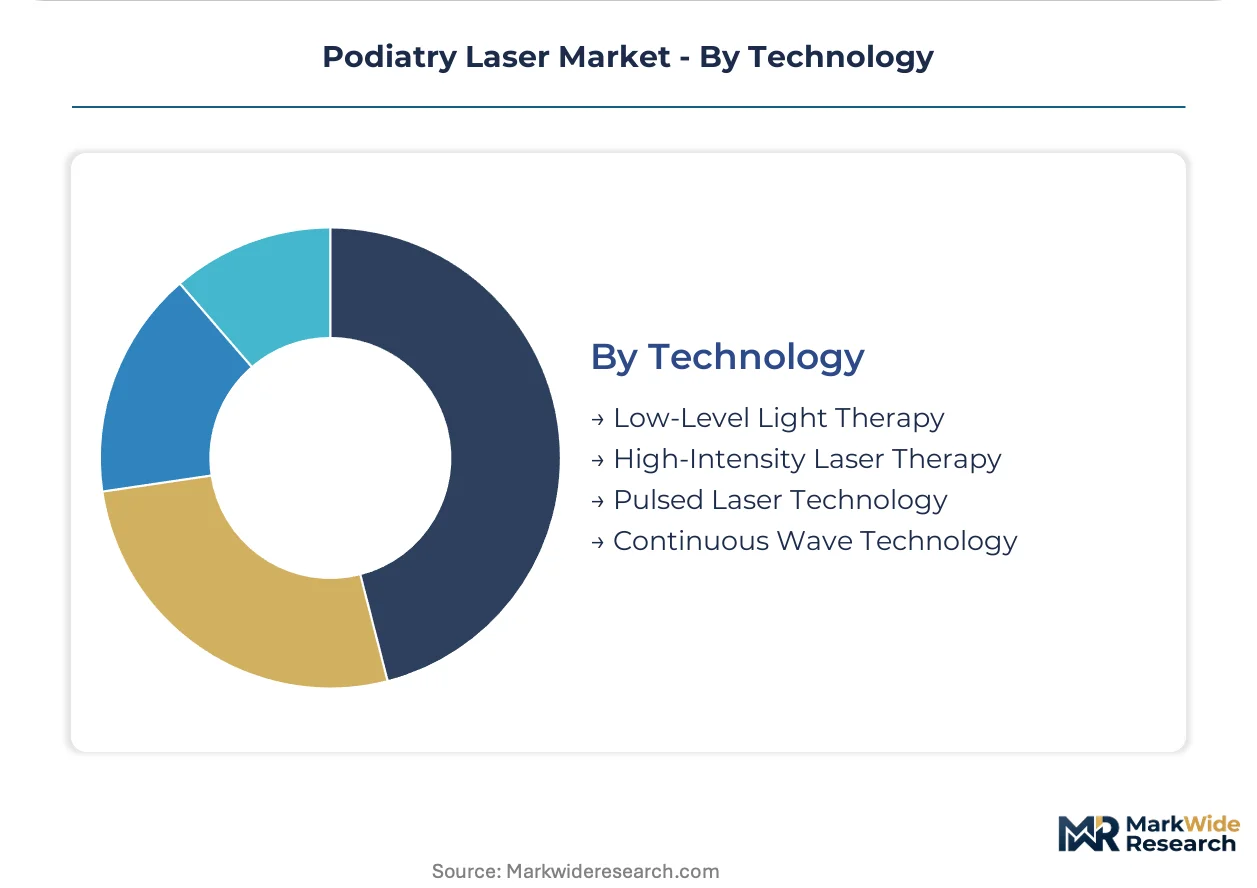
High-intensity laser therapy holds dominant revenue share; pulsed laser technology is gaining share fastest through surgical application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and CMS reimbursement determinations in the United States create the strongest policy tailwinds for podiatry laser deployment. EU MDR conformity assessments and national procurement frameworks in Germany and the United Kingdom shape European adoption trajectories. India's CDSCO oversight and emerging clinic infrastructure in tier-2 cities present expansion opportunities for portable systems.
United States
Integrated podiatry-dermatology service models in Texas and Florida drive capital investment in multi-wavelength platforms. FDA 510(k) substantial equivalence requirements govern wavelength indication claims and commercialization timelines. Houston and Dallas multi-site group practices exceeding 20 locations are consolidating procurement through leasing arrangements with bundled maintenance and training.
Germany
Podiatry-dermatology joint practices standardize multi-wavelength platforms as shared capital assets across clinic networks. EU MDR technical documentation requirements extend notified body review cycles for Class IIb laser certifications. The Rhine-Ruhr metropolitan region concentrates procurement consolidation around MDR-certified suppliers, excluding legacy CE-marked devices without updated technical files.
United Kingdom
Podiatry-dermatology joint practices in England adopt dual-wavelength systems combining Nd:YAG with superficial modalities. NHS procurement frameworks and NICE technology appraisals influence hospital capital committee decisions for multi-wavelength platforms. Greater London academic medical centers are adopting Er:YAG fractional delivery systems with integrated temperature monitoring for resident training programs.
India
Tier-2 cities lack dedicated podiatry infrastructure, creating first-mover positioning for portable diode systems. CDSCO medical device rules govern import licensing and clinical trial requirements for laser platforms. Maharashtra and Karnataka metropolitan clusters are witnessing initial clinic-level adoption of compact solid-state devices for fungal nail protocols.
Japan
Sports medicine affiliated podiatry practices seek non-pharmacological alternatives to opioid protocols for chronic foot conditions. PMDA premarket approval requirements and reimbursement listing processes shape commercialization timelines for laser-assisted procedures. The Kanto region around Tokyo concentrates specialist clinic density and academic medical center adoption of photobiomodulation platforms.
Podiatry Laser Market Competitive Landscape
On the supply side, the industry is moderately consolidated around established aesthetic laser manufacturers extending platforms into podiatric applications. Three strategic archetypes dominate: diversified aesthetic device conglomerates with podiatry module extensions, specialty laser fabricators with dedicated foot-and-ankle platforms, and emerging portable system specialists targeting cost-sensitive clinic segments. Competitive moves concentrate on dual-wavelength platform development and direct-to-clinic leasing model deployment.
Among diversified aesthetic device manufacturers, Fotona, Sciton, and Cynosure exemplify the premium-tier positioning archetype. Fotona represents the direct clinical training infrastructure model sustaining premium placement across European and North American networks. Sciton occupies a position defined by application-specific module design extending platform utility across specialty boundaries. Cynosure anchors the reimbursement relationship archetype controlling hospital procurement cycles through established payor connections.
| Leading Market Players |
|---|
| Fotona |
| Sciton |
| Intros Medical Laser |
| Theralase Technologies |
| Cutera |
| Lumenis |
| Cynosure |
| Aerolase |
| Biolase |
| Others |
Value Network & Pricing Analysis
Yttrium-aluminum-garnet crystal supply concentration in Chinese processing facilities exposes Nd:YAG laser manufacturers to export control friction that simultaneously widens pricing spreads between certified and uncertified tiers and forces supply chain restructuring toward dual-source qualification programs.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared platforms and economy-tier devices lacking notified body approval. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and warranty duration rather than hardware differentiation alone. Cost compression in the economy tier is intensifying because portable diode manufacturers from India are challenging legacy gas-laser incumbents on acquisition cost. Independent podiatry practices in Texas and Florida exhibit highest price sensitivity, while hospital procurement committees prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Export control regimes limiting rare-earth element flows constrain yttrium crystal availability for solid-state laser fabrication. Manufacturing concentrates in China, Germany, and the United States, with Chinese facilities dominating YAG substrate growth and German precision optics houses controlling beam delivery assembly. Supply chain risk centers on single-source dependency for Nd:YAG rods, which draws from three qualified vendors subject to national security screening. Distribution runs through specialty medical device distributors with clinical training capabilities, though direct-to-clinic leasing models are displacing traditional channel structures in saturated North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The podiatry laser market sits in a post-pandemic capital expenditure recovery cycle, with deferred clinic equipment upgrades now releasing pent-up demand as CMS reimbursement determinations improve procedure economics.
For Market Incumbents: Harden platform differentiation through dual-wavelength integration that combines superficial fungal protocols with deep-tissue pain management, neutralizing substitute threats from single-application devices. Secure backward integration into YAG crystal supply through offtake agreements with Chinese processors, insulating margin position from export control volatility. Prioritize MDR technical file updates to maintain CE marking access as German and French networks consolidate procurement around certified suppliers.
For New Entrants and Emerging Players: Pursue portable diode system deployment in India's tier-2 cities, where CDSCO oversight creates first-mover positioning before established brands establish distribution. Target sports medicine affiliated podiatry practices seeking non-pharmacological pain alternatives, as this application segment expands faster than fungal nail treatment saturation. Deploy direct-to-clinic leasing with bundled training to bypass distributor gatekeepers and compress customer acquisition costs.
For Investors and Strategic Acquirers: The market sits at an early consolidation phase that targets dual-wavelength platform specialists with established reimbursement relationships. Long-term viability over the next decade hinges on software-enabled procedure customization capabilities rather than hardware specifications alone. Acquisition candidates should demonstrate installed base expansion in podiatry-dermatology joint practices. The signal to monitor is EU MDR notified body queue length, as extended review cycles will determine which mid-tier manufacturers survive certification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Wavelength Platform Development | Consolidates fungal and pain protocols into single capital asset, reducing clinic equipment footprint. |
| Direct-to-Clinic Leasing Model | Bypasses distributor margins in Texas and Florida multi-site group practices exceeding twenty locations. |
| FDA 510(k) Clearance Pathway | Unlocks CMS reimbursement codes that convert cosmetic cash-pay volumes into billable procedures. |
| MDR Technical File Update | Maintains CE marking access as German Rhine-Ruhr networks exclude legacy devices without conformity. |
| Software Companion Development | Photothermal dosing algorithms differentiate platforms beyond hardware specifications in academic medical centers. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR notified body conformity assessments, and CMS coverage determinations preceded structured interviews with podiatry clinic owners, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, GPO equipment contracts, and CDSCO import licensing records. Bottom-up installation base modeling triangulated against top-down capital expenditure forecasts across the analysis window.
Assumptions held reimbursement code expansion trajectories and regulatory clearance timelines at base-case parameters while varying YAG crystal supply availability and EU MDR review cycle duration. Segmentation dimensions modeled include laser modality, clinical application, end-user setting, and technology delivery mechanism. CAGRs derived from procedure volume elasticity to reimbursement status and capital equipment replacement cycles. Industry-specific inputs incorporated fungal nail treatment protocol adoption rates and sports medicine affiliation density.
Macroeconomic conditions sit as an overlay; deviation in clinic capital expenditure budgets or medical device import tariff schedules would shift the trajectory. Forecasts reflect assumptions about sustained CMS coverage for laser-assisted procedures and stable rare-earth element trade flows. Material shifts in FDA substantial equivalence requirements or EU MDR Class IIb laser classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Spine Devices Market