
 Kimchi Market | 2026-2036
Kimchi Market Size, Share, and Industry Trends Forecast 2026-2036
Kimchi Market Analysis
South Korea is fragmenting as new artisanal producers and regional cooperatives challenge the dominance of legacy manufacturers. CJ CheilJedang anchors domestic volume through integrated fermentation facilities and controlled cold-chain distribution. Daesang Corporation competes on ingredient sourcing, leveraging its captive supply of domestic napa cabbage and gochugaru pepper flakes. Pulmuone differentiates through premium positioning in overseas Asian markets.
Kimchi denotes a lacto-fermented vegetable preparation, traditionally comprising napa cabbage and radish seasoned with chili, garlic, and salted seafood, achieving pH below 4.6 through controlled anaerobic fermentation. The product functions as a probiotic-rich condiment, side dish, and cooking ingredient across commercial and consumer food systems. Traditional kimchi and packaged kimchi together occupy the core revenue pool, while vegan kimchi records the fastest trajectory as plant-based dietary frameworks displace fish-sauce formulations in Western markets. Application through food service channels captures margin concentration, whereas retail distribution sustains volume scale through supermarket and online retail penetration.
South Korea's Ministry of Food and Drug Safety and the United States FDA jointly govern export market access through HACCP alignment and acidified food registration requirements. The Codex Alimentarius fermented food standards further condition cross-border trade specifications for pH, salinity, and microbial thresholds. Stakeholders must monitor regulatory divergence between fermentation-permissive Asian frameworks and the stricter additive-labeling regimes emerging in European import jurisdictions.
Market Dynamics
Fermentation safety certification requirements from South Korea's MFDS and the US FDA are fragmenting production capacity between export-qualified facilities and domestic-only operators, creating a bifurcated supply structure.
Growth Catalysts
- Plant-based dietary frameworks:Vegan formulations are displacing fish-sauce-based recipes in Western retail channels, opening new consumer segments previously excluded by dietary restrictions.
- HACCP-aligned cold-chain infrastructure:Restaurant chains and institutional food service operators in North America are expanding refrigerated distribution networks that accommodate live-culture products.
- Probiotic functional positioning:Health-conscious urban consumers in the United States are driving velocity through gut-health marketing claims validated by microbiome research.
Market Restraints
- Napa cabbage supply volatility:Climate-dependent harvests in South Korea's primary growing regions create input cost instability for volume producers.
- Export certification concentration:MFDS-registered fermentation facilities cluster in specific Korean provinces, creating geographic single-point vulnerabilities.
- Acidified food registration friction:US FDA requirements for pH documentation and process filing create 12-18 month market entry timelines for new exporters.
Strategic Opportunities
- European plant-based import channels:Stricter additive-labeling regimes in EU jurisdictions favor clean-label vegan formulations with simplified ingredient decks.
- E-commerce direct-to-consumer fermentation:Subscription models for live-culture products bypass traditional retail slotting constraints and preserve probiotic viability through controlled logistics.
- Dual carbon goals convergence:China's SAMR sustainability frameworks and low-carbon fermentation energy standards create preferential procurement pathways for carbon-efficient producers.
Industry Challenges
- Master fermenter talent scarcity:Traditional jeongol expertise required for consistent pH control and microbial management faces generational transfer gaps.
- Legacy ERP integration complexity:Batch-level traceability requirements for Codex Alimentarius compliance force reconfiguration of existing inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kimchi Market |
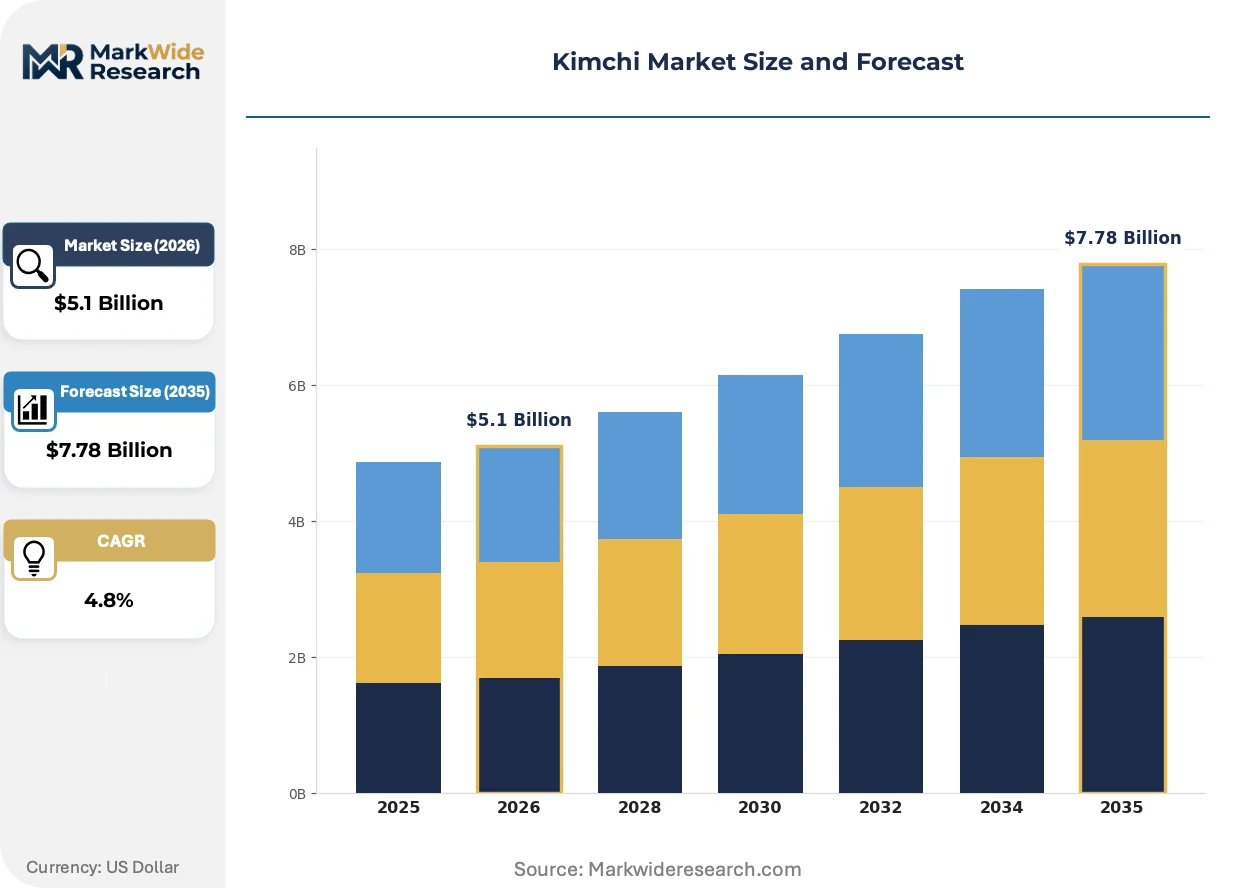
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $7.78 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Kimchi, Vegan Kimchi, Organic Kimchi, Packaged Kimchi Application: Food Service, Retail, Home Cooking, Snacks Packaging Type: Glass Jars, Plastic Containers, Vacuum Sealed Bags, Tubs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | Dongwon Industries, Lucky Foods, Daesang Corporation, Choi's Kimchi LLC, Cosmos Food Co., Inc., CJ CheilJedang, Hansung Food Co., Ltd, Nongshim Co., Ltd., Pulmuone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kimchi Market Emerging Trajectories
Controlled-atmosphere packaging and digital fermentation monitoring are compressing quality variance between artisanal and industrial production, eroding traditional differentiation mechanisms.
Smart fermentation sensors are virtualizing the role of experienced jeongol masters by automating pH, temperature, and microbial load monitoring in real-time. Mid-scale producers in South Korea and the United States are adopting these systems fastest, reducing batch failure rates and enabling consistent export-grade output without decades of accumulated expertise. This virtualization is compressing the premium that artisanal producers previously commanded for consistency guarantees.
REACH-aligned chemical safety documentation requirements in Europe are forcing reformulation of traditional seasoning blends containing salted seafood derivatives. Manufacturers must now submit full constituent disclosures for gochugaru and jeotgal components, adding compliance overhead that favors larger producers with dedicated regulatory affairs capacity. Premium vegan kimchi lines targeting German and French retail channels are responding fastest by eliminating marine-derived ingredients entirely.
Direct sourcing relationships between restaurant groups and certified fermentation facilities are displacing traditional distributor intermediaries in North American food service. Large multi-unit operators in Los Angeles, New York, and Toronto are negotiating volume contracts with specific MFDS-registered Korean producers, capturing margin and securing supply priority. This channel consolidation is most visible in Korean-American population centers where menu authenticity commands pricing power.
Kimchi Market Segmentation
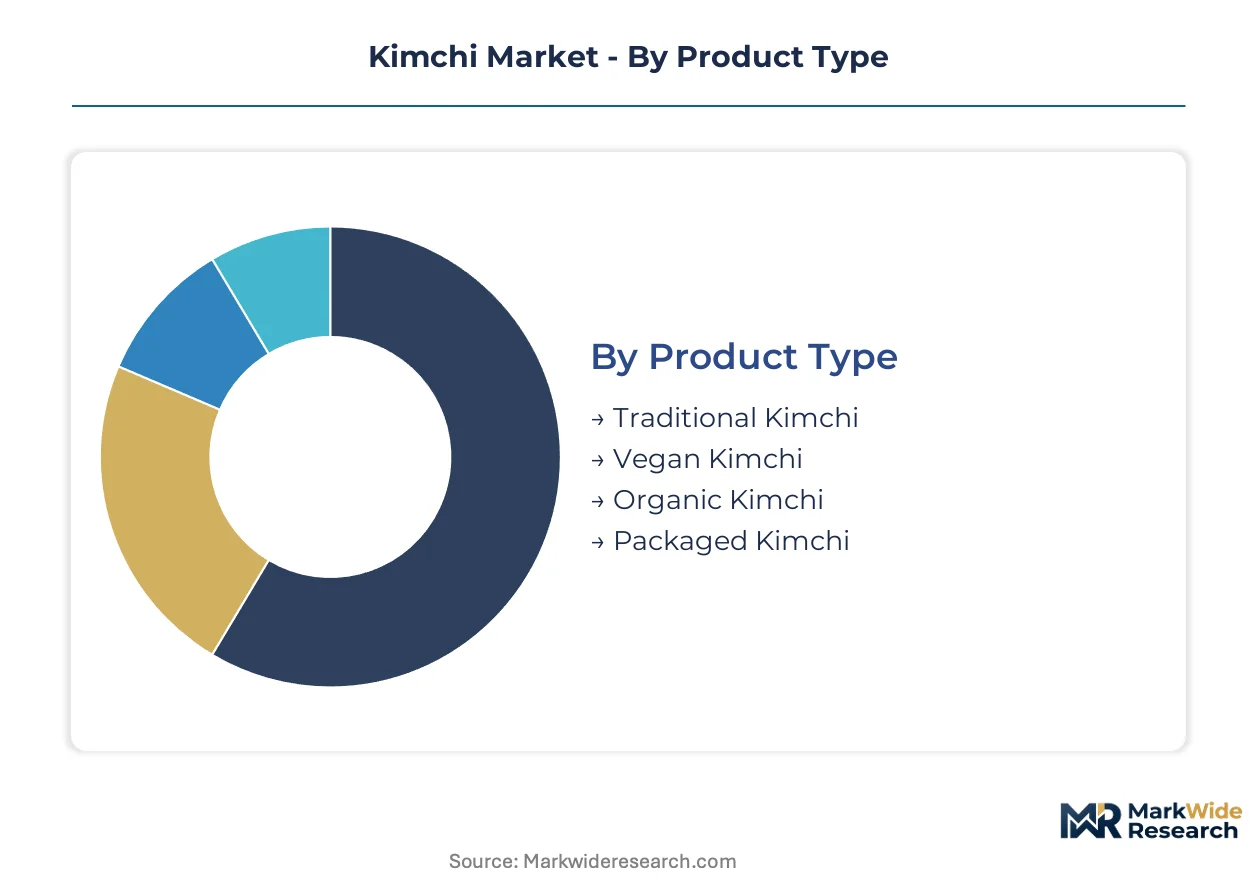
Kimchi producers navigate four distinct segmentation axes that determine pricing power, shelf placement, and margin capture. Product formulation and packaging format drive production economics, while application channel and distribution pathway shape customer acquisition costs and brand positioning.
Product Type:
Cycle times vary sharply across formulations, with packaged variants turning inventory fastest through standardized production runs while artisanal traditional batches require extended fermentation holds.
- Traditional Kimchi:Lacto-fermented napa cabbage and radish prepared with gochugaru, garlic, and salted seafood achieves pH below 4.6 through controlled anaerobic fermentation. Korean-American population centers in Los Angeles and New York sustain demand through restaurant supply contracts and ethnic retail channels where authenticity commands premium positioning.
- Vegan Kimchi:Plant-based formulations eliminate fish sauce and jeotgal, substituting kelp, miso, or mushroom-derived umami compounds. Health-conscious urban consumers in the United States drive velocity through gut-health marketing and allergen-free claims, with German and French retail channels expanding fastest under REACH-aligned clean-label requirements.
- Organic Kimchi:Certified organic napa cabbage and gochugaru sourced without synthetic pesticides or fertilizers.
- Packaged Kimchi:Mass-produced variants with standardized fermentation protocols for extended shelf stability and broad retail distribution.
Traditional kimchi anchors the volume base while vegan kimchi gains share at the steepest rate.
Application:
Margin concentration clusters in food service channels where contract volumes and direct procurement displace distributor markups, while retail sustains scale through supermarket and online penetration.
- Food Service:Restaurant chains and institutional operators in the United States negotiate direct contracts with MFDS-registered Korean producers, capturing supply priority and menu authenticity premiums in Korean-American population centers.
- Retail:Supermarket and online channels sustain mass-market volume through refrigerated distribution networks accommodating live-culture products.
- Home Cooking:Ingredient-format kimchi sold for consumer preparation and recipe integration.
- Snacks:Ready-to-eat kimchi-based products including chips, crackers, and dried formulations.
Food service channels capture margin concentration while retail distribution sustains volume scale.
Packaging Type:
Cost tiers stratify by material and barrier properties, with glass commanding premium positioning and vacuum formats enabling extended distribution reach.
- Glass Jars:Inert barrier properties preserve flavor integrity and support premium positioning in specialty retail channels.
- Plastic Containers:Lightweight, shatter-resistant formats dominate mass-market retail through cost efficiency and logistics optimization.
- Vacuum Sealed Bags:Oxygen exclusion extends probiotic viability and shelf life for e-commerce direct-to-consumer subscription models.
- Tubs:Bulk formats target food service and institutional procurement with volume pricing and simplified handling.
Plastic containers dominate volume throughput while vacuum sealed bags expand fastest in e-commerce channels.
Distribution Channel:
Customer acquisition economics diverge by channel maturity, with established supermarket networks offering scale and emerging online platforms enabling direct brand relationships.
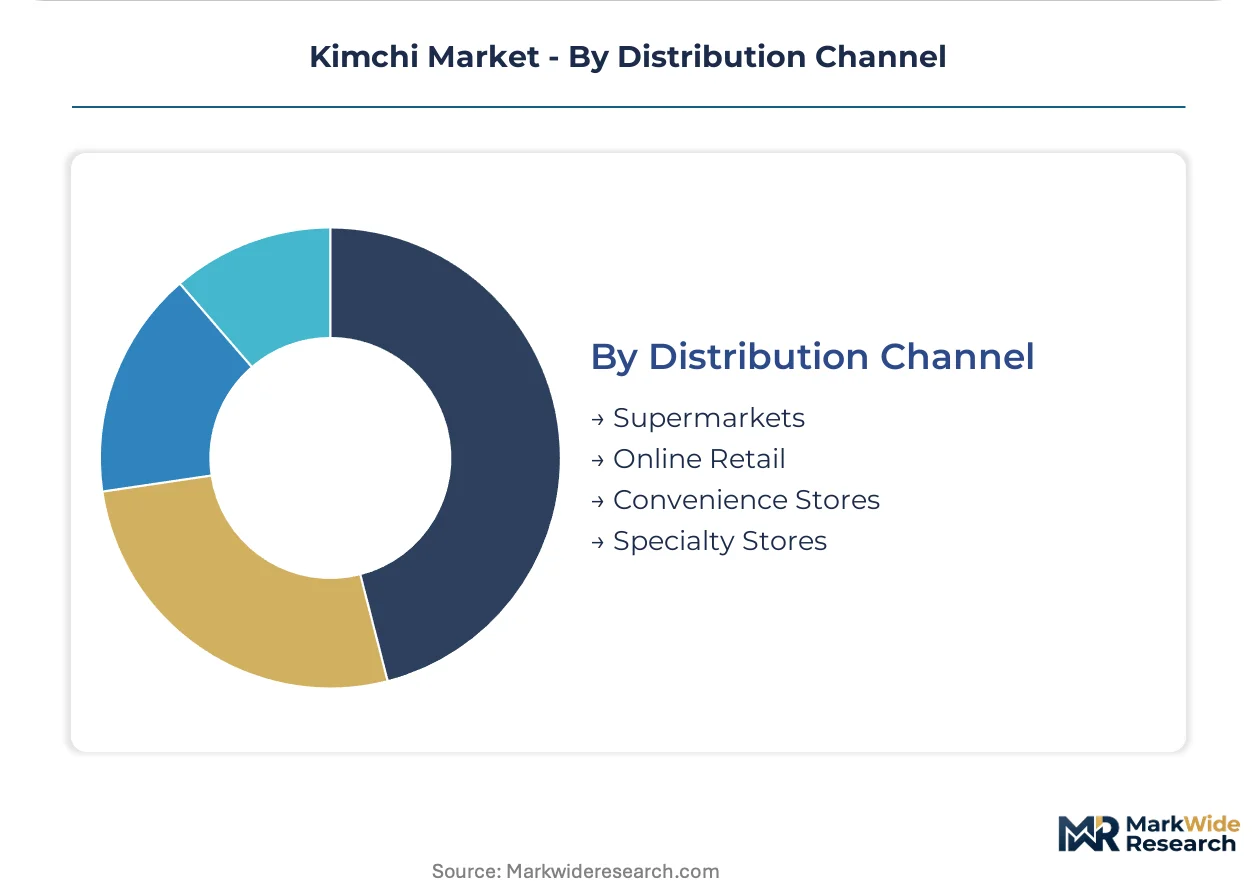
- Supermarkets:Refrigerated retail placement in Korean-American population centers and health-focused urban markets drives baseline velocity through established cold-chain infrastructure.
- Online Retail:Subscription models for live-culture products bypass traditional slotting constraints and preserve probiotic viability through controlled logistics networks.
- Convenience Stores:Impulse-oriented placement targets grab-and-go consumption with smaller format packaging.
- Specialty Stores:Ethnic grocers and natural food retailers curate premium and artisanal variants for authenticity-seeking consumers.
Supermarkets anchor the volume base while online retail climbs the fastest as direct-to-consumer fermentation models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS-registered fermentation facilities anchor South Korea's export dominance, with certification requirements fragmenting production capacity between export-qualified and domestic-only operators across the kimchi supply chain.
United States
Korean-American population centers in Los Angeles and New York drive food service demand through direct procurement contracts with MFDS-registered Korean producers. The FDA enforces acidified food registration requirements that create 12-18 month market entry timelines for new exporters. Cold-chain infrastructure expansion in urban corridors enables live-culture retail distribution.
South Korea
Domestic consumption sustains volume base while napa cabbage supply volatility from climate-dependent harvests creates input cost instability. The Ministry of Food and Drug Safety enforces strict fermentation safety standards that shape export certification requirements. Production clusters in Gyeonggi and South Chungcheong provinces concentrate export-qualified capacity.
Germany
REACH-aligned chemical safety documentation requirements force reformulation of traditional seasoning blends containing salted seafood derivatives. Health-conscious urban consumers in Berlin and Munich drive velocity through gut-health marketing claims. Clean-label vegan formulations expand fastest through specialty retail channels.
Japan
Established fermented food culture sustains baseline demand for probiotic-positioned products. METI frameworks condition import specifications for pH and microbial thresholds. Tokyo-Osaka corridor concentrates retail distribution through refrigerated supermarket networks.
China
SAMR sustainability frameworks and low-carbon fermentation energy standards create preferential procurement pathways for carbon-efficient producers. Yangtze River Delta industrial zones host emerging domestic production capacity. E-commerce platforms enable direct-to-consumer subscription models bypassing traditional retail constraints.
Kimchi Market Vendor Landscape
Integrated conglomerates and specialized fermentation houses split the market between volume scale and artisanal authenticity positioning. Consolidation pressures concentrate around export certification access, with MFDS-registered facilities commanding supply priority. Three archetypes dominate: legacy chaebol with captive agricultural supply, mid-scale regional cooperatives leveraging traditional jeongol expertise, and Western-market specialists reformulating for plant-based dietary frameworks. Competitive moves center on backward integration into napa cabbage cultivation and direct procurement relationships with North American restaurant chains.
Within the integrated conglomerate tier, CJ CheilJedang and Daesang Corporation exemplify scale-driven positioning through controlled cold-chain distribution and captive supply of domestic inputs. Pulmuone occupies a distinct premium-export niche targeting overseas Asian markets with authentication-focused branding. These three anchors represent divergent strategic responses to bifurcating demand between authenticity-seeking ethnic channels and health-positioned Western retail.
| Leading Market Players |
|---|
| Dongwon Industries |
| Lucky Foods |
| Daesang Corporation |
| Choi's Kimchi LLC |
| Cosmos Food Co., Inc. |
| CJ CheilJedang |
| Hansung Food Co., Ltd |
| Nongshim Co., Ltd. |
| Pulmuone |
| Others |
Supply Flow & Price Mechanics
Gyeonggi and South Chungcheong provinces concentrate MFDS-registered fermentation facilities, anchoring export-grade capacity and concentrating margin capture with certified producers who command supply priority from North American restaurant chains.
Pricing Analysis
Price spreads between South Korean export-grade kimchi and domestic-only production run wide, with certification tier and cold-chain integrity as primary differentiation drivers. Three-tier pricing structure across premium artisanal, certified export-grade, and mass-market packaged levels separates MFDS-registered facilities from regional cooperatives. Cost compression in mass-market tiers is intensifying because plastic packaging and shorter fermentation cycles erode traditional quality premiums. Food service buyers in Los Angeles and New York show lowest price sensitivity, prioritizing authentication and supply security over unit economics.
Supply Chain Analysis
Tariff exposure between South Korea and the United States dominates supply chain risk calculus for export-oriented producers. Production gravity centers on South Korea, with emerging capacity in China's Yangtze River Delta and experimental facilities in California's Central Valley. Raw material dependencies rest on domestic napa cabbage cultivation, gochugaru pepper flake processing, and jeotgal fermentation for traditional formulations. Single-source vulnerability concentrates in climate-dependent harvest cycles. Distribution runs through refrigerated logistics networks serving Korean-American population centers and health-focused urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated North American restaurant chains and institutional operators, as direct procurement contracts displace traditional distributor intermediaries and fragment legacy supplier relationships.
For Market Incumbents: Entrench export certification advantage by expanding MFDS-registered capacity in Gyeonggi province before regional cooperatives achieve compliance scale. Secure backward integration into napa cabbage cultivation to buffer climate-driven input volatility. Lock multi-year direct procurement contracts with Los Angeles and Toronto restaurant groups to preempt emerging domestic US fermentation facilities.
For New Entrants and Emerging Players: Build out plant-based vegan formulation capacity targeting German and French retail channels where REACH-aligned clean-label requirements favor simplified ingredient decks. Penetrate e-commerce subscription models for live-culture products, bypassing supermarket slotting fees and preserving probiotic viability through controlled last-mile logistics. Lead with gut-health marketing validated by microbiome research to differentiate from established Korean heritage brands.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale regional cooperatives possessing traditional jeongol expertise but lacking export certification infrastructure. Long-term viability favors producers bridging artisanal authenticity with automated fermentation monitoring systems. Watch for inflection when smart sensor adoption rates cross threshold enabling consistent export-grade output without generational expertise transfer.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Investment | Unlocks North American food service contracts with 12-18 month FDA alignment timelines. |
| Backward Integration into Napa Cabbage | Captures supply security against climate-driven harvest volatility in South Korean growing regions. |
| Vegan Formulation Development | Opens German and French retail channels under REACH-aligned chemical disclosure requirements. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting constraints while preserving live-culture viability through controlled logistics. |
| Smart Fermentation Sensor Deployment | Virtualizes jeongol expertise to compress quality variance between artisanal and industrial production. |
Methodological Framework
Initial hypotheses were tested against primary input from fermentation facility operators, restaurant procurement directors, cold-chain logistics coordinators, and regulatory affairs specialists at export certification bodies, then refined against MFDS registration databases, US FDA acidified food filings, customs trade records, and refrigerated distribution network maps. Bottom-up volume estimates from facility-level production capacity were triangulated with top-down demand segmentation across food service, retail, and direct-to-consumer channels.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product formulation, packaging format, application channel, and geographic regulatory cluster. CAGRs were derived from trajectory fitting to historical velocity patterns and projected penetration rates. Forecast inputs incorporated napa cabbage harvest yield variability, MFDS certification queue lengths, and cold-chain infrastructure expansion timelines in target urban corridors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by California-based fermentation startups or accelerated smart sensor adoption by regional Korean cooperatives would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market