
 Dumplings Market | 2026-2036
Dumplings Market Size, Share, and Industry Trends Forecast 2026-2036
Dumplings Market Analysis
Automated dough-sheeting and filling-deposition technology is tilting production economics toward high-volume frozen output. Ajinomoto Co. Inc. leverages its integrated seasoning and frozen food divisions to control flavor consistency across regional production hubs. CJ CheilJedang Corporation anchors its dumpling portfolio on proprietary cold-chain logistics that sustain texture quality through extended distribution cycles. Sanquan Food Co. Ltd. dominates China's frozen dumpling aisle through manufacturing scale that spans twelve dedicated production facilities.
Dumplings consist of thin wheat-based or starch-based wrappers encasing seasoned fillings, formed through sheeting, depositing, and sealing processes that determine cooking performance and shelf stability; the product serves as a protein-delivery vehicle in both retail convenience meals and food service operations. Frozen dumplings occupy the largest value pool given capital-intensive production barriers and extended retail shelf life, while fresh dumplings command premium positioning in urban markets where consumers prioritize wrapper texture. The food service end user segment generates the fastest volume growth as restaurant operators outsource labor-intensive preparation to centralized suppliers.
China's SAMR enforces GB standards for frozen prepared foods that mandate additive disclosure and microbial limits, while the FDA and USDA regulate import dumplings entering US retail through hazard analysis and pathogen screening protocols. The EU's EFSA and national food safety agencies apply stringent labeling and allergen rules that shape formulation choices for European-bound exports. Stakeholders must monitor how divergent cold-chain integrity requirements across these jurisdictions influence plant certification costs and market access timelines.
Market Dynamics
Automated filling-deposition systems are compressing unit economics for frozen dumpling manufacturers, enabling centralized production to displace kitchen-level preparation across food service chains and retail private-label programs.
Growth Catalysts
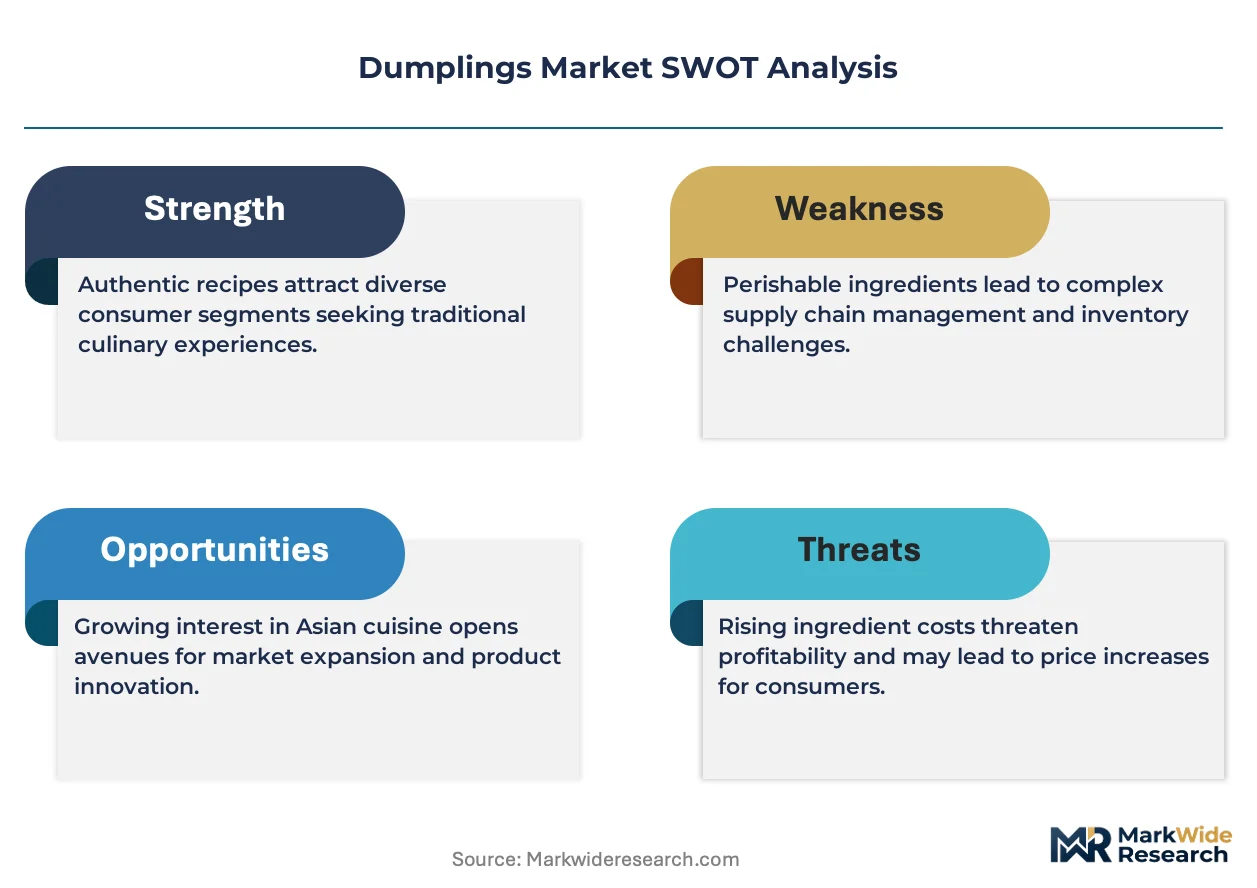
- GB Standards Modernization:China's SAMR is tightening microbial limits and additive disclosure rules for frozen prepared foods, accelerating manufacturer investment in automated traceability systems that reduce recall risk and unlock export certification.
- Food Service Labor Arbitrage:Centralized frozen-to-steam formats cut back-of-house labor hours by eliminating wrapper preparation and filling operations, driving volume commitments from quick-service and casual-dining operators.
- Cold-Chain Infrastructure Expansion:Refrigerated logistics networks across Southeast Asia and Latin America are extending distribution reach for texture-stable frozen products previously confined to mature markets.
Market Restraints
- Wheat Flour Price Volatility:Wrapper production depends on wheat futures exposed to Black Sea supply disruptions and climate yield variability, compressing margin buffers for undifferentiated private-label suppliers.
- Production Concentration Risk:China's twelve-facility manufacturing clusters dominate global frozen output, creating single-source vulnerability for brands dependent on Shandong and Henan province capacity.
- Fresh Format Substitution:Urban consumers in Shanghai, Beijing, and Shenzhen increasingly favor refrigerated short-shelf-life dumplings for texture quality, threatening frozen volume in premium channels.
Strategic Opportunities
- Plant-Based Filling Formulation:Pea and soy protein extrusion technologies are reaching cost parity with pork and shrimp, opening positioning for flexitarian and religious-dietary segments previously excluded from traditional recipes.
- Direct-to-Restaurant Distribution:Bypassing traditional broadline distributors through proprietary last-mile cold delivery captures margin and captures data on consumption velocity by SKU and operator type.
- EU Allergen Labeling Alignment:EFSA-mandated 14-allergen disclosure protocols, once adopted voluntarily, preempt regulatory friction and accelerate market access timelines for European retail expansion.
Industry Challenges
- Automation Engineering Talent Scarcity:Deposition precision and sealing integrity require mechatronics specialists familiar with food-grade stainless systems, a skill set concentrated in industrial automation hubs with cross-sector competition.
- Multi-Jurisdiction Certification Lag:Simultaneous FDA, EFSA, and SAMR facility audits extend product launch timelines by 8-14 months for manufacturers seeking parallel market entry.
- Legacy Equipment Integration Friction:Retrofitting existing sheeting lines with vision-based quality inspection requires custom mechanical adapters and control system reprogramming that stalls throughput during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dumplings Market |
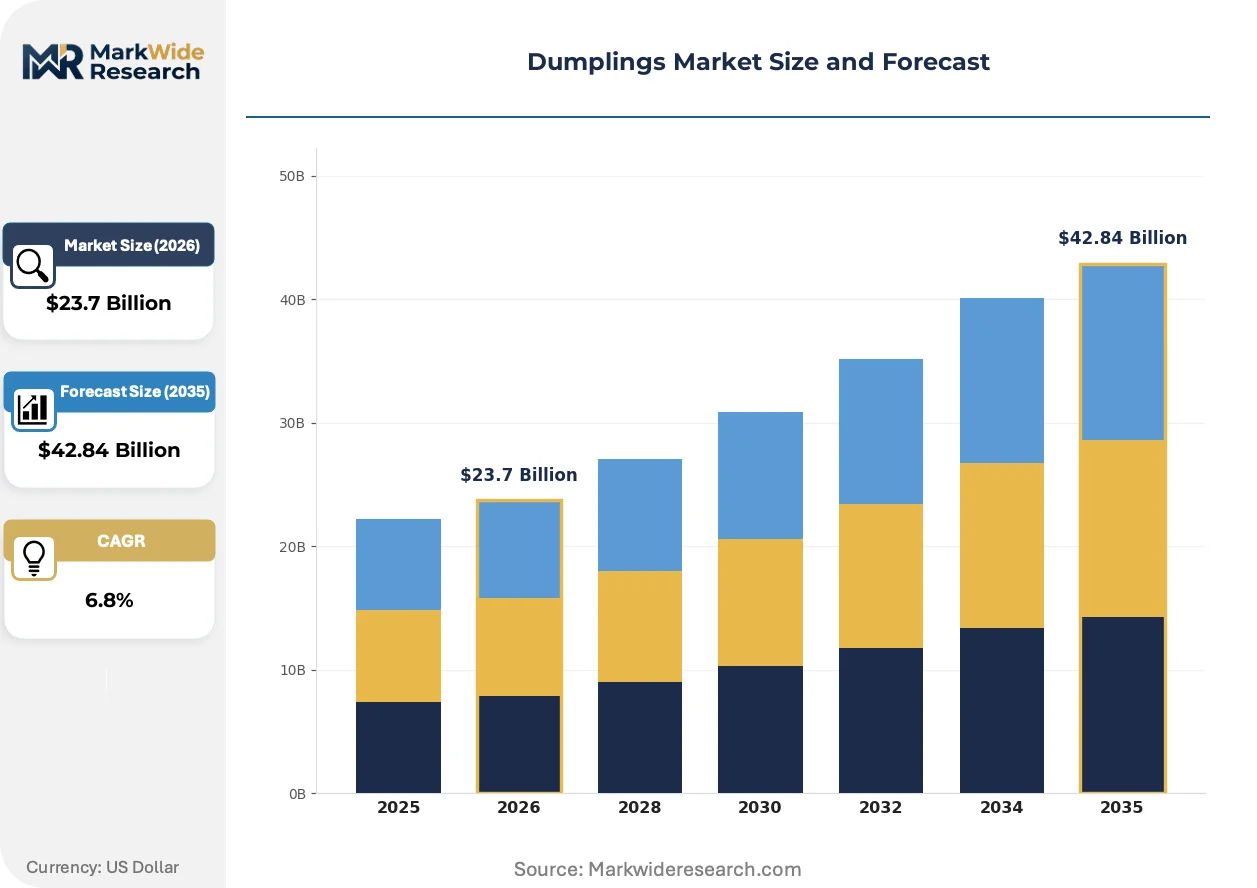
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Dumplings, Fresh Dumplings, Steamed Dumplings, Pan-Fried Dumplings Filling Type: Pork, Chicken, Vegetable, Seafood Distribution Channel: Supermarkets, Grocery Stores, Online Retail, Restaurants End User: Households, Food Service, Caterers, Institutions |
| Companies Covered | Ajinomoto Co. Inc., Wonton Food Inc., CJ CheilJedang Corporation, Day-Lee Foods Inc., Wei-Chuan USA Inc., General Mills Inc., Sanquan Food Co. Ltd., InnovAsian Cuisine Enterprises Inc., Charoen Pokphand Foods Public Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dumplings Market Emerging Trajectories
Sheeting and deposition technologies are converging with digital quality control, while regulatory fragmentation and channel evolution are reshaping how manufacturers prioritize capacity investments and geographic sequencing.
High-speed vision-based defect detection systems identify wrapper thickness variation and filling weight deviation in real-time during continuous production runs. Mid-scale manufacturers in South Korea and Thailand are adopting these systems ahead of full line replacement. Manual inspection stations and sample-based quality protocols are rendering obsolete as lot-level consistency becomes a baseline procurement requirement from multinational retail buyers.
China's SAMR is implementing phased traceability mandates requiring ingredient lot codes to link through distribution to point-of-sale scanning within GB frozen food standards. Manufacturers must retrofit ERP systems and supplier onboarding protocols to capture field-level origin data for wheat, proteins, and additives. Export-oriented facilities in Shandong province are absorbing disproportionate compliance costs to maintain EU and US market access under parallel EFSA and FDA documentation requirements.
Food service procurement teams are consolidating supplier relationships from fragmented local dumpling workshops toward approved vendor lists with HACCP certification and national distribution coverage. Broadline distributors including Sysco and US Foods are expanding private-label frozen dumpling SKUs to capture this consolidation, displacing direct manufacturer relationships in the independent restaurant segment. This concentration is most visible in North American metropolitan markets where labor cost pressure has eliminated in-house dumpling preparation across mid-tier Asian-fusion chains.
Dumplings Market Segmentation
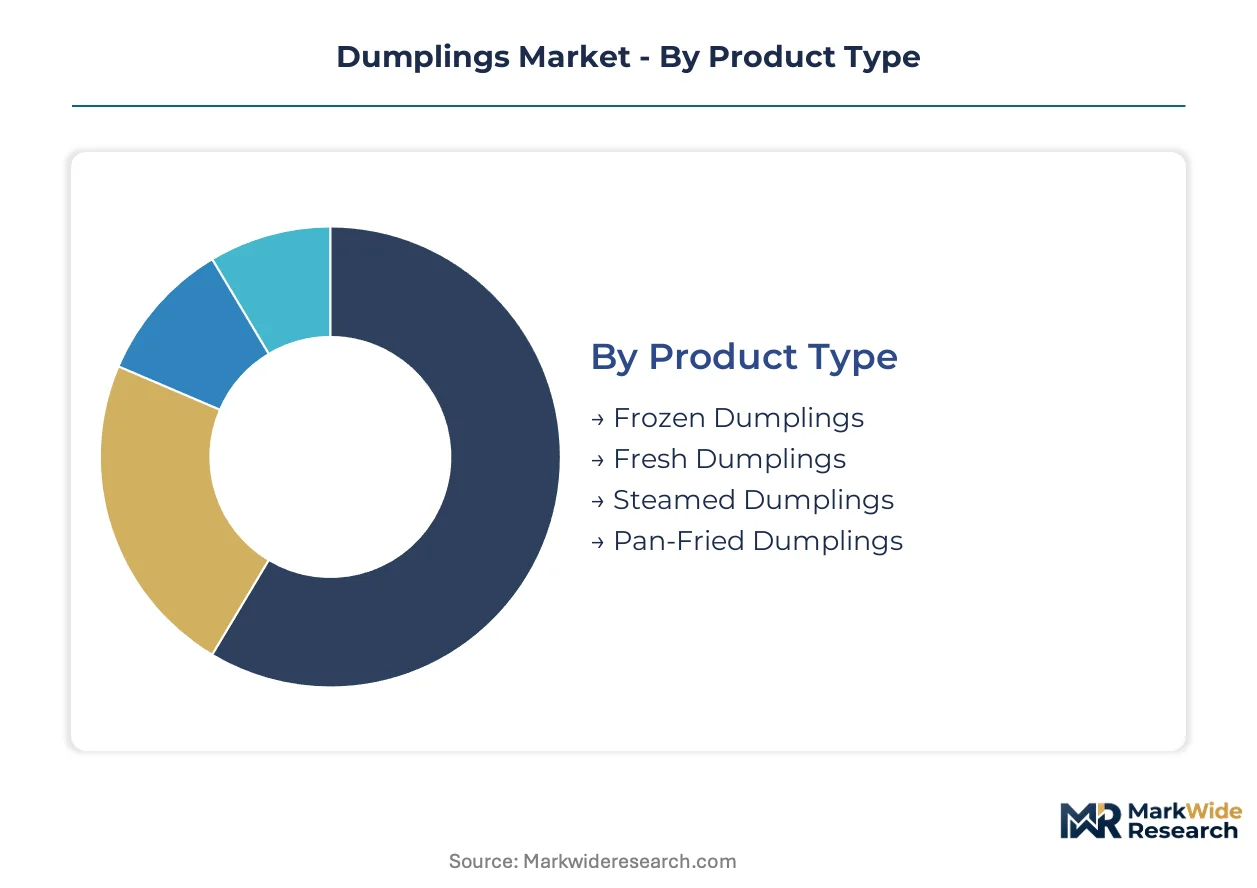
Dumpling manufacturers prioritize segment-specific production cycles to match shelf-life constraints against capital deployment. Frozen formats demand multi-year equipment amortization while fresh variants require rapid inventory turns. Understanding these velocity differentials shapes capacity planning and margin capture strategies across the value chain.
Product Type:
Cycle times vary dramatically: frozen products stretch across months of distribution while fresh formats compress from production to consumption within days. This temporal spread dictates equipment utilization rates and working capital intensity by segment.
- Frozen Dumplings:Wheat-based wrappers encase fillings before flash-freezing locks texture integrity for extended shelf stability. Industrial-scale production lines in China's Shandong province supply retail chains and food service distributors across domestic tier-one cities and export markets. Capital-intensive freezing tunnels and automated sealing equipment create barriers that concentrate manufacturing among multi-facility operators.
- Fresh Dumplings:Refrigerated short-shelf-life formats prioritize wrapper elasticity and filling moisture retention without preservative systems. Urban households in Shanghai and Beijing drive procurement through premium supermarket channels where texture quality commands price premiums over frozen alternatives. Daily production runs and cold-chain urgency compress margin buffers for regional suppliers.
- Steamed Dumplings:Pre-cooked formats target convenience-oriented consumption occasions with reduced home-preparation time.
- Pan-Fried Dumplings:Partially cooked variants optimized for crisp-texture finishing in residential or commercial kitchens.
Frozen dumplings anchor the volume base while fresh dumplings gain share at the steepest rate.
Filling Type:
Protein input costs and religious dietary compliance requirements stratify margin structures across filling categories. Pork and chicken formulations benefit from established supply chains while alternative proteins face formulation stability challenges.
- Pork:Traditional filling base combining ground meat with vegetable adjuncts and seasoning systems optimized for freeze-thaw stability. China's domestic hog farming clusters in Henan and Sichuan provinces supply raw material to frozen dumpling manufacturers under SAMR traceability mandates. Price volatility in feed grain markets transmits directly to wrapper-filling cost ratios.
- Chicken:Leaner protein alternative with faster cooking properties and broader religious dietary acceptance across halal and kosher observant populations. Southeast Asian production facilities in Thailand and Vietnam leverage integrated poultry processing to supply export-oriented dumpling lines.
- Vegetable:Cabbage, mushroom, and glass noodle combinations targeting flexitarian and Buddhist vegetarian dietary segments.
- Seafood:Shrimp and fish formulations requiring stringent cold-chain maintenance to prevent protein degradation.
Pork formulations dominate production volume while plant-based alternatives expand most quickly among urban health-conscious demographics.
Distribution Channel:
Channel selection determines packaging format, case configuration, and promotional investment levels. Direct-to-operator routes bypass retail margin stacking but demand specialized delivery infrastructure.
- Supermarkets:Multi-SKU frozen food aisles with promotional calendar dependency and private-label competition. China's Hema Fresh and Japan's Aeon chains dedicate linear footage to premium dumpling assortments with origin labeling.
- Grocery Stores:Neighborhood-format retailers emphasizing value positioning and local brand recognition over national advertising support.
- Online Retail:Direct-to-consumer frozen delivery requiring insulated packaging and last-mile cold-chain integrity.
- Restaurants:Food service procurement with volume commitments, specification customization, and HACCP documentation requirements.
Supermarket placement secures the broadest consumer reach while restaurant direct distribution climbs fastest as operators outsource preparation.
End User:
User type dictates portion sizing, preparation instruction complexity, and nutritional labeling emphasis. Household convenience seekers prioritize single-serve formats against food service bulk requirements.
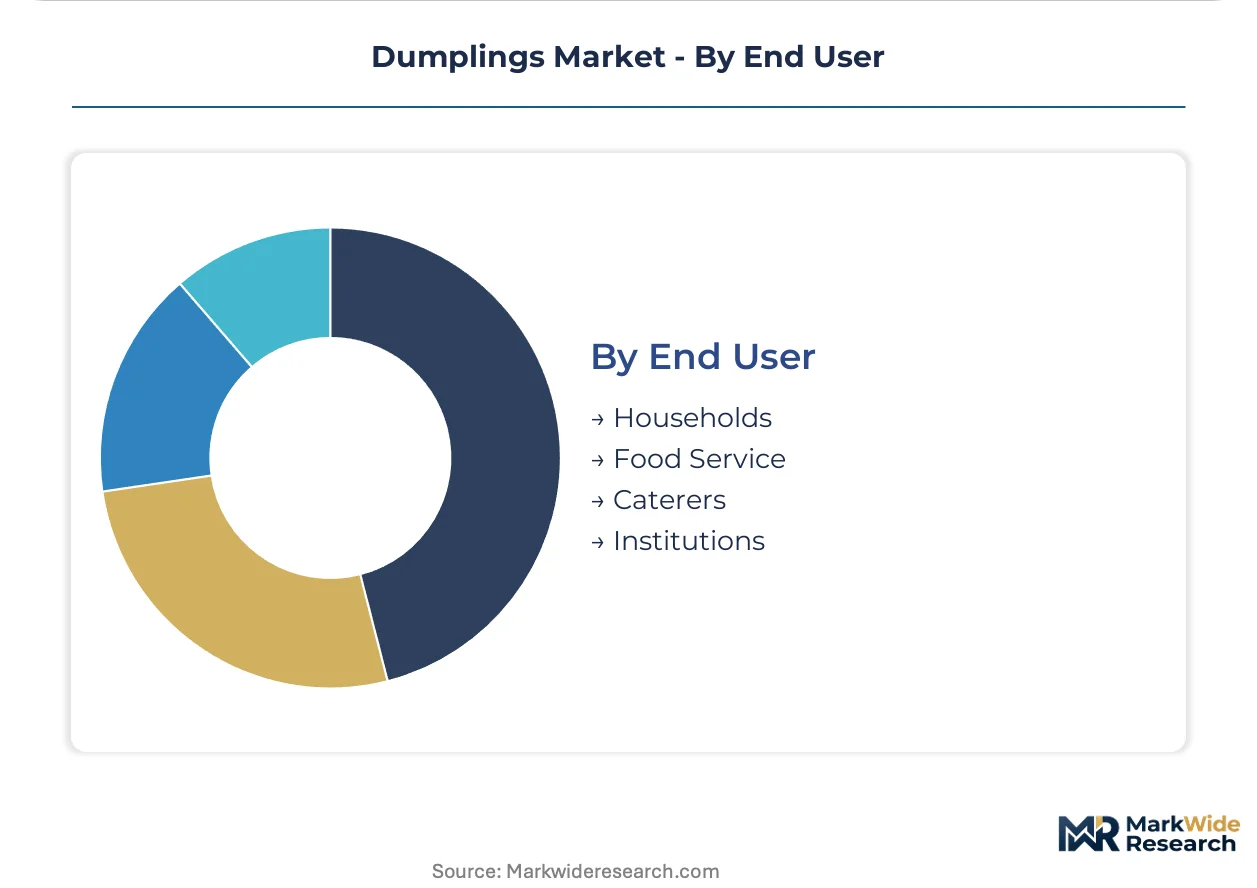
- Households:Retail-packaged formats with cooking instructions calibrated for residential equipment and time constraints. China's urban dual-income families drive repeat purchase frequency through freezer stock-up occasions.
- Food Service:Bulk-packaged products with operator-specific seasoning and wrapper thickness specifications.
- Caterers:Event-scale quantities with holding-stability requirements for buffet service conditions.
- Institutions:School and corporate cafeteria formats with cost targets and nutritional compliance mandates.
Household consumption provides the stable demand foundation while food service adoption accelerates most rapidly through labor cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports frozen dumpling stock to North American retail and food service channels through dedicated cold-chain corridors, while South Korea and Japan supply premium formats to Southeast Asian markets.
China
Urban households in Shanghai and Beijing drive frozen dumpling consumption through convenience-seeking purchasing patterns. SAMR enforces GB standards for frozen prepared foods that mandate additive disclosure and microbial testing protocols. Manufacturing clusters in Shandong and Henan provinces host twelve dedicated production facilities serving domestic tier-one cities and export markets.
United States
Food service operators outsource labor-intensive dumpling preparation to centralized frozen suppliers across metropolitan markets. FDA and USDA regulate import dumplings through hazard analysis and pathogen screening protocols. California and New York Metro area distribution hubs handle the majority of Asian-fusion restaurant procurement through broadline distributors.
Japan
Convenience store chains and supermarket deli counters sustain steady demand for premium frozen gyoza formats. METI oversees food safety frameworks that align with JIS standards for processed food manufacturing. Osaka-based production facilities supply Kansai region retail networks while Tokyo-oriented lines serve the Kanto metropolitan corridor.
South Korea
Domestic mandu consumption concentrates in Seoul Capital Area households seeking quick-preparation protein options. MFDS regulates frozen food additive limits and labeling requirements that manufacturers must satisfy for retail placement. Busan-Ulsan industrial zones host automated production lines exporting to Vietnamese and Thai markets.
Thailand
Integrated poultry processing clusters support chicken-based dumpling export manufacturing for halal-observant markets. The country's national food safety regulator applies stringent cold-chain documentation for frozen prepared foods. Bangkok metropolitan area facilities leverage regional logistics networks to distribute throughout Southeast Asia.
Dumplings Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidated manufacturing scale in China contrasts with fragmented regional suppliers in North America and Europe. Two archetypes dominate: vertically integrated seasoning-to-frozen conglomerates and dedicated dumpling specialists with proprietary cold-chain logistics. Competitive moves center on automated production line deployment and direct-to-restaurant distribution bypassing traditional broadline intermediaries.
Among Asia-Pacific-based conglomerates, Ajinomoto Co. Inc. and CJ CheilJedang Corporation exemplify integrated players controlling flavor consistency and distribution infrastructure. Sanquan Food Co. Ltd. anchors the manufacturing-scale archetype with multi-facility production concentration. Day-Lee Foods Inc. and Wei-Chuan USA Inc. represent North American market specialists bridging import supply with regional food service networks.
| Leading Market Players |
|---|
| Ajinomoto Co. Inc. |
| Wonton Food Inc. |
| CJ CheilJedang Corporation |
| Day-Lee Foods Inc. |
| Wei-Chuan USA Inc. |
| General Mills Inc. |
| Sanquan Food Co. Ltd. |
| InnovAsian Cuisine Enterprises Inc. |
| Charoen Pokphand Foods Public Company Limited |
| Others |
Supply Flow & Price Mechanics
Shandong-to-Los Angeles cold-chain corridors transmit freight cost volatility directly into margin structures, compressing undifferentiated frozen dumpling suppliers while rewarding operators with captive wheat sourcing and automated sheeting capacity that sustains price premiums across tier-one urban markets.
Pricing Analysis
Prior-generation manual sheeting lines price at commodity levels against current-generation automated deposition systems that command 15-25% premiums for lot-level consistency, while next-generation vision-inspected output targets food service contract premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by wrapper thickness precision and filling weight tolerance. Pricing pressure stems from wheat flour futures volatility transmitted through Black Sea supply disruptions. Private-label retail buyers exhibit highest price sensitivity; direct-to-restaurant procurement teams prioritize specification adherence over per-unit cost.
Supply Chain Analysis
Export-control regimes on food-grade stainless steel processing equipment limit automation technology flows to Southeast Asian manufacturing zones, concentrating advanced sheeting and sealing capacity in China's Shandong and Henan provinces alongside secondary clusters in South Korea and Thailand. Wheat flour, pork protein, and pea protein isolates constitute primary input dependencies. Single-source vulnerability concentrates in Shandong's twelve-facility manufacturing clusters. Distribution runs through broadline food service distributors and direct-to-operator cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-restaurant platform economics are displacing traditional distributor intermediaries, with interoperability between manufacturer ERP systems and operator inventory management creating data-rich procurement relationships that reshape competitive positioning.
For Market Incumbents: Pre-empt fresh-format substitution threats by retrofitting existing frozen lines with rapid-changeover capabilities that enable short-run refrigerated production for texture-prioritizing urban consumers. Anchor backward integration into wheat milling and protein processing to buffer margin compression from commodity volatility. Prioritize HACCP certification investments that secure approved vendor status with consolidating food service procurement teams.
For New Entrants and Emerging Players: Build out plant-based filling formulation capabilities targeting flexitarian and religious-dietary segments where pea and soy protein extrusion technologies are reaching cost parity with traditional pork and shrimp recipes. Penetrate direct-to-restaurant distribution white space in North American metropolitan markets where labor cost pressure has eliminated in-house dumpling preparation. Lead with proprietary last-mile cold delivery that captures consumption velocity data by SKU.
For Investors and Strategic Acquirers: SAMR's phased traceability mandates reshape the acquisition landscape by elevating facilities with retrofitted ERP systems and supplier onboarding protocols above legacy competitors facing compliance cost burdens. Long-term viability centers on manufacturing-scale operators with multi-facility geographic diversification and export certification under parallel FDA and EFSA requirements. Monitor automation engineering talent scarcity as the inflection signal indicating which facilities can sustain throughput expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Production Line Deployment | Vision-based quality inspection and high-speed sheeting reduce labor cost per unit for frozen output. |
| Direct-to-Restaurant Distribution Buildout | Proprietary last-mile cold delivery captures margin and consumption velocity data from food service operators. |
| Plant-Based Filling Formulation | Pea and soy protein extrusion technologies unlock flexitarian and religious-dietary segments previously excluded. |
| Multi-Jurisdiction Certification Investment | Parallel FDA, EFSA, and SAMR facility audits accelerate market access timelines for export-oriented capacity. |
| Backward Integration into Wheat Milling | Captive flour supply buffers margin compression from Black Sea supply disruptions and climate yield variability. |
Methodological Framework
Cross-validation between executive interviews and trade data anchors the qualitative findings across this analysis. Primary fieldwork engaged frozen food manufacturing executives, food service procurement directors, cold-chain logistics operators, and retail category buyers. Secondary validation drew from SAMR regulatory filings, customs and trade flow databases, SEC 10-K disclosures from listed food conglomerates, and industry association production statistics. Bottom-up facility capacity assessments and top-down retail audit data were triangulated to establish volume baselines.
Calibration against historical growth patterns and elasticity estimates informed the projection framework across the analysis window. Segmentation dimensions modeled include product format, filling protein source, distribution channel, and end-user type, with regional regulatory clusters as a cross-cutting dimension. CAGRs were derived from trend extrapolation adjusted for technology adoption curves and channel shift dynamics. Wheat futures volatility and automation penetration rates served as industry-specific forecast inputs.
Stress conditions across wheat supply disruptions, cold-chain infrastructure expansion pace, and regulatory compliance cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption timelines and channel consolidation trajectories. Material shifts in SAMR traceability mandate implementation schedules or EFSA allergen labeling enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Dehydrated Food Market