
 Processed and Frozen Vegetables Market | 2026-2036
Processed and Frozen Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Processed and Frozen Vegetables Market Intelligence
Divergent investment in automated processing and cold chain logistics is bifurcating the competitive landscape. Large-scale operators like McCain Foods Limited leverage global supply chains and extensive distribution networks to dominate the frozen potato segment. Bonduelle S.A. differentiates through brand marketing and product innovation in mixed vegetables and specialty items. Meanwhile, Conagra Brands Inc. competes across multiple product categories by utilizing its vast retail channel access.
Processed and frozen vegetables are food products that have undergone preparation such as cleaning, cutting, and blanching before being rapidly frozen to temperatures below -18°C. This industrial process halts enzymatic and microbial activity, preserving the vegetable's nutritional content, flavor, and texture for extended periods. Frozen potatoes, particularly french fries, represent the largest product category by volume due to strong demand from the quick-service restaurant industry. The adoption of Individually Quick Frozen (IQF) technology is a key value driver, enabling premium pricing for free-flowing products like peas and corn targeted at household consumers.
Regulatory frameworks, including the U.S. Food and Drug Administration's (FDA) standards on food safety and the European Food Safety Authority's (EFSA) regulations on contaminants and labeling, govern market access. These rules mandate strict process controls and transparent nutritional information, directly influencing production costs and consumer trust. Stakeholders must now decide how to balance investments in advanced freezing technologies against the rising consumer demand for clean-label products with minimal processing.
Market Dynamics
The central structural force shaping the processed and frozen vegetables market is the capital-intensive divide between automated, large-scale processing and cold chain logistics. This bifurcation separates global operators from smaller firms, creating distinct competitive tiers based on technological adoption and distribution reach.
Growth Catalysts
- IQF Technology Adoption:The proliferation of Individually Quick Frozen (IQF) technology enhances product quality by preserving texture and nutritional value, allowing producers to command premium prices for free-flowing vegetables like peas and corn.
- Food Service Sector Demand:Expansion of quick-service and restaurant chains creates consistent, high-volume demand for standardized products like frozen french fries, which require uniform quality and preparation characteristics.
- Retail Modernization in China:The rapid expansion of supermarket and hypermarket formats across China, coupled with rising disposable incomes, is accelerating household adoption of frozen vegetables as a convenient food staple.
Market Restraints
- Energy Cost Volatility:The industry's heavy reliance on energy for blast freezing, cold storage, and refrigerated transportation exposes processors to significant margin pressure from fluctuating electricity and fuel prices.
- Agricultural Supply Chain Risks:Production volumes are intrinsically linked to agricultural yields, which are increasingly vulnerable to climate change, extreme weather events, and water scarcity, leading to input price instability.
- Stringent Regulatory Compliance:Adherence to food safety standards from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) necessitates costly process controls, documentation, and testing, acting as a barrier for new entrants.
Strategic Opportunities
- Clean-Label Product Development:There is a significant opportunity to capture health-conscious consumers by developing and marketing frozen vegetable products with minimal processing, no artificial additives, and transparent sourcing stories.
- Direct-to-Consumer Channels:The growth of e-commerce and subscription box models provides a pathway for brands to bypass traditional retail gatekeepers, build direct customer relationships, and test new product innovations.
- Emerging Market Penetration:Targeting urban centers in Southeast Asia and Latin America, where cold chain infrastructure is improving and consumer lifestyles are modernizing, offers new avenues for market expansion beyond mature regions.
Industry Challenges
- High Capital Expenditure:Upgrading or building facilities with automated processing lines and advanced cryogenic freezing systems requires substantial upfront capital investment, challenging small and mid-sized enterprises.
- Cold Chain Logistics Complexity:Managing the integrity of the frozen supply chain, particularly for last-mile delivery in the burgeoning e-commerce sector, presents significant operational and cost hurdles.
- Skilled Labor Scarcity:A shortage of technicians qualified to operate, maintain, and repair sophisticated automated processing and packaging machinery can lead to operational inefficiencies and downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed and Frozen Vegetables Market |
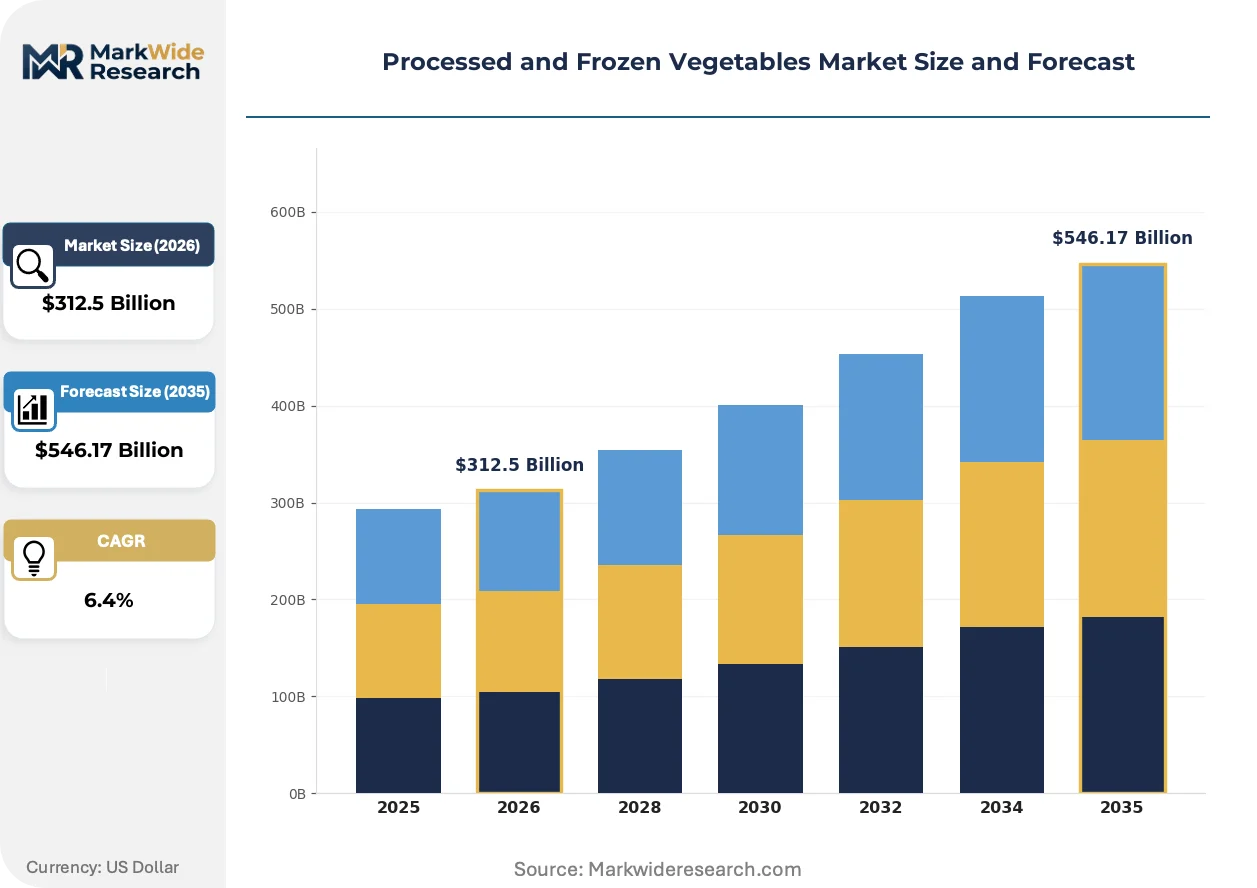
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $546.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Peas, Frozen Carrots, Mixed Vegetables, Frozen Potatoes End User: Households, Restaurants, Food Manufacturers, Catering Services Technology: Blast Freezing, Cryogenic Freezing, IQF, Freeze-Drying Distribution Channel: Supermarkets, Online Retailers, Wholesale Distributors, Convenience Stores |
| Companies Covered | Bonduelle S.A., Nomad Foods, General Mills Inc., Pinnacle Foods Inc., Greenyard NV, Conagra Brands Inc., McCain Foods Limited, Hanover Foods Corp., J.R. Simplot Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed and Frozen Vegetables Market Strategic Shifts & Innovations
The market's evolution is defined by a push for greater operational efficiency through automation while simultaneously responding to consumer demand for natural and convenient products. This dynamic forces innovation in both processing technology and product formulation to balance industrial scale with perceived freshness.
Cryogenic freezing, which utilizes liquid nitrogen or carbon dioxide, offers an ultra-rapid freezing process ideal for delicate vegetables. Specialty food manufacturers and processors of high-value produce are adopting this method to better preserve cellular integrity. This advanced technique is miniaturizing the formation of ice crystals within the vegetable, which prevents cell wall damage and maintains a superior texture and nutrient profile compared to conventional air-blast freezing.
The European Union's Farm to Fork Strategy, a key component of the EU Green Deal, is promoting more sustainable food production systems. This initiative pressures processors to reduce their overall environmental footprint, including energy and water consumption. The frozen vegetable segment is responding by investing in more energy-efficient freezing technologies and increasing transparency in sourcing raw materials from certified sustainable farms.
Consumer purchasing behavior is shifting toward value-added, ready-to-cook frozen vegetable mixes over traditional single-ingredient bags. This preference is disrupting the retail freezer aisle, compelling brands to innovate with pre-seasoned, chopped, and blended products that significantly reduce meal preparation time. This pattern is most pronounced in North American and European household markets, driven by consumer demand for convenient and healthy meal solutions.
Processed and Frozen Vegetables Market Segmentation
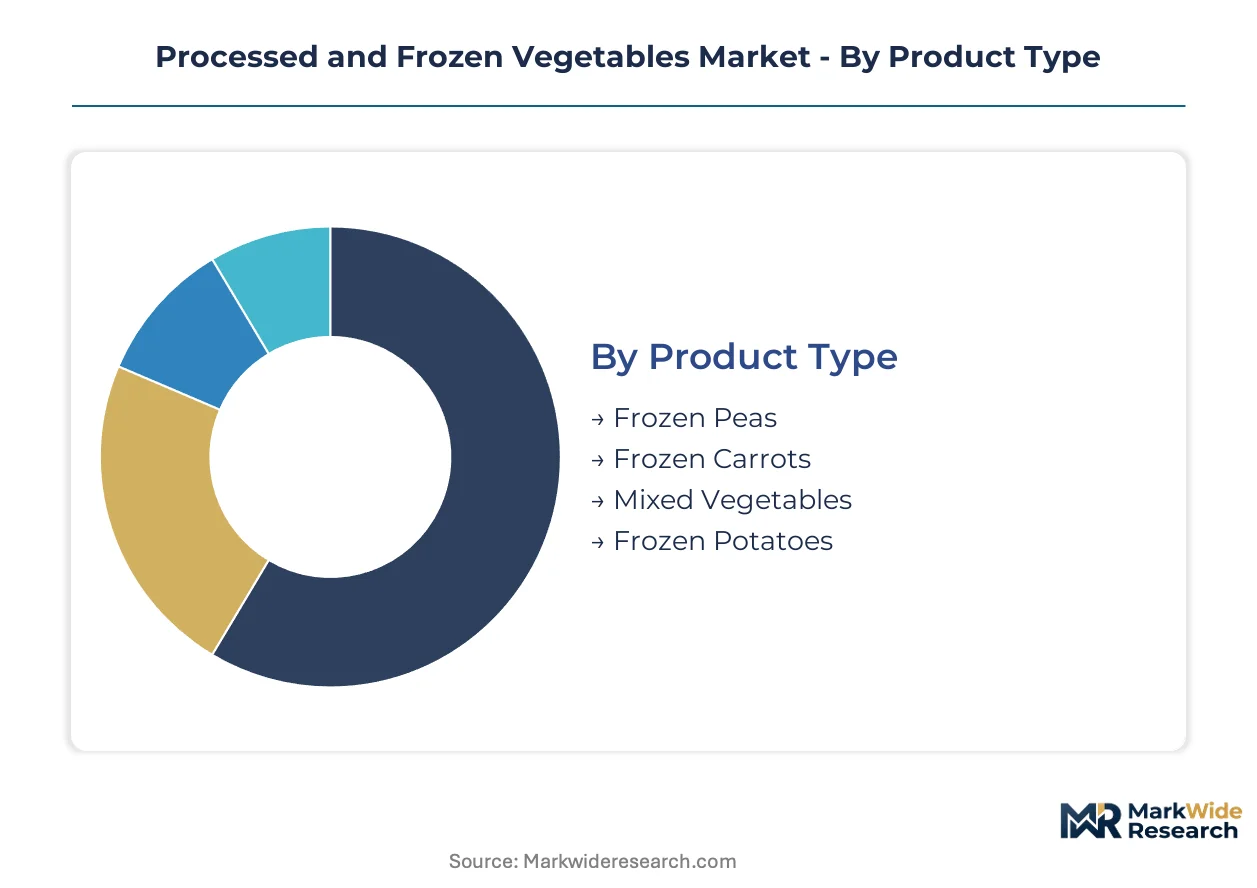
Segmentation within the processed and frozen vegetables market reveals distinct consumption patterns and operational requirements across various product types, end-users, technologies, and distribution channels. Understanding these divisions is essential for market participants to tailor product development and optimize supply chain strategies for specific consumer needs.
Product Type:
The market for frozen vegetables faces substitution pressure from fresh produce, particularly for basic items, necessitating innovation in convenience and value-added offerings.
- Frozen Potatoes:This segment includes products like french fries and potato wedges, which undergo washing, cutting, blanching, and rapid freezing. Demand concentrates heavily in the quick-service restaurant industry and food service sector due to consistent quality and ease of preparation.
- Mixed Vegetables:Consisting of various vegetable combinations, often pre-chopped and seasoned, these products cater to consumer demand for convenience and reduced meal preparation time. Innovation in flavor profiles and exotic blends drives household adoption in North American and European markets.
- Frozen Peas:Individual peas are typically blanched and then Individually Quick Frozen (IQF) to maintain their texture and nutritional integrity. This product type sees steady demand from both household consumers and food manufacturers for use in various dishes and processed foods.
- Frozen Carrots:Prepared as diced, sliced, or whole baby carrots, these are blanched and frozen to preserve their color and vitamin content. Frozen carrots are a staple ingredient for home cooking and industrial food applications, including soups and stews.
Frozen Potatoes anchors the volume base while Mixed Vegetables gains share at the steepest rate.
End User:
End user segmentation highlights varying requirements for product form, packaging, and volume, influencing supply chain configuration and product specifications.
- Households:Consumers purchase frozen vegetables for at-home meal preparation, prioritizing convenience, health, and extended shelf life. The expansion of supermarket formats and rising disposable incomes in countries like China drive this segment.
- Restaurants:Quick-service and casual dining establishments require consistent quality, uniform portioning, and ease of preparation for high-volume menu items. Frozen french fries represent a significant demand component from this sector.
- Food Manufacturers:Industrial food producers utilize frozen vegetables as ingredients in ready meals, soups, sauces, and other processed food items. They demand bulk quantities, specific cuts, and reliable supply chains for their production lines.
- Catering Services:Institutional caterers for schools, hospitals, and corporate events rely on frozen vegetables for efficient meal production and portion control. This segment values cost-effectiveness and minimal preparation time.
The Household segment concentrates the largest volume, while Restaurants exhibit the highest growth in product customization.
Technology:
Technology choices in freezing impact product quality, energy consumption, and capital expenditure, directly affecting market competitiveness and product differentiation.
- IQF:Individually Quick Frozen technology rapidly freezes individual pieces of vegetables, preventing clumping and preserving cellular structure, flavor, and nutritional value. This method allows producers to command premium pricing for free-flowing products like peas and corn.
- Cryogenic Freezing:This ultra-rapid freezing process uses liquid nitrogen or carbon dioxide to achieve extremely low temperatures, minimizing ice crystal formation and maintaining the cellular integrity of delicate vegetables. Specialty food manufacturers adopt this technology for high-value produce.
- Blast Freezing:A conventional method involving circulating cold air at high velocity over vegetables, blast freezing is cost-effective for large volumes. This technology is widely used for bulk freezing of various vegetables, though it can sometimes lead to larger ice crystals.
- Freeze-Drying:This process involves freezing the vegetable and then removing ice by sublimation under vacuum, resulting in a lightweight product with extended shelf life. Freeze-drying is used for specialty ingredients and camping foods, offering minimal nutritional degradation.
IQF technology garners the largest market share, while Cryogenic Freezing demonstrates the most significant investment expansion.
Distribution Channel:
Distribution channels determine market reach, pricing strategies, and logistical complexities, connecting producers to diverse end-user segments.
- Supermarkets:Large retail chains serve as the primary channel for household consumers, offering a wide array of frozen vegetable products. Modernization of retail infrastructure in emerging markets drives sales through this channel.
- Online Retailers:E-commerce platforms and subscription box services provide direct access to consumers, enabling brands to bypass traditional retail gatekeepers. This channel facilitates new product innovation and builds direct customer relationships.
- Wholesale Distributors:These entities supply frozen vegetables in bulk to food service establishments, catering services, and smaller retailers. They manage complex logistics and cold chain requirements for large-volume transactions.
- Convenience Stores:Smaller retail formats offer limited selections of frozen vegetables, catering to immediate consumption needs or impulse purchases. These stores typically stock single-serve or smaller package sizes.
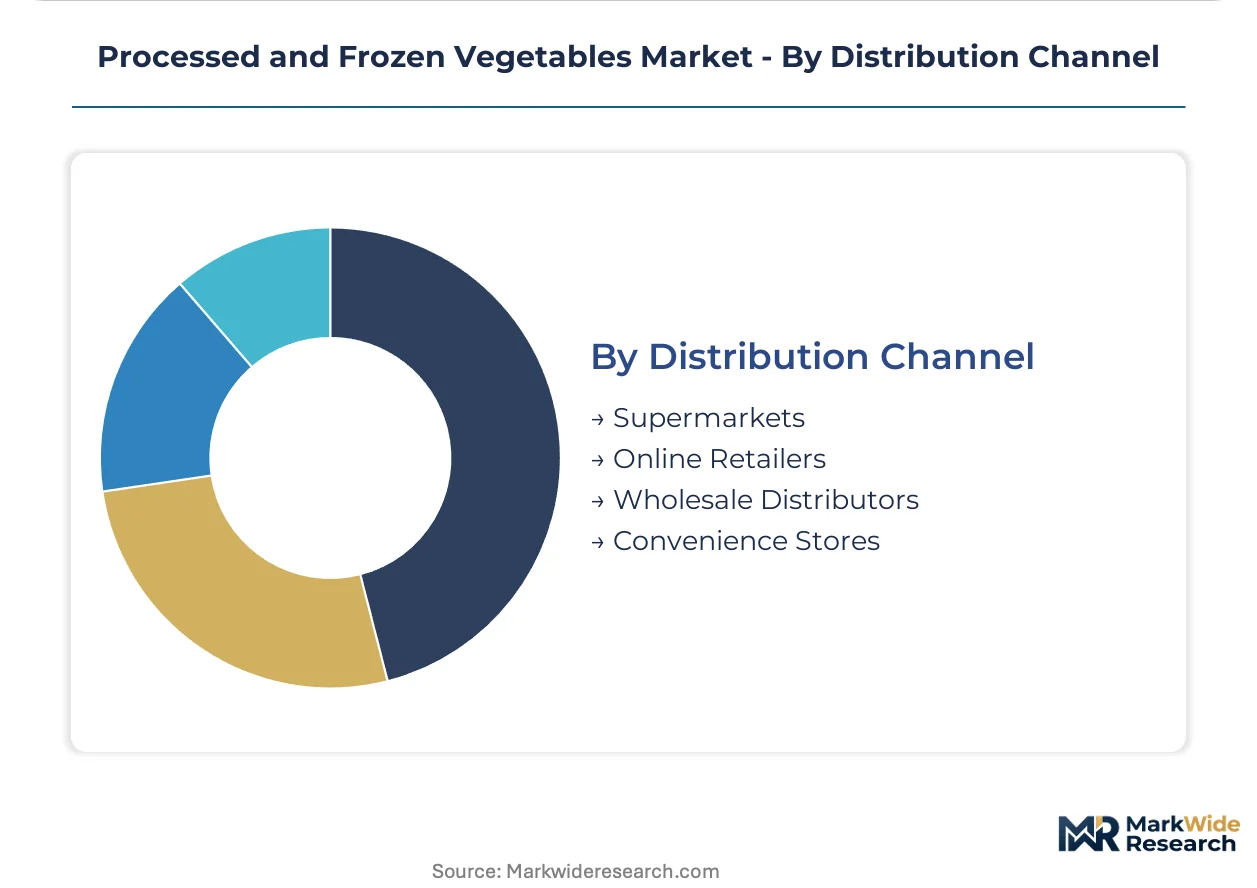
Supermarkets maintain the highest volume throughput, with Online Retailers expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global processed and frozen vegetables market exhibits varied import-export dynamics across key regions. Developed economies often import specialized frozen vegetable products while also exporting high-value processed items. Emerging markets balance domestic consumption with increasing foreign trade.
China
China's market demand expands due to rising household incomes and rapid supermarket retail expansion. The State Administration for Market Regulation (SAMR) enforces stringent food safety and labeling requirements. The Yangtze River Delta region drives frozen vegetable consumption through its dense urban population and modern retail networks.
United States
United States demand stems from the quick-service restaurant industry and households seeking convenience. The U.S. Food and Drug Administration (FDA) mandates strict food safety and nutritional labeling. California's Central Valley acts as a processing hub, utilizing advanced IQF technologies to supply frozen vegetables across North America.
Germany
Germany exhibits robust demand for frozen vegetables, driven by consumer preferences for convenience, health, and organic options. The European Food Safety Authority (EFSA) regulations significantly impact product quality and labeling standards. North Rhine-Westphalia hosts numerous food processing facilities focusing on sustainable practices and efficient freezing methods.
India
India's market expands with rapid urbanization and evolving consumer lifestyles favoring convenient food solutions. The Food Safety and Standards Authority of India (FSSAI) governs food safety and quality standards for all frozen food products. The National Capital Region (NCR) around Delhi demonstrates significant growth, propelled by improving cold chain logistics and modern retail.
Brazil
Brazil's processed and frozen vegetable market benefits from an expanding middle class and modernizing retail channels. ANVISA enforces strict food safety and hygiene regulations for all frozen food manufacturers. São Paulo state attracts significant investment in advanced food processing and cold chain logistics, serving a growing consumer base.
Processed and Frozen Vegetables Market Key Industry Players
Concentration sits with large-scale operators leveraging global supply chains and extensive distribution networks. The market exhibits a tiered structure, with global food giants coexisting with regional specialists and niche innovators. Strategic archetypes include high-volume commodity processors, brand-driven specialty producers, and diversified food conglomerates. Dominant competitive moves involve significant capital expenditure into automated processing and continuous investment in cold chain logistics infrastructure, creating barriers to entry for smaller firms.
Global food processing giants anchor the competitive landscape, with McCain Foods Limited exemplifying a dominant operator in the frozen potato segment through vast production capabilities and extensive distribution networks. Bonduelle S.A., a European-based specialist, differentiates through brand marketing and product innovation, particularly in mixed vegetables and specialty items. Conagra Brands Inc., an American food company, occupies a strong position across multiple product categories by leveraging its extensive retail channel access and diverse brand portfolios to reach a broad base of household consumers.
| Leading Market Players |
|---|
| Bonduelle S.A. |
| Nomad Foods |
| General Mills Inc. |
| Pinnacle Foods Inc. |
| Greenyard NV |
| Conagra Brands Inc. |
| McCain Foods Limited |
| Hanover Foods Corp. |
| J.R. Simplot Co. |
| Others |
Cost & Logistics Intelligence
Optimized capacity utilization in automated processing lines dictates supply concentration and sets a competitive price floor for bulk frozen vegetables. This industrial scale favors operators with extensive cold chain logistics capabilities.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for bulk frozen vegetables. Pricing stratifies across premium, standard, and economy tiers based on processing technology like IQF, organic certification, and volume scale. Energy cost volatility creates margin pressure across all product categories. Households exhibit higher price sensitivity for basic items, while quick-service restaurants prioritize consistent quality over marginal price differences.
Supply Chain Analysis
Strategic stockpile management balances agricultural seasonality with consistent market demand for frozen vegetables. Supply concentrates in agricultural hubs across the United States, China, and Germany, drawing from fresh produce and specialized packaging materials. Climate change impacts on agricultural yields pose a structural risk to input stability. Distribution runs through wholesale distributors to food service and supermarkets for household consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The processed and frozen vegetables market offers fragmentation opportunities for niche players. Consumer demand for clean-label products and ready-to-cook mixes creates distinct segments beyond bulk commodities.
For Market Incumbents: Compound investments in advanced freezing technologies and cold chain logistics infrastructure to maintain scale advantages. Expand global supply chains to mitigate agricultural supply chain risks and energy cost volatility. Continuous R&D in product innovation, like pre-seasoned mixes, defends against emerging niche players. Channel control through supermarket partnerships reinforces market position against new entrants.
For New Entrants and Emerging Players: Organic certification fast-tracks market entry for health-conscious consumers seeking premium frozen vegetables. Target clean-label product development with transparent sourcing stories, leveraging e-commerce and subscription box models. Focus on urban centers in Southeast Asia where cold chain infrastructure is improving, offering value-added, ready-to-cook mixes. This approach bypasses traditional retail gatekeepers for direct customer relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated mid-cap specialists serving both food service and household segments. Long-term viability rests on stable demand for convenience and health-oriented frozen options over the next decade. Target acquisition candidates with strong brand equity in mixed vegetables or proprietary IQF/cryogenic freezing capabilities. The signal to watch is the increasing penetration of direct-to-consumer channels for specialty frozen foods.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Investment | Enhances operational efficiency and reduces production costs for high-volume frozen potato segments. |
| Cryogenic Freezing Adoption | Preserves cellular integrity and nutritional value in delicate vegetables, commanding premium pricing. |
| Clean-Label Product Launch | Captures health-conscious consumer demand for minimally processed frozen vegetable options. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail, building direct customer relationships and testing new product innovations. |
| Sustainable Sourcing Certification | Addresses EU Farm to Fork Strategy pressures and consumer preferences for environmentally responsible produce. |
Research Approach
Operator-level perspectives from food technologists, cold chain logistics managers, and retail category buyers anchored the qualitative base. Primary interviews were triangulated with secondary validation from government food safety reports and agricultural output statistics. This approach combined bottom-up market insights with top-down industry trends.
Sensitivity analysis informed the forecast framework across the analysis window, evaluating multiple market scenarios. Segmentation dimensions modeled included product type, end-user, technology, distribution channel, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included IQF technology adoption rates and energy price forecasts.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or extreme weather events would require recalibration. Forecasts reflect assumptions regarding agricultural yields and consumer purchasing behavior. Revision becomes warranted when significant input cost fluctuations cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Frozen Sardine Market