
 Frozen Meat Market | 2026-2036
Frozen Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Meat Market Analysis
Skilled cold-chain technicians is rotating from legacy warehouse operations toward automated blast-freezing facilities, tightening labor availability for mid-scale processors. JBS S.A. leverages vertical integration across Brazilian cattle ranches and U.S. beef processing plants to sustain margin control through feedlot-to-retail traceability. Tyson Foods, Inc. anchors its competitive stance through brand strength in private-label retail channels, while Cargill, Inc. dominates industrial ingredient supply to foodservice distributors.
Frozen meat comprises animal protein preserved at temperatures below minus eighteen degrees Celsius through rapid blast freezing or cryogenic tunnel methods, halting microbial activity while maintaining myofibrillar structure for subsequent thawing and cooking. The primary commercial purpose centers on extending distribution radius from slaughter facilities to retail and foodservice endpoints without spoilage loss. Beef and chicken categories lead volume throughput, with vacuum pack configurations capturing premium margin pools in supermarket channels due to extended shelf life and reduced freezer burn incidence. Online retail distribution is expanding fastest among channels, though wholesale distributors still occupy the largest revenue share through institutional contracts with hospital and school systems.
FDA inspection protocols and USDA grading standards govern product safety and quality classification in the United States, while EFSA and national veterinary regulators across Europe enforce residue monitoring and animal welfare compliance for imported frozen protein. China's SAMR and GB standards for frozen meat imports are tightening cold-chain documentation requirements, reshaping export eligibility for non-compliant origins. Stakeholders must monitor evolving carbon-accounting rules for refrigeration energy use, as regulatory bodies in multiple jurisdictions advance climate-linked reporting obligations that will recalibrate facility investment priorities.
Market Dynamics
Blast freezing technology is compressing the cost structure for frozen meat distribution by extending shelf stability while reducing spoilage loss across extended supply chains. This single capability shift is redrawing competitive boundaries between integrated processors and third-party cold-chain operators.
Growth Catalysts
- Quick-service restaurant expansion:Labor shortages in North American kitchen operations are forcing chains to outsource protein prep to frozen suppliers with blast-freezing capabilities.
- Modified atmosphere packaging:Vacuum and gas-flush configurations are capturing premium supermarket placement by eliminating freezer burn incidence.
- Export-oriented processing clusters:Brazilian feedlot-to-port infrastructure anchors massive capacity serving Asian and Middle Eastern buyers under tightened cold-chain documentation.
Market Restraints
- Energy cost volatility:Blast freezing and cryogenic tunnel operations expose processors to electricity and liquid nitrogen price swings that compress operating margins.
- Technician scarcity:Skilled cold-chain labor is migrating from legacy warehouses to automated facilities, tightening availability for mid-scale operators.
- Import documentation tightening:China's SAMR and GB standards are disqualifying non-compliant origins from eligibility, reshaping export market access.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer frozen meat delivery is outpacing traditional wholesale growth as last-mile cold-chain solutions mature.
- Carbon-accounting compliance services:Refrigeration energy reporting obligations under EU CSRD and emerging US EPA frameworks create advisory revenue streams.
- Traceability technology convergence:Integration of blockchain documentation with blast-freezing logs enables feedlot-to-retail verification for premium positioning.
Industry Challenges
- Cold-chain technician recruitment:Automated blast-freezing facilities are poaching experienced personnel from conventional warehouse operations.
- Multi-jurisdiction certification timelines:Simultaneous FDA, USDA, EFSA, and SAMR compliance requirements extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Meat Market |
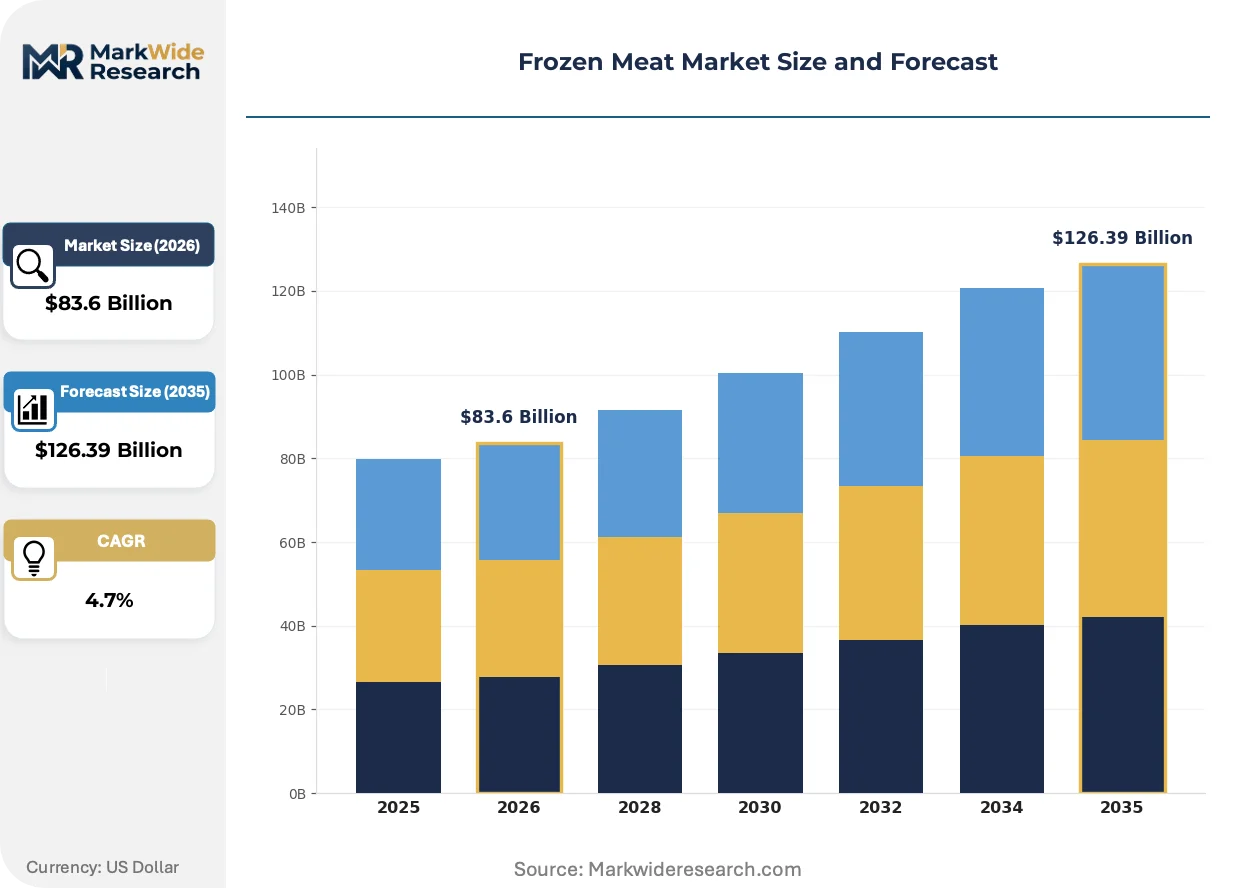
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $126.39 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Chicken, Seafood Packaging Type: Vacuum Pack, Reusable Containers, Sachets, Bulk Packaging Distribution Channel: Supermarkets, Online Retail, Restaurants, Wholesale Distributors End User: Households, Food Processing, Catering Services, Institutional Users |
| Companies Covered | WH Group Limited, BRF S.A., JBS S.A., NH Foods Ltd., Danish Crown A/S, Tyson Foods, Inc., Marfrig Global Foods S.A., Conagra Brands, Inc., Cargill, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Meat Market Emerging Trajectories
Processing technology and packaging science are compressing the gap between fresh and frozen product perception. These shifts are enabling new distribution geometries that bypass traditional wholesale hierarchies.
Cryogenic tunnel freezing is bifurcating the equipment market between high-throughput automated lines and smaller batch units for specialty processors. Quick-service chains are adopting the high-capacity configurations fastest, while artisanal suppliers gravitate toward modular systems. This technology split is compressing price competition at the mid-tier equipment segment.
EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in commercial freezing equipment. Equipment manufacturers are retooling toward ammonia and CO2 cascade systems. Cold-chain operators in Germany and France are absorbing retrofit costs earliest, forcing margin compression across European processing networks.
Hospital and school system buyers are consolidating procurement through national purchasing cooperatives. These aggregators are disintermediating traditional foodservice distributors by contracting directly with blast-freezing processors. The shift is most visible in US institutional channels where USDA commodity programs intersect with cooperative buying structures.
Frozen Meat Market Segmentation
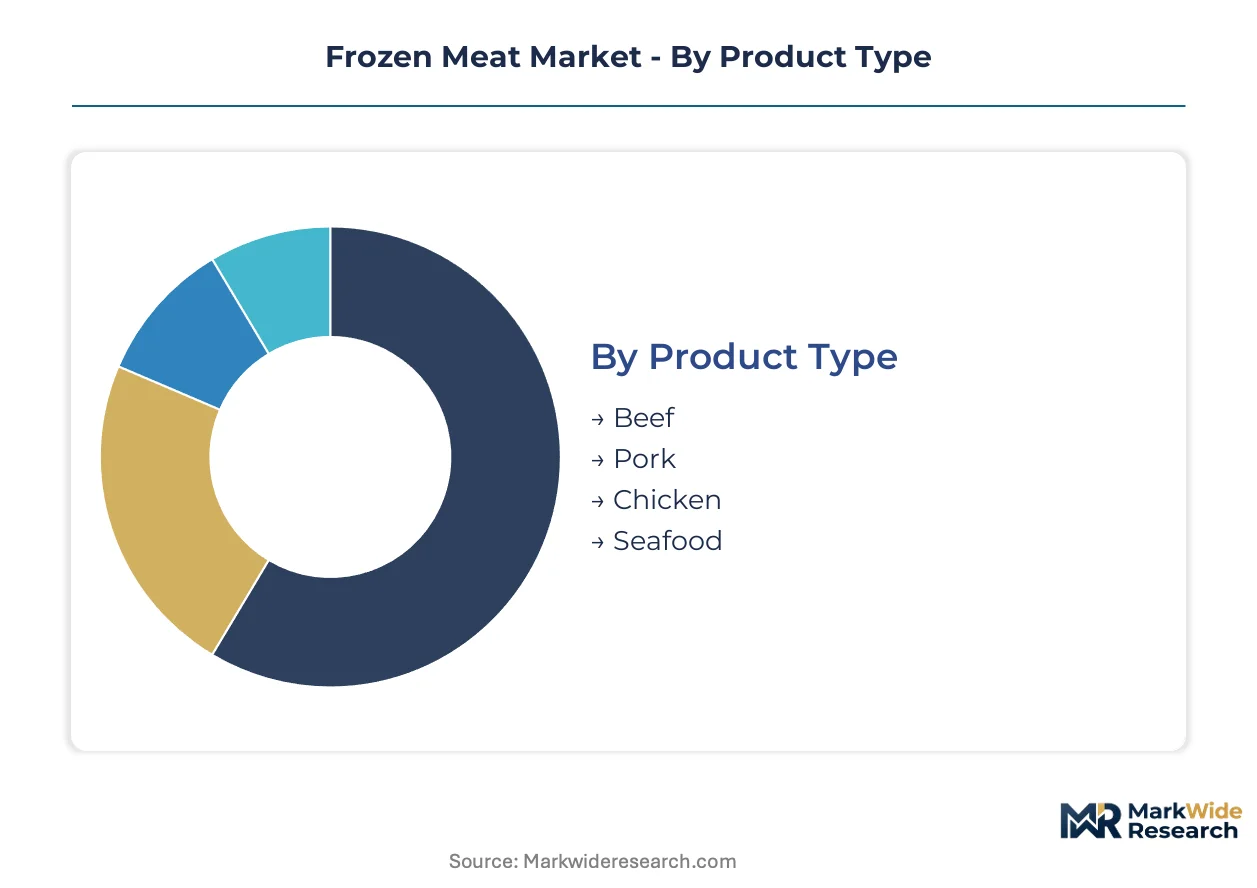
Frozen meat segmentation reveals divergent supply chain requirements across protein categories and packaging configurations. Distribution channel dynamics are compressing traditional wholesale hierarchies while end-user concentration reshapes procurement patterns.
Product Type:
Beef and chicken anchor domestic consumption across North American and European markets, while pork and seafood segments tilt heavily toward export-oriented processing clusters in Brazil and Southeast Asia.
- Beef:Blast-frozen primal cuts and ground formulations dominate institutional procurement through USDA commodity programs. Quick-service restaurant chains in the United States are expanding frozen beef procurement as kitchen labor shortages persist.
- Chicken:Vacuum-packed breast portions and mechanically separated meat supply industrial food processing and retail private-label channels. Brazilian processors JBS S.A. and BRF S.A. anchor massive export capacity serving Middle Eastern buyers under tightened SAMR documentation.
- Pork:Frozen pork belly and ham segments concentrate in European cured-meat processing and Asian import markets.
- Seafood:Individually quick-frozen fish fillets and shellfish serve retail and foodservice through specialized cold-chain operators.
Beef commands the established base. The steepest expansion runs through chicken.
Packaging Type:
Cost tiers separate premium vacuum configurations from economy bulk formats, with modified atmosphere technology capturing margin expansion in supermarket channels.
- Vacuum Pack:Barrier film configurations eliminate freezer burn incidence while extending shelf stability. Premium supermarket placement in Germany and France absorbs higher unit costs through reduced spoilage loss.
- Reusable Containers:Rigid polymer totes serve closed-loop distribution between processors and large-scale institutional kitchens. Closed-loop logistics concentrate in Nordic markets with established return infrastructure.
- Sachets:Single-serve portions target direct-to-consumer online retail with last-mile cold-chain solutions.
- Bulk Packaging:Cryovac-lined corrugated containers supply food processing and wholesale distributor channels at lowest unit cost.
Vacuum pack commands the established base. The steepest expansion runs through sachets.
Distribution Channel:
Volume concentration favors wholesale distributors through institutional contracts, while online retail climbs fastest as last-mile freezing solutions mature.
- Supermarkets:Multi-temperature display cases and private-label programs anchor retail volume. Modified atmosphere packaging enables premium placement in European chains absorbing EU F-Gas retrofit costs.
- Online Retail:Direct-to-consumer subscription models and meal-kit assembly are outpacing traditional channel growth. Cold-chain logistics providers in the United States are deploying specialized frozen last-mile fleets.
- Restaurants:Quick-service chains outsource protein prep to blast-freezing suppliers with portion-controlled specifications.
- Wholesale Distributors:Hospital and school system contracts through national purchasing cooperatives sustain largest revenue share.
Wholesale distributors command the established base. The steepest expansion runs through online retail.
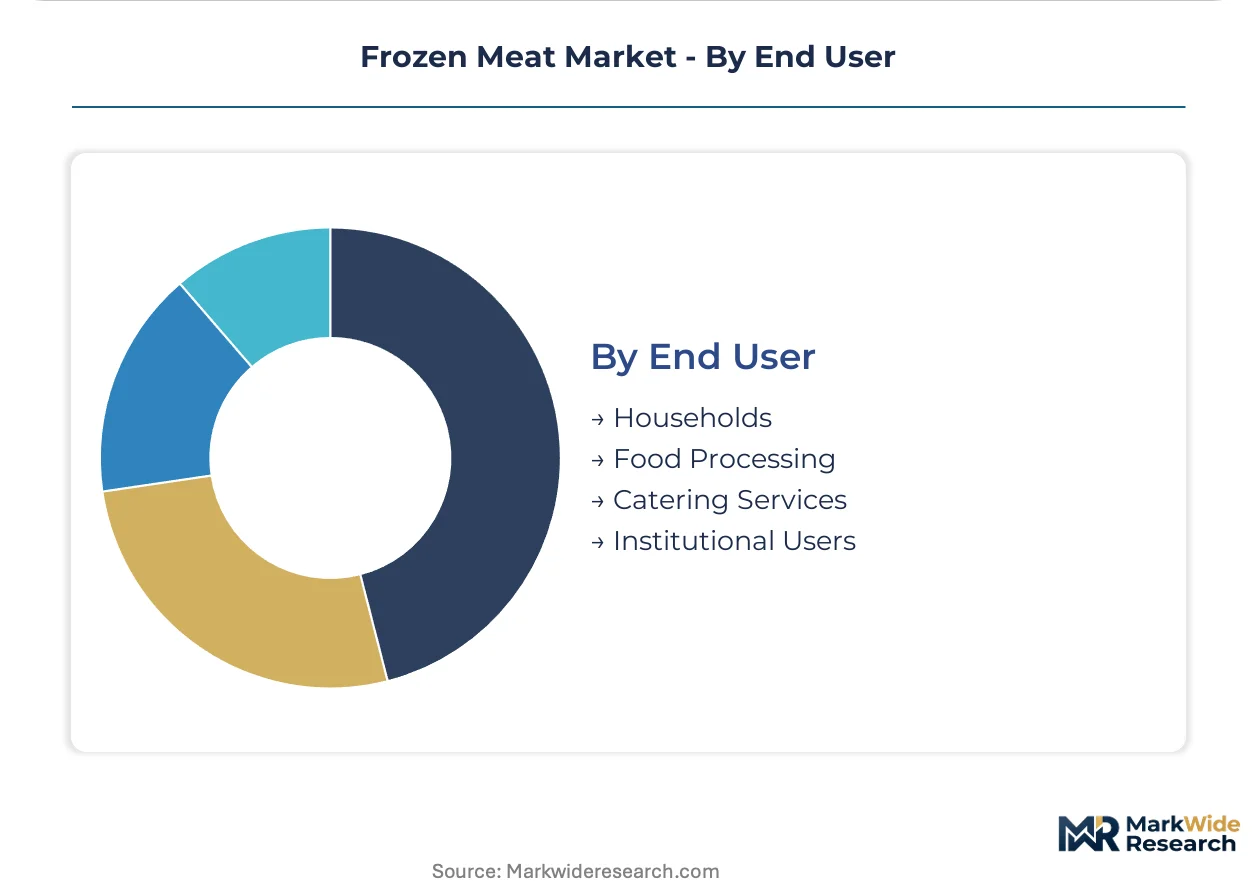
End User:
Application requirements split between household convenience orientation and industrial scale processing with divergent specification tolerances.
- Households:Retail-packaged portions with extended shelf life target weekly meal planning and emergency stockpiling. Online subscription penetration is climbing fastest among household segments in urban United States markets.
- Food Processing:Bulk frozen blocks and pre-portioned inputs supply ready-meal manufacturing and further processing operations. Industrial buyers in Germany consolidate procurement through cooperative structures.
- Catering Services:Event and contract catering demand consistent portion weights and rapid thaw characteristics.
- Institutional Users:Hospital and school nutrition programs prioritize cost control through USDA commodity programs and cooperative purchasing.
Food processing commands the established base. The steepest expansion runs through households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. US buyers prioritize portion-controlled formats for foodservice outsourcing, while Brazilian procurement centers on export-grade primal cuts for Asian markets. European demand tilts toward premium vacuum-packed retail configurations with carbon-accounting documentation.
United States
Quick-service restaurant chains drive frozen beef and chicken procurement as kitchen labor shortages persist. USDA grading standards and FDA inspection protocols govern safety classification, with commodity programs channeling volume into institutional contracts. Chicago-area cold-chain hubs anchor distribution networks serving hospital and school system buyers through national purchasing cooperatives.
Brazil
Export-oriented processing clusters dominate frozen protein output for Middle Eastern and Asian destinations. ANVISA enforces residue monitoring and cold-chain documentation compliance for international shipments. São Paulo state feedlot-to-port infrastructure supports massive throughput at JBS S.A. and BRF S.A. facilities with integrated traceability systems.
China
Import demand concentrates on frozen pork and beef as domestic production gaps persist. SAMR and GB standards tighten cold-chain documentation requirements, disqualifying non-compliant origins from market access. Shanghai and Tianjin port cold-storage facilities are expanding capacity to handle documentation-heavy import inspection protocols.
Germany
Retail channels absorb premium vacuum-packed configurations with extended shelf stability. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing ammonia and CO2 cascade retrofits across processing networks. Bavarian and North Rhine-Westphalia cold-chain operators are absorbing these retrofit costs earliest, compressing margins across regional networks.
Japan
Convenience-oriented retail formats drive demand for individually quick-frozen portions and pre-portioned meal inputs. METI oversees energy-efficiency standards for commercial freezing equipment under national decarbonization targets. Osaka-Kobe industrial corridors host specialized processors serving domestic retail and limited export channels with strict quality specifications.
Frozen Meat Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in frozen meat supply. The upper tier commands captive supply chains from feedlot through blast-freezing, while mid-scale operators compete on packaging flexibility and regional cold-chain reach. Two archetypes dominate: vertically integrated protein conglomerates with multinational processing footprints, and specialized exporters with concentrated geographic focus. Capacity expansion and traceability technology licensing represent the dominant competitive moves as documentation requirements tighten across import markets.
Within the integrated conglomerate tier, JBS S.A. and BRF S.A. exemplify the Brazilian export-oriented archetype with massive feedlot-to-port infrastructure. Tyson Foods, Inc. occupies a position representing North American foodservice and retail private-label supply. Danish Crown A/S anchors European cooperative structures with premium positioning in vacuum-packed retail channels. These three entities represent distinct geographic and structural approaches to frozen protein supply.
| Leading Market Players |
|---|
| WH Group Limited |
| BRF S.A. |
| JBS S.A. |
| NH Foods Ltd. |
| Danish Crown A/S |
| Tyson Foods, Inc. |
| Marfrig Global Foods S.A. |
| Conagra Brands, Inc. |
| Cargill, Inc. |
| Others |
Supply Flow & Price Mechanics
Blast-freezing capacity utilization at Brazilian and U.S. integrated processors anchors price floors across export and domestic channels, concentrating margin power among feedlot-to-port operators while squeezing mid-scale competitors dependent on third-party cold-chain services.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement through USDA commodity programs and hospital purchasing cooperatives, insulating volume buyers from spot-market volatility in cryogenic nitrogen and electricity inputs. Price differentiation rests on vacuum-pack certification grade and blast-freezing throughput scale, with premium supermarket tiers absorbing higher unit costs through reduced spoilage loss. Cost compression in mid-tier beef and chicken portions is intensifying as automated facilities poach skilled technicians from legacy warehouses. Quick-service restaurant chains demonstrate lowest price sensitivity due to labor-cost arbitrage from outsourced protein prep, while small-scale food processors face acute margin pressure from energy cost volatility.
Supply Chain Analysis
Strategic stockpile preferences concentrate among Brazilian export processors maintaining buffer inventories at São Paulo state feedlot-to-port facilities to satisfy tightened SAMR documentation requirements for Asian shipments. Geographic supply concentration centers on Brazil, the United States, and Germany, with raw material dependencies spanning cattle feedlot capacity, cryogenic nitrogen supply, and barrier film packaging substrates. Single-source vulnerability runs through specialized cold-chain technician labor pools migrating toward automated blast-freezing facilities. Distribution runs through wholesale distributors serving institutional contracts, though direct-to-consumer online channels are bypassing traditional hierarchies fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated blast-freezing technician pools are thinning across legacy warehouse operations, creating a capability bottleneck that favors integrated processors with in-house training pipelines over mid-scale competitors dependent on external labor markets.
For Market Incumbents: Shield margin position by deepening backward integration into captive cattle feedlot operations and ammonia-based refrigeration retrofit capacity ahead of EU F-Gas phase-down deadlines. Prioritize blockchain-traceability certification investment to defend against disqualification risk under tightening Chinese SAMR documentation protocols. For New Entrants and Emerging Players: Differentiate on carbon-accounting compliance services for European retail channels facing CSRD refrigeration energy reporting obligations. Target direct-to-consumer online retail in urban U.S. markets with modular batch-freezing systems and subscription-based portion-controlled offerings, leveraging last-mile cold-chain maturation as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated Brazilian exporters with long-term offtake contracts to Middle Eastern and Asian buyers under multi-jurisdiction certification coverage. Acquisition focus should center on mid-scale processors with underutilized blast-freezing capacity and established traceability infrastructure. Watch for inflection when China's SAMR disqualification thresholds expand to additional origin countries, reshaping export eligibility premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Capacity Expansion | JBS S.A. and BRF S.A. anchor Brazilian export dominance through feedlot-to-port infrastructure scale. |
| Carbon-Accounting Compliance Program | EU CSRD obligations create advisory revenue streams for cold-chain operators with energy monitoring capabilities. |
| Blockchain Traceability Integration | SAMR documentation requirements in China reward processors with feedlot-to-retail verification systems. |
| Ammonia Refrigeration Retrofit | German and French operators absorb EU F-Gas phase-down costs earliest, compressing regional network margins. |
| Direct-to-Consumer Channel Launch | U.S. meal-kit assemblers deploy specialized frozen last-mile fleets bypassing wholesale distributor hierarchies. |
Methodological Framework
Operator-level perspectives from blast-freezing facility managers, cold-chain logistics directors, USDA commodity program procurement officers, and quick-service restaurant supply chain executives anchored the qualitative base for this analysis. Primary interview data triangulated against secondary sources including FDA inspection records, EFSA residue monitoring reports, Chinese SAMR import documentation databases, and Brazilian ANVISA cold-chain compliance filings. Bottom-up capacity and throughput estimates from processing facilities converged with top-down trade flow analysis across the projection horizon.
Sensitivity analysis tested demand elasticity under scenarios of energy cost volatility and technician labor scarcity across protein type, packaging configuration, distribution channel, and end-user application dimensions. CAGRs derived from volume-throughput modeling at integrated processing clusters and export-oriented facilities, incorporating blast-freezing technology adoption curves and modified atmosphere packaging penetration rates as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment and stable multi-jurisdiction certification timelines would require recalibration. Forecasts reflect documented assumptions regarding labor migration patterns and regulatory enforcement intensity. Revision becomes warranted when Chinese SAMR disqualification thresholds or EU F-Gas retrofit cost absorption rates cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Taiyaki Ice Cream Market