
 GCC Frozen Finger Chips Market | 2026-2036
GCC Frozen Finger Chips Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Frozen Finger Chips Market Intelligence
Expatriate culinary talent in commercial kitchens is rotating toward standardized, pre-processed inputs that reduce prep time and variance. McCain Foods leverages its regional production footprint to supply consistent product specs across Gulf markets. Lamb Weston sustains competitive tension through its frozen potato specialization and food service channel depth. Farm Frites anchors its position with European sourcing credentials that resonate with premium hotel and restaurant buyers in the UAE.
Frozen finger chips are par-fried potato strips, typically blanched and quick-frozen at minus 18 degrees Celsius, designed for finish-frying or baking without raw potato handling. The product eliminates peel-waste variability and oil-absorption inconsistency that plague fresh-cut operations in high-volume kitchens. Plain product type dominates volume as institutional buyers prioritize cost predictability and menu neutrality across diverse customer bases. Food service sales channel captures the dominant margin pool, while online retail is expanding fastest among urban households in Saudi Arabia and Qatar seeking convenience formats.
Saudi Food and Drug Authority cold-chain mandates and UAE Ministry of Climate Change and Environment import standards shape product entry requirements and storage infrastructure investment across the Gulf. GCC-wide technical regulations for frozen vegetables, aligned with Gulf Standardization Organization benchmarks, enforce labeling, temperature logging, and shelf-life transparency that filter out informal suppliers. Stakeholders must monitor evolving halal certification integration with frozen potato traceability protocols as consumer scrutiny intensifies.
Market Dynamics
Quick-service restaurant chains across Saudi Arabia and the UAE are accelerating frozen finger chip procurement as labor costs for fresh-cut operations climb and cold-chain compliance mandates tighten under SFDA and MOCCAE oversight.
Growth Catalysts
- SFDA Cold-Chain Mandates:Saudi Food and Drug Authority enforcement of temperature-logging requirements is filtering out informal suppliers and consolidating procurement toward certified frozen distributors with compliant storage infrastructure.
- Quick-Service Restaurant Expansion:Burger and fried-chicken franchise networks in Dubai, Riyadh, and Dammam are standardizing menus around par-fried potato inputs that eliminate peel-waste variability and oil-absorption inconsistency.
- Expatriate Chef Talent Rotation:Commercial kitchens across the Gulf are replacing fresh-cut stations with pre-processed frozen inputs to reduce prep time and variance in high-volume operations.
Market Restraints
- European Sourcing Concentration:Premium hotel and restaurant buyers in the UAE depend heavily on European import credentials, creating exposure to freight cost volatility and currency fluctuation.
- Fresh-Cut Substitution in Local Cuisine:Traditional Arabic kitchens and independent restaurants in smaller GCC markets continue favoring fresh potato handling for texture and authenticity perception.
- Import Tariff Friction:UAE Ministry of Climate Change and Environment standards and Saudi customs protocols impose documentation burdens that delay container clearance during peak demand periods.
Strategic Opportunities
- Qatar Online Retail Channel:Urban households in Doha are expanding fastest among convenience-seeking segments for frozen potato home-delivery formats.
- Halal Traceability Integration:Evolving consumer scrutiny is creating white space for suppliers who embed halal certification protocols directly into frozen potato batch documentation.
- Air-Fryer Compatibility Formulation:Equipment manufacturers and food service buyers are converging on par-fried strips engineered for finish-baking without deep-frying infrastructure.
Industry Challenges
- Cold-Chain Capex Intensity:Distributors must invest in minus 18 degrees Celsius storage and transport fleets to meet Gulf Standardization Organization benchmarks for frozen vegetable handling.
- Labeling Compliance Timelines:Gulf Standardization Organization shelf-life transparency and temperature-logging requirements demand systems integration that smaller logistics operators struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Frozen Finger Chips Market |
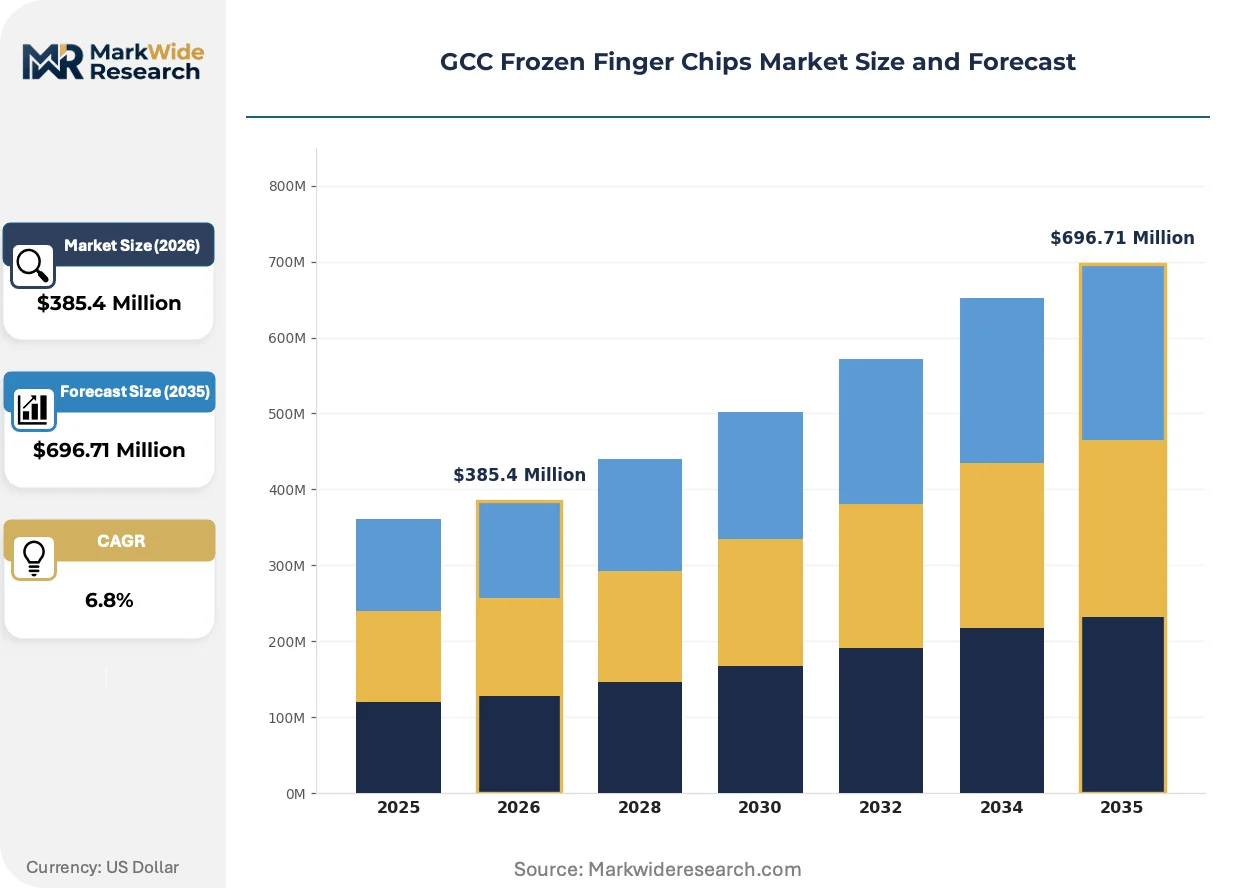
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Spicy, Cheese, Barbecue Packaging Type: Bags, Boxes, Bulk, Pouches Sales Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | McCain Foods, Lamb Weston, J.R. Simplot, Aviko, Farm Frites, Cavendish Farms, Agristo, Kraft Heinz, Simplot Foods, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Frozen Finger Chips Market Strategic Shifts & Innovations
Standardization pressures from food service buyers are compressing product variance and reshaping supplier capability requirements across the Gulf frozen potato value chain.
Air-fryer optimized par-fried formulations are fragmenting traditional deep-fry equipment dependencies in commercial kitchens. Burger chains in Saudi Arabia are piloting these strips to reduce oil waste and ventilation infrastructure costs. The technology is fragmenting finish-cooking method standardization that previously unified kitchen equipment procurement across franchise networks.
SFDA and MOCCAE are tightening import documentation and cold-chain verification protocols for frozen vegetables. These mandates are forcing distributors to deploy real-time temperature monitoring systems from port to point-of-sale. Food service channels in Dubai and Riyadh are absorbing compliance costs fastest, while smaller retail operators lag in infrastructure investment.
Urban households in Saudi Arabia and Qatar are rotating toward direct-to-door frozen potato procurement through e-grocery platforms. This channel is displacing traditional supermarket freezer-aisle purchasing among dual-income expatriate families. The shift is most visible in Dammam and Doha, where delivery app penetration in food categories exceeds broader GCC averages.
GCC Frozen Finger Chips Market Segmentation
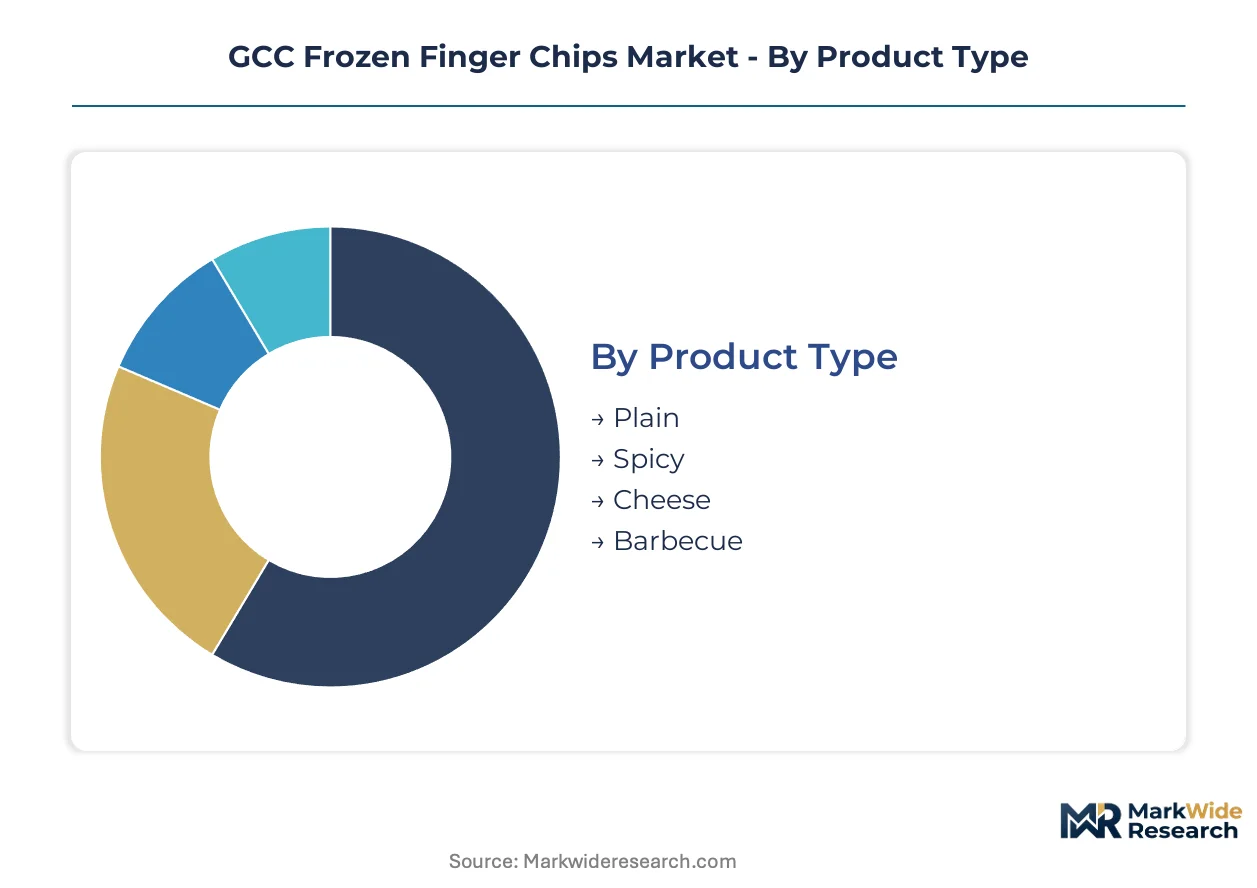
Frozen finger chip segmentation in the GCC reveals divergent pressure points across product formulations and channel economics. Plain variants face fresh-cut substitution in traditional kitchens, while flavored formats compete against snack category alternatives. Packaging and channel choices reflect the tension between food service scale efficiency and retail convenience seeking.
Product Type:
Substitution pressure varies sharply across flavor profiles, with unseasoned formats most vulnerable to fresh potato handling in independent restaurants.
- Plain:Unseasoned par-fried strips prioritize oil-absorption consistency and menu neutrality for high-volume kitchens. Demand concentrates in Dubai and Riyadh quick-service chains where labor cost escalation and SFDA cold-chain mandates eliminate fresh-cut stations.
- Spicy:Chili-coated formulations target regional palate preferences in Saudi Arabia and Bahrain. Growth is accelerating among younger consumers in Dammam and Manama seeking bold flavor differentiation from standard offerings.
- Cheese:Cheddar-dusted variants serve snack occasion expansion in cinema and entertainment venues across Doha and Abu Dhabi.
- Barbecue:Smoked-flavor coatings align with American-style burger chain menu standardization in Kuwait City and Jeddah.
Plain retains volume leadership; Spicy holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates institutional procurement from premium retail convenience formats in urban Gulf markets.
- Bulk:Industrial totes and food service sacks deliver par-fried strips at lowest unit cost for franchise networks. Procurement concentrates in Jeddah and Dubai central kitchens where volume scale justifies dedicated cold-chain logistics.
- Bags:Consumer-facing polyethylene sacks dominate Saudi supermarket freezer aisles. Demand is climbing fastest among Riyadh households seeking portion-controlled convenience without premium pricing.
- Boxes:Rigid cardboard cases protect product integrity in ambient retail environments with inconsistent cold-chain handling.
- Pouches:Stand-up flexible packaging targets premium positioning in Qatar and UAE hypermarkets.
Bulk commands institutional procurement volume; Bags are gaining share fastest in retail channel expansion.
Sales Channel:
Application concentration determines margin capture, with direct food service relationships yielding superior pricing power against fragmented retail.
- Food Service:Direct supply to restaurant chains and institutional kitchens generates the dominant margin pool. Concentration centers on Dubai, Riyadh, and Dammam burger and fried-chicken franchise networks standardizing around par-fried inputs.
- Online Retail:E-grocery platforms and delivery apps are expanding most quickly among Doha and Riyadh dual-income households. Urban convenience seeking displaces traditional supermarket purchasing in Saudi Arabia and Qatar.
- Supermarkets:Hypermarket freezer aisles retain volume in Kuwait and Bahrain where delivery infrastructure lags.
- Convenience Stores:Small-format retail captures impulse and fill-in purchases in high-traffic locations.
Food Service retains volume leadership; Online Retail holds the steepest expansion curve.
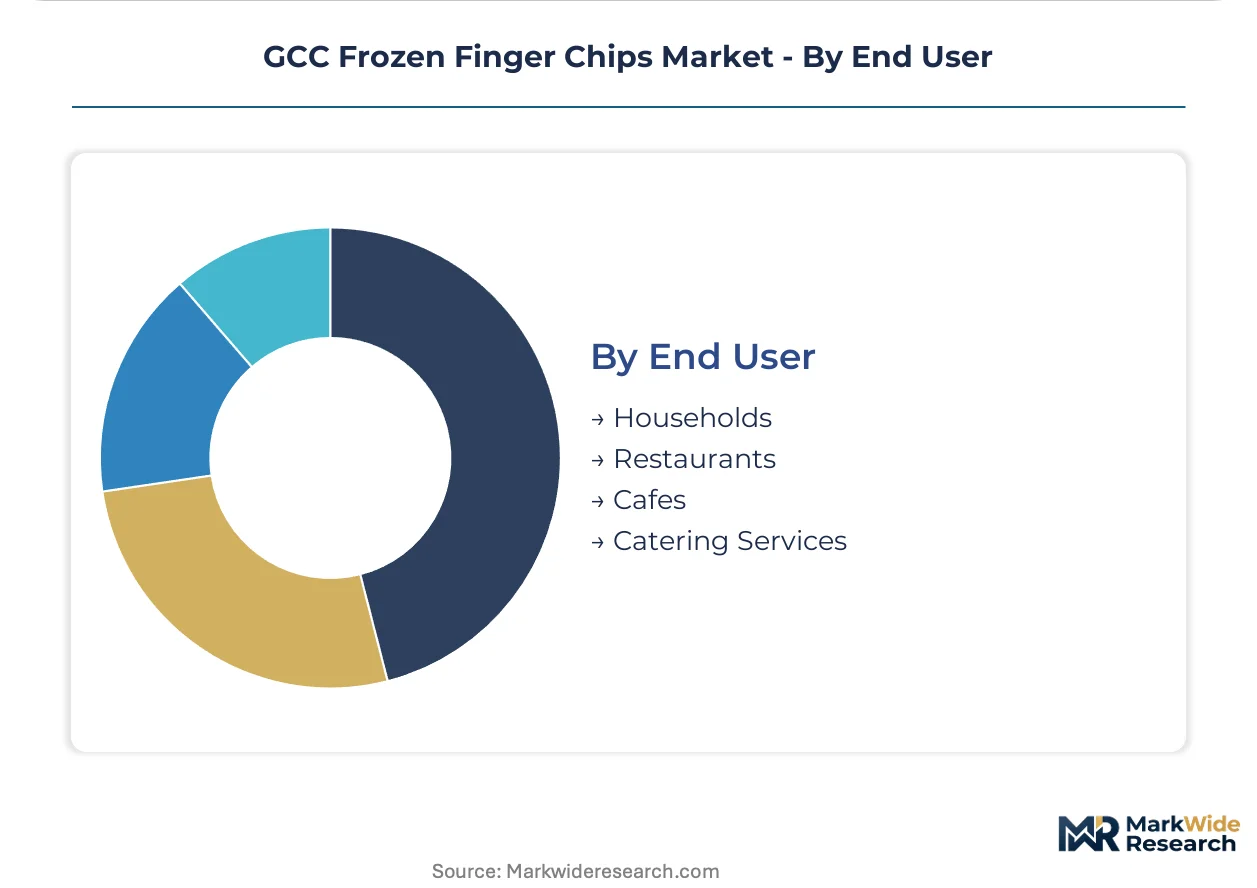
End User:
Customer type maturity separates established commercial demand from emerging household convenience adoption across Gulf markets.
- Restaurants:Quick-service and casual dining chains anchor commercial demand with standardized par-fried procurement. Concentration in Saudi Arabia and UAE franchise networks drives volume scale.
- Households:Urban families in Qatar and Saudi Arabia are rotating fastest toward frozen potato home consumption. E-grocery penetration and air-fryer ownership accelerate substitution of fresh potato handling.
- Cafes:Coffee shop chains and independent beverage outlets in Dubai and Manama add finger chips as snack accompaniments.
- Catering Services:Event and institutional catering in Kuwait and Bahrain sources frozen formats for consistency at volume.
Restaurants retain volume leadership; Households hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and the UAE diverge sharply in frozen finger chip consumption patterns. Saudi kitchens favor bulk institutional procurement for quick-service franchise networks, while UAE buyers split demand between premium hotel sourcing and food service standardization. Qatar and Kuwait exhibit nascent retail channel acceleration absent in the larger markets.
Saudi Arabia
Quick-service restaurant chains in Riyadh and Jeddah drive bulk procurement of plain par-fried strips for standardized menu execution. The Saudi Food and Drug Authority enforces temperature-logging mandates that filter informal distributors from the cold-chain network. Eastern Province central kitchens in Dammam are consolidating frozen potato sourcing under compliant logistics operators.
United Arab Emirates
Dubai hotel and restaurant buyers demand European-sourced credentials for premium positioning alongside food service volume contracts. The Ministry of Climate Change and Environment imposes import documentation standards that delay container clearance during peak demand windows. Abu Dhabi catering operations are adopting frozen formats for event consistency at volume scale.
Qatar
Urban households in Doha are rotating fastest toward e-grocery frozen potato procurement among dual-income expatriate families. The Ministry of Public Health aligns import standards with Gulf Standardization Organization benchmarks for frozen vegetable traceability. Retail channel expansion concentrates in Doha metro delivery zones where app penetration exceeds regional averages.
Kuwait
American-style burger chains in Kuwait City standardize menus around barbecue-flavored par-fried inputs for palate differentiation. National import protocols enforce halal certification integration with batch documentation requirements. Supermarket freezer aisles retain volume leadership as delivery infrastructure lags behind Saudi and Qatari urban centers.
Bahrain
Spicy-coated formulations target younger consumers in Manama seeking flavor differentiation from standard quick-service offerings. The national food regulator applies Gulf Standardization Organization shelf-life transparency rules that demand systems investment from smaller distributors. Cinema and entertainment venues in the capital are expanding snack occasion procurement of cheese-dusted variants.
GCC Frozen Finger Chips Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale-driven multinationals commanding food service relationships while regional specialists capture premium retail positioning. The market structure rewards backward integration into raw potato supply and cold-chain infrastructure ownership. Two archetypes dominate: vertically integrated processors with Gulf production footprints, and import-dependent specialists leveraging European sourcing credentials. Competitive moves center on halal certification protocol integration and air-fryer formulation development.
Within the integrated processor tier, McCain Foods and Lamb Weston anchor positions through regional manufacturing scale and food service channel depth. Farm Frites occupies a specialist position, representing the European-import credential archetype that resonates with premium UAE hotel and restaurant buyers. These three exemplify the strategic tension between localized production efficiency and transcontinental sourcing prestige that defines competitive positioning across Gulf markets.
| Leading Market Players |
|---|
| McCain Foods |
| Lamb Weston |
| J.R. Simplot |
| Aviko |
| Farm Frites |
| Cavendish Farms |
| Agristo |
| Kraft Heinz |
| Simplot Foods |
| Others |
Cost & Logistics Intelligence
Forty-five to sixty-day ocean freight lead times from European processing plants to Jeddah and Dubai cold-storage facilities concentrate pricing power with distributors owning compliant minus 18 degrees Celsius warehousing. This inventory-to-delivery interval shapes contract structures and exposes buyers to freight cost volatility during peak QSR procurement windows.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement, locking plain par-fried strip volumes for Riyadh and Dubai quick-service chains at fixed unit rates across annual cycles. Price differentiation rests on halal certification tier and cold-chain compliance documentation grade, with SFDA-certified distributors commanding premiums over informal suppliers. Pricing pressure stems from European freight rate volatility and currency fluctuation against Gulf currencies. Quick-service franchise networks exhibit lowest price sensitivity due to menu standardization requirements, while independent restaurants in smaller Bahrain and Kuwait markets negotiate aggressively on spot purchases.
Supply Chain Analysis
Inventory cycles stretching sixty to ninety days from Dutch and Belgian processing plants through Rotterdam port consolidation create working capital intensity for Gulf distributors. Supply concentrates in the Netherlands, Belgium, and Germany for premium European-credentialed product, while Saudi Arabia and the UAE anchor regional re-export and central kitchen consolidation. Raw material dependencies include seed potato varieties, frying oil formulations, and blast-freezing equipment components. Single-source vulnerability runs through Rotterdam-Jeddah container lanes during peak demand periods. Distribution runs through integrated cold-chain operators with captive warehousing in Dammam, Dubai, and Doha.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where SFDA and MOCCAE cold-chain certification requirements create switching costs that lock food service buyers into compliant supplier relationships.
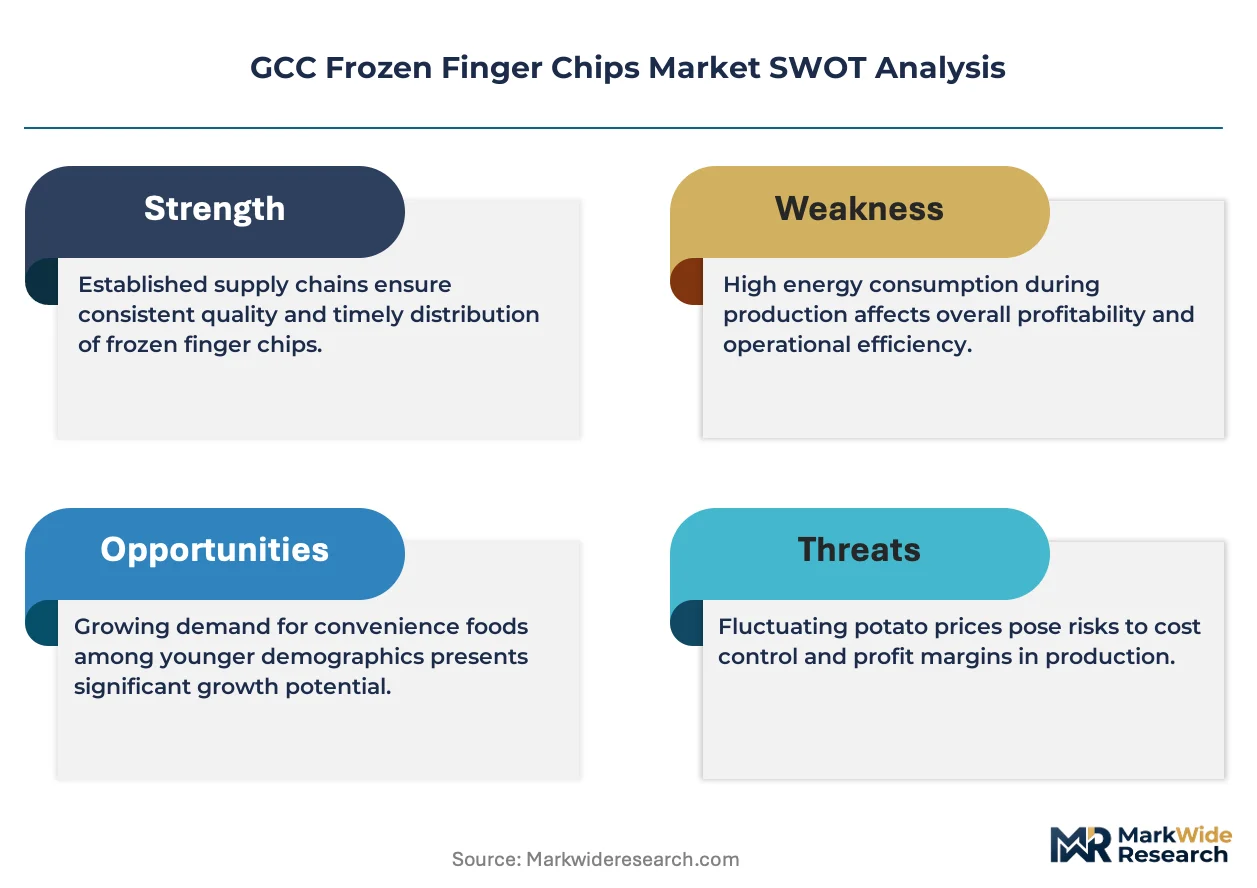
For Market Incumbents: Secure halal traceability protocol integration ahead of evolving Saudi Food and Drug Authority batch-documentation mandates. Deepen backward integration into captive cold-chain fleets across Eastern Province and Northern Emirates to defend margin position against freight cost volatility. Lock multi-year offtake contracts with Dubai and Riyadh franchise networks before air-fryer formulation standards fragment procurement specifications. For New Entrants and Emerging Players: E-grocery platform direct-supply gaps in Doha and Dammam offer white-space entry points where incumbent distributors under-serve dual-income household convenience demand. Target Qatar online retail channel expansion with stand-up pouch formats optimized for home-delivery logistics. Pursue air-fryer compatibility certification as a differentiated go-to-market angle for premium urban household positioning. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cold-chain capex intensity and regulatory compliance burdens favor scaled operators with Gulf production or warehousing footprints. Acquisition targets should display integrated minus 18 degrees Celsius logistics ownership and established SFDA certification relationships. Watch for air-fryer formulation standardization across Saudi burger chains as an inflection signal for equipment-agnostic product displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Traceability Integration | SFDA batch-documentation mandates favor suppliers embedding certification into frozen potato supply chains. |
| Air-Fryer Formulation Development | Finish-baking compatibility reduces oil-waste costs for Saudi burger chains piloting alternative cooking methods. |
| Cold-Chain Infrastructure Expansion | Minus 18 degrees Celsius warehousing ownership in Dammam and Dubai locks in compliant distributor positioning. |
| Long-Term Food Service Contracts | Annual offtake agreements with Riyadh franchise networks secure volume against spot-market volatility. |
| Online Retail Channel Penetration | E-grocery platform partnerships in Doha capture fastest-expanding household convenience segment. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with frozen potato procurement managers, QSR supply chain directors, and cold-chain logistics operators across Saudi Arabia, the UAE, and Qatar; and secondary validation through customs trade records, Gulf Standardization Organization regulatory filings, and food service distributor financial disclosures. Bottom-up channel volume estimates triangulated against top-down market sizing from import documentation and central kitchen capacity assessments.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product flavor profile, packaging format tier, sales channel type, and end-user application. CAGRs derived from trend extrapolation of food service procurement patterns and household adoption curves, cross-referenced against QSR expansion announcements and e-grocery platform growth metrics. Air-fryer penetration rates and halal certification integration timelines served as industry-specific forecast modifiers.
Underlying assumptions cover stable SFDA and MOCCAE regulatory enforcement trajectories, with deviation risk concentrated in import tariff friction and European sourcing cost volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
South America RTE Food Market