
 United Arab Emirates Frozen Food Market | 2026-2036
United Arab Emirates Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Frozen Food Market Analytics
Asset-light leasing models for blast-freezing equipment are rewriting competitive entry barriers across the UAE frozen food landscape. Al Kabeer Group leverages its captive poultry supply chain to sustain margin control in frozen meat categories. Lulu Group International anchors volume through hypermarket dominance and private-label frozen lines. Tanmiah Food Company differentiates via halal-certified processing standards that resonate with Gulf consumer expectations.
Frozen food encompasses products preserved at temperatures below minus eighteen degrees Celsius through rapid blast freezing, a process that arrests microbial activity and maintains nutritional integrity for extended shelf life. The category serves commercial kitchens and retail households requiring consistent ingredient availability without cold-room infrastructure. Frozen ready meals command premium positioning among UAE food service providers seeking labor-cost reduction, while frozen seafood competes on import-source traceability. Supermarkets and hypermarkets occupy the dominant channel position, though online retail is capturing share among younger demographics in Dubai and Sharjah.
MOHAP enforces cold-chain compliance through mandatory HACCP documentation and temperature-logging requirements that elevate operational costs for smaller distributors. FSSAI-aligned import standards for cross-border frozen shipments from India and Pakistan add inspection-layer complexity at UAE ports. Stakeholders must monitor how Dubai Municipality's evolving food safety digitization mandates reshape traceability investments and supplier qualification timelines.
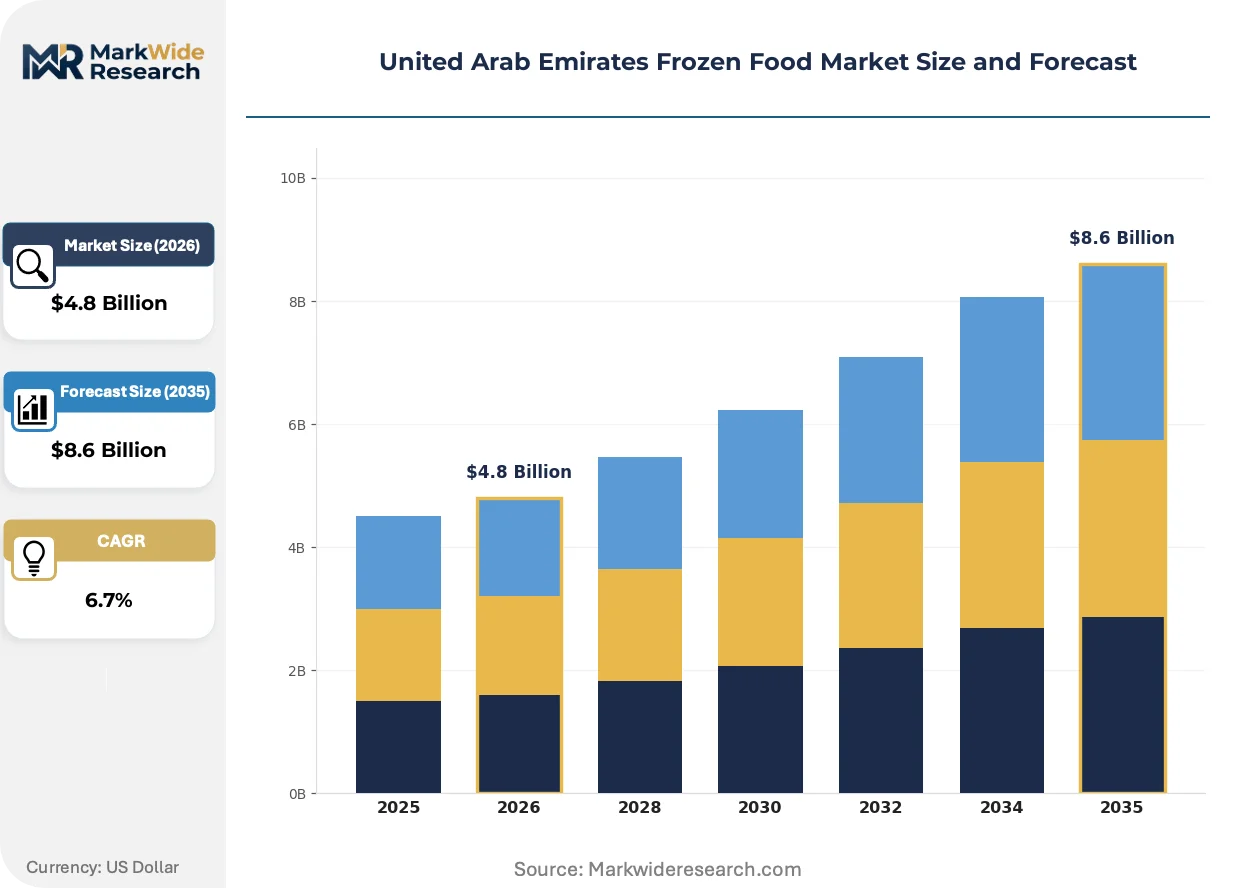
Market Dynamics
MOHAP's digitized cold-chain mandates are forcing distributors across Dubai and Sharjah to replace manual temperature logs with IoT-enabled traceability infrastructure, compressing margins for smaller operators while advantaging scaled logistics providers.
Growth Catalysts
- Centralized Kitchen Expansion:Quick-service restaurant chains in Dubai's food service corridor are consolidating procurement through bulk frozen purchases, creating volume pull for blast-frozen ready meals and processed proteins.
- FSSAI-Aligned Import Standards:Cross-border frozen shipments from India and Pakistan now flow through streamlined inspection protocols at UAE ports, reducing dwell time for seafood and poultry consignments.
- Halal Certification Premium:Gulf consumer expectations for halal-certified processing are driving food service buyers to prioritize suppliers with captive slaughterhouse-to-freezer traceability.
Market Restraints
- Blast-Freezing Equipment Costs:Asset-heavy ownership of cryogenic tunnel freezers requires capital deployment that locks out mid-tier processors from margin-competitive categories.
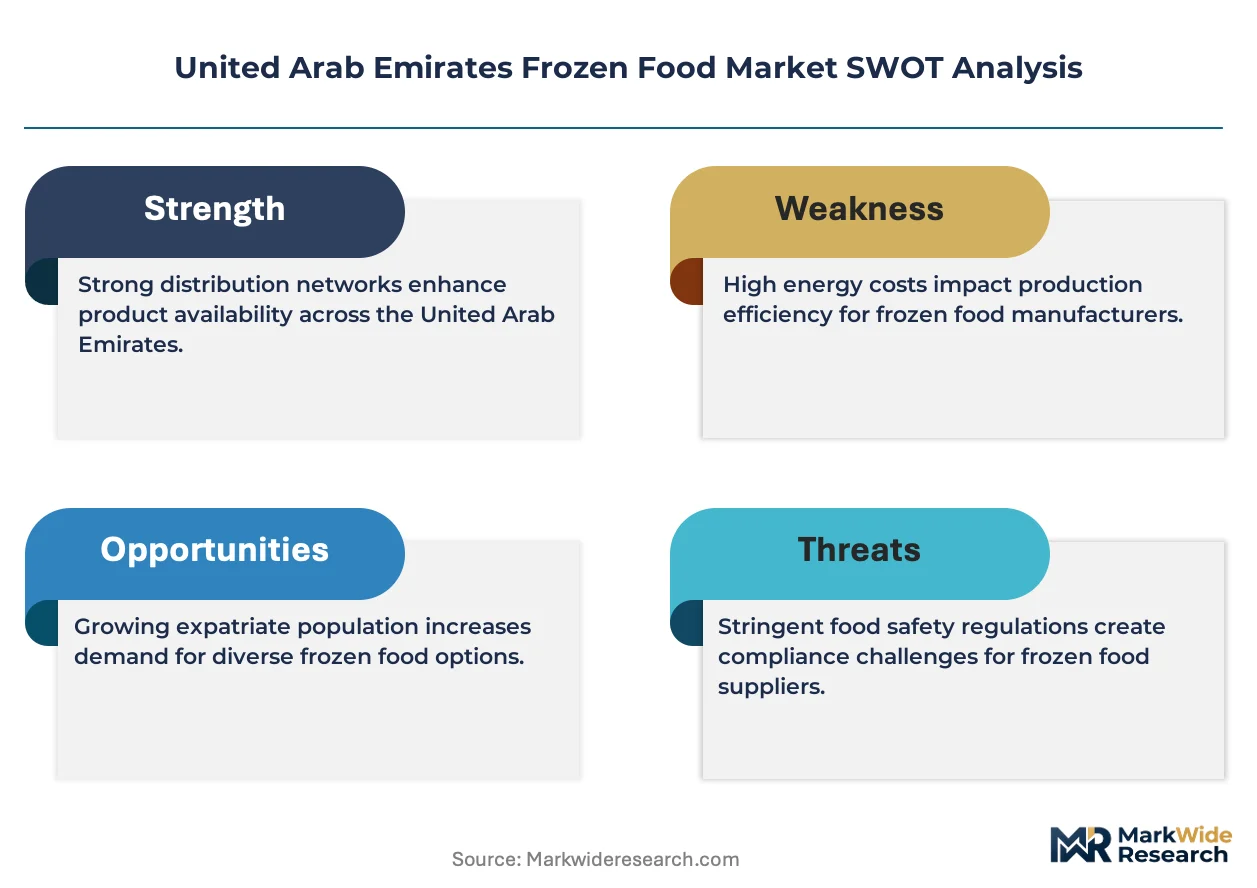
- Energy Price Volatility:Cold storage operations across the Emirates face input cost pressure from fluctuating electricity tariffs, particularly affecting multi-temperature zone facilities.
- Import Dependency Concentration:Frozen seafood and red meat categories rely on narrow sourcing corridors from South Asia and South America, exposing buyers to shipping lane disruptions.
Strategic Opportunities
- Asset-Light Leasing Models:Third-party blast-freezing equipment rentals are lowering entry barriers for new processors in Abu Dhabi's Khalifa Industrial Zone.
- Private-Label Hypermarket Penetration:Retail chains are expanding captive frozen lines, creating white space for contract manufacturers with HACCP-compliant facilities.
- Online Retail Channel Development:Younger demographics in Sharjah are adopting direct-to-consumer frozen delivery, bypassing traditional supermarket intermediaries.
Industry Challenges
- HACCP Documentation Burden:MOHAP's mandatory hazard analysis requirements demand dedicated compliance personnel that strain smaller distributor headcounts.
- Legacy System Integration:Temperature-logging digitization mandates clash with existing ERP infrastructure at family-owned cold storage operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Frozen Food Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Meat, Frozen Seafood, Frozen Ready Meals Distribution Channel: Supermarkets, Hypermarkets, Online Retail, Convenience Stores End User: Households, Restaurants, Cafes, Food Service Providers Packaging Type: Bags, Boxes, Trays, Vacuum Packs |
| Companies Covered | Lulu Group International, Al Areesh Foods, Al Islami Foods, Khazan Meat Factory, Emirates Snack Foods LLC, IFFCO Group, Tanmiah Food Company, HK Food Group, Al Kabeer Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Frozen Food Market Evolving Landscape
Traceability technology and procurement digitization are compressing supplier qualification timelines while fragmenting channel power away from traditional hypermarket gatekeepers toward direct food service relationships.
Blockchain-enabled provenance tracking is hybridizing with existing cold-chain monitoring systems. Hotel procurement departments in Dubai are piloting distributed ledger verification for frozen seafood origin claims. This convergence is hybridizing supplier selection criteria, compressing qualification cycles from months to weeks while raising IT infrastructure requirements.
MOHAP's phased implementation of digitized food safety mandates is reshaping operational compliance. Distributors must now maintain real-time temperature dashboards accessible to inspectors. Frozen ready meal importers face the steepest adaptation costs as they reconfigure documentation workflows ahead of enforcement deadlines.
Centralized kitchen procurement teams are consolidating supplier rosters into preferred-vendor agreements with volume-commitment clauses. This concentration is displacing spot-market purchasing among mid-size restaurant groups in Abu Dhabi. Procurement leverage is shifting toward operators with multi-outlet footprints capable of guaranteeing minimum order thresholds.
United Arab Emirates Frozen Food Market Segmentation
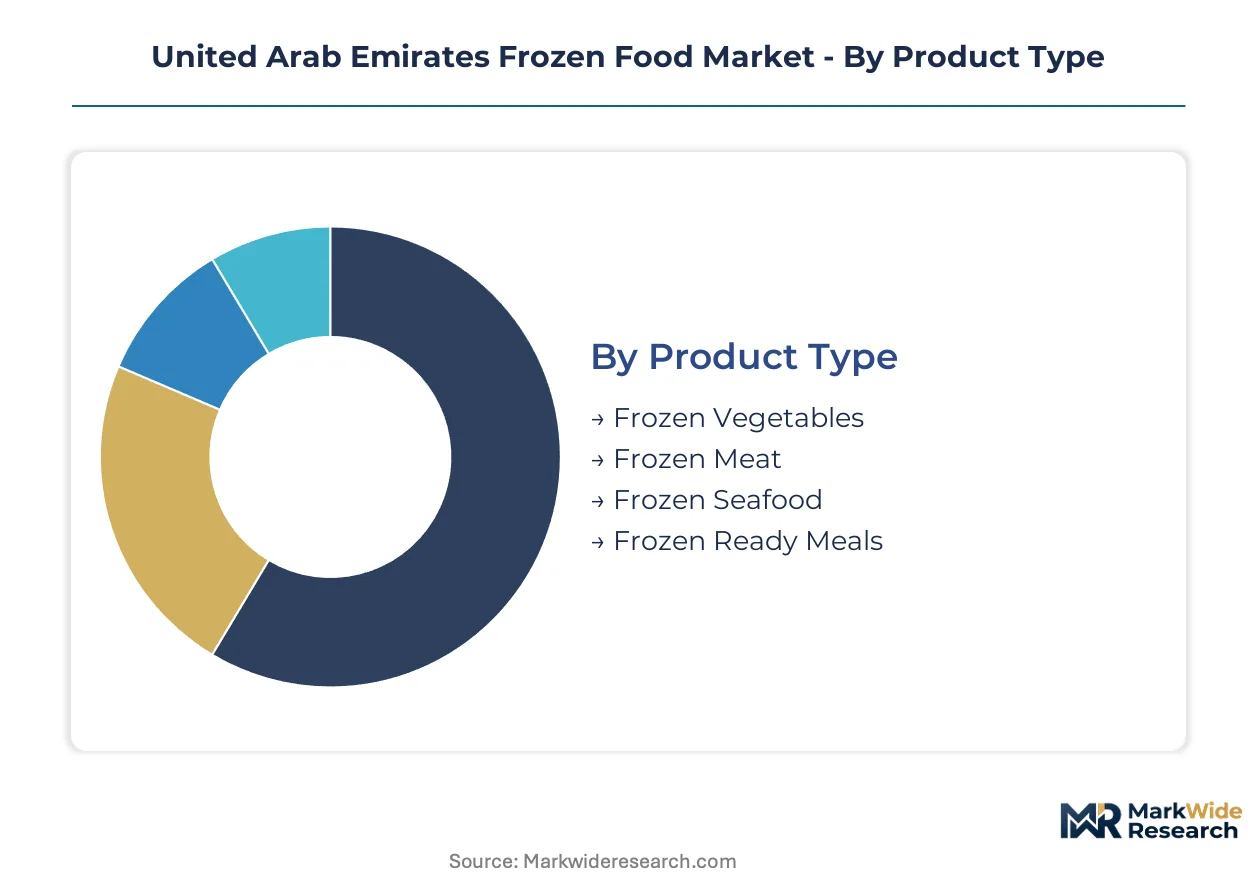
Frozen food segmentation in the UAE reflects divergent cold-chain requirements across product categories and channel formats. Each dimension carries distinct margin profiles and compliance burdens that shape supplier positioning.
Product Type:
After-sales service intensity varies sharply across frozen categories, with ready meals demanding technical support for blast-freezing equipment and seafood requiring traceability documentation services.
- Frozen Vegetables:IQF-processed produce maintains cellular structure through rapid individual quick freezing, preserving texture for rethermalization. Demand concentrates in Dubai's centralized kitchen facilities where labor-cost reduction drives bulk procurement of pre-cut vegetable blends.
- Frozen Meat:Blast-frozen poultry and red meat products retain protein integrity through cryogenic tunnel processing at minus forty degrees Celsius. Abu Dhabi's hotel procurement departments favor captive-slaughterhouse supply chains with halal certification documentation.
- Frozen Seafood:Flash-frozen catch from South Asian and South American corridors competes on port-of-origin traceability.
- Frozen Ready Meals:Complete meal solutions target food service operators seeking menu standardization without kitchen infrastructure.
Frozen meat holds the largest share; momentum sits with frozen ready meals.
Distribution Channel:
Channel economics fragment across format types, with hypermarkets capturing volume through private-label programs and online retail climbing fastest among younger demographics in Sharjah.
- Supermarkets:Neighborhood-format stores stock curated frozen assortments for household replenishment shopping, typically carrying three to five stock-keeping units per category.
- Hypermarkets:Large-format retail anchors volume through dedicated frozen aisles with multi-temperature zone displays and captive private-label lines manufactured under contract.
- Online Retail:Direct-to-consumer frozen delivery platforms bypass traditional intermediaries, requiring specialized last-mile cold packaging and same-day fulfillment infrastructure.
- Convenience Stores:Small-footprint urban outlets carry impulse-oriented frozen snacks and single-serve meals for immediate consumption.
Hypermarkets dominate volume capture; online retail shows steepest expansion trajectory.
End User:
Customer type determines procurement scale and specification rigor, with food service providers imposing the most stringent HACCP documentation requirements.
- Households:Retail consumers purchase frozen products for home meal preparation, prioritizing convenience and extended shelf stability over premium positioning.
- Restaurants:Full-service dining establishments source frozen proteins and prepared components to manage ingredient consistency across menu cycles.
- Cafes:Limited-service beverage-focused outlets require frozen bakery items and pre-portioned dessert components for rapid assembly.
- Food Service Providers:Institutional caterers and centralized kitchen operators consolidate procurement through volume-commitment agreements with blast-freezing suppliers.
Food service providers command the largest procurement volumes; restaurants represent the most fragmented customer base.
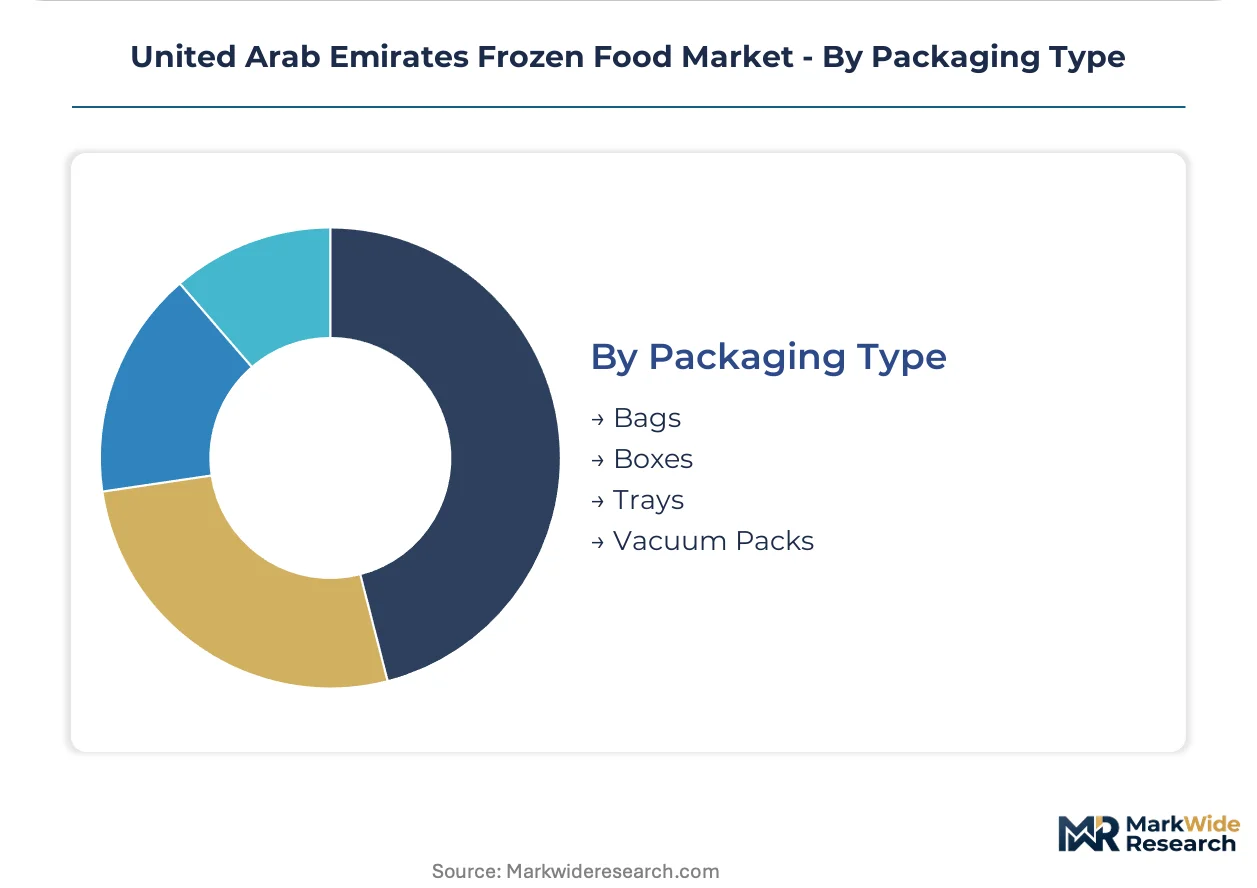
Packaging Type:
Packaging format selection balances barrier properties against disposal regulations, with vacuum packs commanding premium positioning for oxygen-sensitive categories.
- Bags:Flexible polyethylene pouches serve commodity frozen vegetables and breaded proteins with cost-efficient material usage.
- Boxes:Rigid paperboard cartons protect fragile frozen items such as pastries and ice cream through structural stacking strength.
- Trays:Thermoformed plastic containers with lidding films present ready meals for microwave or oven rethermalization.
- Vacuum Packs:Barrier film systems evacuate oxygen to extend color retention in frozen seafood and premium meat cuts.
Bags capture the highest unit volumes; vacuum packs gain share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE's frozen food trade flows reflect a structural import dependency, with domestic blast-freezing capacity concentrated in coastal processing zones while re-export volumes to GCC neighbors amplify Dubai's logistics hub function.
Dubai
Jebel Ali Port handles the majority of frozen seafood and poultry consignments entering the Emirates, with centralized kitchen operators in Dubai's food service corridor driving bulk procurement of blast-frozen ready meals. MOHAP's digitized cold-chain mandates require real-time temperature dashboards for all distributors operating within the emirate. Dubai Industrial City hosts the densest concentration of private-label contract manufacturers serving hypermarket retail chains.
Abu Dhabi
Khalifa Industrial Zone is attracting asset-light blast-freezing equipment leasing models that lower entry barriers for new processors. The emirate's hotel procurement departments favor captive-slaughterhouse supply chains with halal certification documentation. Abu Dhabi Agriculture and Food Safety Authority enforces inspection protocols that align with federal MOHAP standards while adding emirate-specific traceability requirements.
Sharjah
Younger demographics in Sharjah are adopting direct-to-consumer frozen delivery platforms, bypassing traditional supermarket intermediaries and driving last-mile cold packaging innovation. The emirate's smaller cold storage operators face margin compression from energy price volatility affecting multi-temperature zone facilities. Sharjah's Hamriyah Free Zone offers tariff advantages for re-export of frozen seafood to South Asian markets.
Northern Emirates
Ras Al Khaimah and Fujairah are developing specialized cold storage infrastructure to capture transshipment volumes from South Asian and South American sourcing corridors. These emirates benefit from lower land costs for cryogenic tunnel freezer deployment compared to Dubai and Abu Dhabi. Federal MOHAP enforcement teams conduct randomized HACCP documentation audits across Northern Emirates distribution facilities.
United Arab Emirates Frozen Food Market Competitive Landscape
On the supply side, the industry is tiered between integrated processors with captive supply chains and asset-light distributors dependent on third-party cold storage. Consolidation pressures favor scaled logistics providers capable of absorbing IoT-enabled traceability investments. Three archetypes dominate: poultry-integrated processors, hypermarket-anchored private-label manufacturers, and halal-certified specialists. Competitive moves center on preferred-vendor agreements with volume-commitment clauses and backward integration into slaughterhouse operations.
Within the integrated processor tier, Al Kabeer Group and Tanmiah Food Company exemplify archetypes combining captive poultry supply with halal-certified processing standards. Lulu Group International anchors the retail-channel vector through hypermarket dominance and private-label frozen lines. Among regional distributors, Al Areesh Foods and Al Islami Foods occupy positions emphasizing frozen meat and ethnic product specialization.
| Leading Market Players |
|---|
| Lulu Group International |
| Al Areesh Foods |
| Al Islami Foods |
| Khazan Meat Factory |
| Emirates Snack Foods LLC |
| IFFCO Group |
| Tanmiah Food Company |
| HK Food Group |
| Al Kabeer Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Dubai Industrial City's blast-freezing facilities is compressing spot-market margins while forcing contract manufacturers toward volume-commitment pricing. This utilization dynamic rewards scaled operators with preferred-vendor status and squeezes mid-tier processors into asset-light leasing arrangements.
Pricing Analysis
Food service providers anchor contract-based long-term offtake structures that lock in quarterly volume floors against price volatility. Three-tier pricing structure across premium, standard, and economy levels separates halal-certified captive-slaughterhouse supply from commodity import tiers and private-label contract manufacturing. Cost compression in economy-tier frozen vegetables is intensifying because of energy tariff fluctuations affecting multi-temperature zone facilities. Centralized kitchen operators show the least price sensitivity due to labor-cost substitution value, while small independent restaurants face acute margin pressure.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Al Kabeer Group, Tanmiah Food Company, and Lulu Group International's private-label facilities across the Emirates. Geographic supply draws from India, Pakistan, and Brazil for poultry and red meat, with South Asian corridors dominating seafood imports. Raw material dependencies rest on blast-freezing equipment components, specialized cold-chain packaging, and halal certification documentation services. Single-source vulnerability runs through Jebel Ali Port's frozen cargo handling infrastructure. Distribution feeds from processor direct-to-hypermarket arrangements supplemented by third-party cold storage operators serving fragmented food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE frozen food sector is recovering from pandemic-era inventory destocking as hotel procurement departments normalize pre-paid volume commitments. This cyclical upswing tracks hospitality occupancy rates across Dubai and Abu Dhabi.
For Market Incumbents: Insulate margin position through backward integration into captive poultry slaughterhouse operations that secure halal certification traceability. Expand IoT-enabled temperature monitoring infrastructure ahead of MOHAP enforcement deadlines to disqualify smaller competitors from preferred-vendor rosters. Asset-light leasing models for blast-freezing equipment represent the priority defensive lever against capital-constrained entrants.
For New Entrants and Emerging Players: Mid-market restaurant groups in Sharjah's emerging food service corridor represent the most penetrable entry point given their displacement from spot-market purchasing by centralized kitchen consolidation. Direct-to-consumer frozen delivery platforms targeting younger demographics bypass entrenched hypermarket gatekeepers. A go-to-market angle anchored on same-day fulfillment infrastructure with specialized last-mile cold packaging captures channel-switching momentum.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across contract manufacturing segments as equipment leasing models displace ownership. Long-term viability over the next decade favors scaled logistics providers capable of absorbing MOHAP digitization investments. Acquisition targets should profile halal-certified processors with slaughterhouse-to-freezer traceability. The signal to watch is consolidation of supplier rosters into volume-commitment agreements by multi-outlet food service operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Slaughterhouse Operations | Halal certification traceability from slaughterhouse to freezer secures premium positioning with hotel procurement departments. |
| IoT-Enabled Cold-Chain Infrastructure Deployment | Real-time temperature dashboards satisfy MOHAP digitization mandates and disqualify non-compliant competitors. |
| Asset-Light Blast-Freezing Equipment Leasing | Third-party rental models lower entry barriers for new processors in Khalifa Industrial Zone. |
| Direct-to-Consumer Frozen Delivery Platform Launch | Same-day fulfillment infrastructure captures younger demographics in Sharjah bypassing supermarket intermediaries. |
| Private-Label Hypermarket Contract Manufacturing | HACCP-compliant facilities access white space in captive frozen lines at Lulu Group International and comparable retail anchors. |
Research Methodology
Operator-level perspectives from cold storage facility managers, hotel procurement directors, hypermarket category buyers, food service supply chain heads, and MOHAP compliance officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs import records, MOHAP enforcement bulletins, hospitality sector procurement databases, and SEC filings of listed food processing entities. Bottom-up volume modeling triangulated with top-down macroeconomic consumption indicators.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around energy tariff trajectories and port throughput disruptions. Segmentation dimensions modeled include product category, distribution channel format, end-user procurement scale, and packaging barrier specifications. CAGRs were derived from trend extrapolation of historical trade flows and elasticity-adjusted demand projections. Forecast inputs incorporated blast-freezing capacity utilization rates and halal certification adoption curves.
Macroeconomic conditions sit as an overlay; deviation in hospitality occupancy rates, electricity tariff schedules, or South Asian shipping lane reliability would shift the trajectory. Forecasts reflect documented assumptions regarding MOHAP enforcement timing and centralized kitchen expansion rates. Quarterly review of port dwell times, cold storage capacity additions, and preferred-vendor agreement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Frozen Bread Market