
 Liquid Mushroom Market | 2026-2036
Liquid Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Mushroom Market Foresight
Buyer concentration in the nutraceutical channel is recalibrating as specialized e-commerce platforms and direct-to-consumer health brands fragment traditional wholesale procurement. Fungi Perfecti leverages its mycological research heritage to sustain premium positioning in North American specialty retail. Chongqing Joywin Natural Products Co., Ltd. anchors bulk extract supply for international formulators through integrated cultivation and processing operations in Sichuan province.
Liquid mushroom denotes aqueous or ethanol-based extracts derived from fungal fruiting bodies or mycelial biomass, typically standardized to polysaccharide or triterpenoid content for bioactive consistency. These extracts serve as functional inputs in dietary supplements, functional beverages, and topical formulations where dose precision and bioavailability outweigh raw powder utility. Lion's Mane liquid extracts command premium positioning in cognitive health applications where hericenones and erinacines drive formulation differentiation. Reishi tinctures occupy mature demand pools in traditional medicine channels across East Asia while penetrating Western adaptogenic product lines. The dietary supplements application segment concentrates margin capture as finished brands extract value through clinical positioning and subscription distribution models.
The FDA exercises oversight through dietary supplement GMPs and New Dietary Ingredient notifications for novel mushroom extracts entering US commerce. EFSA evaluates Novel Food applications for non-traditional fungal species across European member states, creating variable approval timelines that shape product launch sequencing. China's NMPA and SAMR coordinate dual-use registration pathways for medicinal and food-grade mushroom extracts under GB standards. Stakeholders must monitor evolving novel food classifications and extraction solvent regulations to align compliance investment with market entry timing.
Market Dynamics
Extraction standardization under tightening novel food classifications is forcing capital reallocation toward solvent-recovery systems and third-party certification infrastructure across the supply base.
Growth Catalysts
- EU Novel Food Regulation streamlining:Accelerated approval pathways for traditional fungal species reduce time-to-market for aqueous extracts entering German and French supplement channels.
- Functional beverage formulators:Ready-to-drink adaptogenic brands drive volume demand for standardized Lion's Mane and Reishi liquid inputs with verified polysaccharide content.
- Ethanol recovery technology:Closed-loop solvent systems cut extraction waste disposal costs and enable organic certification compliance for premium positioning.
Market Restraints
- Raw mycelium supply concentration:Austrian and Bavarian biomass suppliers control upstream availability, creating bottleneck risk for Central European processors.
- Novel Food application costs:EFSA safety dossier requirements impose six-figure compliance burdens that exclude smaller extractors from EU commercialization.
- Freeze-dried powder substitution:Lower-cost whole-mushroom powders compete in mass-market supplement applications where bioavailability claims carry less weight.
Strategic Opportunities
- Topical cosmetic applications:Triterpenoid-rich Reishi extracts penetrate prestige skincare formulations seeking adaptogenic positioning in South Korean and Japanese markets.
- Direct-to-consumer subscription channels:Specialized health platforms bypass wholesale margin compression through recurring revenue models and clinical storytelling.
- Dual-use registration pathways:China's SAMR coordination of medicinal and food-grade standards enables single-facility output serving both TCM and functional food demand.
Industry Challenges
- Mycological analytical talent scarcity:Qualified chromatography technicians for hericenone and erinacine quantification command premium wages in Sichuan and Zhejiang processing hubs.
- Batch-to-batch bioactive variance:Fruiting body substrate composition differences complicate standardization protocols for contract manufacturers serving multi-brand portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Mushroom Market |
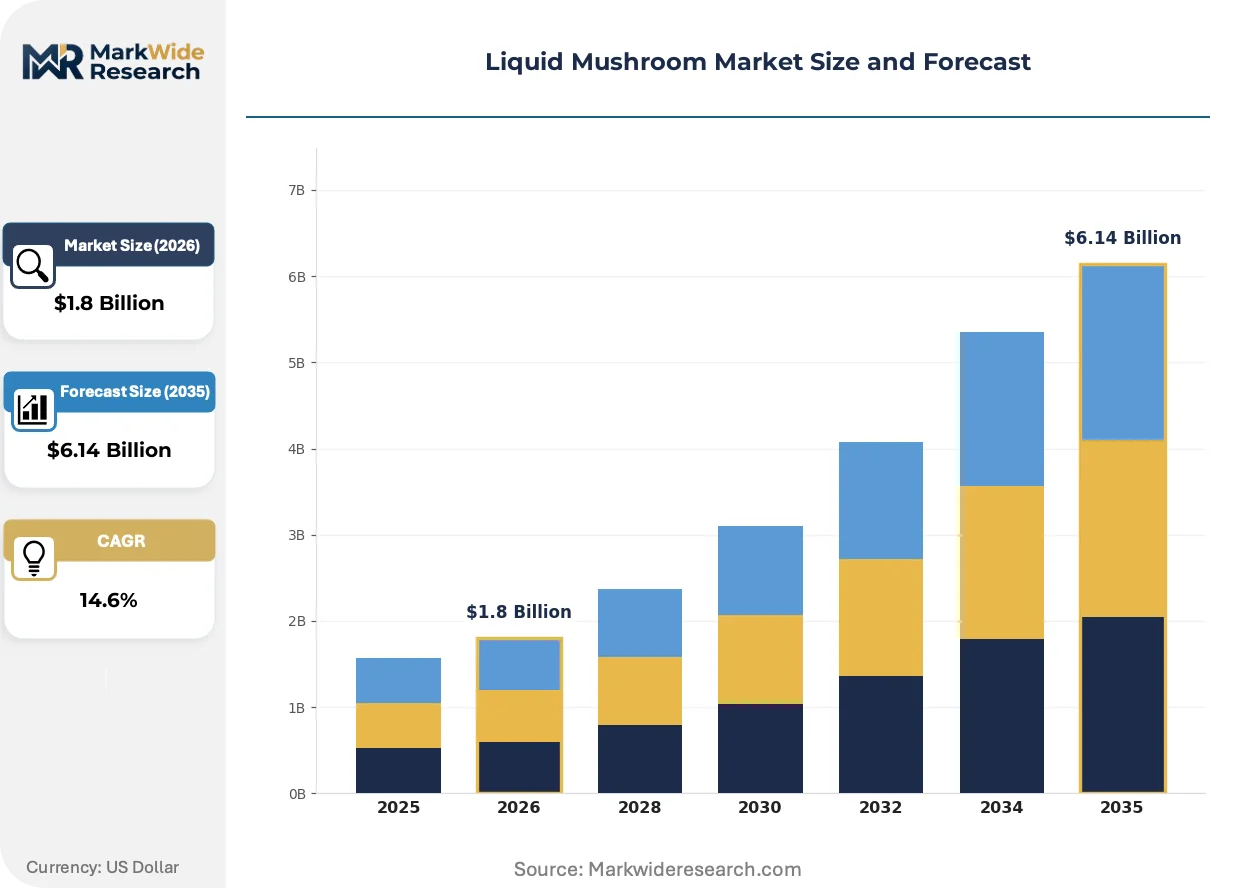
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shiitake, Reishi, Chaga, Lion’s Mane Application: Food & Beverages, Nutraceuticals, Cosmetics, Dietary Supplements Form: Liquid Extracts, Powders, Capsules, Tinctures Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | Tyroler Glückspilze, Natura Mushrooms, Catskill Fungi, FNG Fungi, Mushroom Science, Amines Biotech Pvt Ltd, Mycelium Sona Biotech Private Limited, Chongqing Joywin Natural Products Co., Ltd., Fungi Perfecti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Mushroom Market Shifts & Advancements
Ultrasonic-assisted extraction is displacing conventional heat-based methods as processors target heat-sensitive bioactive preservation and throughput acceleration.
Subcritical water extraction is converging with membrane filtration to produce high-purity beta-glucan isolates without ethanol residue. North American specialty supplement brands are adopting these outputs for clean-label positioning. The technology is converging with carbon footprint reduction mandates by eliminating solvent transport and disposal logistics.
EFSA's evolving Novel Food guidance on fungal mycelium biomass is compressing approval timelines for fermented substrates versus wild-harvested fruiting bodies. German and Dutch formulators are resequencing product launches toward mycelium-derived extracts. This regulatory pivot favors integrated cultivator-processors with in-house fermentation capacity over extract-only operations.
Subscription-based replenishment models are displacing retail shelf presence as the primary customer acquisition channel for cognitive health formulations. Direct-to-consumer brands in the United States and United Kingdom capture lifetime value through automated reordering. This channel shift concentrates marketing spend on digital clinical education rather than wholesale slotting fees.
Liquid Mushroom Market Segmentation
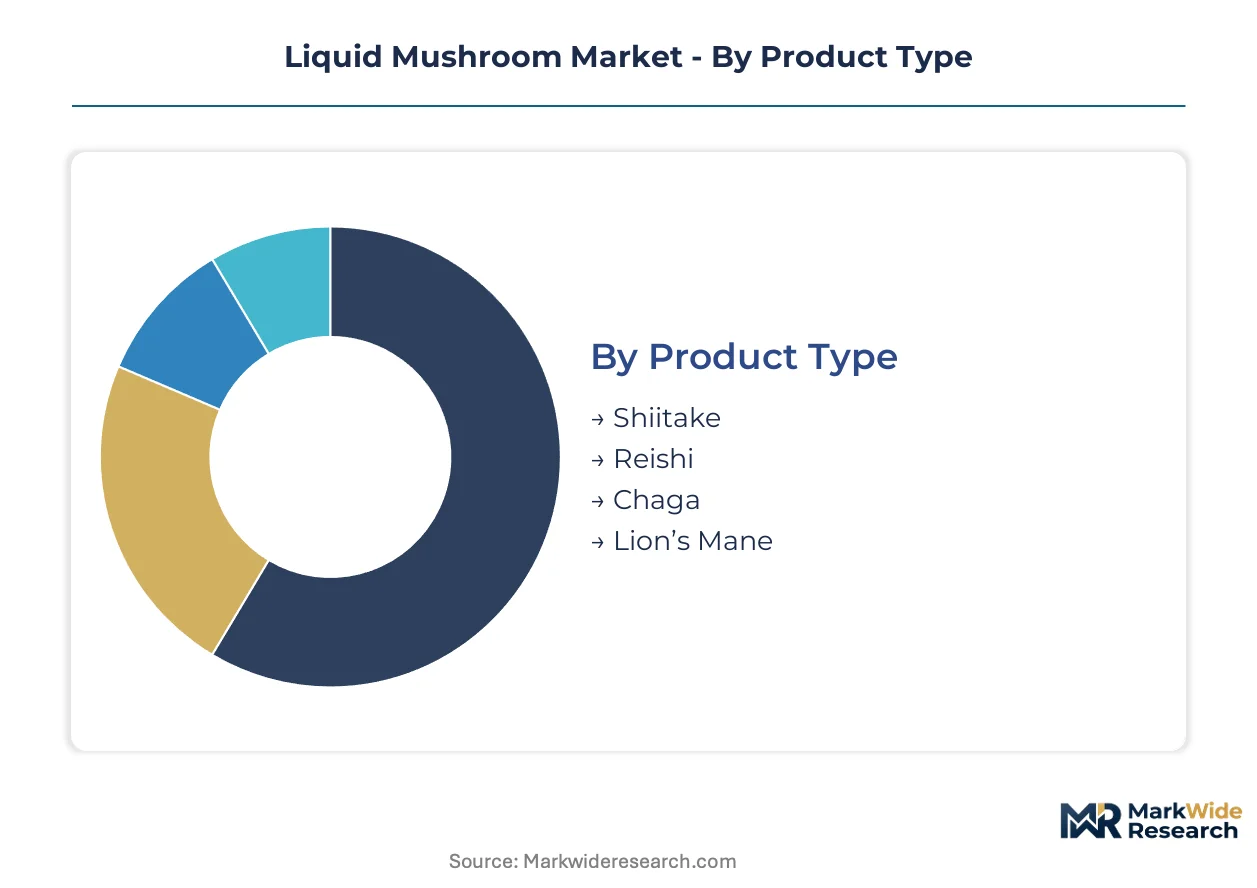
Liquid mushroom segmentation reveals divergent compliance pathways across product categories. Certification requirements for novel food status, organic extraction, and cosmetic ingredient safety create tiered market access barriers that reshape competitive positioning.
Product Type:
EFSA Novel Food approvals and USDA organic certification create asymmetric compliance burdens across fungal species, with traditional fruiting bodies facing streamlined pathways versus fermented mycelium substrates.
- Lion's Mane:Hericenone and erinacine bioactives drive specification premiums in cognitive health formulations. Demand concentrates in United States direct-to-consumer channels where clinical positioning justifies subscription pricing.
- Reishi:Triterpenoid-rich extracts serve dual traditional medicine and Western adaptogenic markets. German and French supplement formulators drive volume through EFSA-approved aqueous extracts.
- Shiitake:Lentinan-standardized outputs anchor immune health applications with established GRAS status in US dietary supplements.
- Chaga:Wild-harvested sourcing constraints limit scalable supply, concentrating availability in premium North American specialty retail.
Reishi sits at the top of the volume ranking, with Lion's Mane climbing the fastest.
Application:
Margin structures diverge sharply across end-use channels, with finished brands capturing value through clinical storytelling versus bulk extract commoditization in ingredient supply.
- Dietary Supplements:Polysaccharide-standardized extracts command specification premiums through third-party testing and subscription distribution models. United Kingdom and German health platforms fragment traditional wholesale procurement.
- Food & Beverages:Ready-to-drink adaptogenic formulations require verified bioactive content and clean-label positioning. Functional beverage brands in North America drive volume demand for heat-stable liquid inputs.
- Nutraceuticals:Clinical trial substantiation separates premium positioning from commodity ingredient supply.
- Cosmetics:Triterpenoid-rich Reishi extracts penetrate South Korean and Japanese prestige skincare through adaptogenic positioning.
Dietary Supplements generate the highest margin capture, with Cosmetics expanding most quickly.
Form:
Bioavailability claims and dose precision requirements reshape form selection, with liquid formats gaining share in applications where absorption speed outweighs convenience factors.
- Liquid Extracts:Aqueous and ethanol-based solutions enable precise dosing and rapid absorption in functional beverages and sublingual supplements. Ultrasonic-assisted extraction preserves heat-sensitive bioactives for premium positioning.
- Tinctures:Alcohol-based preservation extends shelf stability for direct-to-consumer cognitive health brands in United States specialty retail.
- Capsules:Encapsulated liquid extracts bridge convenience and bioavailability for mass-market supplement applications.
- Powders:Freeze-dried alternatives compete on cost in applications where bioavailability claims carry less weight.
Liquid Extracts dominate value generation, with Tinctures gaining share fastest.
Distribution Channel:
Customer acquisition economics favor recurring revenue models over retail shelf presence, reallocating marketing spend from slotting fees to digital clinical education.
- Online Retail:Specialized health platforms and direct-to-consumer brands capture lifetime value through automated replenishment. Subscription models displace wholesale margin compression in United States and United Kingdom markets.
- Health Food Stores:Staff-educated positioning sustains premium pricing for clinical-grade extracts with third-party certification.
- Specialty Stores:Curated assortments favor heritage mycological brands with research-backed positioning.
- Supermarkets:Mass-market penetration requires price-competitive powder alternatives to liquid extracts.
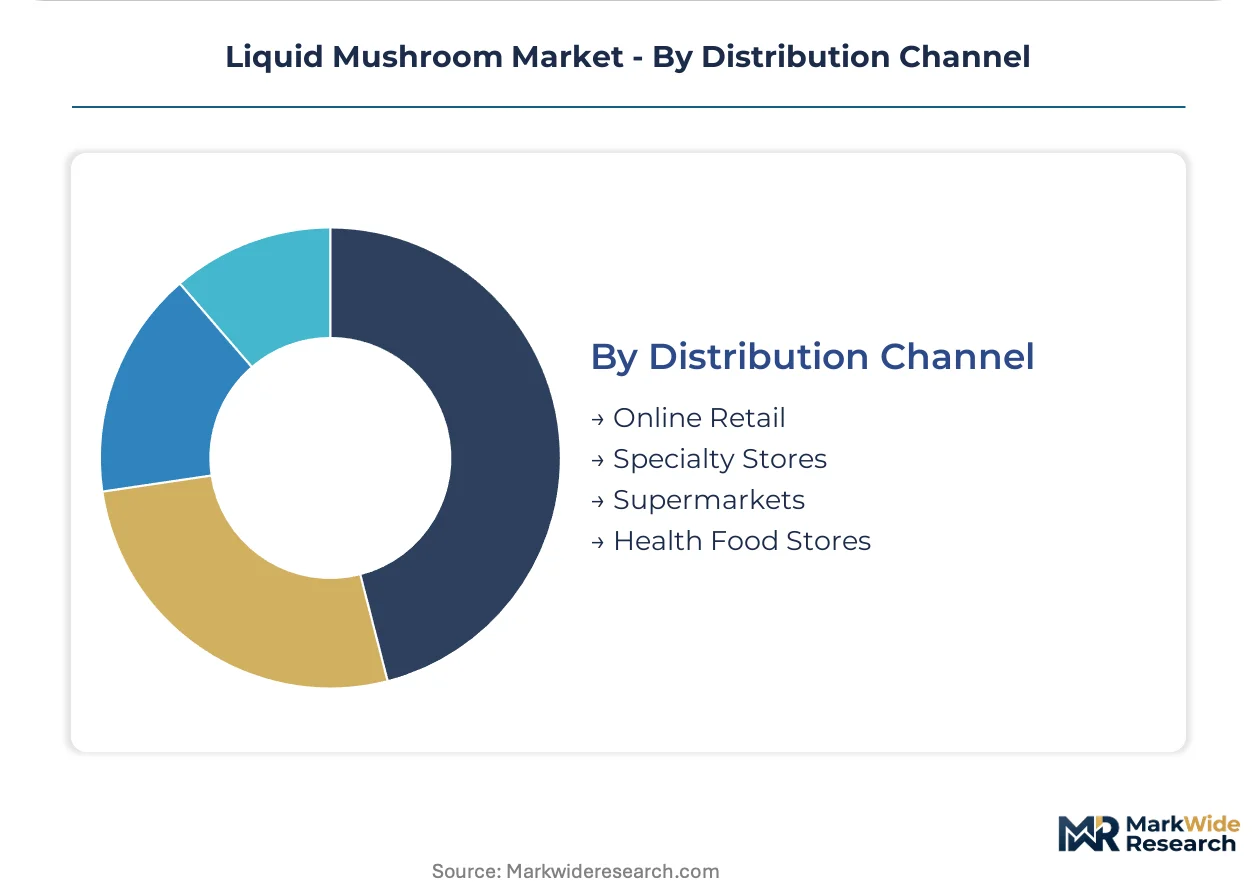
Online Retail leads channel value creation, with Health Food Stores showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest volume throughput in European liquid mushroom processing, while the United States leads direct-to-consumer subscription penetration for cognitive health formulations.
United States
Specialized e-commerce platforms and direct-to-consumer health brands fragment traditional wholesale procurement patterns. The FDA exercises oversight through dietary supplement GMPs and New Dietary Ingredient notifications for novel mushroom extracts entering commerce. Pacific Northwest mycological research clusters anchor premium positioning in specialty retail channels.
Germany
EFSA-approved aqueous Reishi extracts drive volume through supplement formulators seeking streamlined Novel Food pathways. The EU Novel Food Regulation creates asymmetric compliance burdens across fungal species and extraction methods. Austrian and Bavarian mycelium suppliers anchor Central European supply chains with concentrated upstream biomass availability.
China
NMPA and SAMR coordinate dual-use registration pathways for medicinal and food-grade mushroom extracts under GB standards. Sichuan province hosts integrated cultivation and processing operations serving international formulators. Chongqing-based processors leverage in-house fermentation capacity to capture regulatory advantages for mycelium-derived extracts.
United Kingdom
Evolving FSA guidelines tighten extraction standard requirements while specialized health platforms bypass wholesale margin compression. The FSA evaluates novel food applications with variable timelines that shape product launch sequencing. London-centered direct-to-consumer brands capture lifetime value through automated replenishment models.
South Korea
Prestige skincare formulators drive demand for triterpenoid-rich Reishi extracts through adaptogenic positioning. The MFDS oversees cosmetic ingredient safety assessments for topical applications. Seoul-based beauty brands penetrate regional markets with clinical storytelling around fungal bioactives.
Liquid Mushroom Market Competitive Landscape
North American producers anchor one tier; Asian specialists hold concentrated extraction capacity. The vendor base organizes around three strategic archetypes: integrated cultivator-processors with in-house fermentation, research-heritage brands commanding premium positioning, and bulk extract suppliers serving international formulators. Competitive moves concentrate on solvent-recovery technology licensing and third-party certification infrastructure expansion.
Among heritage research-oriented specialists, Fungi Perfecti exemplifies premium positioning through mycological credibility. Chinese integrated operators such as Chongqing Joywin Natural Products Co., Ltd. occupy the bulk supply tier with captive cultivation and processing capabilities. European biomass specialists including Tyroler Glückspilze represent upstream concentration in Central European mycelium supply.
| Leading Market Players |
|---|
| Tyroler Glückspilze |
| Natura Mushrooms |
| Catskill Fungi |
| FNG Fungi |
| Mushroom Science |
| Amines Biotech Pvt Ltd |
| Mycelium Sona Biotech Private Limited |
| Chongqing Joywin Natural Products Co., Ltd. |
| Fungi Perfecti |
| Others |
Supply & Pricing Matrix
Mycelium biomass costs originating from Austrian and Bavarian cultivation hubs flow through extraction processing tiers to determine finished extract pricing stratification across premium, standard, and economy levels. Solvent-recovery capital investments and third-party certification infrastructure create asymmetric cost structures that separate EFSA-compliant aqueous extracts from commodity ethanol-based alternatives in German and French procurement channels.
Pricing Analysis
Capacity additions in Sichuan province are reshaping price floors for Lion's Mane and Reishi liquid extracts as integrated cultivator-processors achieve scale economies unavailable to extract-only operations. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified ultrasonic extracts from conventional heat-processed alternatives and unstandardized bulk supply. Price differentiation hinges on hericenone quantification precision and EFSA Novel Food dossier completion. Cost compression in the economy tier is intensifying because freeze-dried powders compete on bioavailability claims in mass-market applications. Direct-to-consumer subscription buyers show least price sensitivity, while supermarket private-label procurement demonstrates highest elasticity.
Supply Chain Analysis
Refurbishment flows for solvent recovery systems and extraction equipment create secondary equipment markets that extend asset lifecycles for mid-scale processors in Zhejiang and Sichuan provinces. Upstream biomass availability concentrates in Austria, Germany, and China, with wild-harvested Chaga sourcing restricted to boreal forest regions of Russia and Canada. Fermented mycelium production draws from cereal substrate supply chains and pharmaceutical-grade glucose feedstocks. Single-source vulnerability persists in qualified chromatography technician availability across Sichuan processing hubs. Distribution runs through specialized e-commerce platforms and health food store networks in the United States and United Kingdom, bypassing traditional wholesale margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid mushroom extract economics favor margin expansion through solvent-recovery technology deployment and subscription channel control that captures lifetime value beyond transactional wholesale pricing.
For Market Incumbents: Deploy closed-loop ethanol recovery systems to defend extraction cost positions against Sichuan-based integrated operators achieving organic certification compliance. Secure captive mycelium supply through backward integration into Austrian or Bavarian cultivation assets before biomass bottleneck risk materializes. Reinforce clinical positioning through third-party hericenone and erinacine quantification protocols that justify subscription pricing premiums against emerging freeze-dried powder substitutes. For New Entrants and Emerging Players: Begin with topical cosmetic applications in South Korean and Japanese prestige skincare, where triterpenoid-rich Reishi extracts face limited established competition and adaptogenic positioning commands formulation premiums. Target direct-to-consumer cognitive health platforms in the United Kingdom, where evolving FSA guidelines create temporary compliance windows for novel mycelium-derived extracts ahead of incumbent re-registration. Pursue white-label supply agreements with functional beverage formulators seeking verified polysaccharide content for ready-to-drink adaptogenic launches. For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA Novel Food compliance costs exceed six figures and exclude smaller extractors from EU commercialization, creating acquisition opportunities for dossier-complete assets. Favor integrated cultivator-processors with in-house fermentation capacity serving dual-use medicinal and food-grade registration pathways under China's SAMR coordination. Monitor EFSA guidance evolution on fungal mycelium biomass classifications as inflection indicator for mycelium-derived extract valuation premiums over wild-harvested fruiting body alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic-Assisted Extraction Scale-Up | Preserves heat-sensitive hericenones for cognitive health premium positioning against conventional processors. |
| EFSA Novel Food Dossier Completion | Unlocks German and French supplement channel access with streamlined approval timelines for aqueous extracts. |
| Closed-Loop Solvent Recovery Installation | Enables organic certification compliance and waste disposal cost reduction for premium extract positioning. |
| Direct-to-Consumer Subscription Launch | Captures lifetime value through automated replenishment models displacing wholesale margin compression. |
| Dual-Use Registration Pathway Pursuit | Leverages China's SAMR coordination to serve both TCM and functional food demand from single facilities. |
Research Methodology
Multiple input streams — primary interviews with extraction facility managers, regulatory affairs specialists at novel food consultancies, and procurement leads at dietary supplement formulators — were reconciled against secondary validation from EFSA Novel Food application databases, SAMR registration filings, and customs trade records for fungal biomass and extract categories. Bottom-up triangulation across processor capacity assessments and top-down demand modeling from end-use channel consumption patterns ensured cross-verified output integrity.
Data-stream reconciliation anchored volume and value projections across the analysis window through segmented modeling of product type, application, form, and distribution channel dimensions with regional regulatory cluster differentiation. CAGRs were derived from trajectory fitting to historical approval timelines and channel penetration curves. Industry-specific forecast inputs incorporated EFSA guidance evolution pace and subscription channel adoption elasticity in United States and United Kingdom cognitive health markets.
Several conditions sit outside the modeled scope, including unannounced regulatory reclassifications, breakthrough cultivation yield improvements, and macroeconomic disruptions to premium discretionary spending. Forecasts reflect documented assumptions about approval pathway timelines and biomass supply stability. Practitioners should monitor EFSA Novel Food guidance updates, Austrian mycelium harvest yields, and direct-to-consumer customer acquisition cost trends for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Maple Syrup Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Global Truffle Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Middle East and Africa Hummus Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Dill Juice Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Triphala Powder Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Personalized Meals Market