
 Plant-Based Tzatziki and Labneh Ferment Bases Market | 2026-2036
Plant-Based Tzatziki and Labneh Ferment Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Tzatziki and Labneh Ferment Bases Market Insights
ISO 22000 certification is reorganizing competitive access in the plant-based tzatziki and labneh ferment bases sector, filtering out smaller culture suppliers lacking hazard-analysis documentation. Danone leverages captive dairy-alternative R&D pipelines to sustain formulation leadership across European retail channels. Chobani anchors its position through Mediterranean heritage brand equity and food service penetration. Kite Hill differentiates via almond-base specialization that extends into clean-label ferment applications.
Plant-based tzatziki and labneh ferment bases comprise defined microbial culture systems—typically incorporating Lactobacillus bulgaricus and Streptococcus thermophilus strains at titers exceeding 10^8 CFU per gram—engineered to acidify and texturize non-dairy substrates into viscous, tangy preparations resembling traditional yogurt-based spreads. Powdered mixes command the dominant volume position due to shelf stability and freight economics, while liquid cultures capture accelerating interest from refrigerated-chain food service operators seeking live-culture authenticity. Ferment base concentrates concentrate margin pools among specialty food producers running small-batch artisan lines, whereas spray-dried cultures dominate scale manufacturing for frozen food companies.
FDA GRAS self-determination and EFSA novel food assessments create divergent compliance pathways for cross-Atlantic suppliers, with the latter demanding exhaustive safety dossiers that extend market access timelines. The EU Green Deal carbon border adjustments and REACH chemical registration requirements further shape formulation choices, pressuring manufacturers to document sustainable substrate sourcing. Stakeholders must monitor evolving live-culture labeling thresholds across jurisdictions to preempt reformulation cycles.
Market Dynamics
EU Green Deal carbon border adjustments and F-Gas Regulation compliance costs are restructuring refrigerated fermentation logistics, forcing culture suppliers to document substrate provenance and cold-chain emissions or forfeit access to German, French, and UK food service channels.
Growth Catalysts
- EFSA Novel Food Pathways:Standardized safety dossier requirements for microbial cultures accelerate cross-border trade by eliminating jurisdiction-by-jurisdiction approval delays for Lactobacillus and Streptococcus strains.
- Food Service Live-Culture Demand:Mediterranean restaurant chains in Southern Europe specify refrigerated liquid cultures over powdered alternatives to meet clean-label menu positioning.
- Almond-Base Substrate Expansion:Specialty producers in Spain and Italy scale procurement of high-fat almond milk concentrates as fermentation feedstock for vegan labneh viscosity targets.
Market Restraints
- REACH Chemical Registration:Fermentation-derived metabolites and processing aids face escalating documentation burdens at ECHA, extending reformulation timelines for export-oriented suppliers.
- Refrigerated-Chain Concentration:Cold storage capacity bottlenecks in the Netherlands and Belgium limit just-in-time distribution of live-culture liquid formats to UK retail.
- Coconut Oil Price Volatility:Clean-label formulations dependent on Southeast Asian coconut cream experience margin compression when commodity swings exceed 15 percent quarterly.
Strategic Opportunities
- Portuguese Artisan Scale-Up:Underpenetrated domestic tzatziki production offers entry points for ferment base suppliers able to meet PDR (Protected Designation of Origin) adjacent positioning.
- CSRD-Aligned Carbon Accounting:Early adoption of EU corporate sustainability reporting standards differentiates culture providers in RFP processes with Danone-scale buyers.
- Direct-to-Restaurant Distribution:Bypassing traditional food service distributors via refrigerated last-mile partnerships captures margin pools currently absorbed by wholesale intermediaries.
Industry Challenges
- ISO 22000 Documentation Burden:Smaller culture houses lack hazard-analysis resources to complete certification, ceding shelf space to consolidated suppliers with captive quality departments.
- Legacy Dairy Equipment Retrofit:Plant-based viscosity targets require stainless-steel fermentation tank modifications that strain capex budgets for mid-scale producers.
- Live-Culture Labeling Threshold Variance:Divergent national definitions of "active" versus "viable" cultures force SKU proliferation across Germany, France, and UK retail packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Tzatziki and Labneh Ferment Bases Market |
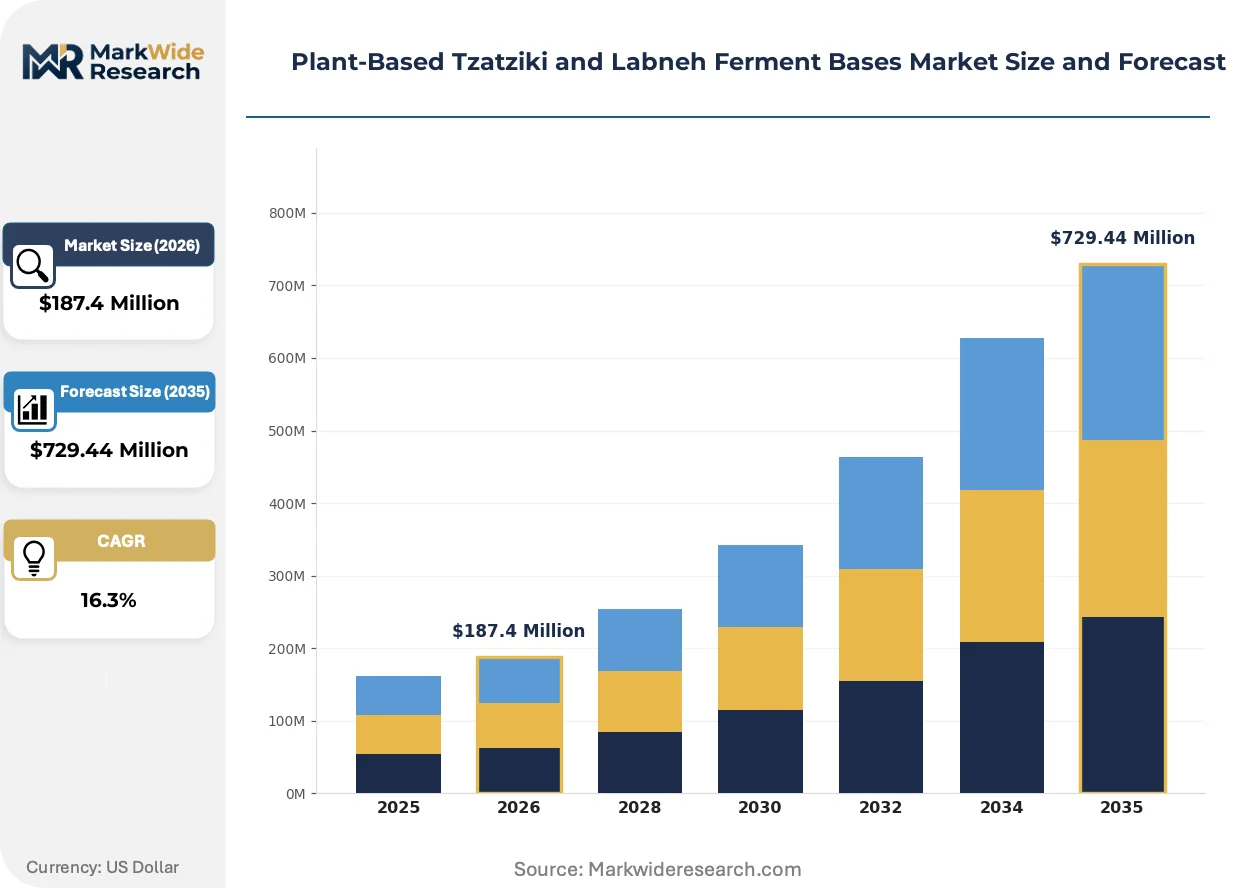
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $729.44 Million |
| CAGR (2026 – 2036) | 16.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferment Base Concentrates, Powdered Mixes, Liquid Cultures, Freeze-Dried Starters, Spray-Dried Cultures Application: Plant-Based Dairy Alternatives, Vegan Dips, Mediterranean Cuisine, Functional Foods, Ready-to-Eat Meals End User: Dairy Alternatives Manufacturers, Specialty Food Producers, Frozen Food Companies, Gourmet Food Retailers, Food Service Providers Packaging Type: Bulk Bags, Sachets, Bottles, Tubs, Retail Ready Packs |
| Companies Covered | Danone, Nestlé, General Mills, The Hain Celestial Group, Chobani, Alpro, Oatly, Kite Hill, Forager Project, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Tzatziki and Labneh Ferment Bases Market Trends and Innovations
Spray-dried versus liquid culture formats are diverging along supply-chain capability lines, with carbon-accounting pressures and live-culture authenticity claims pulling formulation strategies in opposing directions across European manufacturing.
Precision fermentation is bifurcating the supplier base into two camps: large-scale frozen food manufacturers demanding standardized powdered concentrates with 18-month shelf stability, and artisan Mediterranean producers paying premiums for small-batch liquid cultures with verified titers above 10^8 CFU per gram. German retail chains now specify batch-traceable live cultures for private-label vegan labneh, compressing margins for undifferentiated commodity suppliers unable to document cold-chain integrity.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent fermentation facilities to retrofit cooling systems or relocate to districts with district cooling infrastructure. Specialty food producers in the United Kingdom face compressed operating windows as hydrofluorocarbon quotas tighten, accelerating interest in ambient-stable powdered formats despite organoleptic trade-offs.
Clean-label certification is displacing conventional ingredient declarations as the primary purchase filter among Southern European food service buyers. Greek and Italian restaurant groups now require almond-base or cashew-base provenance documentation alongside microbial strain transparency, shifting procurement evaluation criteria from unit cost to substrate traceability and third-party audit frequency.
Plant-Based Tzatziki and Labneh Ferment Bases Market Segmentation
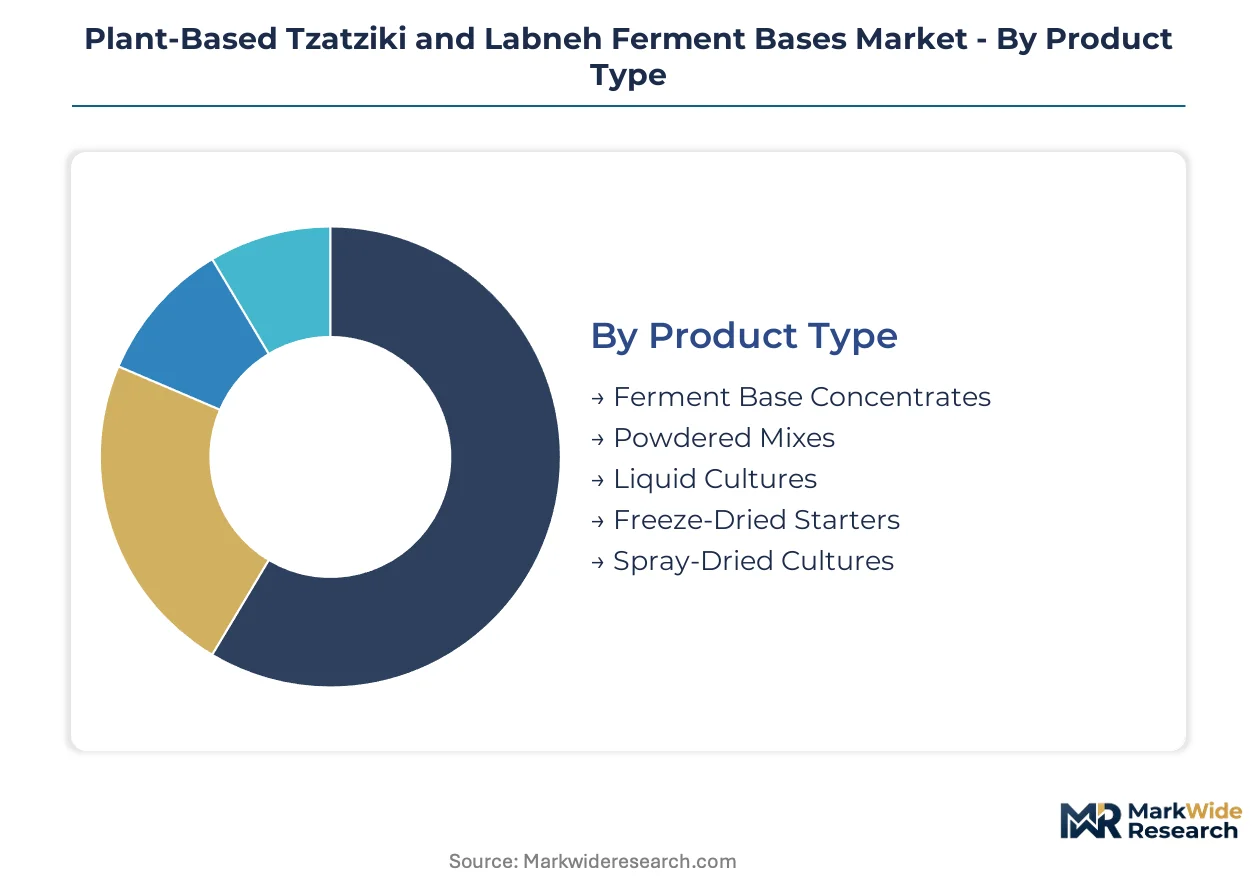
Segmentation in the plant-based tzatziki and labneh ferment bases market exposes divergent margin structures across supply chain positions. Powdered formats and bulk packaging concentrate profitability among scale manufacturers, while liquid cultures and specialty retail formats capture premium pools in Mediterranean food service channels.
Product Type:
Highest margin capture sits with formats that reconcile shelf stability claims against live-culture authenticity demands.
- Ferment Base Concentrates:High-titer microbial suspensions exceeding 10^8 CFU per gram packaged in refrigerated bulk totes. Artisan producers in Spain and Italy pay premiums for small-batch concentrates that deliver clean-label viscosity without powdered texture artifacts.
- Powdered Mixes:Spray-dried or roller-dried culture matrices with 12-18 month ambient stability. Frozen food manufacturers in Germany specify these for cost-efficient vegan labneh production where live-culture claims are secondary to logistics simplicity.
- Liquid Cultures:Refrigerated single-strain or multi-strain suspensions requiring continuous cold chain. UK food service distributors increasingly specify batch-traceable liquid formats for Mediterranean restaurant chains.
- Freeze-Dried Starters:Lyophilized culture cakes with extended shelf life and rapid rehydration. Gourmet retailers in France stock these for home fermentation kits targeting clean-label enthusiasts.
- Spray-Dried Cultures:Atomized culture droplets dried in heated chambers for uniform particle size. Scale manufacturers favor these for automated blending lines in plant-based dairy alternative facilities.
The dominant share belongs to Powdered Mixes, while Liquid Cultures is closing the gap fastest.
Application:
Revenue concentration tracks Mediterranean cuisine authenticity requirements and functional positioning claims.
- Plant-Based Dairy Alternatives:Industrial-scale production of vegan yogurt, cream cheese, and spreadable bases. Manufacturers in the Netherlands optimize fermentation protocols for almond and oat substrate compatibility.
- Vegan Dips:Tzatziki-style preparations with cucumber, garlic, and herb inclusions. UK retail chains demand ISO 22000-certified bases for private-label vegan dip lines.
- Mediterranean Cuisine:Restaurant and food service applications emphasizing traditional flavor profiles. Southern European operators specify liquid cultures with verified Streptococcus thermophilus titers for menu authenticity.
- Functional Foods:Probiotic-positioned spreads with documented CFU counts at consumption. German health-food retailers require third-party viability testing for shelf-stable claims.
- Ready-to-Eat Meals:Pre-packaged meal components incorporating fermented bases. Frozen meal producers prioritize powdered formats for production line integration.
Plant-Based Dairy Alternatives commands the largest volume position, though Mediterranean Cuisine is expanding most quickly as food service channels professionalize.
End User:
Procurement sophistication separates commodity buyers from premium-positioned specialists.
- Dairy Alternatives Manufacturers:Industrial-scale operators running continuous fermentation with automated pH control. These buyers negotiate multi-year contracts for standardized powdered cultures.
- Specialty Food Producers:Small-batch artisan operations emphasizing substrate provenance and strain transparency. Portuguese and Greek producers in this tier pay 40-60% premiums for documented almond-base fermentation feedstock.
- Frozen Food Companies:Mass-market operators requiring 18-month shelf stability and freeze-thaw tolerance. These users drive demand for encapsulated culture formats.
- Gourmet Food Retailers:Premium-positioned outlets stocking ferment bases for home use. French and Italian retailers specify retail-ready packaging with multilingual labeling.
- Food Service Providers:Restaurant chains and institutional caterers with refrigerated distribution networks. UK and German Mediterranean chains increasingly bypass distributors for direct culture procurement.
Dairy Alternatives Manufacturers holds the dominant procurement volume, while Food Service Providers is gaining share fastest through direct sourcing initiatives.
Packaging Type:
Format selection reflects cold-chain availability and production scale economics.
- Bulk Bags:Multi-kilogram flexible containers for industrial fermentation tanks. Scale manufacturers in Belgium and the Netherlands specify these for just-in-time powder delivery.
- Sachets:Single-use portions targeting home fermentation and small commercial batches. Gourmet retailers stock these for consumer convenience positioning.
- Bottles:Rigid containers for liquid cultures with dispensing closures. Food service operators in France prefer these for kitchen portion control.
- Tubs:Wide-mouth containers for paste or semi-liquid concentrates. Artisan producers value these for manual scooping access.
- Retail Ready Packs:Shelf-display cartons with consumer-facing graphics. German and UK supermarkets require these for branded vegan labneh base placement.
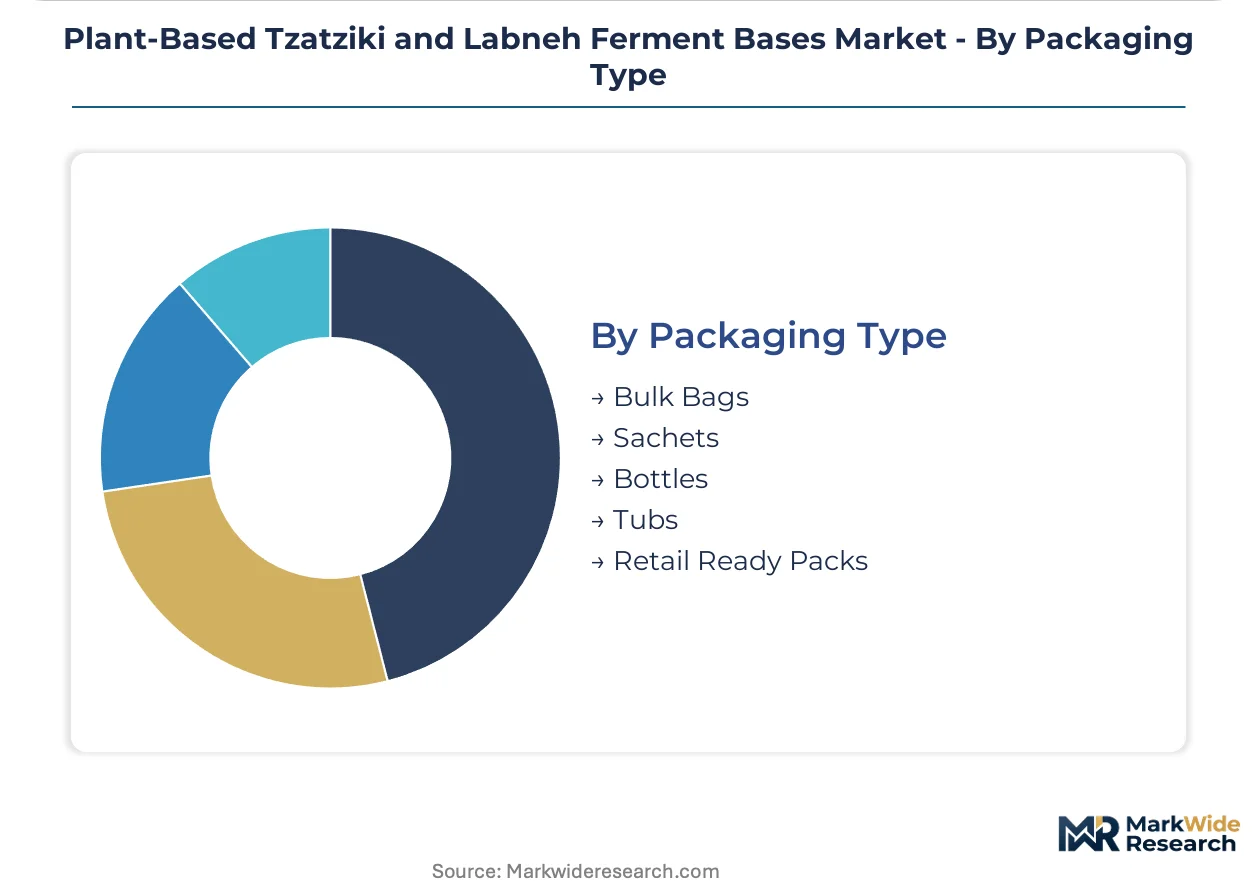
Bulk Bags maintains the dominant format share, though Retail Ready Packs is climbing fastest as branded consumer lines proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty food producers and Mediterranean restaurant chains concentrate procurement across Germany, France, the United Kingdom, Italy, and Spain, with each market presenting distinct regulatory hurdles and substrate sourcing preferences.
Germany
Industrial-scale dairy alternatives manufacturers drive bulk powdered culture demand for automated vegan labneh production lines. The EU F-Gas Regulation compresses operating windows for refrigerated fermentation facilities in Bavaria and North Rhine-Westphalia. Berlin-based food service distributors increasingly specify ISO 22000-certified liquid cultures for Mediterranean restaurant chains seeking clean-label menu positioning.
France
Gourmet retailers and artisan producers anchor demand for freeze-dried starter kits and small-batch ferment base concentrates. EFSA novel food assessment requirements extend market access timelines for imported microbial strains. The Provence-Alpes-Côte d'Azur cluster hosts expanding almond-base substrate processing for vegan labneh viscosity targets.
United Kingdom
Food service providers bypass traditional distributors through direct refrigerated last-mile partnerships with culture suppliers. Cold storage capacity bottlenecks in the Netherlands and Belgium constrain just-in-time distribution of live-culture liquid formats to UK retail. London-based Mediterranean restaurant groups now mandate batch-traceable Streptococcus thermophilus titers for menu authenticity claims.
Italy
Specialty food producers in Emilia-Romagna and Lombardy scale procurement of high-fat almond milk concentrates as fermentation feedstock. REACH chemical registration requirements at ECHA escalate documentation burdens for fermentation-derived metabolites. Italian clean-label certification schemes displace conventional ingredient declarations as primary purchase filters among Southern European food service buyers.
Spain
Underpenetrated domestic tzatziki production offers entry points for ferment base suppliers meeting Protected Designation of Origin adjacent positioning. The EU Green Deal carbon border adjustments pressure manufacturers to document sustainable substrate sourcing from Andalusian almond cooperatives. Barcelona-based artisan producers pay premiums for documented fermentation feedstock traceability.
Plant-Based Tzatziki and Labneh Ferment Bases Market Competitive Landscape
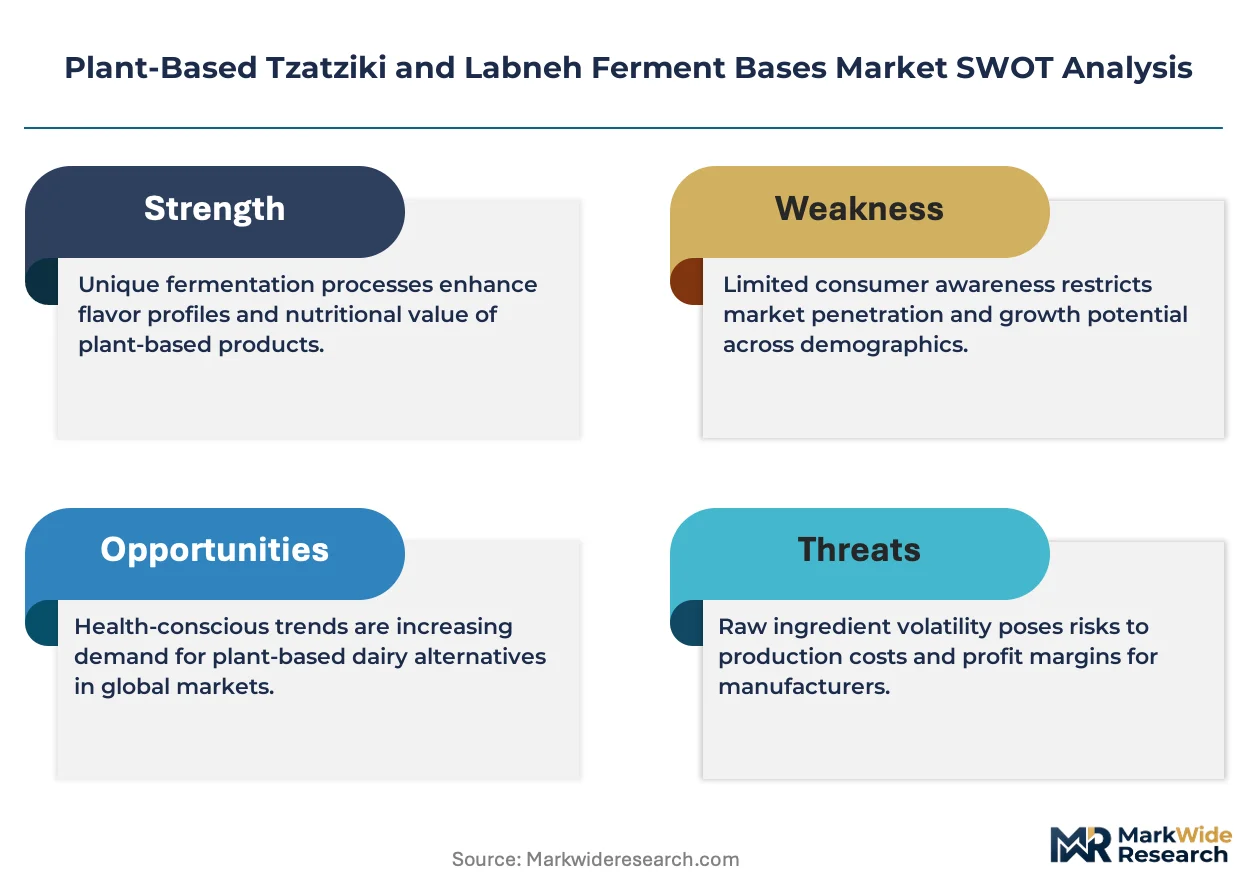
Player mix skews toward diversified dairy alternatives conglomerates and specialized plant-based culture houses. Consolidation pressures filter smaller suppliers lacking captive R&D pipelines or ISO 22000 certification resources. Two strategic archetypes dominate: scale-driven manufacturers optimizing spray-dried formats for frozen food clients, and substrate-specialized artisans commanding premiums for almond-base provenance. Competitive moves center on backward integration into fermentation feedstock sourcing and direct-to-restaurant distribution bypassing wholesale intermediaries.
Within the diversified conglomerate tier, Danone leverages captive dairy-alternative R&D pipelines across European retail channels. Chobani anchors positioning through Mediterranean heritage brand equity and food service penetration. Kite Hill occupies a specialist position via almond-base expertise extending into clean-label ferment applications. These three exemplify how formulation leadership, brand heritage, and substrate specialization respectively carve defensible positions against commodity culture suppliers.
| Leading Market Players |
|---|
| Danone |
| Nestlé |
| General Mills |
| The Hain Celestial Group |
| Chobani |
| Alpro |
| Oatly |
| Kite Hill |
| Forager Project |
| Others |
Pricing and Supply Chain Analysis
Batch-size economies in spray-dried culture production concentrate margin leverage among German and Dutch scale manufacturers, compressing price floors for artisan producers lacking captive fermentation capacity while elevating procurement premiums for liquid-culture authenticity claims.
Pricing Analysis
Cost-plus contracts with coconut oil and almond-base indexation dominate procurement agreements between culture suppliers and frozen food manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified concentrates from commodity powdered mixes and unverified liquid formats. Price differentiation hinges on cold-chain documentation depth and strain transparency certification. Pricing pressure stems from REACH chemical registration compliance costs passed through ECHA documentation requirements. Frozen food companies exhibit highest price sensitivity due to commodity-scale volume procurement, while Mediterranean restaurant chains absorb premiums for batch-traceable live cultures.
Supply Chain Analysis
Rotterdam and Antwerp port congestion elevates inbound logistics costs for Southeast Asian coconut cream and almond-base concentrates arriving via Mediterranean trade lanes. Supply concentration centers on Spain and Italy for high-fat almond milk feedstock, the Netherlands for industrial-scale culture propagation, and Belgium for spray-drying infrastructure. Raw material dependencies include coconut cream viscosity agents, almond protein isolates, and pharmaceutical-grade nitrogen for lyophilization. Single-source vulnerability runs through Andalusian almond cooperative supply agreements. Distribution runs through refrigerated food service distributors in Germany and the United Kingdom, with direct-to-restaurant partnerships gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EFSA novel food pathway standardization accelerates cross-border culture trade and Mediterranean food service chains professionalize live-culture specifications.
For Market Incumbents: Shield formulation leadership by deepening backward integration into almond-base substrate sourcing from Spanish and Italian cooperatives. Secure ISO 22000 certification moats to filter smaller culture houses lacking hazard-analysis resources. Defend against precision fermentation entrants by locking multi-year refrigerated distribution partnerships with UK and German Mediterranean restaurant chains.
For New Entrants and Emerging Players: Lead with Portuguese artisan scale-up opportunities where domestic tzatziki production remains underpenetrated and PDR-adjacent positioning commands premium positioning. Target direct-to-restaurant distribution bypassing wholesale intermediaries in London and Berlin food service clusters. Anchor go-to-market strategy on CSRD-aligned carbon accounting documentation that differentiates in Danone-scale RFP processes.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors substrate-specialized artisans with documented almond-base provenance and captive fermentation feedstock relationships. Long-term viability over the coming decade hinges on regulatory navigation capabilities across EFSA novel food and REACH chemical registration frameworks. Acquisition target archetype: culture houses with ISO 22000 certification and established Mediterranean food service penetration. Watch for inflection signals in EU F-Gas Regulation phase-down schedules forcing refrigeration-dependent facility consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Almond-Base Sourcing | Captures margin pools from Spanish and Italian cooperatives while securing substrate traceability documentation. |
| ISO 22000 Certification Investment | Filters smaller competitors and unlocks access to UK retail private-label vegan dip contracts. |
| Direct-to-Restaurant Distribution Partnerships | Bypasses wholesale intermediaries in London and Berlin to capture food service margin compression. |
| CSRD-Aligned Carbon Accounting Adoption | Differentiates culture providers in RFP processes with Danone-scale diversified conglomerate buyers. |
| Precision Fermentation Scale-Up | Addresses bifurcated demand between shelf-stable powdered concentrates and live-culture liquid formats. |
Research Methodology
A standing panel of fermentation R&D directors, specialty food procurement leads, Mediterranean restaurant chain operators, and EFSA regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with culture house quality managers and almond-base substrate suppliers combined with secondary validation from EU Green Deal policy documents, ECHA REACH registration databases, and customs trade data for fermentation feedstock flows. Bottom-up volume modeling triangulated against top-down value estimates from food service distributor revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks including dairy alternatives manufacturer capex disclosures and refrigerated logistics capacity reports. The analytical framework modeled product type, application, end user, and packaging format dimensions across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating EFSA novel food approval timelines, EU F-Gas Regulation phase-down schedules, and almond-base substrate price volatility assumptions.
Forecasts assume regulatory continuity in EU Green Deal carbon border adjustments and REACH chemical registration requirements; material policy shifts would require re-modeling. Specific risk factors include divergence in live-culture labeling thresholds across Germany, France, and the United Kingdom forcing SKU proliferation, and coconut oil commodity swings exceeding quarterly tolerance bands. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Targeting Pod Market
Plant Based Food
Japan Plant Protein Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Italy Plant Protein Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
Plant Based Tuna Market
Plant Based Food
North America Plant-Based Egg Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Africa Pea Protein Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
Plant-Based Meatballs Market