
 US Alcohol E-Commerce Market | 2026-2036
US Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
US Alcohol E-Commerce Market Insights
Premium and craft-tier beverage assortments is reorganizing how US consumers discover and purchase alcohol online. Drizly leverages its marketplace model to aggregate local liquor store inventory for same-hour delivery. Total Wine & More anchors its hybrid strategy through proprietary e-commerce fulfillment paired with physical showroom networks. Amazon competes by extending Prime logistics infrastructure into beer, wine, and spirits where state laws permit direct shipment.
US Alcohol E-Commerce encompasses the digital sale and fulfillment of beer, wine, spirits, and cider through websites and mobile applications, requiring age-verification protocols, temperature-controlled logistics, and compliance with state-specific shipping restrictions. The primary commercial purpose is to connect regulated beverage suppliers with legal-age consumers through licensed intermediaries while maintaining chain-of-custody documentation. Wine and spirits command disproportionate margin pools within product type segmentation due to higher per-unit values and subscription-friendly consumption patterns. Direct-to-Consumer channels represent the fastest-growing distribution pathway as wineries and distilleries build first-party customer relationships outside traditional wholesale tiers.
The Alcohol and Tobacco Tax and Trade Bureau (TTB), state Alcoholic Beverage Control (ABC) agencies, and the FDA jointly govern labeling, interstate shipping, and age-verification standards that dictate platform operating models and geographic reach. TTB certificate of label approval requirements and state-specific shipping permits create fragmented compliance burdens that favor platforms with regulatory technology investments. Stakeholders must monitor pending state legislation on direct-to-consumer spirits shipping and third-party delivery service licensing to anticipate market access shifts.
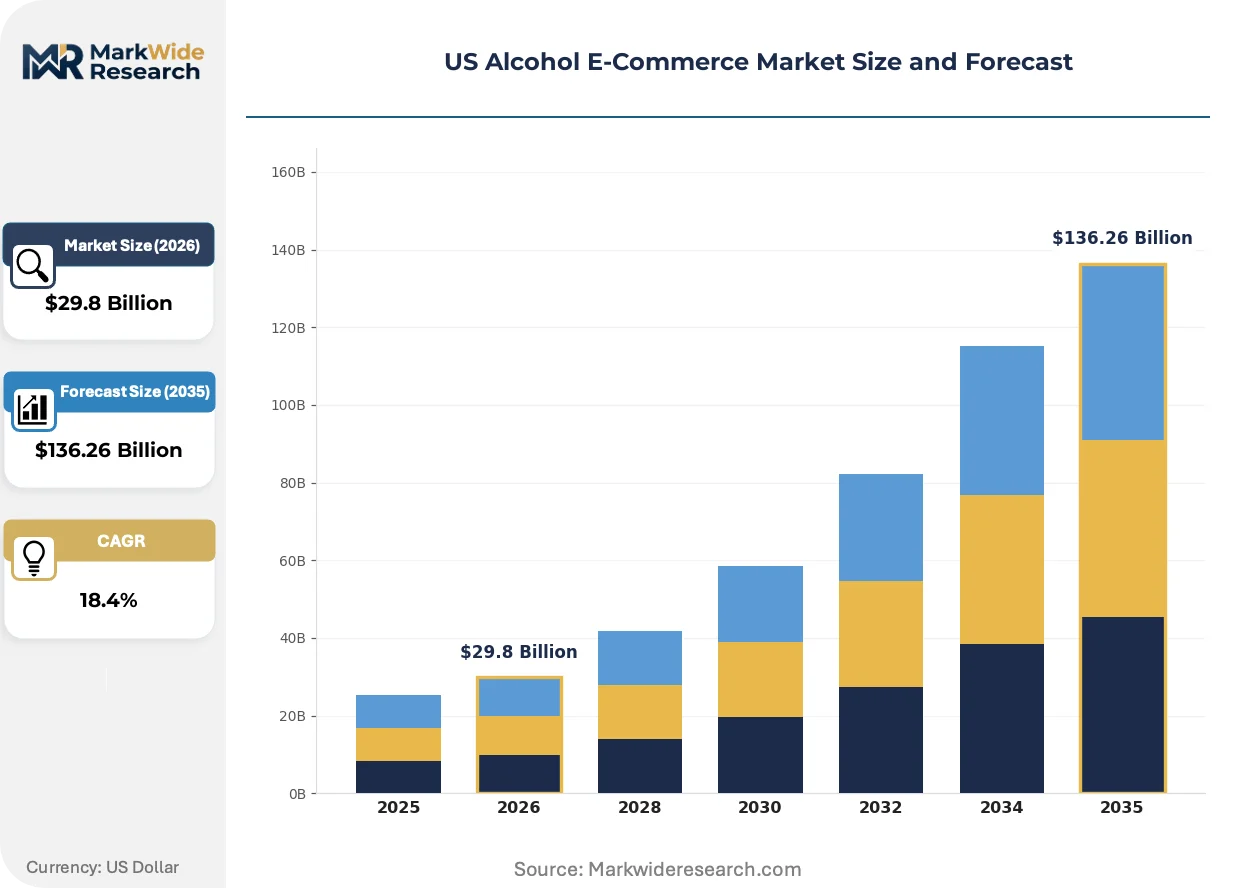
Market Dynamics
The three-tier distribution system's collision with direct-to-consumer shipping permissions is fragmenting fulfillment models across state lines, forcing platforms to maintain parallel compliance architectures for each jurisdiction's ABC board requirements.
Growth Catalysts
- Mobile-first purchasing behavior:Millennial and Gen X consumers complete transactions through native applications with embedded age-verification protocols, collapsing the discovery-to-delivery window.
- TTB label approval digitization:Electronic certificate of label approval processes accelerate product onboarding for marketplace operators seeking SKU breadth.
- California-Texas-Florida demand concentration:Population density intersects with relaxed interstate shipping statutes in these states, anchoring fulfillment network investments.
Market Restraints
- State-by-state permit fragmentation:Each ABC board maintains distinct direct-shipping thresholds and tax remittance schedules, multiplying administrative overhead.
- Temperature-controlled last-mile costs:Wine and spirits require specialized logistics infrastructure that generalist carriers cannot economically provision.
- Spirits shipping prohibition states:Seventeen jurisdictions maintain outright bans on direct-to-consumer spirits delivery, capping addressable market expansion.
Strategic Opportunities
- Subscription-based wine clubs:Recurring revenue models bypass per-transaction acquisition costs while building first-party customer data assets.
- Pending state legislative reforms:Direct-to-consumer spirits shipping bills under consideration in Pennsylvania and New York would unlock previously inaccessible demand pools.
- AI-powered personalization engines:Machine learning recommendation systems converge with inventory aggregation to surface hyper-local availability.
Industry Challenges
- Age-verification technology integration:Biometric and document-scanning systems must interface with legacy POS infrastructure at retail partner locations.
- Chain-of-custody documentation:TTB audit trails require real-time tracking integration across fragmented third-party delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Alcohol E-Commerce Market |
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $136.26 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Distribution Channel: Online Retailers, Direct-to-Consumer, Grocery Stores, Liquor Stores Customer Type: Millennials, Gen X, Baby Boomers, Event Planners Occasion: Celebrations, Regular Consumption, Gifts, Parties |
| Companies Covered | Drizly, Total Wine & More, Wine.com, Minibar Delivery, BevMo, Instacart, Amazon, Saucey, Vivino, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Alcohol E-Commerce Market Trends and Innovations
Platform operators are rearchitecting around regulatory technology investments rather than treating compliance as a cost center, embedding verification and documentation into core user experiences.
Blockchain-based provenance tracking is fragmenting supply chain transparency expectations. Wineries in Napa and Sonoma deploy distributed ledger systems to authenticate bottle lineage from vineyard to consumer. Premium collectors now demand cryptographic proof of storage conditions and ownership history, compressing margin for operators lacking such infrastructure.
State ABC boards in New Jersey and Illinois are piloting unified direct-shipping permit frameworks. These regulatory experiments reduce multi-state compliance burden for marketplace operators. Wine clubs and craft distilleries with limited legal resources benefit disproportionately from standardized application processes and reciprocal tax agreements.
Subscription bundling is displacing single-bottle transactions among urban millennials. Curated assortments replace individual selection, with algorithmic curation supplanting sommelier guidance. This pattern concentrates in metropolitan California markets where delivery density supports fixed-route optimization and reduced per-stop fulfillment costs.
US Alcohol E-Commerce Market Segmentation
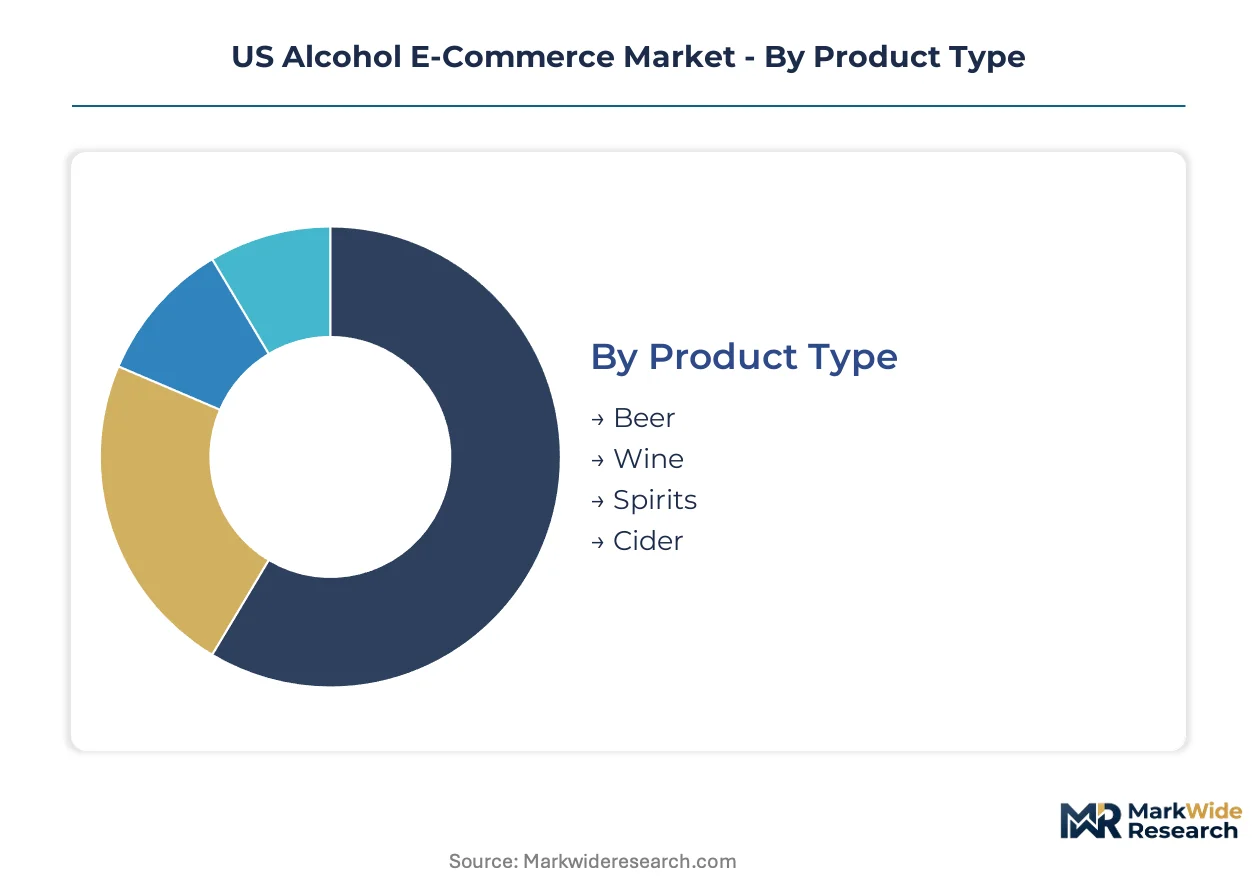
Segmentation in US alcohol e-commerce reveals how regulatory constraints and consumption patterns fragment addressable demand. Platform operators must architect distinct fulfillment pathways for each product category and channel combination to capture margin pools effectively.
Product Type:
Wine commands the highest per-unit margins and subscription attach rates, while spirits face the most restrictive interstate shipping regimes. Margin concentration follows product longevity and temperature sensitivity rather than volume throughput.
- Wine:Temperature-controlled logistics requirements and cellar-aging compatibility drive premium pricing tiers. California's Napa and Sonoma valleys anchor domestic supply, with direct-to-consumer shipping permits enabling first-party customer relationships outside three-tier distribution. Millennial subscription adoption concentrates in urban coastal markets where delivery density supports fixed-route optimization.
- Spirits:Higher proof-to-weight ratios reduce shipping costs per alcohol unit but trigger stricter ABC board scrutiny. Seventeen states maintain outright direct-shipping prohibitions, forcing marketplace operators to route orders through licensed retail intermediaries. Bourbon and American whiskey subcategories show strongest demand concentration in Texas and Florida.
- Beer:Perishable shelf life and weight-bulk economics favor local fulfillment networks over interstate shipping. Craft breweries leverage direct-to-consumer exceptions where state laws permit, though refrigerated last-mile costs compress margins versus wine and spirits.
- Cider:Seasonal consumption patterns and lower average order values challenge subscription model viability. Pacific Northwest production clusters supply national demand through hybrid retail-direct channels.
Wine holds installed capacity for recurring revenue extraction. Spirits is rotating up the share rankings as state legislative reforms expand direct-shipping permissions.
Distribution Channel:
Channel selection determines compliance burden intensity and customer data ownership rights. Direct-to-consumer pathways bypass wholesale markups but multiply permit administration costs across state jurisdictions.
- Direct-to-Consumer:Wineries and distilleries ship directly to legal-age consumers using TTB-compliant age-verification protocols. This channel captures full retail margin but requires state-by-state permit maintenance and tax remittance systems. Napa Valley operators pioneered the model, now expanding into spirits as state laws liberalize.
- Online Retailers:Marketplace aggregators like Drizly and Instacart connect local licensed retailers with consumers through mobile-first interfaces. These platforms absorb age-verification technology costs while earning transaction fees on third-party inventory. California and New York density supports same-hour delivery promises.
- Liquor Stores:Brick-and-mortar licensees extend reach through proprietary e-commerce sites and third-party platform partnerships. State ABC boards regulate delivery radius and hours of operation, creating geographic moats against pure-play digital competitors.
- Grocery Stores:Supermarket chains with existing alcohol licenses leverage click-and-collect infrastructure for beverage fulfillment. Texas and Florida permit grocery wine and beer sales, anchoring regional network investments.
Direct-to-Consumer holds installed capacity for margin capture. Online Retailers is rotating up the share rankings as marketplace aggregation reduces consumer search friction.
Customer Type:
Generational cohorts exhibit divergent platform preferences and price elasticities that reshape acquisition economics. Event-based purchasing concentrates in urban markets with same-day delivery infrastructure.
- Millennials:Mobile-native purchasing behavior favors app-based discovery with algorithmic curation replacing traditional sommelier guidance. This cohort shows highest subscription adoption rates and willingness to experiment with craft and premium tiers. California metropolitan areas concentrate demand density.
- Gen X:Balanced portfolio approach across established brands and emerging producers with moderate price sensitivity. This segment drives mid-tier wine club growth and values convenience over discovery. Texas suburban markets show strong representation.
- Baby Boomers:Established brand loyalty and higher average order values favor direct winery relationships over marketplace intermediation. This cohort requires more explicit age-verification reassurance during digital onboarding.
- Event Planners:Bulk purchasing for weddings and corporate functions demands flexible delivery windows and volume pricing. Seasonal demand spikes stress fulfillment capacity in Florida and California event corridors.
Millennials hold installed capacity for lifetime value extraction. Gen X is rotating up the share rankings as subscription models mature beyond early-adopter penetration.
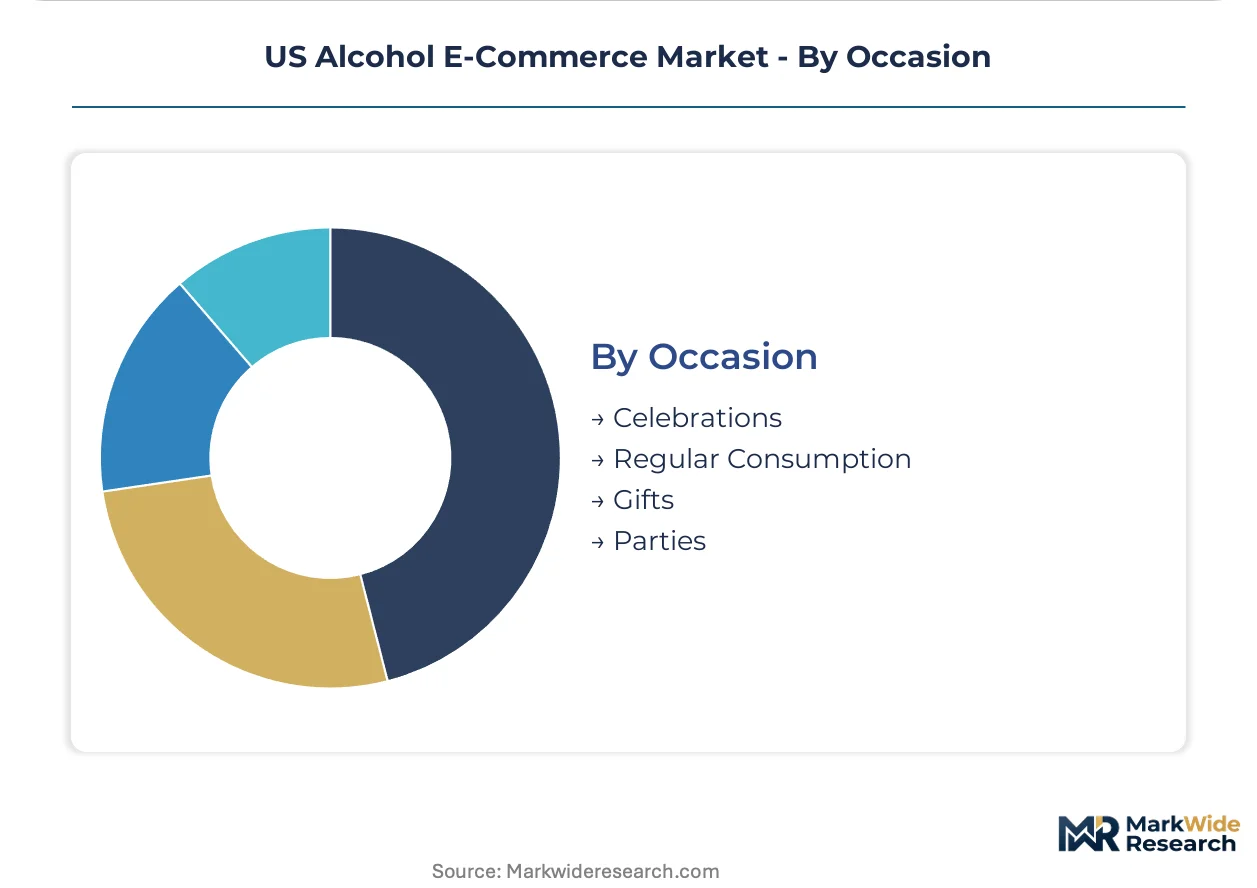
Occasion:
Occasion-based segmentation determines packaging configurations and delivery urgency requirements. Gift purchases command premium pricing but impose stricter presentation and timing standards.
- Regular Consumption:Replenishment-driven purchasing supports subscription revenue models with predictable fulfillment scheduling. Wine clubs and craft beer memberships concentrate in this occasion category with highest customer lifetime value potential.
- Gifts:Premium packaging and handwritten note services differentiate platform offerings. Holiday seasonal peaks require inventory pre-positioning and expanded customer service capacity. Corporate gifting programs in New York and California drive B2B channel development.
- Celebrations:Anniversary and milestone purchases favor sparkling wine and premium spirits with commemorative labeling options. Delivery timing precision matters more than price optimization.
- Parties:Volume purchasing for social gatherings demands multi-bottle discounts and ice bucket accessories. Impulse-driven with shorter decision windows, favoring platforms with fastest delivery promises.
Regular Consumption holds installed capacity for recurring revenue anchoring. Gifts is rotating up the share rankings as platform investments in presentation infrastructure reduce friction for premium occasion purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows into California and Texas fulfillment hubs outpace export shipments from domestic wine regions, creating net import dependence in consumption centers while Napa and Sonoma producers ship direct-to-consumer orders nationwide.
California
Napa Valley wineries and Los Angeles-based marketplace platforms generate the highest direct-to-consumer shipment volumes nationwide. The California Department of Alcoholic Beverage Control permits third-party delivery services to operate under licensed retailer partnerships, reducing regulatory friction for platform operators. San Francisco and Los Angeles metropolitan areas concentrate same-hour delivery infrastructure investments from Drizly and Instacart.
Texas
Urban centers in Dallas-Fort Worth and Houston drive spirits demand through relaxed direct-shipping statutes for wine and beer. The Texas Alcoholic Beverage Commission allows grocery retailers to hold wine and beer licenses, expanding click-and-collect fulfillment options. Austin's craft distillery cluster leverages direct-to-consumer exceptions to build first-party customer relationships outside traditional wholesale tiers.
Florida
Miami and Orlando event corridors generate seasonal demand spikes for bulk wine and spirits purchasing tied to wedding and corporate hospitality seasons. The Florida Division of Alcoholic Beverages and Tobacco maintains reciprocal shipping agreements with 14 states, simplifying multi-jurisdictional compliance for marketplace operators. Tampa Bay's craft brewery density supports local fulfillment network optimization for perishable beer shipments.
New York
The New York State Liquor Authority is considering direct-to-consumer spirits shipping legislation that would unlock previously inaccessible demand pools for bourbon and American whiskey producers. New York City anchors premium wine club subscription growth among millennial professionals. Finger Lakes wineries exploit direct-shipping permits to bypass three-tier markups in downstate markets.
Illinois
Chicago's metropolitan population density supports fixed-route delivery optimization and reduced per-stop fulfillment costs for subscription wine services. The Illinois Liquor Control Commission pilots unified direct-shipping permit frameworks that reduce multi-state compliance burdens for craft distilleries. Peoria and Rockford distribution centers serve as Midwest fulfillment hubs for interstate e-commerce shipments.
US Alcohol E-Commerce Market Competitive Landscape
Concentration sits with marketplace aggregators that intermediate between licensed retailers and consumers rather than holding inventory directly. The vendor base spans three strategic tiers: pure-play digital marketplaces, hybrid brick-and-click retailers with proprietary fulfillment networks, and generalist logistics platforms extending existing infrastructure into regulated categories. Competitive positioning hardens around regulatory technology investments and age-verification protocol sophistication. M&A activity targets last-mile delivery capabilities and state-level permit portfolios.
Within the marketplace aggregator tier, Drizly and Instacart occupy positions that exemplify the inventory-light model, connecting local licensed retailers with consumers through mobile-first interfaces. Total Wine & More anchors the hybrid strategy, pairing physical showroom networks with proprietary e-commerce fulfillment. Amazon sits within the generalist logistics extension archetype, leveraging Prime infrastructure where state direct-shipping laws permit.
| Leading Market Players |
|---|
| Drizly |
| Total Wine & More |
| Wine.com |
| Minibar Delivery |
| BevMo |
| Instacart |
| Amazon |
| Saucey |
| Vivino |
| Others |
Pricing and Supply Chain Analysis
Three-to-five-day age-verification processing windows compress inventory turns for marketplace operators while amplifying pricing power for vertically integrated wineries with captive fulfillment networks. This lead-time differential separates premium direct-to-consumer channels from aggregator models burdened by third-party compliance delays.
Pricing Analysis
Industrial OEM buyers anchor subscription-based recurring revenue models that bypass per-transaction acquisition costs. Three-tier pricing structure across premium, standard, and economy levels reflects state shipping permit access and temperature-controlled logistics bundling. Pricing pressure stems from refrigerated last-mile cost inflation as specialized carriers consolidate regional capacity. Event planners exhibit highest price sensitivity due to volume-driven negotiation leverage, while millennial subscribers show lowest elasticity for curated assortments.
Supply Chain Analysis
Napa Valley distribution capacity and Texas hub infrastructure anchor domestic fulfillment density for temperature-controlled wine shipments. California grape supply draws from Central Valley bulk contracts and Sonoma premium estates, while spirits sourcing rests on Kentucky bourbon cooperage and Florida molasses feedstock. Single-source vulnerability concentrates in specialized cold-chain carriers serving the final mile. Distribution runs through licensed retailer intermediaries in states with direct-shipping prohibitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US alcohol e-commerce sits in early-cycle expansion as direct-to-consumer spirits shipping bills advance through state legislatures, unlocking previously inaccessible demand pools for craft distilleries and premium bourbon producers.
For Market Incumbents: Compound regulatory technology investments into unified compliance architectures that collapse multi-state permit administration costs. Prioritize backward integration into temperature-controlled last-mile capacity to defend margin position against carrier consolidation. Monitor Pennsylvania and New York legislative calendars as inflection points for spirits shipping permissions. For New Entrants and Emerging Players: Lead with AI-powered personalization engines targeting millennial subscription adoption in California metropolitan corridors where delivery density supports fixed-route optimization. Exploit white-space in corporate gifting programs serving New York and Florida event corridors. Anchor go-to-market through sommelier-curated algorithmic bundles displacing traditional selection guidance. For Investors and Strategic Acquirers: Carve-out targets emerge from regional liquor store chains with underutilized e-commerce infrastructure and state permit portfolios. Frame long-term viability around regulatory arbitrage as state ABC boards pilot unified shipping frameworks. Watch Illinois and New Jersey permit standardization experiments as signals for platform scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Investment | Embedded age-verification protocols reduce compliance friction across fragmented ABC board requirements. |
| Temperature-Controlled Capacity Expansion | Captive cold-chain infrastructure insulates margins from specialized carrier consolidation pricing power. |
| Direct-to-Consumer Spirits Licensing | First-mover permits in reforming states unlock bourbon and American whiskey subscription revenue pools. |
| AI Personalization Engine Deployment | Algorithmic curation surfaces hyper-local inventory availability while reducing consumer search friction. |
| Subscription Model Migration | Recurring revenue structures bypass per-transaction acquisition costs and build first-party customer data assets. |
Research Methodology
Operator-level perspectives from marketplace platform executives, state ABC board administrators, winery direct-to-consumer directors, cold-chain logistics operators, and spirits distillery compliance officers anchored the qualitative base. Primary fieldwork combined with secondary validation from TTB label approval databases, state shipping permit registries, SEC 10-K filings of publicly traded beverage retailers, and Nielsen retail audit data. Bottom-up shipment volume estimates triangulated against top-down consumer expenditure surveys.
Sensitivity analysis across regulatory reform scenarios, carrier capacity constraints, and generational adoption curves informed the projection framework. Segmentation dimensions modeled include product type, distribution channel, customer cohort, and occasion-based purchasing patterns across the analysis window. CAGRs derived from historical shipment velocity adjusted for state-level legislative momentum and fulfillment network expansion timelines. Forecast inputs incorporated TTB label approval digitization trajectories and millennial mobile-first transaction migration rates.
The analysis sits within stated boundaries; outcomes outside sustained direct-to-consumer legislative liberalization or cold-chain infrastructure investment would require recalibration. Practitioners should keep alternative scenarios live as Pennsylvania and New York spirits shipping bill progressions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
China Tequila Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market