
 Frozen Fruit Bars Market | 2026-2036
Frozen Fruit Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Fruit Bars Market Analysis
Multi-pack bundling is recalibrating how households purchase frozen fruit bars, shifting volume from impulse single-serve toward planned pantry stocking. Unilever leverages its freezer logistics network to sustain dominant placement in mass retail. Nestlé S.A. anchors its portfolio through dairy-fruit hybrid formulations that command higher price points. JonnyPops differentiates via simplified ingredient panels that appeal to parent purchasers seeking transparency.
Frozen fruit bars are water-based or dairy-based frozen confections manufactured through blast freezing of fruit purees, juices, or cultured mixtures at temperatures below minus twenty degrees Celsius, designed for refreshment and portion-controlled snacking. Fruit puree formulations occupy the core volume position due to smoother texture profiles and extended shelf stability. Yogurt-based segments capture disproportionate margin pools as protein-fortified positioning commands retail premiums. Bulk pack configurations within the packaging type dimension concentrate institutional demand from schools and hospitality channels.
The FDA governs nutrition labeling and ingredient declarations for frozen desserts sold in the United States, while the USDA oversees fruit content claims through its standard of identity protocols. State-level dairy regulations in California and Wisconsin further constrain formulation choices for yogurt-based variants. Stakeholders must monitor evolving clean-label enforcement thresholds and freezer energy efficiency standards that will reshape manufacturing capital deployment decisions.
Market Dynamics
Reformulation pressure from the FDA's updated Nutrition Facts labeling requirements for added sugars is forcing manufacturers to rebuild ingredient decks while maintaining the sensory profiles consumers expect from frozen fruit bars.
Growth Catalysts
- Clean-label enforcement thresholds:The FDA's added-sugar disclosure mandates are accelerating ingredient simplification across the category. Reformulated products with transparent panels are capturing shelf space in conventional retail channels.
- Protein-fortified positioning:Yogurt-based formulations with elevated protein content are commanding retail premiums. Dairy-fruit hybrid products appeal to health-conscious households seeking functional snacking options.
- Institutional procurement expansion:Bulk pack configurations are concentrating demand from school nutrition programs and hospitality channels. Foodservice distributors are building dedicated frozen dessert SKUs for contract feeding operations.
Market Restraints
- Fruit puree input volatility:Concentrated strawberry and mango puree costs fluctuate with seasonal harvest yields in Mexico and Southeast Asia. Margin compression intensifies when tropical weather patterns disrupt supply.
- Freezer logistics concentration:Cold-chain distribution capacity clusters around Unilever's legacy freezer network in mass retail. New entrants face barrier-to-entry costs for securing comparable temperature-controlled shelf placement.
- State dairy regulation fragmentation:California and Wisconsin impose divergent standards of identity for yogurt-based variants. Multi-state manufacturers must maintain parallel formulation runs to achieve compliance.
Strategic Opportunities
- Underpenetrated convenience store channel:Frozen fruit bars remain underrepresented in petroleum retail and urban convenience formats. Impulse-oriented single-serve packaging could unlock incremental occasion-based consumption.
- Freezer energy efficiency standards:Emerging EPA commercial refrigeration mandates will reshape manufacturing capital deployment. Early adopters of low-GWP refrigerant systems may capture sustainability-driven retail procurement preferences.
- Functional ingredient convergence:Probiotic cultures and adaptogenic botanicals are converging with traditional fruit bar formats. Positioning at the intersection of refreshment and wellness could expand addressable occasions.
Industry Challenges
- Clean-label formulation expertise scarcity:Food scientists capable of delivering shelf-stable texture without conventional stabilizers command premium compensation. Recruitment competition from plant-based dairy segments intensifies talent acquisition costs.
- Blast freezing capex intensity:Temperatures below minus twenty degrees Celsius require specialized tunnel freezing equipment. Capacity expansion demands significant capital commitment with extended depreciation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Fruit Bars Market |
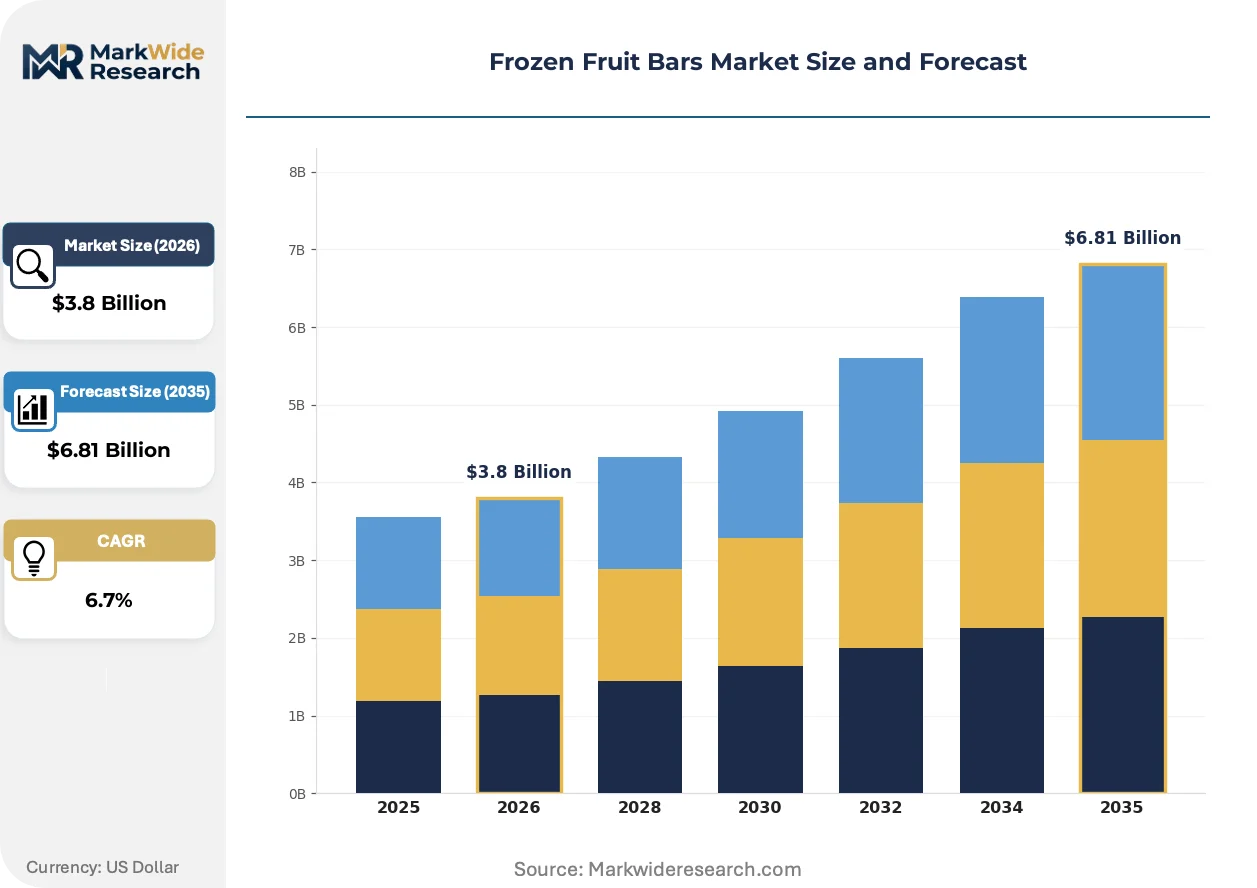
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Puree, Whole Fruit, Yogurt-Based, Non-Dairy Flavor Profile: Citrus, Berry, Tropical, Mixed Fruit Packaging Type: Single Serve, Multi-Pack, Bulk Pack, Value Pack Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service |
| Companies Covered | Unilever, J&J Snack Foods Corp., Nestlé S.A., Beyond Better Foods LLC, JonnyPops, Dreyer's Grand Ice Cream, Natural Fruit Corporation, Paleteria La Michoacana, Wells Enterprises, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Fruit Bars Market Emerging Trajectories
Ingredient transparency technology and reformulation science are converging to reshape how frozen fruit bars are formulated, labeled, and merchandised across retail environments.
High-pressure processing (HPP) is decentralizing the traditional thermal pasteurization infrastructure that has dominated frozen dessert manufacturing for decades. Premium natural-positioned brands are adopting HPP to preserve raw fruit flavor profiles without heat degradation. This technology is decentralizing production geography by enabling smaller-batch regional facilities to achieve shelf stability previously requiring centralized industrial scale.
The FDA's updated Nutrition Facts labeling requirements for added sugars are compelling systematic reformulation across the category. Manufacturers must now disclose added sugars separately from naturally occurring fruit sugars, creating compliance complexity for products using concentrated juices. Yogurt-based segments are most affected, as many existing formulations relied on added sugars to balance cultured tartness and are now rebuilding sweetness architectures.
Household pantry-stocking behavior is displacing impulse-driven single-serve purchasing in the frozen fruit bar category. Multi-pack bundling formats are capturing volume as consumers plan snack inventories rather than making point-of-freezer decisions. This shift is most visible in United States conventional retail channels, where club store configurations and promotional multi-buy pricing have trained shoppers toward bulk acquisition patterns.
Frozen Fruit Bars Market Segmentation
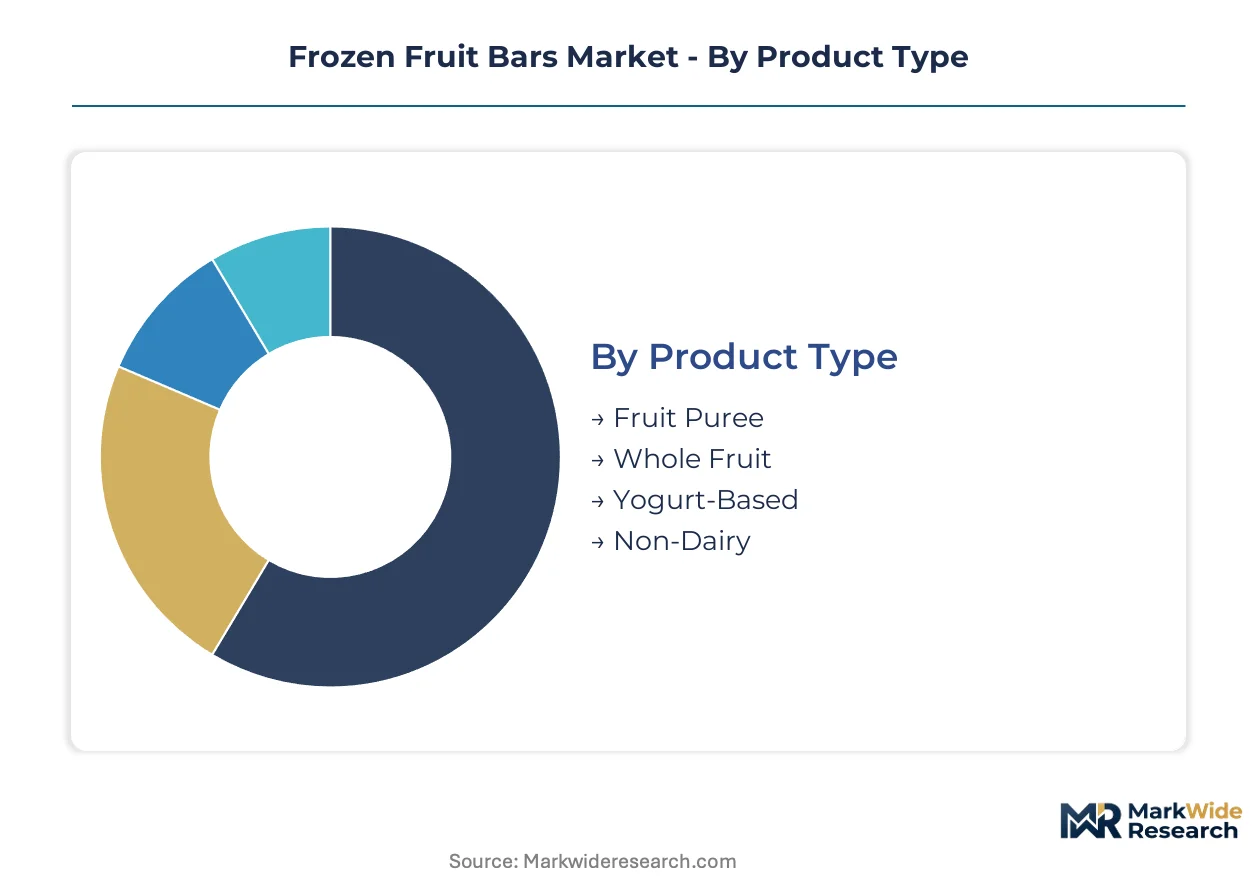
Frozen fruit bars demand heterogeneous manufacturing configurations across segments. Capital allocation decisions vary sharply between water-based and dairy-based production lines. Understanding segment-specific investment thresholds enables precise capacity planning and margin defense.
Product Type:
Blast freezing infrastructure requirements differentiate capital intensity across formulations. Tunnel freezing equipment for dairy-based variants demands stainless steel compliance and CIP systems that pure water-based lines avoid.
- Fruit Puree:Formulations blend concentrated fruit purees with water and stabilizers before blast freezing at sub-minus-twenty-degree temperatures. United States conventional retail channels concentrate volume here as smoother texture profiles drive repeat purchase. Shelf stability advantages reduce cold-chain spoilage rates versus whole fruit alternatives.
- Yogurt-Based:Cultured dairy-fruit hybrids require protein fortification and active culture maintenance through freezing. Premium positioning in health-conscious households commands retail price multiples. California and Wisconsin dairy regulations impose parallel formulation compliance costs on multi-state manufacturers.
- Whole Fruit:Chunk-inclusion formats suspend fruit pieces in juice bases. Texture variability limits institutional procurement adoption.
- Non-Dairy:Coconut cream and oat milk bases serve lactose-intolerant and vegan positioning. Emerging plant-based dairy segments intensify ingredient sourcing competition.
Most installed capacity flows through Fruit Puree. Expansion is steepest in Yogurt-Based.
Flavor Profile:
Raw material sourcing geography determines working capital intensity across flavor families. Tropical variants tie up inventory in longer supply chains from Southeast Asia and Mexico.
- Citrus:Lemon, lime, and orange formulations leverage concentrated juice infrastructure with year-round supply stability. Florida and California growing regions anchor North American sourcing. Lower input volatility supports predictable margin structures.
- Berry:Strawberry, raspberry, and blueberry purees command premium positioning in parent-targeted clean-label portfolios. Pacific Northwest and Mexican harvest cycles create seasonal procurement windows. Anthocyanin stability challenges require accelerated freeze processing post-harvest.
- Tropical:Mango, pineapple, and passion fruit formulations depend on Southeast Asian and Latin American supply. Weather pattern disruption in Thailand and Mexico concentrates margin risk.
- Mixed Fruit:Blended profiles balance cost and complexity across multiple supply origins. Formulation flexibility enables rapid response to single-commodity price spikes.
Volume concentrates in Berry. Citrus is climbing the fastest as supply reliability attracts procurement preference.
Packaging Type:
Packaging line automation requirements scale with bundle configuration complexity. Multi-pack formats demand collation and wrapping systems absent in single-serve operations.
- Multi-Pack:Four-to-twelve count configurations dominate United States club store and conventional retail promotional activity. Household pantry-stocking behavior has trained shoppers toward bulk acquisition patterns. Secondary packaging materials represent significant per-unit cost component.
- Bulk Pack:Institutional configurations serve school nutrition programs and hospitality channels. Foodservice distributors build dedicated frozen dessert SKUs around contract feeding operations. Extended thaw windows require modified stabilizer systems.
- Single Serve:Individual wrapper formats target impulse and convenience store channels. Petroleum retail penetration remains underdeveloped relative to ice cream novelty formats.
- Value Pack:Economy-positioned large counts compete on price-per-ounce metrics. Margin compression limits branded manufacturer participation.
Procurement is shifting toward Multi-Pack. Bulk Pack is gaining share fastest in institutional channels.
Distribution Channel:
Cold-chain logistics infrastructure requirements vary by channel service level. Foodservice demands frozen transport compliance that retail direct-store-delivery networks already maintain.
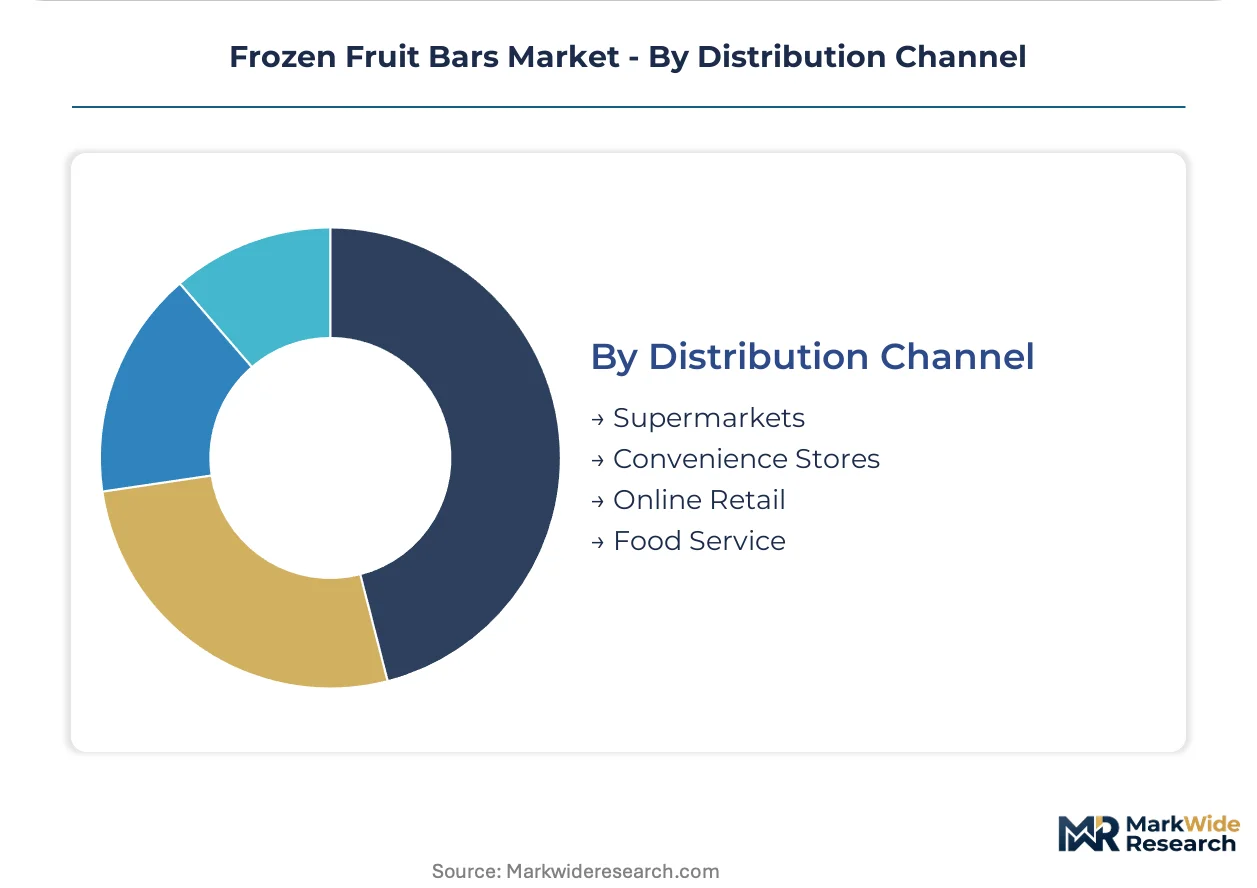
- Supermarkets:Conventional retail channels concentrate United States volume through dedicated freezer door placements. Unilever's legacy freezer logistics network sustains dominant shelf space allocation. Promotional calendar dependency creates revenue seasonality.
- Food Service:Contract feeding and hospitality procurement operates on bid-based annual agreements. Bulk pack configurations align with institutional portion control requirements.
- Convenience Stores:Petroleum retail and urban convenience formats remain underpenetrated for frozen fruit bars. Impulse-oriented single-serve packaging could unlock occasion-based consumption expansion.
- Online Retail:Direct-to-consumer frozen shipping requires insulated packaging and dry ice investment. Last-mile cold-chain reliability constraints limit geographic reach.
Revenue concentrates in Supermarkets. Food Service is expanding most quickly as institutional procurement builds dedicated SKUs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The frozen fruit bar industry traces its commercial origins to mid-twentieth-century California, where citrus processing infrastructure first enabled mass-market water-based frozen confections. Distribution networks radiated outward from West Coast freezer logistics hubs, establishing the United States as the foundational market for category development and premium natural-positioned brand proliferation.
United States
Conventional retail channels concentrate volume through dedicated freezer door placements in supermarkets and club stores. The FDA's updated Nutrition Facts labeling requirements for added sugars are compelling systematic reformulation across domestic manufacturing operations. California and Wisconsin dairy regulations impose parallel compliance costs on yogurt-based variant producers operating across state lines.
Mexico
Tropical fruit puree supply chains anchor procurement from Michoacán and Jalisco growing regions for North American processing facilities. Mexican harvest cycles for strawberry and mango concentrates create seasonal procurement windows that influence working capital intensity. Paleteria La Michoacana exemplifies regional brand architecture that has expanded into United States Hispanic market channels through authentic flavor positioning.
Canada
Health Canada and the PMRA govern ingredient declarations and pesticide residue thresholds for imported fruit concentrates entering Canadian retail distribution. British Columbia and Ontario cold-chain logistics networks support multi-pack bundling formats in club store channels. Canadian consumers demonstrate elevated preference for clean-label ingredient panels relative to United States benchmarks.
Germany
The EFSA and EU Green Deal sustainability frameworks are reshaping freezer energy efficiency standards for commercial refrigeration equipment deployed across German retail. Bavaria and North Rhine-Westphalia host dairy-fruit hybrid formulation expertise concentrated in established European frozen dessert manufacturing clusters. German consumers prioritize organic certification and reduced-sugar positioning in frozen confection procurement decisions.
Japan
METI standards and JIS certification protocols govern commercial refrigeration equipment deployed in Japanese convenience store and supermarket channels. Kanto and Kansai industrial corridors concentrate blast freezing infrastructure for premium fruit bar export production. Japanese distribution emphasizes single-serve impulse formats in petroleum retail and urban convenience formats with limited freezer door allocation.
Frozen Fruit Bars Market Vendor Landscape
Premium-margin players sit above commodity-margin players across ingredient transparency and freezer logistics infrastructure dimensions. The vendor base organizes into three structural tiers: multinational conglomerates with captive cold-chain networks, mid-cap natural-positioned specialists, and regional private-label fabricators. Strategic archetypes include clean-label transparency specialists, dairy-fruit hybrid innovators, and freezer logistics scale operators. Dominant competitive moves center on multi-pack bundling format expansion and high-pressure processing technology licensing for regional production decentralization.
Among multinational conglomerates, Unilever and Nestlé S.A. occupy positions as freezer logistics scale operators with legacy mass retail placement. JonnyPops exemplifies the clean-label transparency specialist archetype through simplified ingredient panel positioning. These three companies represent distinct strategic vectors: Unilever anchors volume through conventional retail channel penetration, Nestlé S.A. commands premium positioning through dairy-fruit hybrid formulations, and JonnyPops captures parent-targeted demand through transparency-focused brand architecture.
| Leading Market Players |
|---|
| Unilever |
| J&J Snack Foods Corp. |
| Nestlé S.A. |
| Beyond Better Foods LLC |
| JonnyPops |
| Dreyer's Grand Ice Cream |
| Natural Fruit Corporation |
| Paleteria La Michoacana |
| Wells Enterprises, Inc. |
| Others |
Supply Flow & Price Mechanics
Club store procurement concentration in the United States anchors a three-tier pricing structure across premium, standard, and economy levels. The shift toward multi-pack bundling has compressed per-unit margins while expanding volume commitments that lock in shelf space allocation.
Pricing Analysis
Premium-mid-economy pricing differentiation separates yogurt-based protein-fortified variants from fruit puree core offerings and private-label value packs. Price differentiation hinges on clean-label certification status and freezer door placement tier. Cost compression in the value tier is intensifying because Mexican strawberry puree input volatility has compressed branded manufacturer participation. Foodservice distributors demonstrate lowest price sensitivity due to annual contract structures, while convenience store operators remain most responsive to promotional allowances.
Supply Chain Analysis
Regional distribution centers in California, Wisconsin, and Texas form a hub-and-spoke pattern that feeds conventional retail freezer networks. Geographic supply concentration centers on Mexico and Thailand for tropical fruit purees, with Pacific Northwest berry concentrates drawing from domestic harvest cycles. Raw material dependencies rest on concentrated mango and strawberry purees plus blast freezing equipment sourced from specialized industrial fabricators. Single-source vulnerability in Southeast Asian passion fruit supply creates margin risk during monsoon disruption periods. Distribution runs through Unilever's legacy cold-chain infrastructure that new entrants cannot replicate without capital intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen fruit bar market compounds steadily as health-conscious pantry-stocking behavior displaces impulse purchasing and locks in recurring revenue streams.
For Market Incumbents: Anticipate reformulation cost escalation from FDA added-sugar disclosure mandates by securing captive supply of high-pressure processing equipment. Deepen backward integration into Mexican and Thai fruit puree sourcing to defend margin position against input volatility. Prioritize certification investment in organic and clean-label standards to maintain premium tier pricing power against emerging transparency specialists.
For New Entrants and Emerging Players: Urban convenience store operators represent an underserved buyer archetype with minimal frozen fruit bar penetration relative to ice cream novelty formats. Target petroleum retail channels with single-serve impulse packaging configurations that bypass incumbent freezer logistics concentration. Pursue direct-store-delivery partnerships with regional foodservice distributors as the most penetrable path to institutional procurement contracts.
For Investors and Strategic Acquirers: Mid-cap consumer packaged goods conglomerates are the most active acquirer in this space, seeking clean-label brand architectures to retrofit into existing freezer logistics networks. The acquisition target archetype combines simplified ingredient panel positioning with regional production decentralization capability. Watch high-pressure processing technology licensing velocity as the inflection indicator for production geography fragmentation that reshapes competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Licensing | Enables regional production decentralization that challenges Unilever's centralized cold-chain dominance. |
| Clean-Label Certification Investment | Captures parent-targeted demand as FDA enforcement thresholds harden ingredient transparency requirements. |
| Convenience Store Channel Expansion | Unlocks impulse occasion growth in petroleum retail formats where frozen fruit bars remain underrepresented. |
| Protein-Fortified Formulation R&D | Commands retail premiums through yogurt-based positioning that appeals to functional snacking households. |
| Backward Integration into Puree Sourcing | Defends margins against Mexican and Thai harvest volatility that disrupts tropical flavor supply. |
Methodological Framework
Direct dialogue with frozen dessert brand managers, supermarket category buyers, foodservice procurement directors, and blast freezing equipment engineers grounded the qualitative foundation. Secondary validation drew from FDA enforcement guidance documents, USDA fruit content claim protocols, Nielsen retail audit data, and customs records of concentrated puree imports. Bottom-up and top-down triangulation reconciled manufacturer shipment data with channel inventory velocity patterns.
Bottom-up modeling traced unit economics through formulation cost structures, packaging line configurations, and freezer logistics cost per case. Segmentation dimensions spanned product type, flavor profile, packaging configuration, and distribution channel across the analysis window. CAGRs emerged from curve-fitting historical volume trajectories against projected pantry-stocking behavior shifts and institutional procurement expansion. Forecast inputs incorporated HPP technology adoption curves and EPA commercial refrigeration mandate compliance timelines.
Underlying measurement precision varies by segment; yogurt-based and multi-pack configurations carry tighter precision than whole fruit and single-serve alternatives due to concentrated manufacturer disclosure. Forecasts reflect documented assumptions about clean-label enforcement trajectory and freezer energy efficiency standard implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Shrimp Market