
 Ice Cream and Frozen Dessert Market | 2026-2036
Ice Cream and Frozen Dessert Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream and Frozen Dessert Market Outlook
European dairy processors is shifting toward higher-margin superpremium output as energy costs reshape frozen dessert economics. Unilever leverages its global manufacturing footprint to sustain volume leadership across multiple continents. Nestlé anchors its position through R&D intensity in reduced-sugar and plant-based formulations. Froneri International Limited specializes in licensed brand production, occupying a distinct niche between proprietary and co-manufactured portfolios.
Ice cream and frozen dessert denotes a frozen dairy or dairy-alternative product typically containing milk fat, sweeteners, emulsifiers, and air overrun between 20% and 100%, manufactured via continuous freezing and hardening processes for direct consumer consumption. The product type dimension shows bars and sandwiches capturing margin pools through portion-controlled pricing, while cups dominate volume throughput in supermarket freezers. Distribution channel dynamics reveal food service recovering faster than retail as away-from-home consumption patterns reassert, though online retail competes aggressively on subscription and direct-to-consumer novelty formats.
The FDA governs standard of identity rules for ice cream in the United States, while the EFSA evaluates novel food ingredients entering European frozen dessert formulations, and the FSSAI enforces microbiological safety thresholds across India's expanding cold-chain distribution network. These frameworks collectively elevate compliance costs for new entrants while rewarding incumbents with established quality management systems. Stakeholders must monitor evolving sugar taxation regimes and labeling mandates as these policies increasingly determine which formulations achieve shelf placement and price positioning.
Market Dynamics
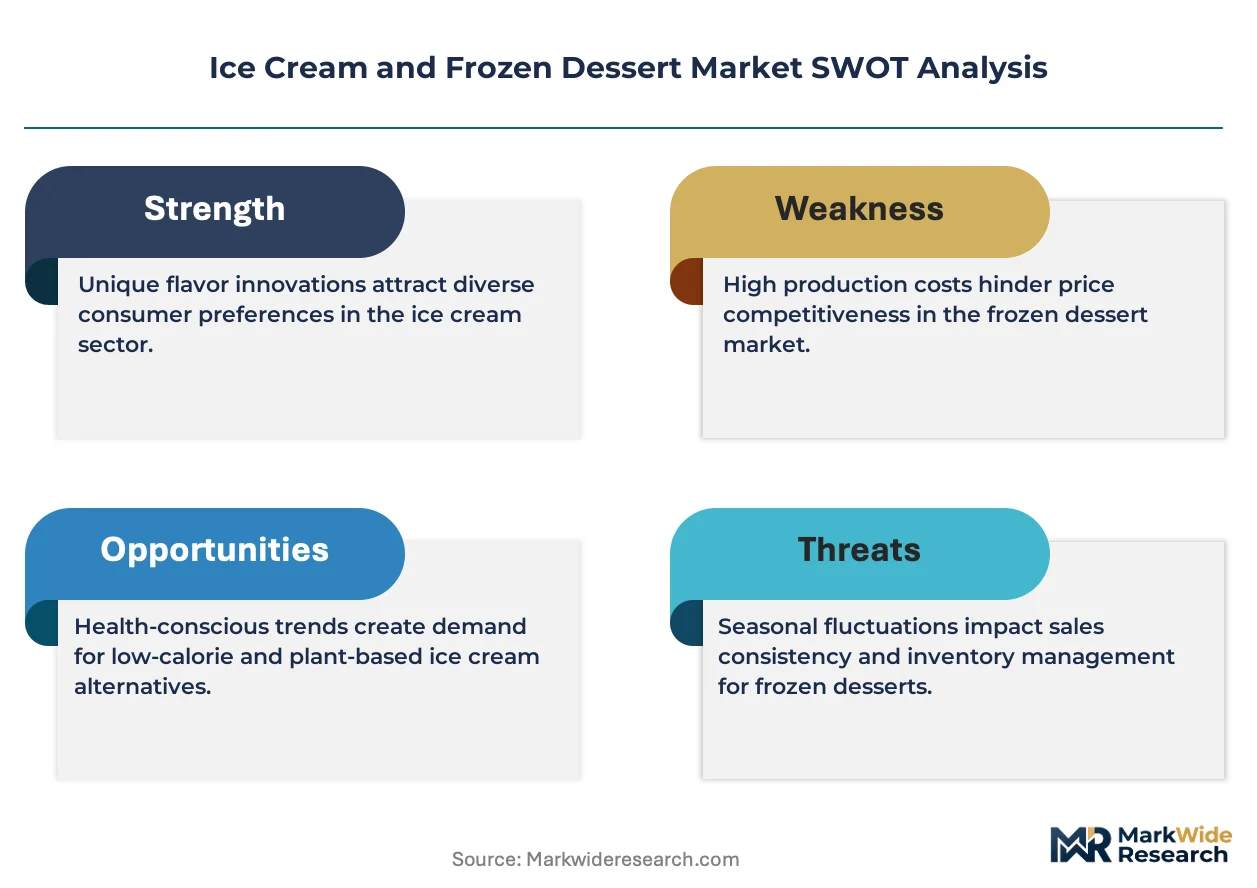
Clean-label mandates from the FDA and EFSA are compressing formulation cycles while energy costs restructure manufacturing footprints across dairy-dependent regions.
Growth Catalysts
- Plant-based formulation R&D:Nestlé and Froneri International Limited accelerate reduced-sugar and dairy-alternative pipelines to capture shifting dietary preferences in Western markets.
- Grab-and-go format expansion:Quick-service restaurant operators enlarge frozen dessert menus as away-from-home consumption patterns reassert post-pandemic norms.
- EFSA novel food pathways:Accelerated approval timelines for innovative stabilizers and alternative proteins enable faster European product launches.
Market Restraints
- Dairy input cost volatility:Milk fat and cream price swings compress margins for superpremium manufacturers dependent on high-overrun formulations.
- Cold-chain infrastructure gaps:India's FSSAI enforcement of microbiological thresholds faces last-mile refrigeration deficits in tier-two and tier-three cities.
- Clean-label compliance burden:Shorter ingredient declaration requirements force reformulation investments that disadvantage smaller regional processors.
Strategic Opportunities
- Subscription direct-to-consumer channels:Online retail platforms compete aggressively on novelty formats, bypassing traditional supermarket freezer slot constraints.
- Licensed brand production models:Co-manufacturing arrangements allow mid-tier processors to access premium brand equity without proprietary R&D overhead.
- India's cold-chain buildout:Central government infrastructure schemes create first-mover advantages for operators establishing hardened distribution networks.
Industry Challenges
- Refrigeration technician scarcity:Specialized cold-chain maintenance skills lag behind freezer fleet expansion in emerging markets.
- Continuous freezing equipment capex:High-capacity scraped-surface heat exchangers require substantial capital commitments that strain balance sheets.
- Multi-jurisdiction label harmonization:Divergent FDA, EFSA, and FSSAI disclosure rules complicate unified packaging strategies for multinational portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream and Frozen Dessert Market |
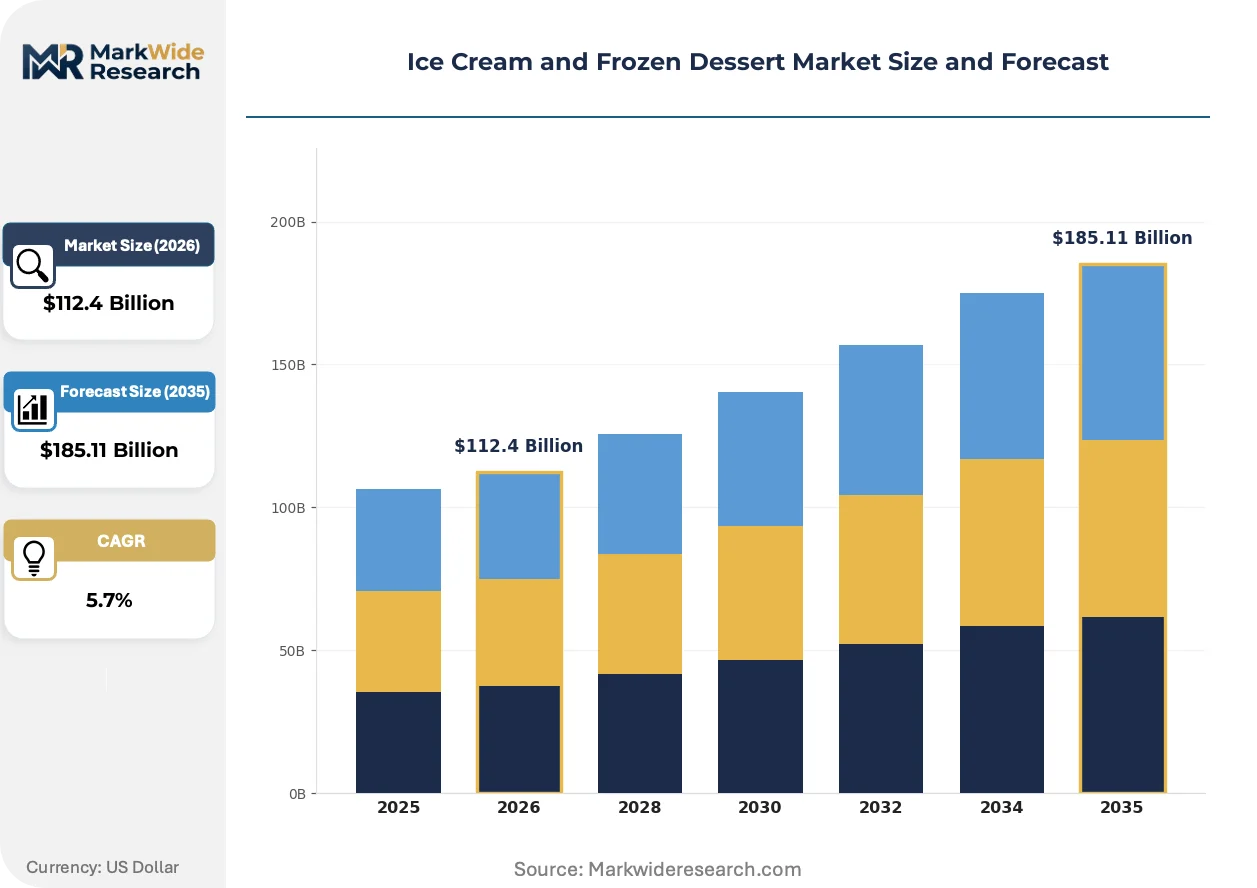
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $185.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cups, Cones, Bars, Sandwiches Flavor Profile: Chocolate, Vanilla, Strawberry, Mint Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Consumer Age Group: Children, Teenagers, Adults, Seniors |
| Companies Covered | Unilever, Nestlé, Froneri International Limited, Blue Bell Creameries, Wells Enterprises, General Mills, Mars, Winward Brands, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream and Frozen Dessert Market Strategic Shifts
Formulation science and distribution architecture are undergoing simultaneous transformation as regulatory pressure meets evolving consumption rituals.
Precision fermentation-derived dairy proteins are rewriting the cost structure of premium frozen desserts. Specialty manufacturers in the United States integrate these inputs to achieve mouthfeel parity with conventional milk fat at reduced ingredient cost. The technology is compressing the price gap between plant-based and dairy superpremium segments.
REACH restrictions on synthetic emulsifiers are forcing European processors toward lecithin and natural gum alternatives. Reformulation timelines have extended by eight to fourteen months as EFSA evaluates novel stabilizer safety dossiers. Superpremium cup formats face the steepest technical hurdles in maintaining texture profiles.
Portion-controlled single-serve formats are displacing bulk family containers in supermarket freezers. Bars and sandwiches capture margin pools through unit pricing while cups retain volume throughput. This rotation is most visible in United States coastal markets where convenience-store penetration exceeds national averages.
Ice Cream and Frozen Dessert Market Segmentation
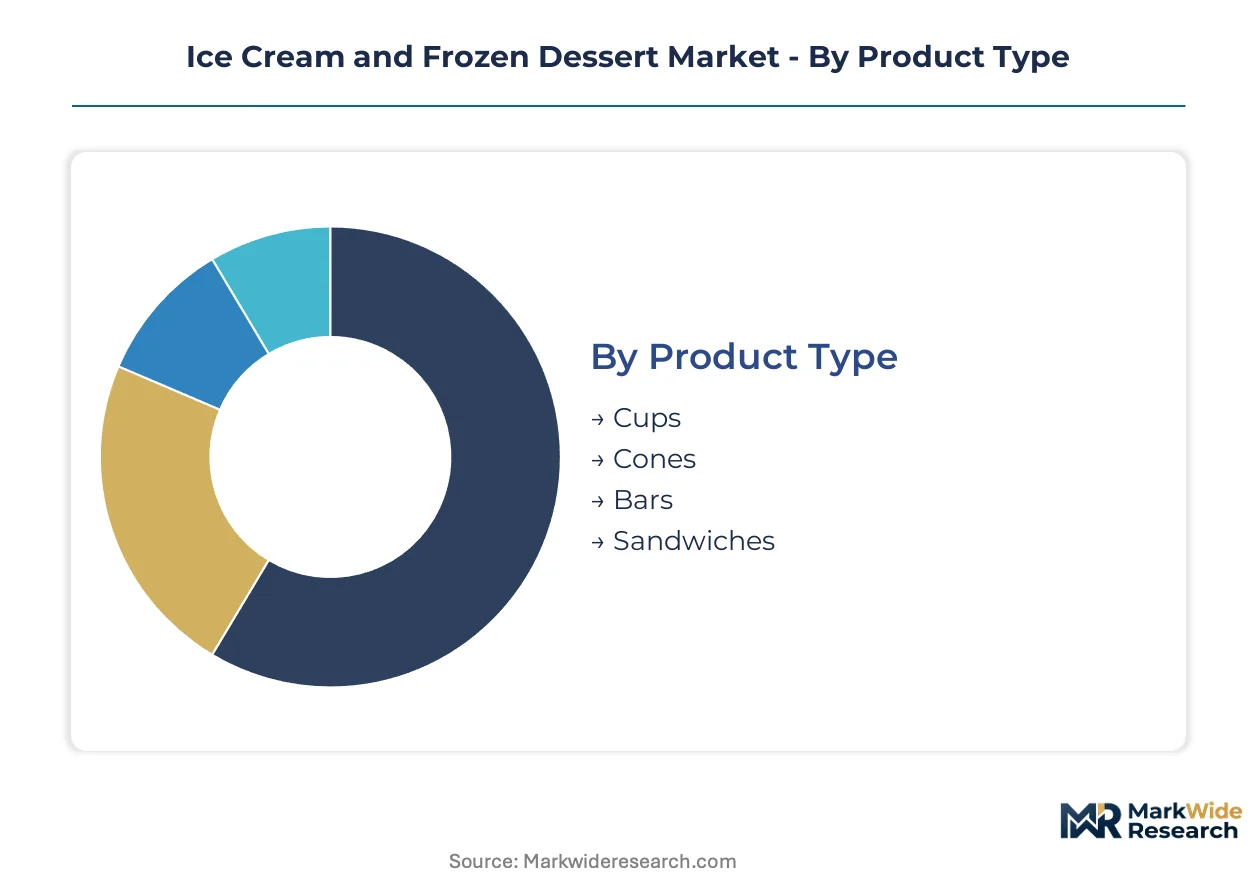
Segmentation in frozen desserts reveals how formulation, format, and channel economics split margin capture across distinct consumer occasions. Manufacturers align production assets to these divisions because freezer space and impulse purchase behavior vary sharply by segment.
Product Type:
Standalone consumption formats dominate grab-and-go channels, while embedded formats rely on complementary purchase contexts.
- Cups:Single-serve vessels with 80-120ml standard fill volumes accommodate premium mix-in layers and textured toppings. Demand clusters in United States supermarket freezers where family multi-packs drive volume throughput. FDA labeling requirements for net content disclosure favor standardized cup sizes.
- Bars:Stick-mounted formats with stick-in-mold freezing enable portion-controlled pricing and extended ambient handling windows. Coastal United States convenience stores favor these for coastal commuter traffic and beach-adjacent impulse purchases. Clean-label stabilizer migration challenges texture retention in reduced-fat formulations.
- Cones:Pre-filled wafer or sugar cone formats integrate edible packaging with product delivery. European QSR chains deploy these for handheld consumption without auxiliary serving ware.
- Sandwiches:Cookie or wafer-enclosed layers require dual-texture stability across freeze-thaw cycles. Food service operators in India favor these for portion consistency in institutional catering contracts.
Volume placements concentrate in Cups; the faster expansion belongs to Bars.
Flavor Profile:
Flavor selection tracks ingredient cost structures and regional dairy heritage, with premium positioning achievable through sourcing narrative rather than formulation complexity.
- Chocolate:Cocoa butter and cocoa powder inputs tie pricing to commodity futures volatility. United States superpremium brands differentiate through single-origin cacao percentages. EFSA novel food pathways enable European processors to experiment with fermented cocoa alternatives.
- Vanilla:Natural extract from Madagascar Bourbon or Tahitian orchids commands 40-60x synthetic vanillin pricing. Indian manufacturers face FSSAI enforcement on artificial flavor declaration thresholds. Clean-label mandates in Western markets accelerate natural extract adoption despite cost premiums.
- Strawberry:Fruit preparation inclusions require pH balancing to prevent dairy protein destabilization. Seasonal sourcing windows in California and Florida concentrate processing capacity.
- Mint:Peppermint oil concentration determines cooling sensation intensity and shelf-life stability. Limited artisanal production in Pacific Northwest supplies specialty manufacturers.
Vanilla commands the broadest demographic penetration; chocolate captures the steepest expansion trajectory in premium tiers.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin structure, with direct-to-consumer formats requiring fundamentally different logistics architectures.
- Supermarkets:Multi-door freezer banks with 20-30 SKU facings per brand demand slotting fee negotiations and promotional calendar coordination. United States coastal markets show highest private-label superpremium penetration. Energy costs reshape refrigeration economics for regional chains.
- Food Service:Dispensed soft-serve and pre-scoped formats recover faster than retail as away-from-home patterns reassert. Quick-service restaurant operators expand dessert menus for check-average enhancement.
- Convenience Stores:Limited freezer door count favors high-velocity single-serve formats with 90-day inventory turns. Urban India shows rapid freezer fleet expansion despite technician scarcity.
- Online Retail:Subscription and direct-to-consumer novelty formats bypass traditional slotting constraints. Dry ice and insulated packaging add 15-25% to landed cost versus retail.
Supermarkets anchor volume throughput; online retail gains share fastest in novelty and subscription formats.
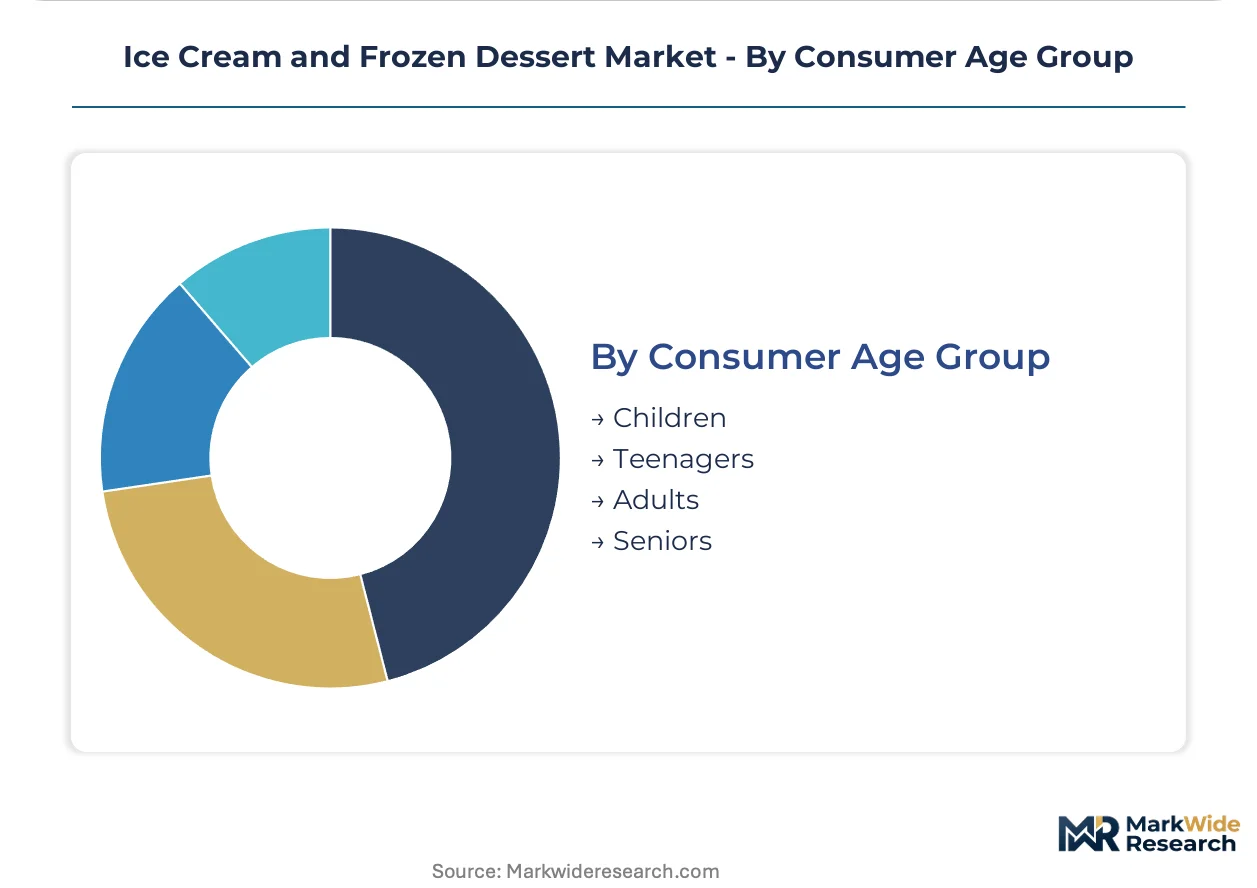
Consumer Age Group:
Age-targeted formulation adjusts sweetness perception, portion sizing, and functional positioning across life-stage nutritional priorities.
- Children:Bright colorants and character licensing drive purchase influence, with parents moderating sugar content acceptance. European REACH restrictions on synthetic dyes force natural pigment reformulation.
- Teenagers:Social media shareability and limited-edition collaborations generate trial and frequency. United States coastal markets show highest responsiveness to influencer-led flavor drops.
- Adults:Reduced-sugar and protein-fortified variants align with wellness positioning. Nestlé R&D intensity targets this segment with functional ingredient integration.
- Seniors:Smaller portion formats and softer texture profiles accommodate dental constraints and reduced caloric requirements. Indian urban centers show emerging demand as cold-chain penetration reaches aging populations.
Adults generate the highest per-capita expenditure; teenagers drive the fastest frequency gains through novelty-seeking behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin dairy belt milk solids anchor North American frozen dessert formulation economics, while European butterfat and Asian palm kernel oil derivatives shape regional cost structures and texture profiles across distinct cold-chain maturity levels.
United States
Premium artisanal demand and private-label superpremium expansion drive shelf-space competition in coastal urban markets. FDA standard-of-identity enforcement on milk fat minimums constrains plant-based labeling claims. Midwest dairy processing clusters around Wisconsin and Minnesota concentrate high-overrun manufacturing capacity serving national distribution networks.
Germany
Energy cost restructuring favors superpremium output migration toward higher-margin formulations. EFSA novel food ingredient pathways accelerate alternative protein stabilizer approvals. Bavarian dairy cooperatives leverage regional butterfat supply chains for export-oriented frozen dessert production.
India
Tier-one urban cold-chain expansion enables branded frozen dessert penetration beyond traditional kulfi distribution. FSSAI microbiological safety thresholds enforce quality standards across fragmented last-mile networks. Maharashtra and Gujarat processing hubs scale hardened distribution infrastructure toward tier-two cities.
United Kingdom
Grab-and-go format adoption accelerates through convenience-store freezer fleet expansion. REACH synthetic emulsifier restrictions force natural stabilizer reformulation cycles. London metropolitan retail density supports direct-to-consumer subscription model trials for premium novelty formats.
Brazil
Tropical climate consumption patterns sustain year-round demand without seasonal troughs. ANVISA food additive regulations govern imported stabilizer approvals for multinational formulation transfers. São Paulo state industrial dairy clusters integrate açai and regional fruit inclusions for differentiated export positioning.
Ice Cream and Frozen Dessert Market Competitive Environment
Global majors compete with regional champions across formulation technology and cold-chain reach, producing a tiered structure where scale-driven volume players, premium specialists, and licensed-brand co-manufacturers occupy distinct margin pools. Three archetypes dominate: integrated dairy processors with captive milk fat supply, R&D-intensive wellness formulators targeting reduced-sugar segments, and flexible co-manufacturers leveraging licensed brand equity. Capacity expansion and portfolio diversification toward plant-based alternatives represent the dominant competitive vectors reshaping manufacturing footprints.
Within the integrated multinational tier, Unilever and Nestlé exemplify scale-driven global reach anchored in diversified frozen dessert portfolios, while Froneri International Limited occupies a specialized position between proprietary brand ownership and licensed production arrangements. These entities represent the competitive spectrum from captive supply chain control through outsourced manufacturing flexibility.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| Froneri International Limited |
| Blue Bell Creameries |
| Wells Enterprises |
| General Mills |
| Mars |
| Winward Brands |
| Dairy Farmers of America |
| Others |
Value Chain & Pricing Dynamics
Clean-label mandates from the FDA and EFSA are forcing manufacturers toward shorter ingredient declarations and natural stabilizers, compelling supply chain restructuring around certified clean-label input suppliers and compressing margins for processors unable to secure volume commitments on premium dairy fractions.
Pricing Analysis
Service bundling separates equipment leasing from ingredient supply in food service contracts, while retail channels favor unbundled per-unit transactional pricing. Three-tier pricing structure across premium, standard, and economy levels tracks butterfat percentage and overrun ratios. Price differentiation hinges on organic certification tier and geographic delivery cost to cold-chain endpoints. Cost compression in superpremium tiers is intensifying because precision fermentation dairy proteins are eroding traditional milk fat premiums. Private-label buyers in United States coastal markets show highest price sensitivity; artisanal direct-to-consumer channels show least.
Supply Chain Analysis
Single-source vulnerability sits with Madagascar vanilla orchid cultivation and Wisconsin dairy belt milk fat concentration. Supply concentration spans the United States, Germany, and India for processing capacity, while New Zealand and the Netherlands anchor dairy solids exports. Raw material dependencies include cocoa butter, palm kernel oil derivatives, and natural gum stabilizers. Tariff exposure on Southeast Asian stabilizer imports threatens margin structures for European processors. Distribution runs through refrigerated third-party logistics networks with freezer fleet consolidation in tier-one urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over milk fat supply and precision fermentation protein capacity determines margin capture. Players are pursuing backward integration into dairy solids and alternative protein feedstocks to defend formulation cost positions.
For Market Incumbents: To counter precision fermentation entrants eroding traditional dairy premiums, secure long-term offtake agreements with Wisconsin and Bavarian dairy cooperatives for milk fat supply. Deepen backward integration into natural stabilizer cultivation through contract farming arrangements in Madagascar and Indonesia. Expand hardened cold-chain infrastructure in Indian tier-two cities before competitor freezer fleet buildout. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable channel for bypassing supermarket slotting fee barriers. Target United States coastal markets with precision fermentation-derived superpremium formats that achieve mouthfeel parity at reduced ingredient cost. White-space exists in India's tier-two urban centers where FSSAI enforcement is tightening but last-mile refrigeration remains underdeveloped. Pursue licensed brand co-manufacturing arrangements to access premium brand equity without proprietary R&D overhead. For Investors and Strategic Acquirers: The window for entry favors flexible co-manufacturers with licensed brand portfolios and established cold-chain networks. Long-term viability across the projection horizon rests on positioning for plant-based and reduced-sugar formulation transitions. Acquisition target archetype: mid-tier processors with captive stabilizer supply relationships and EFSA novel food approval experience. Watch for inflection where precision fermentation protein costs cross below conventional dairy solids pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Integration | Rewrites cost structure of premium frozen desserts by achieving milk fat mouthfeel parity at reduced input cost. |
| Cold-Chain Infrastructure Buildout | Creates first-mover advantage in Indian tier-two cities where FSSAI enforcement meets last-mile refrigeration gaps. |
| Licensed Brand Co-Manufacturing Expansion | Allows mid-tier processors to access premium brand equity without proprietary R&D overhead or slotting fee commitments. |
| Natural Stabilizer Reformulation Investment | Addresses REACH restrictions on synthetic emulsifiers while maintaining texture profiles in superpremium cup formats. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional supermarket freezer slot constraints and captures novelty-seeking consumer segments in coastal United States markets. |
Study Parameters
Trade association filings, customs records, and regulatory submission databases formed the secondary backbone for this analysis. Primary interviews with frozen dessert brand managers, category buyers at United States supermarket chains, cold-chain logistics operators, and EFSA regulatory affairs specialists combined with secondary validation across FDA standard-of-identity rulings and FSSAI microbiological safety guidelines. Bottom-up volume modeling triangulated against top-down value estimates from industry revenue disclosures.
Historical trendline analysis of milk fat pricing volatility and stabilizer cost trajectories informed the analytical framework. Segmentation dimensions modeled include product format, flavor profile, distribution channel, and consumer age group across the projection horizon. CAGRs derived from regression analysis of volume throughput and value capture by segment. Industry-specific forecast inputs incorporated energy cost restructuring in European dairy processing and precision fermentation protein adoption curves.
Caveats apply where dairy input cost volatility, EFSA novel food approval delays, or Indian cold-chain infrastructure buildout pace could materially shift the outlook. Forecasts reflect assumptions on clean-label compliance timelines and plant-based formulation adoption rates. Deviation in precision fermentation protein cost curves or FSSAI enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Frozen Meat and Fish Market