
 Middle East and Africa Freeze-Dried Product Market | 2026-2036
Middle East and Africa Freeze-Dried Product Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Freeze-Dried Product Market Foresight
Procurement strategy across the Middle East and Africa freeze-dried product sector is shifting from single-source European imports toward multi-source regional and Asian supply arrangements. Paradise Fruits leverages its Mediterranean sourcing network to compete on berry and tropical fruit lines. Almarai anchors dairy-adjacent freeze-dried portfolios through its captive Saudi distribution infrastructure. Emirates Freeze Dried Foods controls UAE-based manufacturing capacity that extends into Gulf Cooperation Council markets with shorter lead times than European competitors.
Freeze-dried products in the Middle East and Africa are dehydrated materials preserved through sublimation at pressures below 6.1 mbar and shelf temperatures typically ranging from -40°C to -50°C, yielding moisture content below 3% and shelf stability exceeding 12 months without refrigeration; this process serves commercial buyers seeking lightweight, nutrient-retentive ingredients for prepared meals, pharmaceuticals, and expeditionary food systems. The fruits segment leads volume throughput due to established date, fig, and strawberry processing lines across Egypt and Morocco, while healthcare applications in hospital nutrition and active pharmaceutical ingredient stabilization represent the fastest-growing margin pool. Retail and convenience food channels are maturing in South Africa and Nigeria, though specialty stores still capture premium pricing for organic-certified and single-origin freeze-dried offerings.
Saudi Food and Drug Authority standards for packaged food labeling and nutrient claims shape product formulation requirements for entrants targeting the Kingdom's hospitality and healthcare sectors. EAC-EA standards harmonization across East African Community member states is simplifying cross-border trade for Kenyan and Tanzanian processors. South Africa's Department of Health regulations on ready-to-use therapeutic foods directly govern freeze-dried emergency nutrition procurement by UN agencies and NGOs operating in the Horn of Africa. Stakeholders must monitor evolving halal certification protocols and energy subsidy reforms across Gulf states, as these will determine which production technologies achieve cost parity against imported European alternatives.
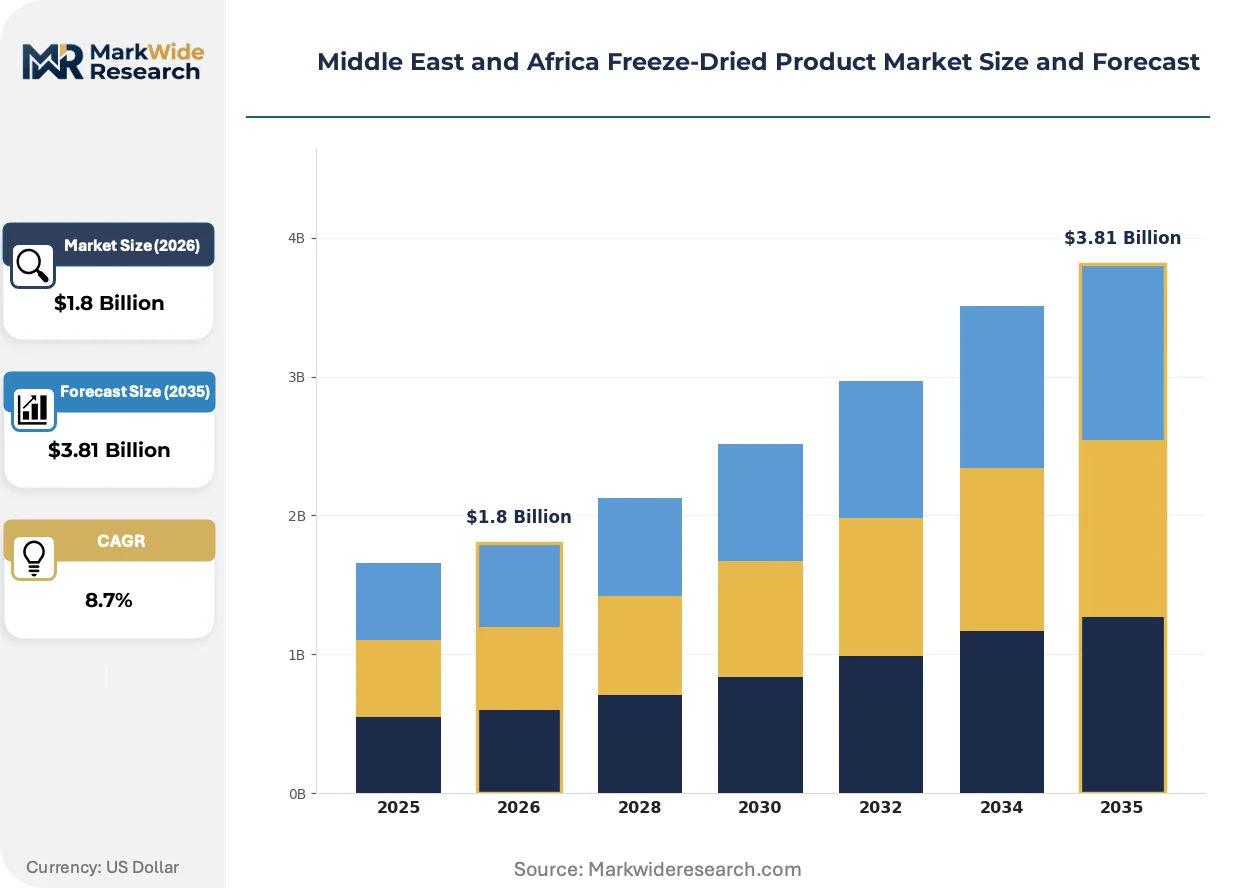
Market Dynamics
Saudi Arabia's food security mandates and UAE hospitality investment are redirecting procurement from European single-source supply toward regional manufacturing networks with shorter lead times and halal-certified output.
Growth Catalysts
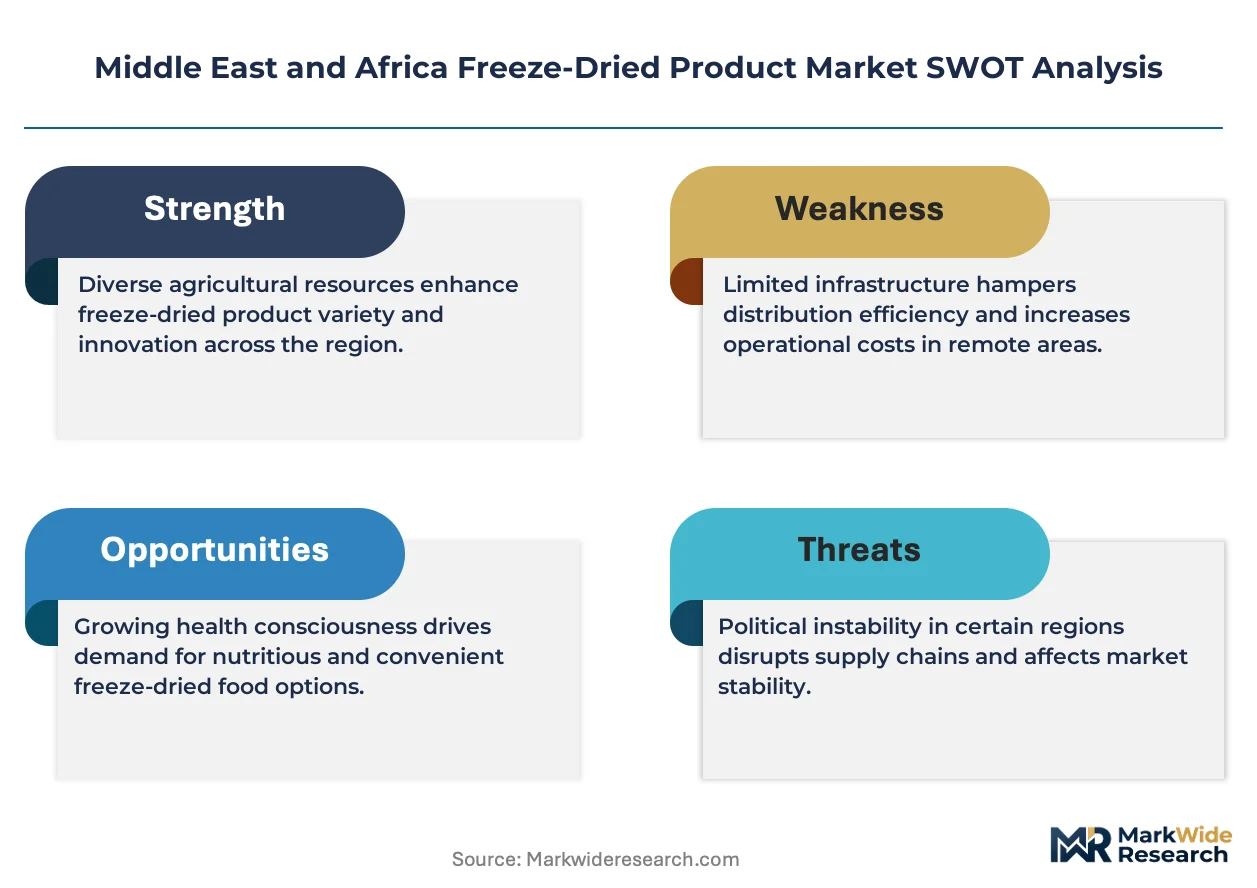
- SFDA packaged food standards:The Saudi Food and Drug Authority's labeling and nutrient claim requirements are accelerating domestic formulation capabilities as foreign entrants localize production to meet hospitality and healthcare sector specifications.
- Military and emergency food services:Defense procurement across Gulf Cooperation Council states and UN agency operations in the Horn of Africa are expanding volume commitments for lightweight, shelf-stable nutrition products.
- Energy-efficient sublimation systems:Advances in vacuum chamber technology are compressing unit production costs for regional manufacturers, narrowing the cost gap against imported European alternatives.
Market Restraints
- Input energy cost volatility:Freeze-drying's intensive electricity demands expose regional producers to subsidy reform risks across Gulf states where industrial power tariffs structure manufacturing economics.
- European equipment supplier concentration:Vacuum chamber and condenser system fabrication remains concentrated among German and Italian engineering firms, creating lead time and currency exposure for African and Middle Eastern processors.
- Dehydration and retort substitution:Alternative preservation methods retain cost advantages for commodity fruit and vegetable applications where nutrient density commands less price premium.
Strategic Opportunities
- Nigerian retail channel development:Convenience food infrastructure maturation in Lagos and Abuja creates first-mover positioning for branded freeze-dried snack and ingredient lines ahead of supermarket consolidation.
- Active pharmaceutical ingredient stabilization:Healthcare applications in hospital nutrition and drug formulation represent margin expansion potential as regional pharmaceutical manufacturing scales under localization policies.
- EAC-EA standards harmonization:East African Community cross-border trade simplification enables Kenyan and Tanzanian processors to aggregate supply across multiple member state sourcing zones.
Industry Challenges
- Halal certification protocol fragmentation:Divergent approval timelines and audit requirements across Gulf state Islamic authorities complicate multi-market product registration for regional suppliers.
- Cold chain integration complexity:Pre-freeze logistics coordination with fragmented African agricultural collection networks creates quality variability and throughput constraints for fruit processing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Freeze-Dried Product Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meat, Seafood Application: Food Processing, Healthcare, Retail, Convenience Foods End User: Hotels, Restaurants, Hospitals, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Paradise Fruits, Almarai, Nestle SA, Al Kabeer Group, Emirates Freeze Dried Foods, Asahi Group Holdings Ltd, Thrive Life LLC, Sunspray Food Ingredients, Harmony House Foods Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Freeze-Dried Product Market Shifts & Advancements
Technology convergence between pharmaceutical-grade lyophilization and food processing equipment is compressing equipment cost curves while regulatory harmonization and procurement model evolution reshape competitive entry pathways.
Radio-frequency-assisted freeze-drying is expanding into commercial fruit and dairy applications across North African processing facilities. Egyptian and Moroccan date and fig processors are adopting hybrid systems that reduce primary drying duration by integrating electromagnetic heating with conventional vacuum sublimation. The technology is expanding into mid-scale regional manufacturers previously priced out of pharmaceutical-grade equipment tiers, enabling capacity expansion without European turnkey project dependency.
SFDA and MOHAP alignment on packaged food labeling standards is streamlining multi-market registration for Gulf-targeting suppliers. The Saudi Food and Drug Authority and UAE Ministry of Health and Prevention have converged nutrient claim verification protocols, reducing duplicate testing burdens for hospitality sector ingredient vendors. Hospital nutrition and therapeutic food procurement by UN agencies now navigates unified documentation requirements, accelerating supplier qualification timelines for East African processors seeking Gulf market access.
Consolidated hospitality procurement through Saudi sovereign wealth-backed hotel development is compressing supplier qualification cycles and favoring multi-year framework agreements over spot purchasing. The Kingdom's giga-project developments are aggregating demand for freeze-dried ingredients across thousands of projected foodservice outlets, shifting vendor selection criteria toward guaranteed volume scalability and captive regional production capacity rather than European brand recognition.
Middle East and Africa Freeze-Dried Product Market Segmentation
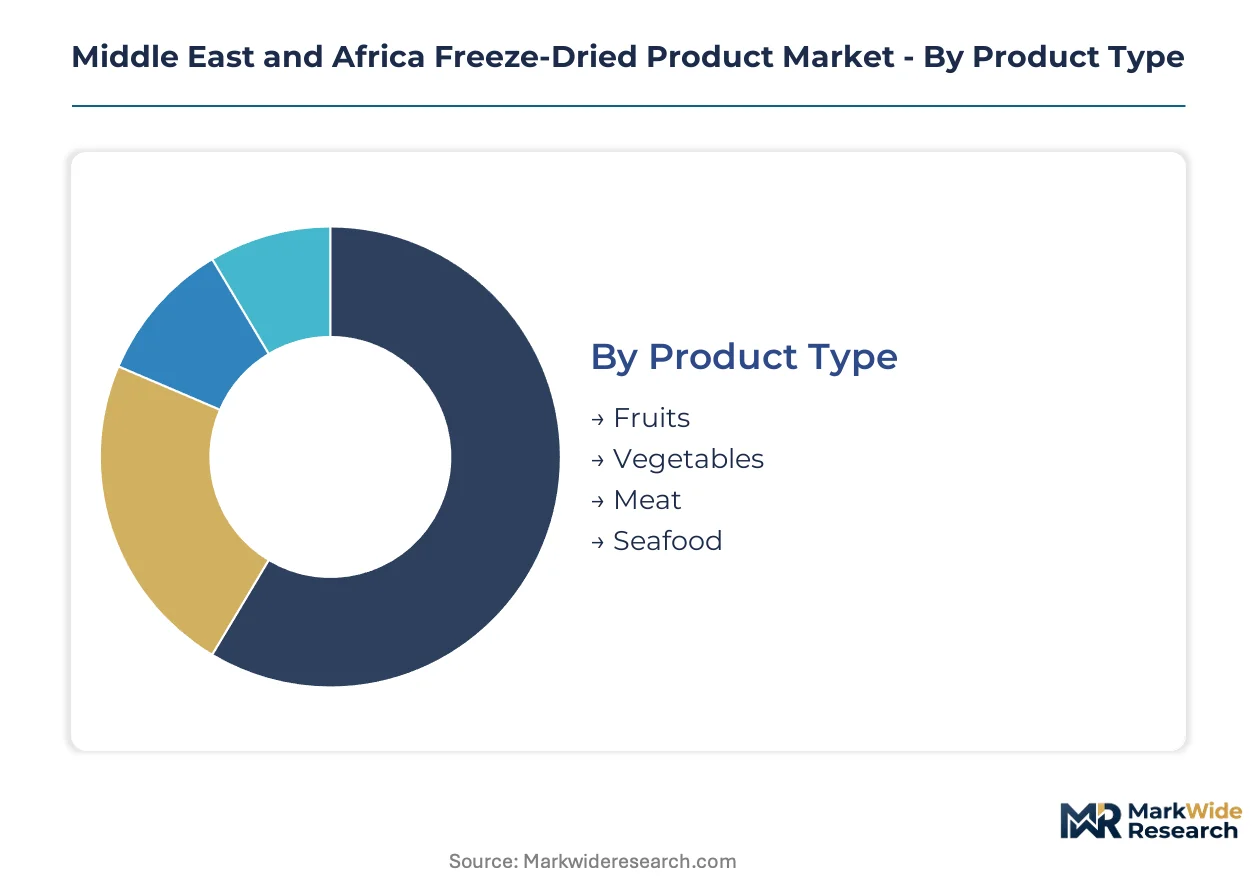
Freeze-dried product procurement patterns diverge sharply across customer types and channels, with hospitality buyers prioritizing shelf stability and volume scalability while healthcare purchasers emphasize nutrient retention specifications. Understanding these segment boundaries enables suppliers to align formulation investments with margin concentration zones.
Product Type:
Fruits dominate volume throughput through established date and fig processing lines, while meat commands premium positioning through halal certification requirements.
- Fruits:Dehydrated berries, dates, figs, and tropical varieties processed at moisture content below 3% serve prepared meal manufacturers and retail snack channels. Egyptian and Moroccan processors anchor regional supply through strawberry and date lines, with Saudi hospitality procurement driving volume commitments for rehydration-ready ingredients.
- Vegetables:Sublimation-preserved tomatoes, peppers, and leafy greens retain color and micronutrient profiles superior to air-dried alternatives. South African hospital nutrition programs source vegetable blends for therapeutic food formulations, though input cost volatility constrains margin expansion.
- Meat:Halal-certified freeze-dried poultry and beef strips supply military ration packs and expeditionary food systems across Gulf Cooperation Council defense procurement.
- Seafood:Dried shrimp and fish protein concentrates target niche pharmaceutical and specialty nutrition applications with limited regional processing infrastructure.
Today's leader: Fruits. Tomorrow's challenger: Meat.
Application:
Commercial processing absorbs bulk volume while healthcare applications concentrate margin capture through regulatory certification barriers.
- Food Processing:Ingredient inputs for ready-meal manufacturing, bakery fillings, and beverage flavor systems constitute the largest demand pool. UAE-based hospitality suppliers procure freeze-dried fruit pieces for dessert and pastry applications across giga-project hotel developments.
- Healthcare:Hospital nutrition, therapeutic foods, and active pharmaceutical ingredient stabilization command price premiums through SFDA and WHO compliance requirements. UN agency procurement for Horn of Africa emergency nutrition programs runs through South African formulation facilities.
- Retail:Branded snack lines and single-origin organic offerings reach consumers through specialty stores in Lagos and Abuja, with supermarket consolidation threatening first-mover positioning.
- Convenience Foods:Instant meal kits and on-the-go nutrition products target Nigerian urban professionals, though cold chain gaps limit fresh-to-freeze input quality.
Healthcare commands the steepest expansion trajectory. Food Processing retains volume dominance.
End User:
Institutional buyers leverage procurement scale while household penetration remains nascent outside South African metro areas.
- Hotels:Saudi sovereign wealth-backed developments aggregate demand across thousands of projected foodservice outlets, favoring suppliers with captive regional production capacity.
- Restaurants:Fine-dining and fast-casual chains in Dubai and Riyadh source freeze-dried garnishes and flavor concentrates for menu consistency.
- Hospitals:Enteral nutrition and therapeutic food procurement follows WHO and national health department specifications, with Kenyan processors qualifying for East African Community cross-border supply.
- Households:Direct consumer purchases concentrate in South African specialty retail and Nigerian e-commerce channels, limited by price positioning against conventional dried alternatives.
Hotels anchor institutional volume. Households offer penetration upside.
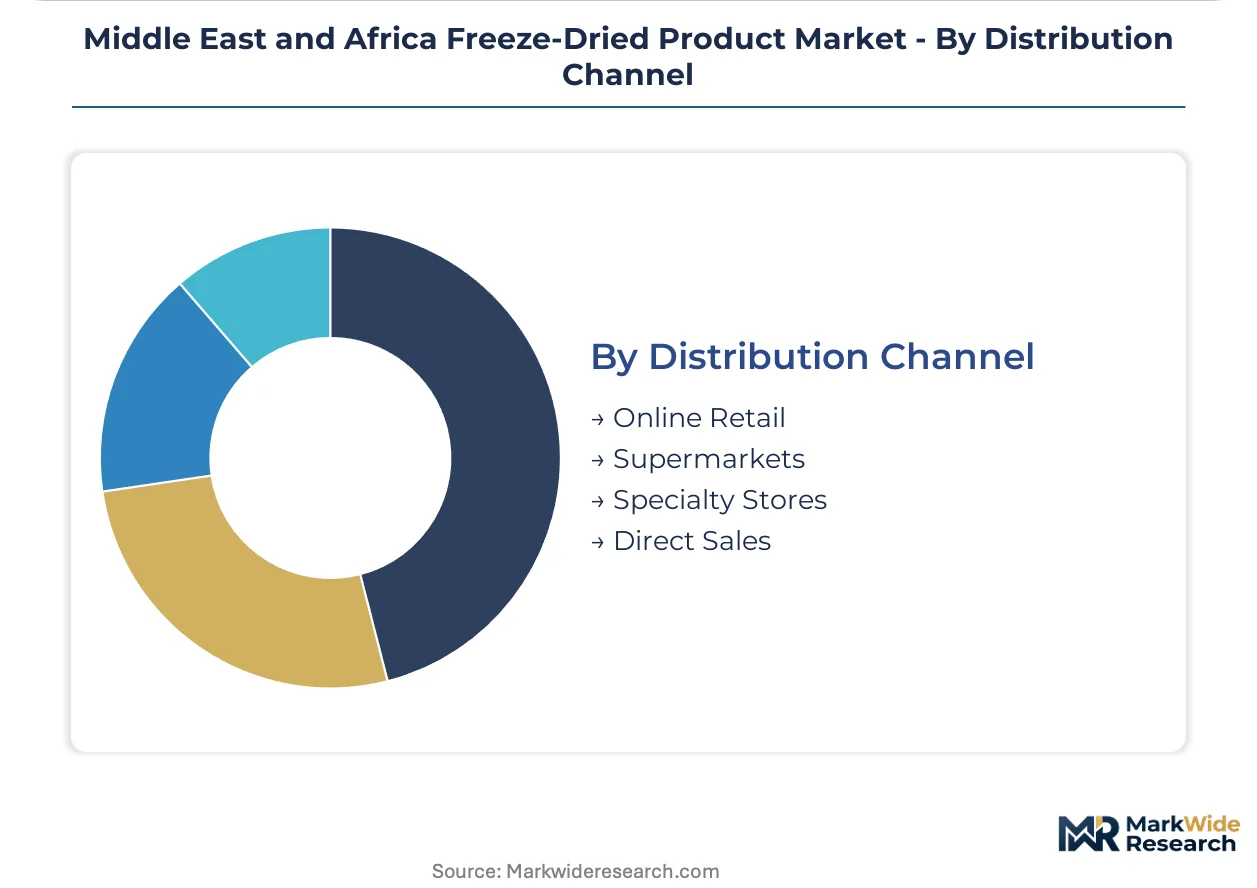
Distribution Channel:
Direct sales capture hospitality procurement while online retail fragments across platform-specific logistics capabilities.
- Online Retail:Jumia and regional e-commerce platforms serve Nigerian and Kenyan consumers, though last-mile cold chain reliability constrains premium positioning.
- Supermarkets:South African chains Pick n Pay and Shoprite stock branded freeze-dried snacks, with shelf space allocation favoring established European imports.
- Specialty Stores:Organic-certified and single-origin offerings command premium pricing in Dubai and Cape Town boutique retail, targeting expatriate and affluent local consumers.
- Direct Sales:Multi-year framework agreements with Saudi giga-project developers and UAE hotel groups bypass distributor margins, requiring suppliers to maintain dedicated account management infrastructure.
Direct Sales secure institutional lock-in. Online Retail scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's giga-project developments and UAE hospitality investment anchor regional demand concentration, with procurement gravity shifting toward captive manufacturing capacity across the Gulf Cooperation Council corridor.
Saudi Arabia
Neom and Red Sea Project developments aggregate freeze-dried ingredient demand across thousands of projected foodservice outlets. SFDA packaged food labeling standards accelerate domestic formulation capabilities as foreign suppliers localize production. Riyadh-based processing facilities are expanding to serve hospitality sector procurement with halal-certified output and shortened lead times.
United Arab Emirates
Dubai and Abu Dhabi hotel groups drive premium ingredient procurement for pastry and dessert applications across luxury hospitality portfolios. MOHAP alignment with SFDA on nutrient claim verification reduces duplicate testing burdens for multi-market suppliers. Emirates Freeze Dried Foods anchors UAE-based manufacturing capacity extending into Gulf Cooperation Council markets.
Egypt
Date and fig processing lines concentrate volume throughput for European and Gulf export markets. The country's national food safety regulator governs export certification requirements for agricultural derivatives. Cairo and Nile Delta agricultural collection networks supply feedstock to freeze-drying facilities serving regional rehydration-ready ingredient demand.
South Africa
Hospital nutrition programs and UN agency procurement for Horn of Africa emergency food systems drive therapeutic formulation demand. The Department of Health regulates ready-to-use therapeutic food specifications governing NGO procurement. Cape Town and Gauteng industrial zones host formulation facilities qualifying for East African Community cross-border supply.
Nigeria
Lagos and Abuja convenience food infrastructure maturation creates first-mover positioning for branded snack and ingredient lines. The country's national food and drug administration oversees packaged food registration requirements for imported and locally manufactured products. Nigerian e-commerce platforms and supermarket consolidation threaten early entrants lacking dedicated distribution infrastructure.
Middle East and Africa Freeze-Dried Product Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and regional captive supply arrangements. The vendor base spans Mediterranean fruit processors, Gulf-based dairy-adjacent operators, and Asian conglomerates with freeze-dried portfolios. Three archetypes dominate: regional manufacturing specialists with captive distribution, multinational ingredient conglomerates with diversified preservation portfolios, and pharmaceutical-grade lyophilization operators crossing into food applications. Competitive moves concentrate on multi-year framework agreements with Saudi giga-project developers and technology licensing for radio-frequency-assisted drying systems.
Among regional specialists, Paradise Fruits exemplifies Mediterranean sourcing network leverage for berry and tropical fruit lines, while Almarai occupies a position anchoring dairy-adjacent portfolios through Saudi distribution infrastructure. Emirates Freeze Dried Foods represents the captive manufacturing archetype with UAE-based capacity extending across Gulf Cooperation Council markets. These three entities illustrate the strategic divergence between sourcing-network dependence, backward integration into distribution, and geographic production placement.
| Leading Market Players |
|---|
| Paradise Fruits |
| Almarai |
| Nestle SA |
| Al Kabeer Group |
| Emirates Freeze Dried Foods |
| Asahi Group Holdings Ltd |
| Thrive Life LLC |
| Sunspray Food Ingredients |
| Harmony House Foods Inc. |
| Others |
Supply & Pricing Matrix
Energy-intensive sublimation cycles at -40°C to -50°C shelf temperatures cascade through three-tier pricing structure across premium, standard, and economy levels, with Gulf state electricity subsidy reforms compressing margins at the economy tier while halal-certified pharmaceutical-grade output commands 40-60% premiums in Saudi and UAE hospital procurement.
Pricing Analysis
Input-cost pass-through from European vacuum chamber imports and volatile Gulf electricity tariffs is compressing standard-tier margins for regional processors. Price differentiation separates pharmaceutical-grade lyophilization from commodity fruit dehydration, with SFDA certification and WHO prequalification anchoring premium positioning. Pricing pressure stems from retort and air-dried substitution in mass-market fruit applications. Military and emergency food buyers exhibit lowest price sensitivity; Nigerian retail channels show highest elasticity to European import alternatives.
Supply Chain Analysis
SFDA and MOHAP halal certification protocols gate supplier qualification timelines, fragmenting vendor pools across Gulf markets. Manufacturing concentrates in Saudi Arabia, UAE, and Egypt, with German and Italian engineering firms controlling vacuum chamber fabrication. Raw material flows draw from Nile Delta date orchards, Moroccan fig cooperatives, and Saudi dairy operations. Single-source equipment dependency creates currency and lead time exposure. Distribution runs through direct sales frameworks with Saudi giga-project developers and UAE hotel groups, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa freeze-dried product market functions as a stable compounder anchored by food security mandates and hospitality infrastructure buildouts across the Gulf Cooperation Council corridor.
For Market Incumbents: Lock in multi-year framework agreements with Saudi sovereign wealth-backed hotel developments before procurement consolidation accelerates. Deepen backward integration into captive halal-certified slaughter and dairy collection networks to defend against Asian conglomerate price competition. Prioritize radio-frequency-assisted drying technology licensing to extend cost advantages against European equipment-dependent rivals.
For New Entrants and Emerging Players: Nigerian supermarket chains represent the most penetrable channel anchor, with Lagos and Abuja convenience food infrastructure maturation outpacing local supply capacity. Target pharmaceutical-grade lyophilization for active ingredient stabilization, where SFDA compliance barriers deter commodity processors. Pursue white-label manufacturing partnerships with East African Community processors seeking Gulf market access.
For Investors and Strategic Acquirers: Consolidation pressure builds where captive distribution infrastructure overlaps with halal certification capabilities across Saudi and UAE markets. Five-to-ten-year viability favors processors with backward-integrated feedstock control and pharmaceutical-grade equipment tiers. Monitor SFDA-MOHAP regulatory divergence as an inflection signal for multi-market qualification cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Radio-Frequency Technology Licensing | Egyptian and Moroccan processors reduce drying duration without European turnkey dependency. |
| Halal Certification Investment | SFDA and MOHAP alignment streamlines multi-market registration for Gulf-targeting suppliers. |
| Captive Distribution Buildout | Direct sales frameworks with Saudi giga-projects bypass margin-stripping intermediaries. |
| Pharmaceutical-Grade Capacity Expansion | WHO-compliant lyophilization captures therapeutic food procurement by UN Horn of Africa operations. |
| East African Sourcing Network Integration | EAC-EA standards harmonization enables Kenyan and Tanzanian cross-border supply aggregation. |
Research Methodology
Multiple input streams — primary interviews with freeze-drying plant managers, hospitality procurement directors, and SFDA regulatory affairs leads; secondary validation through Saudi customs records, UN agency procurement databases, and EAC trade harmonization documentation; plus equipment supplier technical specifications — were reconciled through bottom-up facility capacity modeling and top-down demand aggregation across hospitality, healthcare, and military end-use segments.
Data-stream reconciliation anchored volume and value outputs across the analysis window, with segmentation modeled by product type, application, end user, and distribution channel. CAGRs were derived from facility expansion pipelines and procurement commitment trajectories. Forecast inputs incorporated Gulf state energy subsidy reform scenarios and EAC-EA standards implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to halal certification protocol fragmentation and European equipment supplier concentration. A model refresh is warranted upon material change in SFDA-MOHAP regulatory alignment or Saudi giga-project development pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Canned Vegetables Market