
 Low-Fat Low-Cholesterol Foods Market | 2026-2036
Low-Fat Low-Cholesterol Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Low-Cholesterol Foods Market Analytics
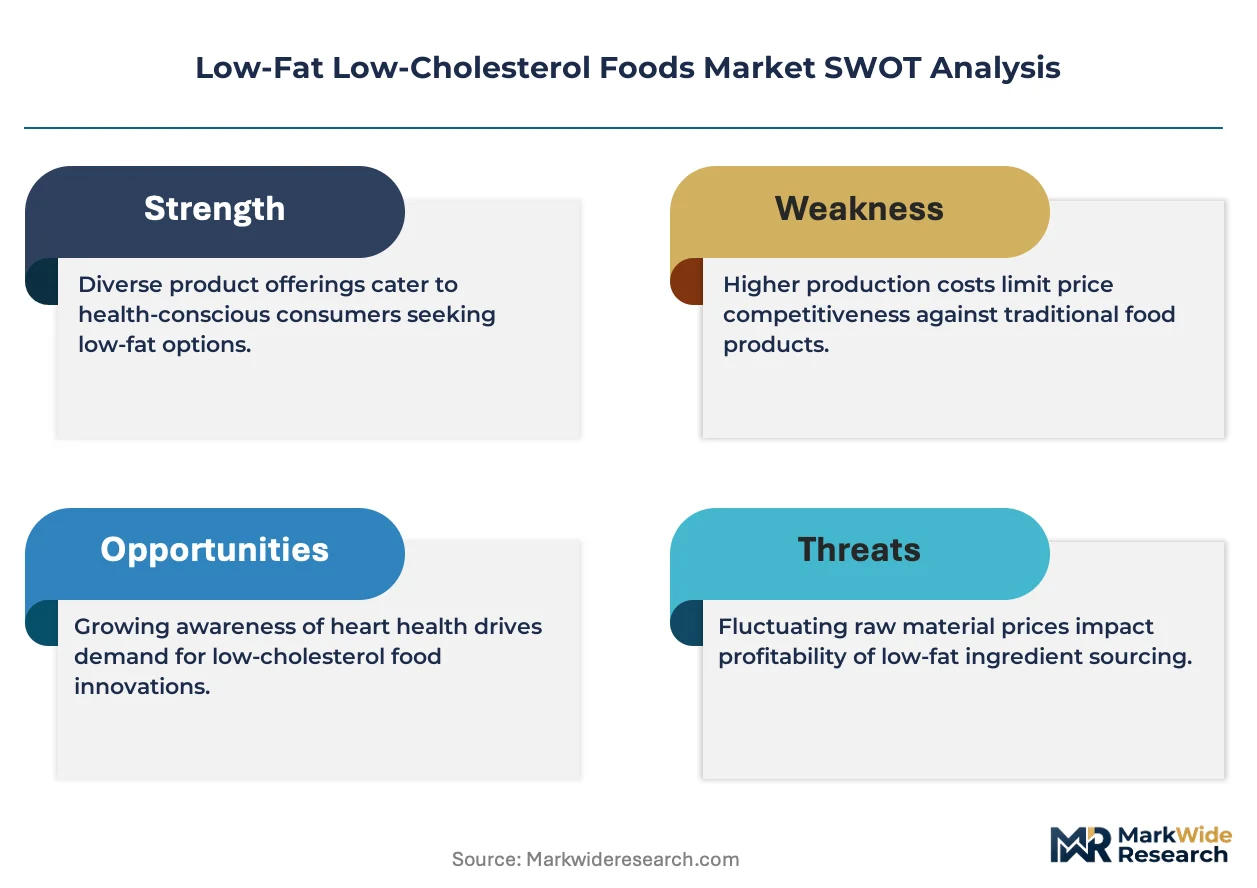
Buyer concentration is shifting from mass-market supermarket channels toward health food stores and online retailers serving fragmented, condition-specific consumer segments. Nestle S.A. leverages its global dairy-alternative R&D pipeline to anchor shelf space in European health food stores. Kraft Heinz Company competes through reformulated legacy brands that occupy mainstream supermarket aisles without premium positioning. Amy's Kitchen specializes in frozen prepared meals that dominate the organic-leaning convenience segment.
Low-fat low-cholesterol foods are formulated products containing less than three grams of fat and under twenty milligrams of cholesterol per standard serving, manufactured through modified lipid profiles, fat-replacement hydrocolloids, and controlled thermal processing to preserve sensory attributes while meeting cardiovascular-health objectives. The dairy products segment sustains the largest revenue pool due to entrenched yogurt and milk-alternative penetration, while plant-based proteins within the ingredient-type dimension represent the fastest structural expansion as formulation science improves amino-acid completeness. Online retailers are capturing margin expansion through subscription models that bypass traditional supermarket slotting fees.
The FDA enforces cholesterol-content claims and trans-fat elimination standards that dictate permissible product labeling, while the EFSA reviews novel-food ingredient approvals that gate European market entry for innovative fat replacers. WHO dietary guideline publications on saturated-fat limits shape national nutrition policies across multiple geographies, indirectly steering procurement criteria for institutional foodservice buyers. Stakeholders must monitor evolving front-of-pack labeling mandates and ingredient-approval timelines to anticipate which formulation platforms secure regulatory clearance ahead of commercial scale-up.
Market Dynamics
Cardiovascular disease prevention programs are redirecting institutional procurement toward reformulated foodservice portfolios, compressing formulation cycles and forcing ingredient suppliers to pre-certify lipid-modified inputs before scale-up.
Growth Catalysts
- WHO Saturated Fat Guidelines:National health ministries in Germany and Japan are translating these limits into school-meal procurement mandates, creating guaranteed offtake for compliant dairy alternatives.
- Fat-Replacement Hydrocolloids:Advanced gellan gum and pectin blends now replicate mouthfeel in yogurt formulations without cholesterol-bearing cream fractions, accelerating clean-label adoption in European health food stores.
- Elderly Nutrition Programs:Japan's municipal governments are expanding preventive-care food subsidies, directing volume toward low-cholesterol prepared meals and functional beverages.
Market Restraints
- Specialty Oil Input Volatility:High-oleic sunflower and algae-derived lipid supplies concentrate in Black Sea and North Atlantic extraction facilities, exposing margins to maritime logistics disruptions.
- Novel-Food Approval Timelines:EFSA's 18-24 month safety assessment windows for new fat replacers delay European commercialization of fermentation-derived structuring agents.
- Whole-Food Substitution:Unprocessed legume and nut consumption is displacing formulated low-fat products among affluent urban consumers seeking ingredient simplicity over engineered nutrition.
Strategic Opportunities
- Subscription Direct-to-Consumer:Online retailers bypass supermarket slotting fees through recurring delivery models, capturing margin expansion in United States metropolitan markets.
- Precision Fermentation Convergence:Combining cell-culture dairy proteins with enzymatic lipid modification enables cholesterol-free cheese analogues with complete amino-acid profiles.
- Institutional Foodservice Reformulation:Hospital and corporate cafeteria operators are requesting turnkey low-cholesterol menu systems, opening B2B service contracts beyond retail shelf placement.
Industry Challenges
- Sensory Scientist Shortage:Formulation teams lack specialists trained in lipid-flavor interaction modeling, slowing the replication of full-fat taste signatures in reduced-cholesterol applications.
- Dual-Label Compliance:Products must simultaneously satisfy FDA cholesterol-content claims and evolving front-of-pack warning systems in Latin American export markets, multiplying certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Low-Cholesterol Foods Market |
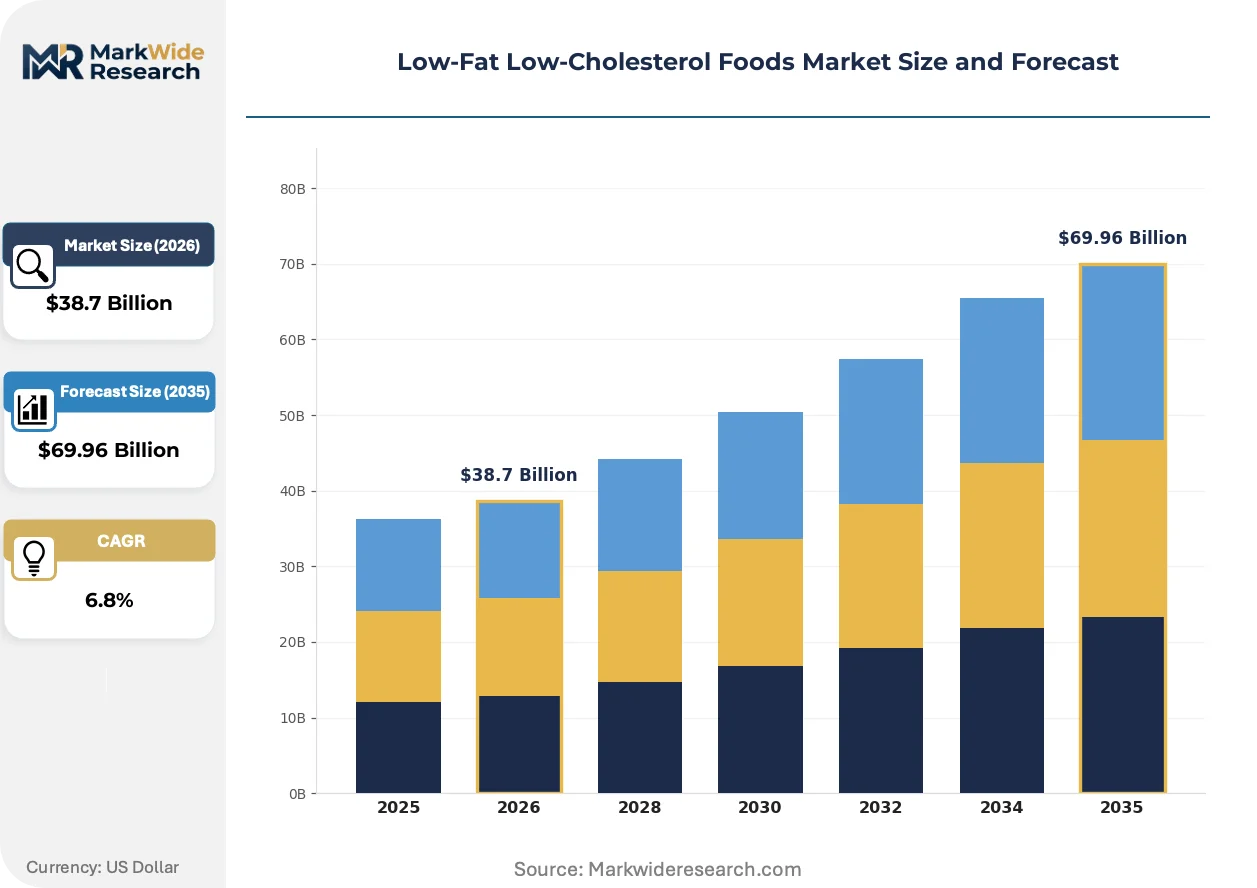
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Dairy Products, Meat Alternatives, Baked Goods Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores Customer Type: Health-Conscious Consumers, Athletes, Elderly, Families Ingredient Type: Whole Grains, Plant-Based Proteins, Low-Fat Dairy, Natural Sweeteners |
| Companies Covered | Nestle S.A., Amy's Kitchen, Knorr, Bellisio Foods, McCain Foods, General Mills, Kraft Heinz Company, ConAgra Foods, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Low-Cholesterol Foods Market Evolving Landscape
Reformulation science is converging with digital nutrition platforms, creating feedback loops between laboratory lipid modification and real-time consumer biometric data that reshape product development priorities.
Enzymatic interesterification is modularizing fat-structuring processes by decoupling fatty-acid positioning from source-oil constraints. Food technologists at mid-sized ingredient houses are adopting these systems to customize melting profiles for regional bakery applications. The technology is modularizing supply chains, allowing single facilities to serve multiple end-use specifications without dedicated production lines.
EFSA's 2023 updated guidance on novel-food allergenicity assessments is extending safety documentation requirements for plant-protein isolates. European manufacturers must now submit expanded clinical data packages before market authorization. Dairy-alternative startups are responding by prioritizing established protein sources over experimental extraction methods to avoid regulatory delays.
Condition-specific nutrition platforms are fragmenting consumer purchasing into micro-segments defined by lipid-metabolism biomarkers. Dietitian-curated digital storefronts are displacing conventional supermarket discovery for cardiovascular-risk households. This pattern is most visible in Germany, where statutory health insurers partially reimburse personalized nutrition counseling that drives algorithmic product recommendations.
Low-Fat Low-Cholesterol Foods Market Segmentation
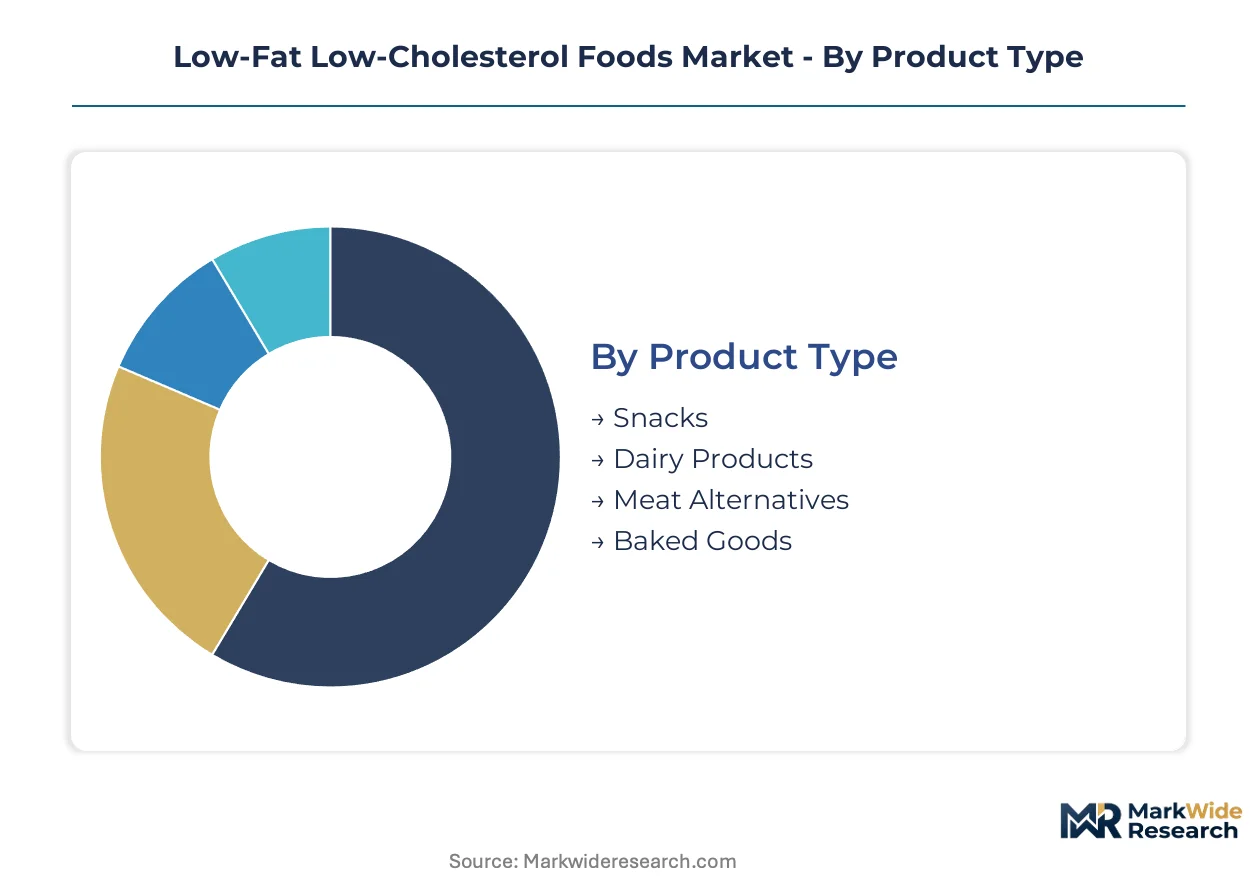
Low-fat low-cholesterol foods require precise formulation across multiple technical and commercial dimensions. Manufacturers must align lipid-modification technologies with distinct procurement channels and biomarker-driven consumer profiles to secure shelf placement and margin retention.
Product Type:
Formulation complexity varies by thermal stability requirements and fat-replacement chemistry.
- Dairy Products:Yogurt and milk alternatives employ hydrocolloid stabilization and enzymatic interesterification to replicate cream mouthfeel. Demand concentrates in Japan's elderly nutrition programs and Germany's preventive-care food subsidies, where cholesterol reduction is a reimbursed health outcome.
- Snacks:Extruded and popped formulations use modified starch matrices and air-inclusion technology to achieve crisp texture without frying oils. United States metropolitan markets show concentration through subscription direct-to-consumer channels that bypass supermarket slotting fees.
- Meat Alternatives:Mycoprotein and legume-textured products utilize lipid-modified binders to simulate marbling.
- Baked Goods:Emulsifier blends and structured shortening systems replace butter and egg yolks in commercial bakery applications.
Mature deployment sits with Dairy Products. Newer deployment is concentrated in Snacks.
Distribution Channel:
Channel economics diverge sharply between fixed-cost retail infrastructure and variable-cost digital fulfillment.
- Online Retailers:Algorithmic recommendation engines and subscription models capture cardiovascular-risk households through dietitian-curated storefronts. Germany's statutory health insurers partially reimburse personalized nutrition counseling that drives traffic to these channels.
- Health Food Stores:Staff-trained environments command premium positioning for clean-label dairy alternatives. European chains anchor shelf space for Nestle's global R&D pipeline outputs targeting condition-specific segments.
- Supermarkets:Kraft Heinz occupies mainstream aisles with reformulated legacy brands lacking premium positioning.
- Convenience Stores:Limited SKU counts favor grab-and-go prepared meals with front-of-pack cholesterol claims.
Volume leadership remains with Supermarkets. Margin expansion is climbing the fastest in Online Retailers.
Customer Type:
Biomarker segmentation fragments purchasing into condition-specific micro-segments with distinct price elasticity.
- Elderly:Municipal preventive-care subsidies in Japan direct volume toward low-cholesterol prepared meals and functional beverages with documented cardiovascular outcomes.
- Health-Conscious Consumers:Affluent urban cohorts in the United States seek ingredient simplicity, displacing formulated products with whole-food legume and nut consumption.
- Athletes:Performance-oriented protein requirements prioritize amino-acid completeness over lipid reduction alone.
- Families:School-meal procurement mandates in Germany translate WHO saturated fat limits into guaranteed offtake for compliant dairy alternatives.
Institutional purchasing concentrates with Elderly segments. Household discretionary spending is gaining share fastest among Health-Conscious Consumers.
Ingredient Type:
Raw material approval timelines and supply concentration determine formulation platform viability.
- Plant-Based Proteins:Pea and fava isolates require EFSA allergenicity documentation under updated guidance, extending safety assessment windows. European manufacturers prioritize established protein sources over experimental extraction methods to avoid regulatory delays.
- Low-Fat Dairy:Skim milk solids and whey fractions leverage existing dairy infrastructure with cholesterol removal via membrane filtration.
- Whole Grains:Fiber-enhanced matrices support front-of-pack labeling claims in multiple geographies.
- Natural Sweeteners:Monk fruit and stevia blends replace sucrose in reduced-calorie positioning without lipid interaction complications.
Supply security sits with Low-Fat Dairy. Steepest expansion trajectory belongs to Plant-Based Proteins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in aging economies where preventive healthcare spending and regulatory nutrition mandates intersect. The United States, Germany, and Japan anchor volume due to elderly nutrition programs and school-meal procurement standards. Municipal subsidy structures and front-of-pack labeling requirements reshape commercialization pathways across these markets.
United States
Cardiovascular-risk households drive algorithmic product recommendations through dietitian-curated digital storefronts. The FDA enforces cholesterol-content claims and trans-fat elimination standards that dictate permissible product labeling. Subscription direct-to-consumer models in metropolitan markets bypass supermarket slotting fees, capturing margin expansion for reformulated brands.
Germany
Statutory health insurers partially reimburse personalized nutrition counseling that steers traffic toward online retailers. EFSA reviews novel-food ingredient approvals that gate European market entry for innovative fat replacers. Preventive-care food subsidies in Bavaria and North Rhine-Westphalia direct volume toward low-cholesterol dairy alternatives.
Japan
Municipal governments expand preventive-care food subsidies for elderly nutrition programs. METI coordinates national standards for functional food claims that align with WHO saturated fat guidelines. Tokyo and Osaka metropolitan areas concentrate demand for low-cholesterol prepared meals and functional beverages with documented cardiovascular outcomes.
United Kingdom
Health-conscious urban cohorts seek ingredient simplicity, displacing formulated products with whole-food legume consumption. The Food Standards Agency enforces front-of-pack labeling mandates that compress formulation cycles. London and Southeast England anchor shelf space for clean-label dairy alternatives in staff-trained health food environments.
France
School-meal procurement translates EU nutritional guidelines into guaranteed offtake for compliant dairy alternatives. ANSM reviews novel-food safety assessments that extend documentation requirements for plant-protein isolates. Île-de-France and Auvergne-Rhône-Alpes concentrate R&D activity for enzymatic lipid modification technologies.
Low-Fat Low-Cholesterol Foods Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and direct-to-consumer subscription models. The vendor base stratifies across three maturity tiers: multinational packaged food conglomerates with reformulated legacy portfolios, mid-sized organic specialists commanding premium health food positioning, and venture-backed startups developing cell-culture dairy analogues. Dominant competitive moves include portfolio diversification into cholesterol-free cheese alternatives and strategic partnerships with institutional foodservice operators seeking turnkey menu systems.
Within the multinational tier, Nestle S.A. and Danone S.A. exemplify scale-driven players leveraging global dairy-alternative R&D pipelines. Kraft Heinz Company occupies a position bridging mainstream supermarket aisles and reformulated health positioning. Amy's Kitchen represents the organic-leaning convenience segment, anchoring frozen prepared meal categories in staff-trained retail environments. These three archetypes illustrate the competitive tension between legacy brand renovation and clean-label specialization.
| Leading Market Players |
|---|
| Nestle S.A. |
| Amy's Kitchen |
| Knorr |
| Bellisio Foods |
| McCain Foods |
| General Mills |
| Kraft Heinz Company |
| ConAgra Foods |
| Danone S.A. |
| Others |
Value Network & Pricing Analysis
WHO dietary guidelines on saturated fat reduction gate qualified supply access and premium-tier pricing power for cardiovascular-positioned formulations. Manufacturers meeting FDA cholesterol-content claims and EFSA novel-food standards capture shelf placement in reimbursed health programs, while uncertified competitors face margin compression in undifferentiated supermarket tiers.
Pricing Analysis
Volume leadership concentrates in reformulated legacy brands occupying mainstream supermarket aisles, while margin expansion accrues to subscription-based online retailers bypassing slotting fees. Three-tier pricing structure across premium health food store positioning, standard supermarket placement, and economy private-label tiers differentiates by certification grade and channel service level. Cost compression in the economy tier is intensifying because whole-food substitution among affluent urban consumers limits volume leverage. Health-conscious elderly segments in Japan and Germany exhibit lowest price sensitivity due to municipal subsidy coverage, whereas US metropolitan families face highest sensitivity when subscription models compete with conventional retail.
Supply Chain Analysis
Domestic-content mandates in European public procurement programs are reshaping sourcing patterns for institutional foodservice contracts. High-oleic sunflower oil and algae-derived lipid concentrates draw from Black Sea extraction facilities and North Atlantic cultivation sites, with gellan gum and pectin hydrocolloid supplies anchored in Asian fermentation hubs. Single-source vulnerability in specialty oil inputs exposes margins to maritime logistics disruptions across Black Sea routes. Distribution runs through health food store networks for premium positioning, supermarket central warehouses for volume throughput, and direct-to-consumer fulfillment centers for subscription retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing conventional enzymatic lipid modification in cholesterol-free dairy analogue development, compressing formulation cycle timelines and resetting competitive moats around cell-culture protein capabilities.
For Market Incumbents: Anticipate margin erosion from venture-backed precision fermentation startups by accelerating backward integration into cell-culture protein supply. Secure exclusive offtake agreements with fermentation-derived ingredient houses before scale-up capacity constraints materialize. Pre-certify reformulated portfolios for dual FDA and EFSA compliance to defend shelf space against novel-food approval delays affecting challenger brands.
For New Entrants and Emerging Players: Precision fermentation convergence offers technology-first wedge positioning in cholesterol-free cheese analogues with complete amino-acid profiles. Target institutional foodservice operators in Japan and Germany seeking turnkey low-cholesterol menu systems, where municipal subsidy structures guarantee volume offtake. Deploy dietitian-curated digital storefronts to bypass supermarket slotting fees and capture algorithmic recommendation traffic from cardiovascular-risk households.
For Investors and Strategic Acquirers: EFSA's extension of novel-food allergenicity assessment timelines is the leading indicator that regulatory clearance velocity will determine platform viability over the investment horizon. Prioritize acquisition targets with established protein source portfolios and pre-submitted safety documentation packages rather than experimental extraction methods. Monitor front-of-pack labeling mandate expansions across Latin American export markets as the signal for dual-compliance cost escalation affecting margin structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Cell-culture dairy proteins enable cholesterol-free formulations with complete amino-acid profiles. |
| Institutional Foodservice Partnership | Hospital and corporate cafeteria operators seek turnkey low-cholesterol menu systems beyond retail. |
| Subscription Direct-to-Consumer Launch | Algorithmic recommendation engines capture cardiovascular-risk households bypassing supermarket slotting fees. |
| Dual-Label Compliance Investment | Simultaneous FDA and evolving Latin American front-of-pack certification multiplies barrier height. |
| Backward Integration into Hydrocolloids | Captive supply of gellan gum and pectin stabilizers secures mouthfeel replication without cream fractions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulation scientists at ingredient houses, procurement directors at institutional foodservice operators, regulatory affairs leads navigating EFSA novel-food pathways, and category buyers at health food retail chains combined with FDA guidance documents, WHO dietary guideline publications, and municipal subsidy program disclosures. Bottom-up volume modeling across product type, distribution channel, and customer segments triangulated against top-down macroeconomic indicators.
Granularity-level modeling deployed segment-specific CAGRs across dairy products, snacks, meat alternatives, and baked goods, with distribution channel dynamics resolved at online retailer, health food store, supermarket, and convenience store levels. Ingredient type trajectories for plant-based proteins, low-fat dairy, whole grains, and natural sweeteners were projected throughout the forecast period. CAGRs derived from historical growth rate analysis adjusted for regulatory catalyst timing and subsidy program expansion schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to Black Sea oilseed supply corridors, breakthrough whole-food legume processing technologies displacing formulated products, and unanticipated EFSA allergenicity guidance revisions extending approval timelines. Forecasts reflect documented assumptions regarding WHO guideline adoption velocity and municipal subsidy continuation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Turkey Cold Storage Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market