
 Popsicle Market | 2026-2036
Popsicle Market Size, Share, and Industry Trends Forecast 2026-2036
Popsicle Market Insights
Market Context
Southeast Asia is fragmenting as Vietnam, Thailand, and Indonesia each build independent cold-chain distribution networks for frozen desserts. Unilever leverages its Wall's and Paddle Pop infrastructure to control retail freezer placement across multiple ASEAN markets. Nestlé sustains dominance in Latin America through localized flavor development and dairy sourcing partnerships. Inner Mongolia Yili Industrial Group anchors volume in China by operating dedicated ice cream plants with captive milk supply.
Technical Definition and Segment Structure
A popsicle is a frozen confection comprising water, sweeteners, flavoring agents, and stabilizers, typically formed through batch freezing at temperatures between minus 20 and minus 30 degrees Celsius and mounted on a stick for handheld consumption. The product serves as a mass-market refreshment item distributed through retail and food service channels with shelf-life requirements dictating uninterrupted cold-chain logistics. Fruit flavored variants occupy the largest volume share due to lower ingredient costs and broad demographic appeal across age groups. Sugar-free formulations are expanding fastest as diabetic-friendly and keto-positioned products capture pharmacy and health-channel placements. Organic segments command premium pricing tiers supported by certification requirements that limit supplier pools and concentrate margin capture among certified dairy and fruit concentrate sources.
Regulatory Environment and Outlook
FDA oversight in the United States governs pasteurization standards, ingredient labeling, and nutritional disclosure for frozen dessert products, while EFSA and national EU regulators enforce additive restrictions through the EU Food Additives Regulation. BIS standards in India mandate microbial limits and packaging material safety for frozen novelties sold through organized retail. China's SAMR supervises GB standards compliance for dairy-derived frozen products including pathogen testing and net content verification. Stakeholders must monitor evolving clean-label mandates and carbon-footprint disclosure rules that will reshape supplier qualification and regional market access requirements.
Market Dynamics
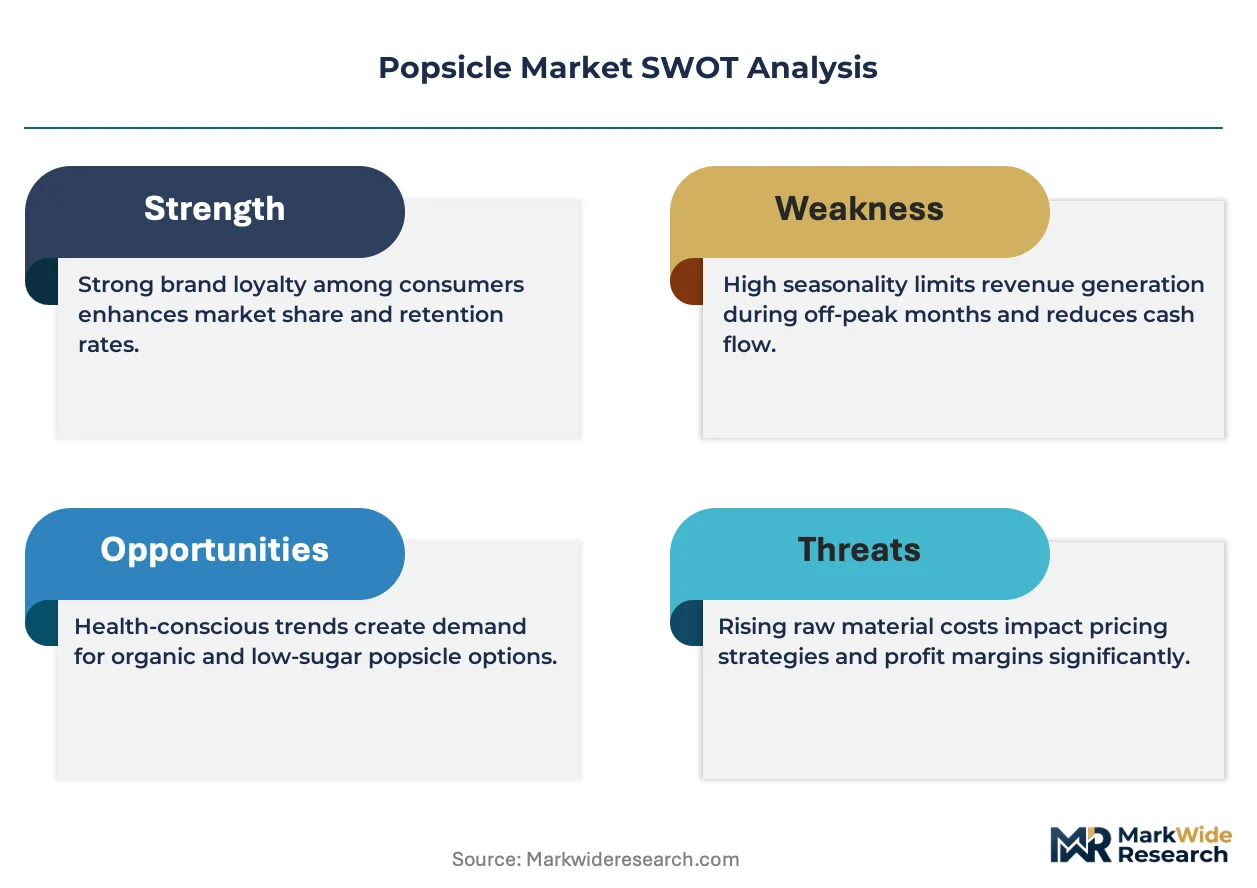
Clean-label mandates from FDA and EFSA are forcing wholesale reformulation across the popsicle supply chain, compressing ingredient supplier pools and raising certification barriers for new market entrants.
Growth Catalysts
- Urban heat stress patterns:Prolonged heat waves in India are accelerating frozen novelty consumption among urban households with rising disposable incomes.
- EFSA additive restrictions:Stricter enforcement of EU Food Additives Regulation is creating competitive moats for manufacturers with established clean-label supply chains.
- Convenience store freezer expansion:Retailers across Vietnam, Thailand, and Indonesia are prioritizing frozen dessert category space as traffic drivers.
Market Restraints
- Dairy input cost volatility:Fluctuating milk powder and butterfat prices compress margins for dairy-based formulations during procurement cycles.
- Cold-chain infrastructure gaps:Last-mile refrigeration failures in secondary Indian cities limit distribution reach and increase spoilage rates.
- Substitution by beverage alternatives:Ready-to-drink functional waters and refrigerated juices capture refreshment occasions during cooler seasons.
Strategic Opportunities
- Pharmacy channel placement:Sugar-free and diabetic-positioned popsicles are securing shelf space in health-focused retail formats.
- Organic certification premium tiers:Limited supplier pools for certified fruit concentrates enable margin capture among compliant manufacturers.
- Keto dietary positioning:High-fat, low-carbohydrate formulations are opening placement in specialty nutrition channels.
Industry Challenges
- Refrigeration technician scarcity:Qualified cold-chain maintenance personnel shortages in emerging markets delay equipment deployment.
- Clean-label reformulation timelines:Natural stabilizer substitution projects require 18-24 month sensory validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popsicle Market |
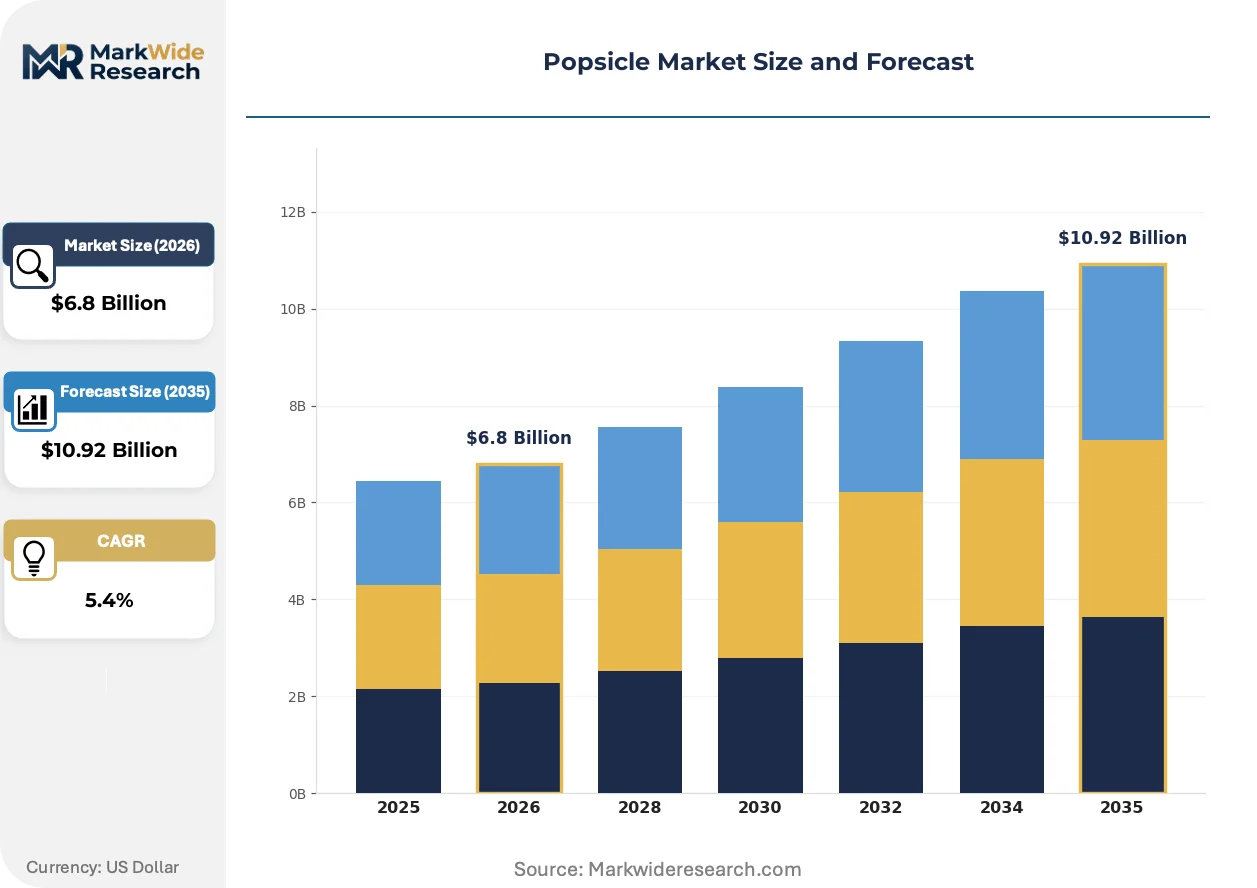
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavored, Creamy, Sugar-Free, Organic End User: Children, Adults, Retailers, Food Service Packaging Type: Box, Cup, Bag, Stick Distribution Channel: Supermarkets, Convenience Stores, E-commerce, Vending Machines |
| Companies Covered | China Mengniu Dairy Company, Akagi Nyugyo, Unilever, GoodPop, The Jel Sert Company, Nestlé, Meiji Holdings, Danone, Inner Mongolia Yili Industrial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popsicle Market Trends and Innovations
Digital traceability systems and batch-level monitoring are reshaping quality assurance protocols, while regulatory pressure and shifting consumer health priorities compress traditional formulation approaches.
Blockchain-enabled supply chain tracking is digitizing ingredient provenance documentation from fruit concentrate sourcing through retail delivery. Mid-sized manufacturers in ASEAN markets are adopting these systems fastest to meet EUDR-equivalent export requirements. This transparency infrastructure is digitizing compliance cost structures and favoring suppliers with established digital records over legacy paper-based operations.
EFSA's evolving stance on artificial colorants is tightening formulation standards for products targeting European retail placement. Manufacturers must now reformulate with natural alternatives or exit the EU market entirely. Sugar-free variants using novel sweetener blends face the steepest regulatory scrutiny and longest approval timelines.
Health-channel buyers are consolidating frozen novelty procurement around certified organic and functional-positioned SKUs. Traditional impulse-buy convenience store placements are losing share to planned purchases through pharmacy and specialty grocery channels. This channel rotation is most pronounced in Germany, France, and the United Kingdom where clean-label certification carries premium pricing power.
Popsicle Market Segmentation
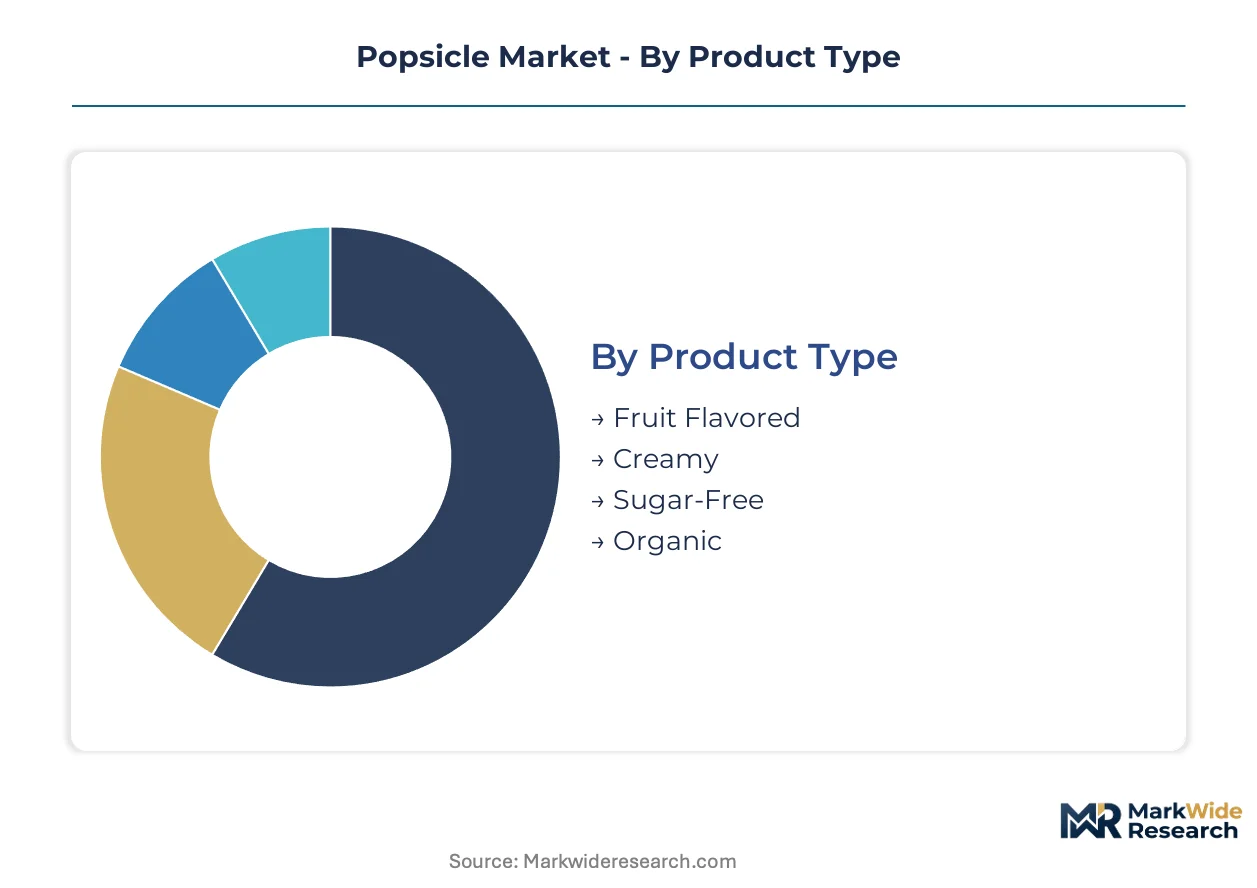
Popsicle manufacturers navigate distinct demand profiles across product formulations, consumer demographics, and channel structures. Segmentation reveals where margin capture concentrates versus where volume scales, informing capacity allocation and cold-chain investment priorities.
Product Type:
Mature mass-market formulations coexist with emerging premium-positioned variants as clean-label mandates reshape R&D roadmaps.
- Fruit Flavored:Water-based formulations with concentrated fruit purees and citric acid stabilization dominate manufacturing throughput. Demand concentrates in India's urban centers where heat-wave frequency and organized retail penetration intersect; lower ingredient costs sustain price accessibility for daily consumption occasions.
- Sugar-Free:Polyol-sweetened and stevia-positioned variants target diabetic consumers and ketogenic diet adherents. Pharmacy channel placements in Germany and France are accelerating as health-focused retailers consolidate frozen novelty procurement around functional-positioned SKUs; EFSA scrutiny of novel sweetener approvals extends validation timelines.
- Creamy:Dairy-fat enriched formulations with butterfat content above 8% deliver indulgence-positioned consumption. Premium convenience store placements in Vietnam and Thailand support margin structures.
- Organic:Certified fruit concentrate and dairy inputs command supplier scarcity premiums. Limited certified supplier pools in the European Union concentrate margin capture among compliant manufacturers.
Fruit Flavored retains volume leadership; Sugar-Free holds the steepest expansion curve.
End User:
Volume concentration tilts toward household purchasers while institutional procurement patterns diverge by service format and price sensitivity.
- Children:Brightly colored, character-licensed formulations with simplified ingredient decks target parental purchase triggers. Demand clusters in Southeast Asian convenience stores where freezer placement prioritizes impulse visibility at child eye-level.
- Adults:Sophisticated flavor profiles and reduced-sugar positioning capture planned purchase occasions. Premium supermarket channels in the United Kingdom and France favor clean-label certification as a purchase filter.
- Retailers:Private-label procurement concentrates among supermarket chains seeking margin differentiation from branded alternatives. Cold-chain reliability requirements filter supplier qualification.
- Food Service:Bulk-format and individually wrapped SKUs serve hospitality and institutional catering. India's emerging café culture is testing dessert-menu placements for premium variants.
Children drives absolute volume throughput; Adults climbs fastest as health-positioned variants expand planned-purchase channels.
Packaging Type:
Format selection traces consumption occasion specificity from immediate consumption to household inventory stocking.
- Stick:Individual handheld formats dominate impulse channels and outdoor consumption. Vending machine compatibility and single-serve pricing sustain ubiquity across convenience retail.
- Box:Multi-unit packaging supports household inventory and promotional pricing. Supermarket freezer door placements favor stackable rectangular formats for space efficiency.
- Cup:Spoonable formats with peelable lids target younger children and controlled-portion positioning. Food service dessert applications in Thailand's hospitality sector test premium cup formats.
- Bag:Flexible pillow pouches for freezer-pop variants minimize packaging cost and shipping cube. E-commerce fulfillment favors lightweight, damage-resistant formats.
Stick maintains channel ubiquity; Box gains share fastest as household stockpiling behavior shifts toward planned purchasing.
Distribution Channel:
Cold-chain infrastructure maturity determines channel accessibility, with last-mile refrigeration gaps filtering geographic reach.
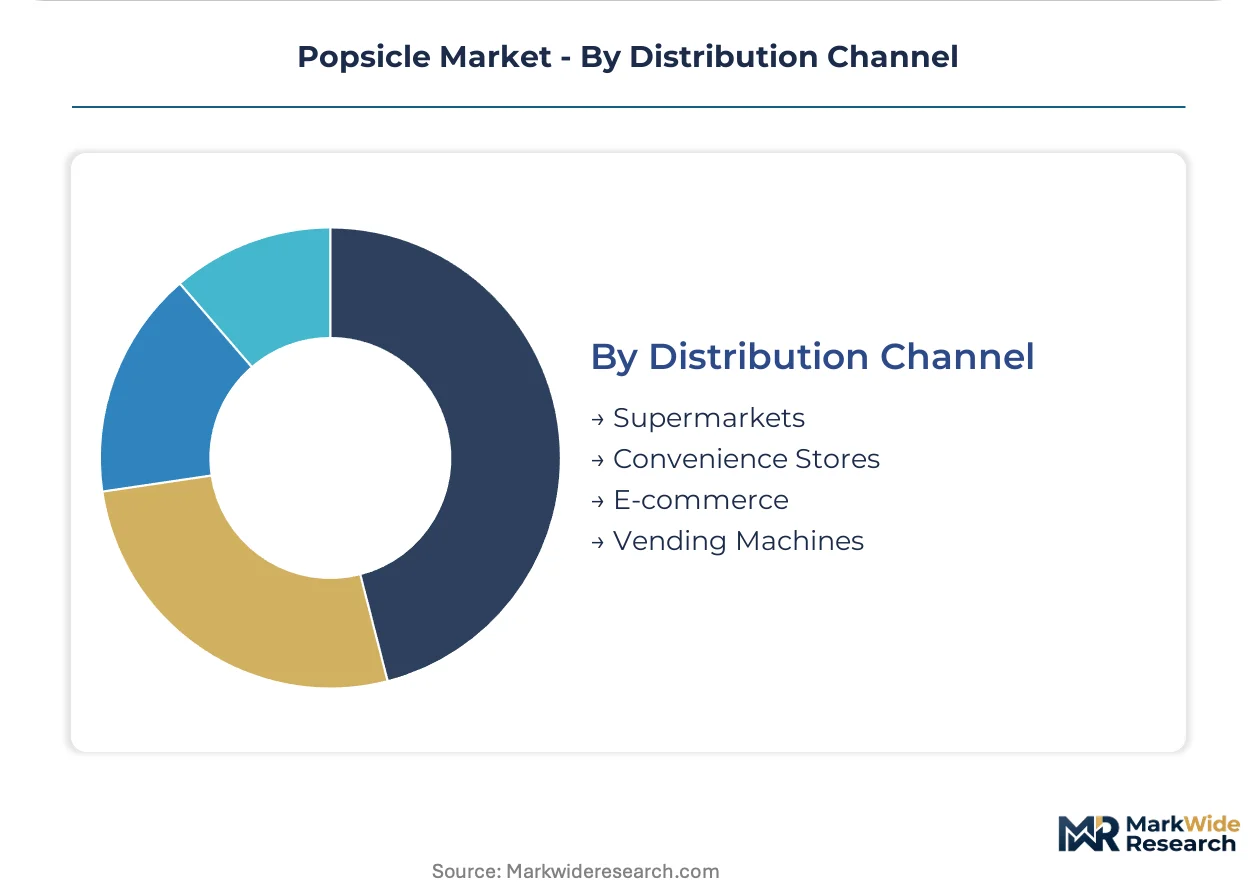
- Supermarkets:Dedicated freezer aisles with temperature monitoring support full product range distribution. India's organized retail expansion in Mumbai and Delhi anchors volume growth for premium variants.
- Convenience Stores:Smaller-format freezer placements prioritize high-velocity SKUs and impulse price points. Vietnam, Thailand, and Indonesia are independently expanding freezer capacity as traffic-driving category investments.
- E-commerce:Insulated packaging and same-day cold-chain fulfillment enable direct-to-consumer penetration. Urban density in Chinese tier-one cities supports viable unit economics for frozen novelty delivery.
- Vending Machines:Refrigerated outdoor units capture immediate consumption in transit corridors and recreational venues. Japan's vending infrastructure density provides operational templates for Southeast Asian deployment.
Supermarkets retains value concentration; E-commerce expands most quickly as last-mile cold-chain investments mature in urban China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and India where integrated dairy operations and expanding cold-chain networks concentrate frozen novelty production. Regulatory divergence between FDA pasteurization mandates, EFSA additive restrictions, and BIS microbial standards fragments formulation requirements across export markets. Urban heat stress and organized retail penetration are accelerating demand in South and Southeast Asian metropolitan corridors.
United States
FDA pasteurization standards and nutritional disclosure rules govern frozen dessert distribution through supermarket and convenience channels. Clean-label reformulation pressures intensify as retailers demand simplified ingredient decks for private-label procurement. Texas and California anchor volume production with dedicated ice cream manufacturing corridors serving national distribution networks.
China
SAMR supervision of GB standards compliance shapes pathogen testing and dairy input verification for frozen novelties. Inner Mongolia Yili Industrial Group operates captive milk supply chains through dedicated ice cream plants in northern dairy belts. Tier-one cities including Shanghai and Beijing support viable e-commerce cold-chain economics for direct-to-consumer frozen novelty delivery.
India
BIS microbial limits and packaging safety standards filter supplier qualification for organized retail placement. Prolonged urban heat waves in Mumbai and Delhi accelerate household consumption among rising disposable income brackets. Cold-chain infrastructure gaps in secondary cities constrain last-mile distribution reach and elevate spoilage risk.
Germany
EFSA enforcement of EU Food Additives Regulation creates competitive moats for manufacturers with established clean-label supply chains. Pharmacy channel placements for sugar-free variants concentrate in health-focused retail formats across Berlin and Munich. Premium supermarket buyers consolidate procurement around certified organic SKUs with full provenance documentation.
Vietnam
Independent cold-chain distribution network construction supports convenience store freezer expansion as a traffic-driving category investment. Unilever leverages Wall's infrastructure to control retail freezer placement across ASEAN market entry points. Ho Chi Minh City and Hanoi anchor demand concentration where urban heat and organized retail penetration intersect.
Popsicle Market Competitive Landscape
Multinational conglomerates and regional dairy specialists split the market between scale-driven volume production and localized flavor adaptation. Tiered competitive dynamics emerge from divergent cold-chain infrastructure ownership and captive ingredient sourcing capabilities. Three archetypes dominate: integrated dairy-industrial groups with captive milk supply, multinational FMCG platforms with freezer placement control, and clean-label specialists targeting health-channel distribution. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure cold-chain partnerships and reformulation capabilities.
Within the integrated dairy tier, Inner Mongolia Yili Industrial Group and China Mengniu Dairy Company exemplify manufacturing scale anchored to captive northern Chinese milk basins. Among multinational platforms, Unilever occupies a position defined by freezer infrastructure control across Southeast Asian convenience retail. Clean-label positioning is represented by GoodPop as a specialist archetype targeting pharmacy and specialty grocery channel consolidation.
| Leading Market Players |
|---|
| China Mengniu Dairy Company |
| Akagi Nyugyo |
| Unilever |
| GoodPop |
| The Jel Sert Company |
| Nestlé |
| Meiji Holdings |
| Danone |
| Inner Mongolia Yili Industrial Group |
| Others |
Pricing and Supply Chain Analysis
Inner Mongolia's captive dairy basins concentrate butterfat and milk powder supply for creamy popsicle formulations, anchoring margin capture in premium-tier dairy-enriched SKUs while compressing cost structures for mass-market water-based variants.
Pricing Analysis
EFSA additive restrictions dictate the pricing tier structure across European retail placement, forcing reformulation investments that stratify pricing across organic-certified premium, clean-label standard, and conventional economy tiers. Price differentiation hinges on certification grade and cold-chain reliability guarantees. Cost compression in conventional formulations is intensifying because natural stabilizer substitution extends R&D cycles. Price-sensitive buyers cluster in Southeast Asian convenience retail, while German pharmacy channels exhibit lowest sensitivity to premium positioning.
Supply Chain Analysis
EU dual-use export controls on food-grade emulsifier technology limit flows of advanced stabilization systems to certain markets, constraining formulation options for manufacturers seeking rapid clean-label transitions. Supply concentrates in China, India, and Germany for fruit concentrate, dairy inputs, and natural colorant extraction respectively. The chain rests on polyol sweeteners, butterfat derivatives, and citric acid stabilization systems. Single-source vulnerability runs through certified organic fruit concentrate suppliers in the European Union. Distribution runs through dedicated freezer placement networks controlled by multinational FMCG platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The popsicle market is recovering from input cost cyclicality as dairy commodity prices normalize and cold-chain infrastructure investments in South Asia mature.
For Market Incumbents: Insulate margin structures by securing captive dairy supply agreements in northern Chinese milk belts and accelerating clean-label certification timelines ahead of EFSA enforcement waves. Channel control through retail freezer placement remains the priority lever against emerging local dairy specialists. For New Entrants and Emerging Players: Establish a beachhead in India's secondary cities where cold-chain gaps have kept organized retail penetration low and local dairy cooperatives dominate. Target sugar-free pharmacy channel placement in Germany and France as the most penetrable premium segment. Lead with keto-positioned formulations and blockchain-enabled provenance documentation to differentiate from incumbent supply chains. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across e-commerce cold-chain fulfillment as insulated packaging standardizes and urban density in Chinese tier-one cities supports viable unit economics. Long-term viability favors acquisitions of clean-label specialists with established organic certification and health-channel relationships. Watch EFSA's stance on novel sweetener approvals as the signal for sugar-free segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Acceleration | EFSA additive restrictions force 18-24 month sensory validation cycles that filter supplier pools. |
| Captive Dairy Supply Integration | Inner Mongolia Yili's northern milk basins demonstrate margin protection against butterfat volatility. |
| Pharmacy Channel Expansion | German health-focused retailers consolidate procurement around diabetic-friendly and keto-positioned SKUs. |
| Blockchain Traceability Deployment | ASEAN mid-sized manufacturers adopt digital provenance systems fastest to meet EUDR-equivalent export requirements. |
| Convenience Store Freezer Control | Unilever's Wall's infrastructure across Vietnam and Thailand locks in impulse-visibility placement. |
Research Methodology
The analysis maps fruit-flavored, sugar-free, creamy, and organic formulation sub-sectors, each validated through supply chain directors at dairy processors, category buyers at convenience retail chains, cold-chain logistics operators, and regulatory affairs specialists at multinational FMCG platforms. Primary interview findings triangulate against customs trade data for fruit concentrate and dairy derivatives, BIS and SAMR regulatory filings, Nielsen retail audit data for freezer placement metrics, and SEC disclosures from listed dairy groups. Bottom-up volume modeling and top-down value reconciliation ensure cross-validation.
Assumptions held fixed include EFSA's current additive restriction enforcement stance, India's urban heat wave frequency patterns, and Southeast Asian convenience store freezer expansion rates; variables tested include dairy input cost volatility bands and e-commerce cold-chain penetration curves. The projection horizon spans product type, end-user demographic, packaging format, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs derive from segment-level volume build-ups and price trajectory assumptions. Forecast inputs incorporate cold-chain infrastructure build-out timelines and clean-label certification adoption curves.
Macroeconomic conditions sit as an overlay; deviation in disposable income growth trajectories in India and dairy commodity price cycles would shift the trajectory. Material shifts in EFSA enforcement timelines or SAMR dairy standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Chilled Processed Food Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Chilled Meal Kits Market