
 United States Frozen Pizza Market | 2026-2036
United States Frozen Pizza Market Size, Share, and Industry Trends Forecast 2026-2036
United States Frozen Pizza Market Intelligence
Asset-light contract manufacturing and third-party cold-chain leasing is tilting competitive dynamics toward brands that outsource production rather than owning brick-and-mortar plants. Conagra Brands Inc. leverages its Omaha-based distribution network to control retail shelf placement across mass-market channels. Nestlé SA sustains premium positioning through R&D intensity in clean-label ingredient systems. Schwan's Company anchors its competitiveness through captive frozen logistics infrastructure that spans from Minnesota to Texas.
United States frozen pizza comprises par-baked or fully baked dough platforms topped with sauce, cheese, and proteins, then flash-frozen at negative forty degrees Fahrenheit to arrest staling and microbial activity; the category serves both at-home convenience consumption and institutional feeding programs requiring extended shelf stability. Thin crust variants dominate volume shipments due to lower freight cost per unit and faster oven recovery times, while gluten-free formulations command disproportionate margin pools despite smaller base volumes. Online retail channels represent the fastest-growing distribution vector as direct-to-freezer delivery models bypass traditional grocery slotting fees.
The USDA oversees meat and poultry topping safety through FSIS inspection protocols, while the FDA governs cheese analogs and vegetable ingredients under FSMA preventive controls, and both frameworks elevate compliance costs for regional entrants lacking in-house regulatory affairs staff. State-level cottage food laws create uneven market access thresholds that favor multi-state operators with centralized quality assurance laboratories. Stakeholders must monitor how evolving sodium reduction targets and front-of-package warning label proposals reshape reformulation roadmaps and consumer perception dynamics.
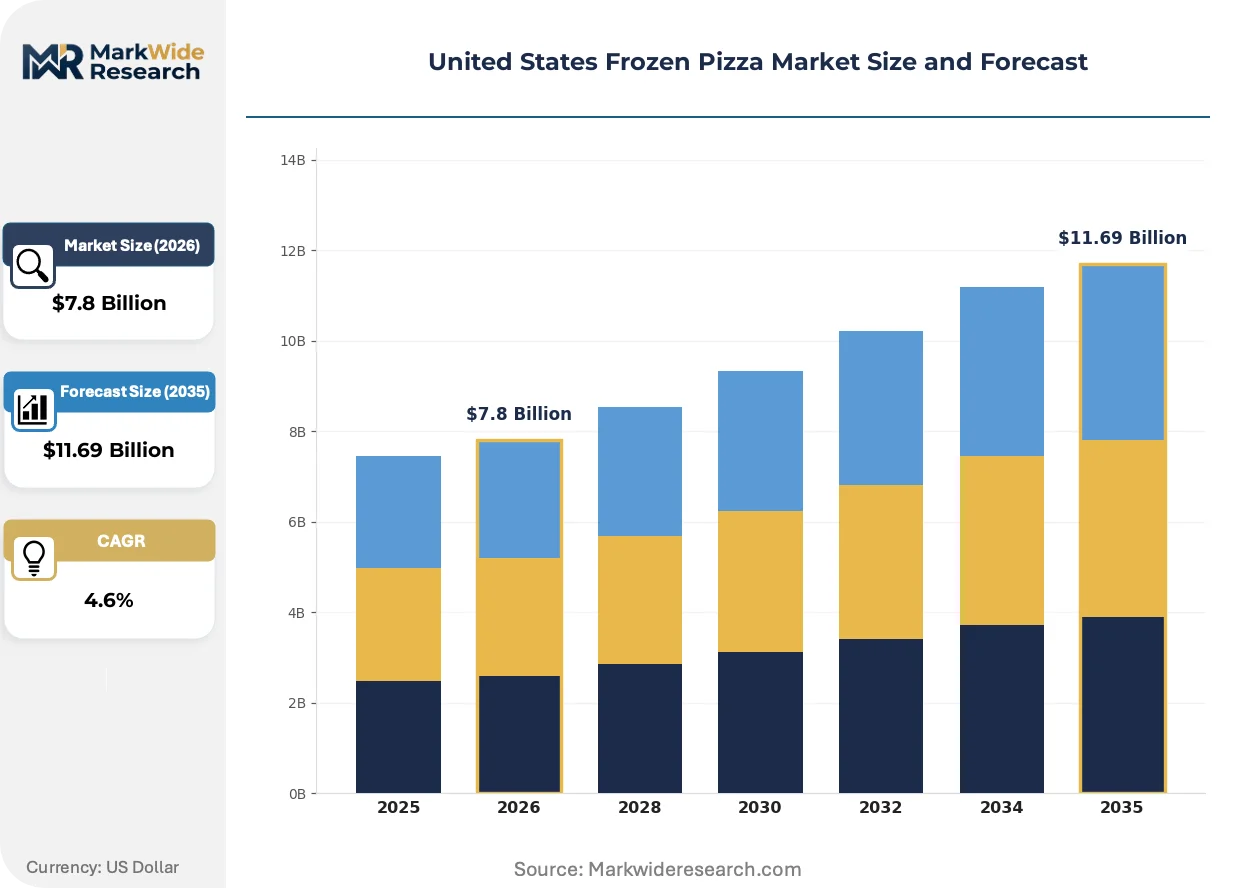
Market Dynamics
Asset-light contract manufacturing is concentrating production control among operators with flexible third-party networks, while FDA labeling mandates force simultaneous reformulation across cheese analogs and sodium targets. Cold-chain infrastructure gaps between Minnesota processing clusters and Sun Belt demand nodes create persistent logistics friction.
Growth Catalysts
- Midwest Manufacturing Belt Concentration:Wisconsin and Minnesota processing clusters generate freight-cost advantages for thin-crust variants shipped to institutional buyers across the Great Plains and Texas corridor.
- FSMA Preventive Controls:The FDA's framework for vegetable ingredients and cheese analogs elevates compliance barriers that favor scaled operators with captive quality assurance laboratories over regional entrants.
- College Foodservice Expansion:University dining programs requiring extended shelf stability and portion consistency are expanding procurement of par-baked platforms for campus retail and residential dining operations.
Market Restraints
- Dairy Input Volatility:Mozzarella and cheese analog cost swings compress margin pools for operators locked into annual retail price commitments with mass-market grocers.
- Regulatory Friction from State Cottage Laws:Uneven market access thresholds across state jurisdictions fragment distribution reach for emerging brands lacking multi-state licensing infrastructure.
- Flash-Freeze Energy Intensity:Negative forty degrees Fahrenheit processing requirements limit site selection to regions with reliable grid capacity and natural gas availability, constraining geographic expansion.
Strategic Opportunities
- Direct-to-Freezer E-Commerce:Online retail channels bypass traditional grocery slotting fees and enable subscription-based replenishment models for at-home convenience consumption.
- Gluten-Free Formulation Premiums:Clean-label ingredient systems command disproportionate margin pools despite smaller base volumes, rewarding R&D investment in alternative dough platforms.
- Sodium Reduction Tailwinds:Front-of-package warning label proposals and FDA sodium targets create first-mover advantages for brands with reformulated sauce and topping portfolios ahead of compliance deadlines.
Industry Challenges
- Cold-Chain Talent Scarcity:Specialized technicians for blast-freeze maintenance and refrigerated transport fleet management face acute shortages in secondary markets outside Minnesota and Wisconsin.
- Legacy ERP Integration:Third-party logistics partnerships require real-time inventory visibility systems that conflict with decades-old warehouse management platforms at established distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Frozen Pizza Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Crust, Stuffed Crust, Gluten-Free, Traditional Crust Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Flavor Profile: Pepperoni, Vegetable, Barbecue Chicken, Cheese Size: Personal Size, Medium, Large, Family Size |
| Companies Covered | Conagra Brands Inc., Palermo Villa Inc., Nestlé SA, Rich Products Corp., Caulipower LLC, General Mills Inc., Amy's Kitchen Inc., Bernatellos Foods, Schwan's Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Frozen Pizza Market Strategic Shifts & Innovations
Reformulation priorities are diverging between sodium-reduced clean-label platforms for health-conscious retail buyers and extended-shelf-life formulations for institutional procurement. Technology migration and channel restructuring are compressing traditional go-to-market timelines.
High-pressure processing for sauce pasteurization is migrating from niche organic lines to mainstream retail SKUs as private-label buyers adopt extended-safety protocols. Mass-market grocers in the Upper Midwest are specifying HPP-treated toppings to reduce spoilage claims and extend distribution radii from Wisconsin production hubs. This migration from thermal-only processing is compressing equipment payback periods and reshaping capital allocation among contract manufacturers.
The FDA's updated Nutrition Facts labeling requirements for packaged foods are forcing simultaneous disclosure of added sugars and revised serving sizes across frozen pizza portfolios. Reformulation teams must reconcile sodium reduction targets with texture stability in par-baked crusts, compressing product development cycles. Thin-crust and gluten-free variants face disproportionate compliance costs due to smaller batch sizes and ingredient complexity.
Foodservice procurement teams at universities and healthcare systems are consolidating supplier rosters around operators with captive frozen logistics infrastructure spanning multiple climate zones. Direct sourcing agreements are displacing broadline distributor intermediaries for high-volume accounts with predictable consumption patterns. This concentration is most visible across the Sun Belt, where Texas and Arizona institutional buyers prioritize supply security over SKU breadth.
United States Frozen Pizza Market Segmentation
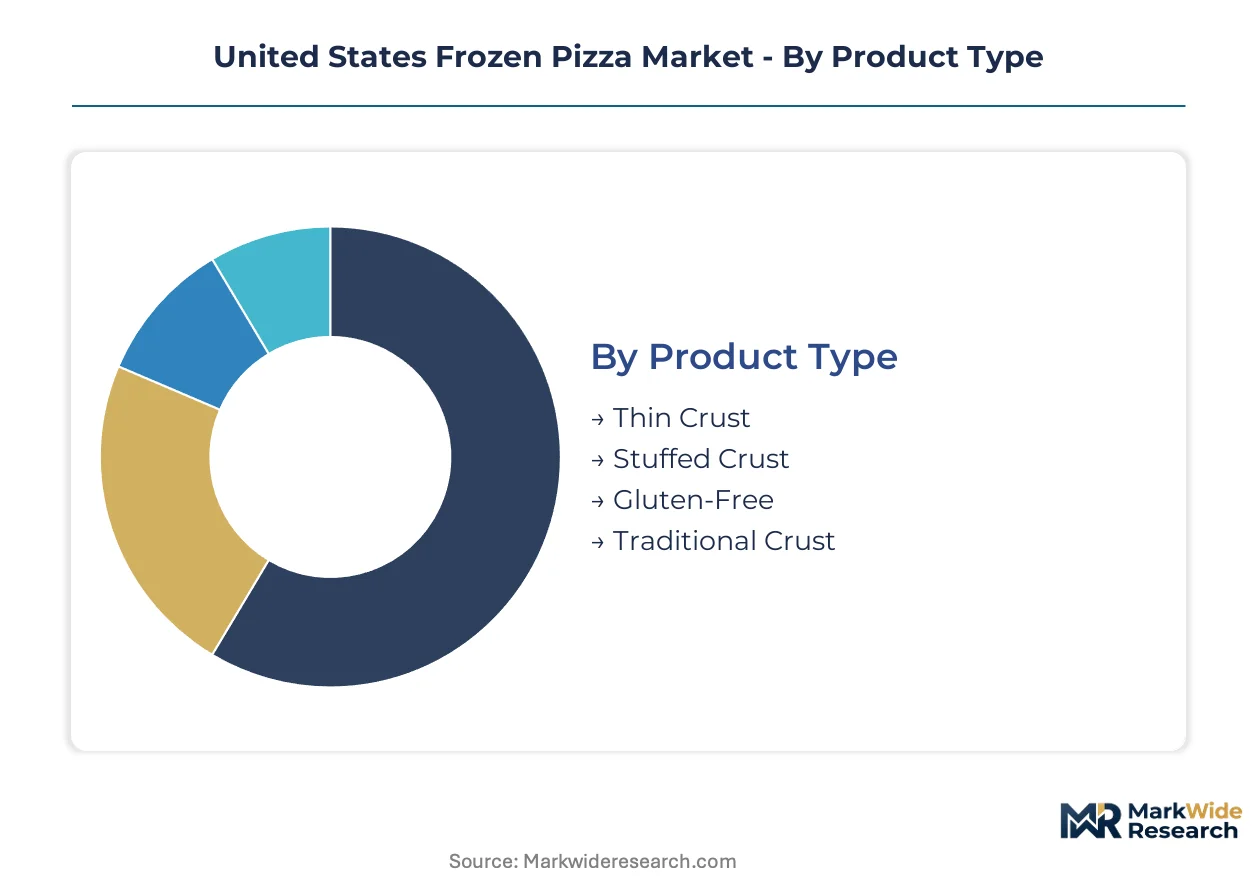
Frozen pizza segmentation reveals how formulation, channel, and occasion-specific requirements fragment procurement priorities across institutional and at-home buyers. Understanding these divides exposes where margin pools concentrate versus where volume throughput dominates.
Product Type:
Mature thin-crust platforms anchor volume throughput while emerging gluten-free formulations capture disproportionate margin expansion.
- Thin Crust:Lower moisture content reduces freight cost per unit and accelerates oven recovery times in foodservice operations. Midwest manufacturing clusters in Wisconsin and Minnesota ship par-baked thin-crust platforms to institutional buyers across the Great Plains and Texas corridor, leveraging density for freight-cost advantages.
- Gluten-Free:Alternative flour systems and dedicated production lines elevate unit economics despite smaller batch sizes. Demand concentrates in coastal metropolitan markets where health-conscious retail buyers absorb premium pricing for clean-label ingredient systems.
- Stuffed Crust:Cheese-injected rim formulations require specialized extrusion equipment and extended freeze times.
- Traditional Crust:Standard-rise dough platforms serve mass-market retail with familiar texture profiles and lower production complexity.
Thin crust handles the majority of throughput; gluten-free is the fastest mover on share.
Distribution Channel:
Cost tier separation between slotting-fee-heavy physical retail and emerging direct-to-freezer digital channels is restructuring go-to-market economics.
- Supermarkets:Mass-market grocers extract annual price commitments and control shelf placement through category captain arrangements. Conagra Brands leverages its Omaha-based distribution network to defend retail footprint across this channel, facing compressed margins from dairy input volatility.
- Online Retail:Direct-to-freezer delivery models bypass traditional grocery slotting fees and enable subscription-based replenishment. E-commerce infrastructure investments concentrate among operators with captive frozen logistics spanning multiple climate zones.
- Convenience Stores:Impulse-oriented single-serve SKUs with extended shelf stability for limited cold-chain capacity.
- Specialty Stores:Premium and organic assortments targeting ingredient-conscious buyers with narrower distribution radii.
Supermarkets retain volume dominance; online retail is expanding most quickly as institutional buyers consolidate direct sourcing agreements.
Flavor Profile:
Application-driven segmentation separates protein-forward platforms for institutional feeding from vegetable-heavy SKUs for health-positioned retail.
- Pepperoni:USDA FSIS-inspected meat toppings dominate college and university foodservice procurement for portion consistency and extended shelf stability. Campus dining programs across the Sun Belt prioritize supply security for high-velocity protein platforms.
- Vegetable:FDA FSMA preventive controls govern ingredient safety as high-pressure processing migrates from niche organic lines to mainstream retail. Mass-market grocers in the Upper Midwest now specify HPP-treated vegetable toppings to reduce spoilage claims.
- Barbecue Chicken:Pre-cooked poultry toppings with sauce integration requiring balanced moisture management.
- Cheese:Mozzarella and analog blends facing reformulation pressure from FDA sodium reduction targets and front-of-package warning label proposals.
Pepperoni carries institutional volume; vegetable formulations are gaining share fastest on clean-label migration.
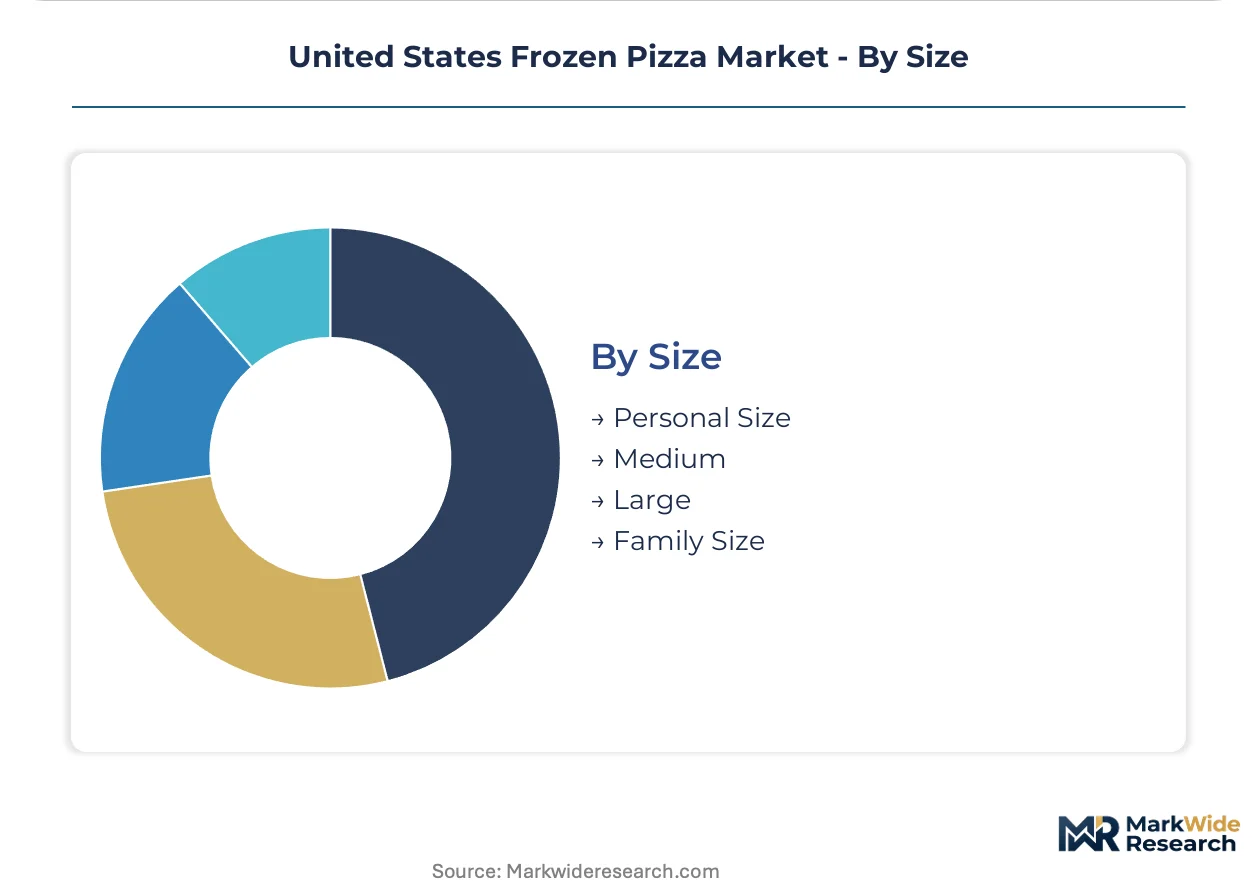
Size:
Customer type segmentation maps portion requirements across solitary convenience consumption, family meal occasions, and high-volume institutional feeding.
- Personal Size:Single-serve platforms target at-home convenience consumption and grab-and-go retail with rapid bake times. College campus retail operations specify personal-size par-baked platforms for residential dining and late-night service windows.
- Family Size:Multi-portion formats serve household replenishment and healthcare system feeding programs with predictable consumption patterns. Texas and Arizona institutional buyers prioritize supply security over SKU breadth for these high-volume accounts.
- Medium:Mid-scale offerings balancing portion flexibility with production batch efficiency.
- Large:Expanded diameter platforms for social occasions and foodservice buffet applications.
Family size dominates institutional procurement; personal size shows the steepest expansion trajectory on single-person household growth and campus retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Sun Belt institutional buyers as supply security premiums override freight-cost advantages anchored in the Midwest manufacturing belt. Wisconsin and Minnesota processing clusters retain production density while Texas and Arizona buyers command procurement leverage through consolidated direct-sourcing agreements.
Midwest Manufacturing Belt
Par-baked thin-crust platforms dominate volume throughput for college foodservice programs across the Great Plains corridor. FDA FSMA preventive controls govern cheese analog and vegetable ingredient safety, elevating compliance costs for regional entrants lacking captive quality assurance laboratories. Minneapolis-St. Paul processing clusters anchor Schwan's Company captive frozen logistics infrastructure spanning to Texas demand nodes.
Southwest Institutional Corridor
Texas and Arizona healthcare systems and university dining programs prioritize supply security over SKU breadth for high-volume family-size procurement. State-level cottage food laws create uneven market access thresholds that favor multi-state operators with centralized licensing infrastructure. Dallas-Fort Worth distribution hubs concentrate cold-chain talent scarcity pressures for blast-freeze maintenance technicians.
Southeast Campus Retail Expansion
Personal-size platforms show steepest expansion trajectory on single-person household growth and late-night campus retail service windows. Front-of-package warning label proposals in select state legislatures reshape reformulation roadmaps ahead of federal compliance deadlines. Atlanta and Charlotte metropolitan markets absorb premium pricing for clean-label gluten-free formulations.
Pacific Coast Premium Markets
Gluten-free and organic assortments command disproportionate margin pools in California and Washington metropolitan corridors despite smaller base volumes. High-pressure processing for sauce pasteurization migrates from niche organic lines to mainstream retail SKUs as private-label buyers adopt extended-safety protocols. Los Angeles and San Francisco cold-chain infrastructure gaps persist for direct-to-freezer e-commerce fulfillment.
Northeast Regulatory Laboratory
Sodium reduction targets and front-of-package warning label proposals concentrate legislative activity in New York and Massachusetts statehouses. FDA updated Nutrition Facts labeling requirements force simultaneous disclosure of added sugars and revised serving sizes across frozen pizza portfolios. Boston and New York Metro institutional buyers consolidate supplier rosters around operators with multi-climate-zone logistics capabilities.
United States Frozen Pizza Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ingredient and logistics niches. The vendor base stratifies between mass-market retail portfolio holders, premium clean-label specialists, and institutional supply security providers. Three archetypes dominate: captive logistics operators, asset-light brand licensors, and contract manufacturing consolidators. M&A activity concentrates on cold-chain infrastructure acquisitions while portfolio diversification moves target gluten-free and sodium-reduced formulation platforms.
Among Midwest-anchored operators, Conagra Brands Inc., Schwan's Company, and Nestlé SA occupy positions across distinct competitive tiers. Conagra Brands exemplifies mass-market retail footprint defense through Omaha-based distribution network control. Schwan's Company anchors institutional supply security through captive frozen logistics spanning Minnesota to Texas. Nestlé SA represents premium-tier R&D intensity in clean-label ingredient systems.
| Leading Market Players |
|---|
| Conagra Brands Inc. |
| Palermo Villa Inc. |
| Nestlé SA |
| Rich Products Corp. |
| Caulipower LLC |
| General Mills Inc. |
| Amy's Kitchen Inc. |
| Bernatellos Foods |
| Schwan's Company |
| Others |
Cost & Logistics Intelligence
The Minnesota-to-Texas freight corridor generates cost asymmetries that concentrate supply control among operators with captive frozen logistics while forcing three-tier pricing stratification across premium clean-label, standard mass-market, and economy private-label tiers.
Pricing Analysis
College and university foodservice programs anchor contract-based long-term procurement pricing with annual volume commitments that insulate operators from dairy input volatility. Price differentiation hinges on clean-label certification tier and geographic delivery distance from Wisconsin processing clusters. Cost compression in the mass-market tier is intensifying as mozzarella and cheese analog swings compress margins for operators locked into retail price commitments. Institutional buyers exhibit lowest price sensitivity due to supply security premiums, while convenience store channels face acute pressure from freight-cost absorption demands.
Supply Chain Analysis
Extended payment terms from mass-market grocers now stretch to ninety days, forcing contract manufacturers toward supply-chain finance facilities to bridge working capital gaps. Production concentrates in Wisconsin, Minnesota, and limited Nebraska facilities that anchor Conagra Brands' Omaha distribution network. Raw material dependencies center on mozzarella blocks, specialized gluten-free flour systems, and blast-freeze equipment components sourced from regional industrial suppliers. Single-source vulnerability persists for high-pressure processing equipment used in sauce pasteurization. Distribution runs through captive frozen logistics for institutional accounts and third-party cold-chain leasing for emerging digital-native brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen pizza market sits at a platform-economics inflection where direct-to-freezer e-commerce interoperability with institutional procurement systems will determine next-generation competitive control.
For Market Incumbents: Build captive logistics moats through multi-climate-zone cold-chain infrastructure spanning from Minnesota processing clusters to Sun Belt demand nodes. Conagra Brands exemplifies this through Omaha-based distribution network control that defends retail shelf placement against emerging digital-native entrants. Add blast-freeze capacity in Texas corridor proximity to capture institutional supply security premiums from healthcare system consolidation.
For New Entrants and Emerging Players: Southeast campus retail corridors show underpenetration for personal-size clean-label platforms targeting single-person household growth and late-night service windows. Atlanta and Charlotte metropolitan markets absorb premium pricing for gluten-free formulations with minimal incumbent presence. Pursue subscription-based replenishment models that bypass traditional grocery slotting fees through direct-to-freezer delivery partnerships.
For Investors and Strategic Acquirers: Asset-light contract manufacturers with flexible third-party networks represent the priority acquisition archetype as production control tilts toward brands that outsource rather than own brick-and-mortar plants. Long-term viability hinges on sodium-reduced formulation pipelines ahead of FDA compliance deadlines. Monitor front-of-package warning label legislative activity in New York and Massachusetts as inflection indicators for reformulation investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Captive frozen logistics spanning Minnesota to Texas secures institutional supply security premiums from healthcare systems. |
| Direct-to-Consumer Launch | Subscription-based replenishment models bypass grocery slotting fees and capture single-person household growth. |
| Premium Tier Introduction | Clean-label gluten-free formulations command disproportionate margin pools in coastal metropolitan markets. |
| Backward Integration into Cheese Analog Production | In-house production of sodium-reduced sauce systems hedges dairy input volatility and accelerates FDA compliance. |
| Sustainability Repositioning | High-pressure processing adoption reduces spoilage claims and extends distribution radii from Wisconsin hubs. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with frozen food category managers, college foodservice procurement directors, blast-freeze equipment technicians, and refrigerated transport fleet operators; and secondary validation through FDA FSMA compliance filings, USDA FSIS inspection protocols, Nielsen retail audit data, and SEC 10-K disclosures from publicly traded operators. Bottom-up shipment data from Wisconsin and Minnesota processing clusters triangulated against top-down channel revenue estimates.
Forecast inputs considered thin-crust versus gluten-free formulation growth trajectories, institutional procurement consolidation patterns, and e-commerce penetration rates across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, flavor profile, and size tier alongside regional cold-chain infrastructure maturity. CAGRs were derived from elasticity-adjusted volume projections and price-mix assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native entrants with supply-chain finance backing would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Basil Leaves Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Low-Fat Cool Whip Market