
 Cambodia Frozen Food Market | 2026-2036
Cambodia Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia Frozen Food Market Outlook
Consolidation among urban restaurant chains is restructuring procurement patterns across the Cambodia frozen food landscape. Charoen Pokphand Foods Public Company Limited leverages its integrated poultry operations to dominate supply contracts with mid-sized hospitality groups. Tyson Foods, Inc. competes through frozen meat portfolios calibrated to quick-service kitchen specifications. Khmer Angkor Food Co., Ltd. anchors its position via localized distribution networks penetrating provincial towns beyond Phnom Penh.
Frozen food comprises perishable products preserved at sub-zero temperatures to arrest microbial activity and maintain nutritional integrity, typically stored at minus 18 degrees Celsius through blast freezing or cryogenic tunnel processes, serving commercial kitchens and retail consumers requiring extended shelf stability without additive dependence. Frozen seafood commands premium positioning in supermarket aisles due to Cambodia's Mekong-Delta sourcing proximity and rising consumer protein diversification. Online retail channels represent the fastest-growing distribution vector as mobile commerce penetration accelerates last-mile cold delivery investments. Bulk packs retain dominance in the food processing end-user segment where manufacturers prioritize ingredient cost efficiency over presentation.
Cambodia's Ministry of Commerce and the country's national food safety regulator enforce import documentation and cold chain compliance standards that elevate barrier thresholds for unverified suppliers. The ASEAN Free Trade Area framework reduces tariff friction for Thai and Vietnamese frozen goods crossing into Cambodian wholesale markets. Stakeholders must monitor evolving packaging waste directives and the pace of domestic cold storage capacity buildout to calibrate inventory positioning and partnership strategies.
Market Dynamics
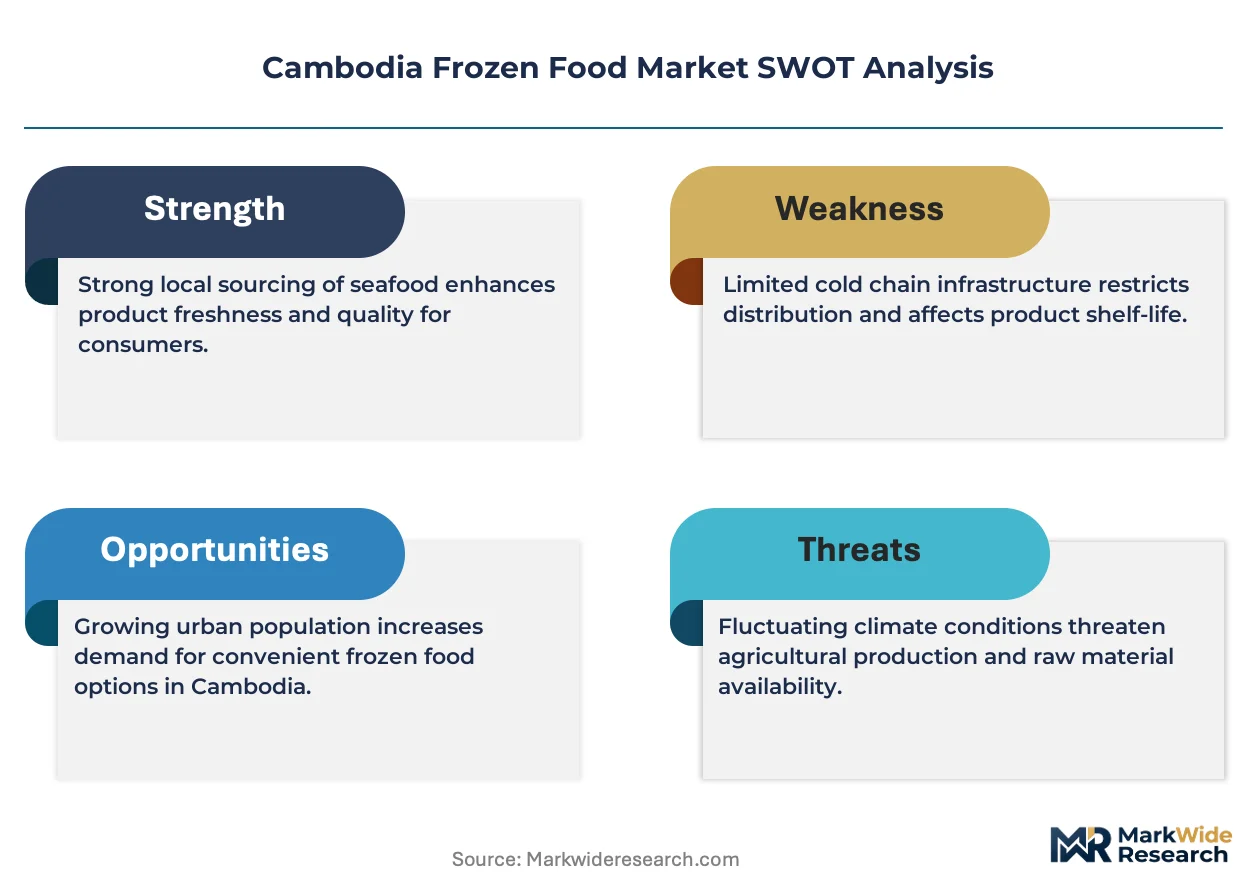
Cold chain infrastructure buildout across Cambodia's provincial corridors is compressing delivery windows for frozen seafood and ready-to-cook proteins, forcing distributors to recalibrate inventory positioning and last-mile partnerships around blast-freezing capacity rather than traditional ice-based transport.
Growth Catalysts
- ASEAN Free Trade Area tariff reductions:Cross-border friction declines for Thai and Vietnamese frozen goods entering Cambodian wholesale markets through Poipet and Bavet border checkpoints.
- Quick-service restaurant expansion:Phnom Penh-based chains standardize kitchen specifications around frozen protein formats to reduce spoilage and labor costs.
- Blast freezing tunnel deployment:Domestic processors adopt cryogenic tunnel technology to extend shelf stability of Mekong-sourced seafood without chemical preservatives.
Market Restraints
- Diesel-powered cold transport dependency:Fuel price volatility directly inflates per-unit logistics costs for frozen goods moving between Siem Reap and provincial distribution nodes.
- Import documentation stringency:Cambodia's Ministry of Commerce and national food safety regulator enforce FSSAI-aligned standards that disqualify unverified Thai and Vietnamese suppliers.
- Fresh wet market substitution:Traditional morning markets in Battambang and Kampong Cham retain price-sensitive protein buyers who prioritize same-day catch over frozen convenience.
Strategic Opportunities
- Sihanoukville port cold storage gap:Underdeveloped reefers at Cambodia's primary maritime gateway create first-mover advantage for operators building bonded frozen warehousing.
- Mobile commerce channel emergence:Delivery apps penetrate Phnom Penh's middle-class households, enabling direct-to-consumer frozen seafood sales that bypass traditional wet market intermediaries.
- Domestic cold chain incentive schemes:Government-backed infrastructure loans target provincial blast-freezing facilities outside the capital corridor.
Industry Challenges
- HACCP certification timelines:Small-scale Cambodian processors face 12-18 month approval windows to meet export-grade food safety management standards.
- Refrigeration technician scarcity:Specialized maintenance skills for ammonia-based industrial freezing systems concentrate in Phnom Penh, leaving provincial facilities dependent on costly capital-city contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia Frozen Food Market |
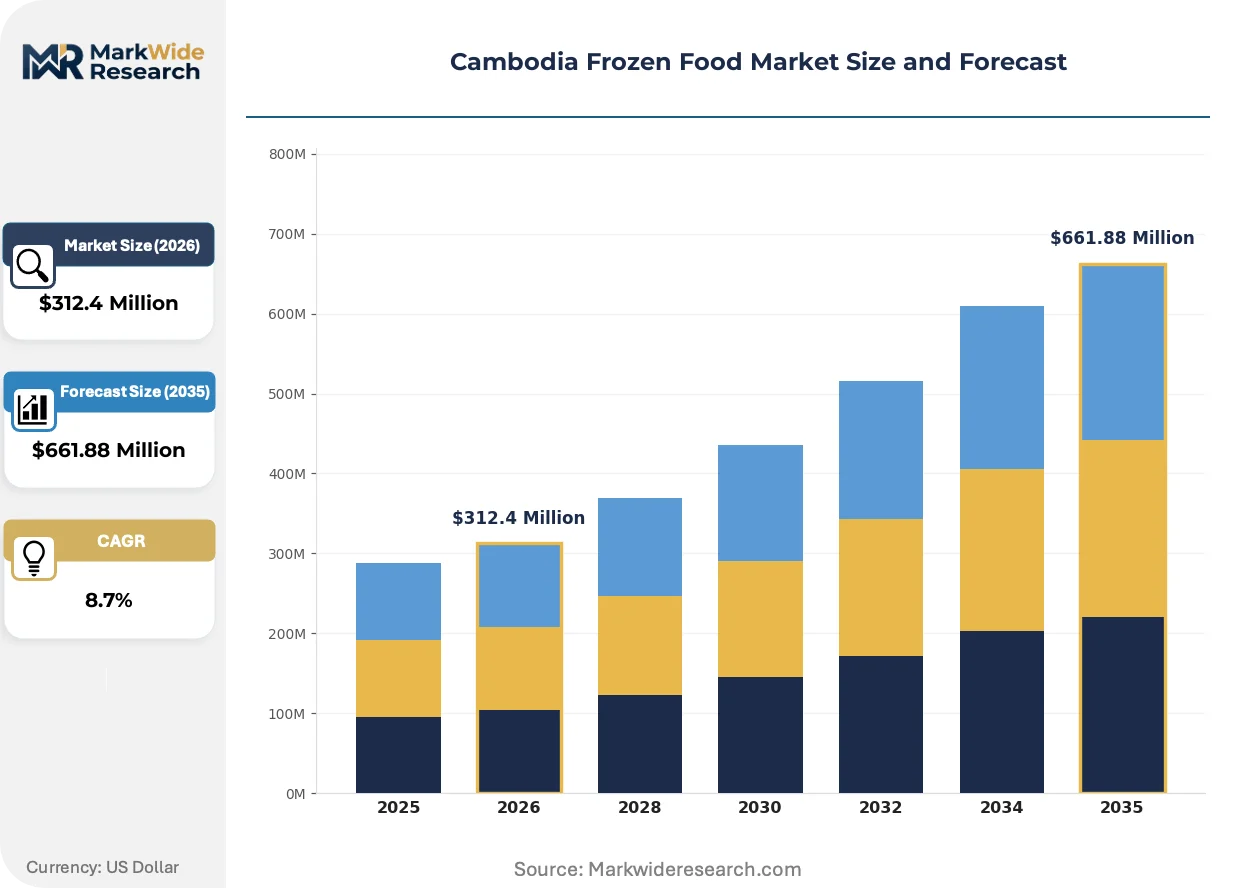
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Seafood, Frozen Meats, Frozen Desserts Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Restaurants, Cafes, Food Processing Packaging Type: Retail Packs, Bulk Packs, Single-Serve Containers, Eco-Friendly Packaging |
| Companies Covered | Tyson Foods, Inc., DiraFrost, Betagro Co., Ltd., Les Vergers Boiron, Natural Garden, Ajinomoto Co., Ltd., Unilever PLC, Khmer Angkor Food Co., Ltd., Charoen Pokphand Foods Public Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia Frozen Food Market Strategic Shifts
Technology adoption across Cambodia's frozen food supply chain is compressing traditional preservation timelines while regulatory alignment with ASEAN standards reshapes import compliance workflows. Distribution channels fragment as mobile platforms disintermediate conventional wholesale hierarchies.
Blast freezing tunnel technology is electrifying preservation economics for domestic seafood processors. Mekong Delta catch operations near Kampong Som deploy cryogenic nitrogen tunnels to arrest enzymatic degradation within hours of harvest. Mid-sized hospitality suppliers in Phnom Penh adopt these systems to reduce ice-dependency and extend delivery radii to Siem Reap without quality degradation.
Cambodia's national food safety regulator enforces cold chain documentation standards that mirror FSSAI import protocols. Thai frozen meat exporters face elevated barrier thresholds at Bavet and Poipet checkpoints, compelling documentation pre-clearance investments. Wholesale distributors respond by consolidating supplier relationships around pre-certified Vietnamese and Thai operators with established compliance histories.
Mobile commerce penetration is restructuring last-mile frozen distribution in urban Cambodia. Phnom Penh households increasingly source frozen seafood through delivery applications rather than traditional Psar Thmei wholesale runs. Cold-box logistics providers build dedicated frozen fleets to serve this channel, compressing delivery windows from same-day to two-hour slots in central districts.
Cambodia Frozen Food Market Segmentation
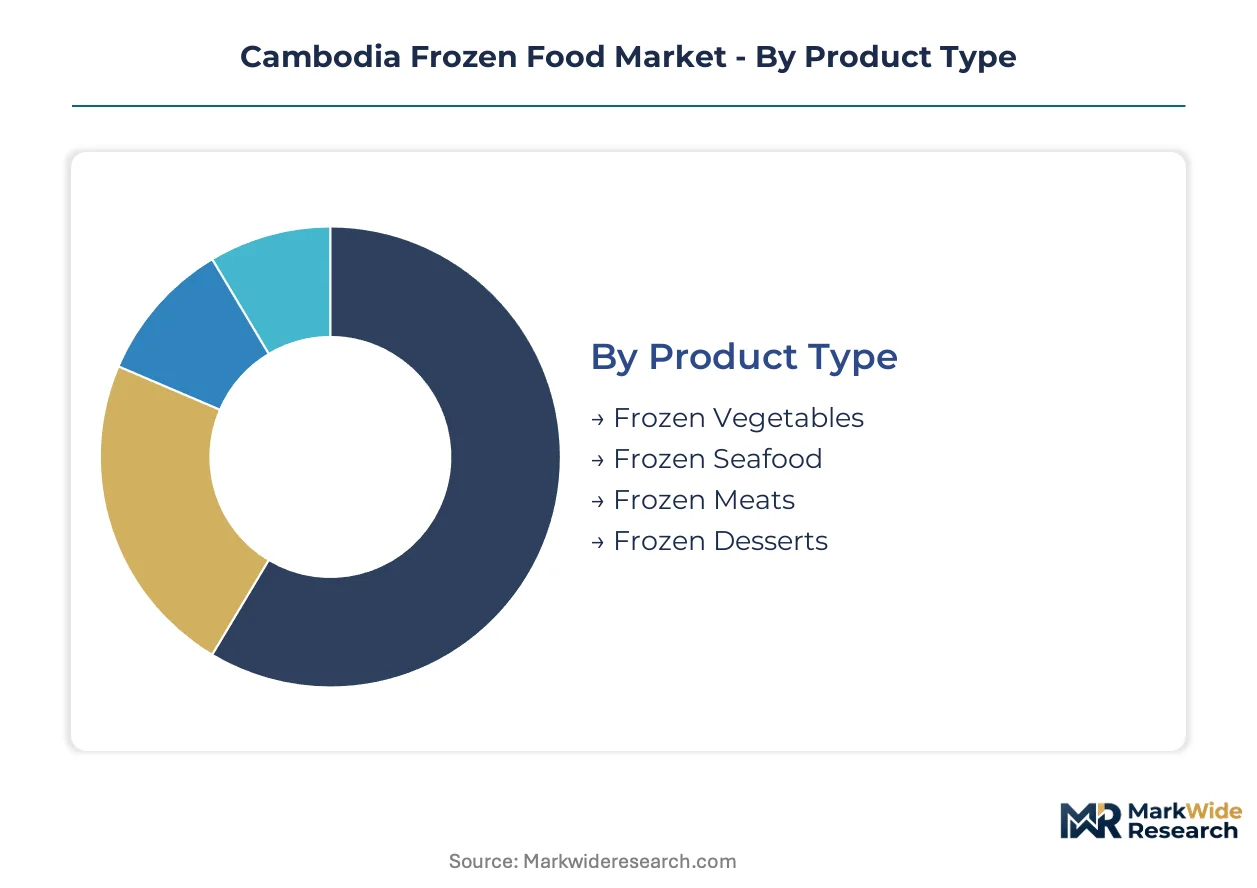
Segmentation in Cambodia's frozen food market reveals how cold chain maturity and urban income stratification create divergent product requirements. Distributors calibrate inventory depth and packaging formats around distinct procurement rhythms across hospitality, retail, and industrial channels.
Product Type:
Customization intensity varies sharply across this category, with seafood and meat processors offering blast-frozen specification tuning for hospitality buyers while vegetables and desserts ship as standardized SKUs.
- Frozen Seafood:Mekong Delta catch and marine species processed through cryogenic tunnel freezing to arrest enzymatic degradation. Phnom Penh hotel chains and Siem Reap hospitality corridors drive premium positioning for individually quick-frozen shrimp and fillet portions.
- Frozen Meats:Poultry, beef, and pork cuts preserved at minus 18 degrees Celsius through blast freezing, with Tyson Foods and Charoen Pokphand supplying quick-service restaurant specifications. Battambang provincial distributors face diesel transport cost pressure moving refrigerated containers from capital-based cold stores.
- Frozen Vegetables:Standardized IQF peas, corn, and mixed blends for food manufacturing and institutional catering.
- Frozen Desserts:Ice cream and pastry products targeting urban supermarket aisles and cafe dessert menus.
Leading the category by volume: Frozen Meats. Expanding most quickly: Frozen Seafood.
Distribution Channel:
Channel selection maps directly to order frequency and cold chain reliability requirements, with high-volume wholesale and emerging mobile commerce commanding distinct logistics investments.
- Supermarkets:Retail frozen aisles in Phnom Penh's Aeon Mall and Lucky Supermarket locations stock blast-frozen seafood and ready-to-cook proteins for middle-class households. Shelf-space allocation favors premium imported brands alongside domestic Mekong-sourced products.
- Online Retail:Mobile commerce platforms penetrate urban corridors with two-hour frozen delivery slots. Dedicated cold-box fleets bypass traditional wet market intermediaries, compressing last-mile windows for Phnom Penh households.
- Convenience Stores:Limited frozen SKUs targeting impulse purchases and single-serve meal solutions.
- Wholesale:Bulk procurement channels serving Battambang and Kampong Cham provincial distributors from capital-based cold storage facilities.
Wholesale channels dominate absolute volume throughput. Online retail channels gain share fastest among urban consumer segments.
End User:
User type determines packaging scale and delivery cadence, with food processors demanding tonnage efficiency while cafes prioritize presentation-grade portion control.
- Restaurants:Mid-sized hospitality groups in Phnom Penh and Siem Reap standardize kitchen specifications around frozen protein formats to reduce spoilage and labor prep time. Charoen Pokphand leverages integrated poultry operations to dominate supply contracts through pre-certified compliance documentation.
- Food Processing:Manufacturers prioritize bulk packs and ingredient cost efficiency over retail presentation, sourcing Mekong-sourced seafood for value-added product lines.
- Households:Urban consumers in Phnom Penh's Boeung Keng Kang and Toul Kork districts adopt frozen convenience for protein diversification.
- Cafes:Beverage-focused outlets requiring dessert and pastry components in controlled portion formats.
Restaurants command the largest procurement volumes. Food Processing demonstrates the steepest expansion trajectory as domestic manufacturing capacity builds out.
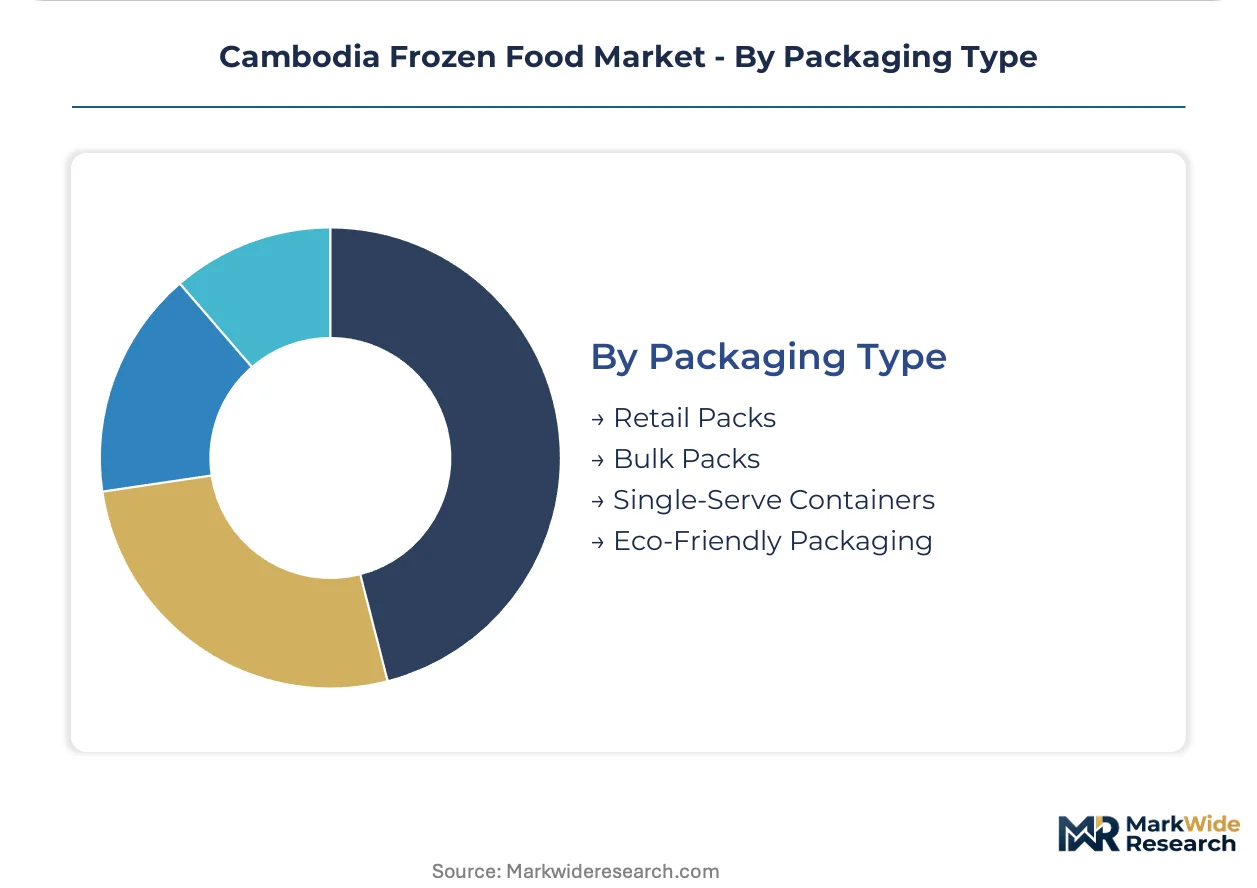
Packaging Type:
Packaging economics separate high-frequency retail replenishment from capital-efficient bulk handling, with sustainability pressures beginning to reshape material specifications.
- Bulk Packs:Industrial-scale cartons and totes for food processing manufacturers prioritizing per-kilogram cost minimization over shelf aesthetics. Kampong Som seafood processors ship Mekong catch in 10-kilogram blocks to Phnom Penh-based manufacturers.
- Retail Packs:Consumer-facing pouches and boxes with nutritional labeling and brand positioning for supermarket frozen aisles.
- Single-Serve Containers:Portion-controlled formats for cafe dessert menus and convenience store meal solutions.
- Eco-Friendly Packaging:Biodegradable and recyclable materials responding to emerging Cambodian Ministry of Environment directives on packaging waste reduction.
Bulk Packs dominate tonnage movement. Eco-Friendly Packaging climbs fastest as regulatory pressure and buyer preferences converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Cambodia's urban corridor linking Phnom Penh to Siem Reap, where hospitality procurement and middle-class retail adoption drive frozen food volume. Provincial cold chain buildout is compressing delivery windows to secondary cities. The country's national food safety regulator enforces import standards that reshape cross-border trade patterns.
Phnom Penh Capital Region
Quick-service restaurant chains and hotel groups anchor frozen protein procurement in the capital. Cambodia's Ministry of Commerce enforces FSSAI-aligned documentation standards at wholesale entry points. Aeon Mall and Lucky Supermarket clusters in Chamkarmon and Toul Kork districts stock blast-frozen seafood for middle-class households.
Siem Reap Hospitality Corridor
Tourism-dependent foodservice operations drive premium frozen seafood demand for international hotel kitchens. The country's national food safety regulator mandates cold chain compliance certificates for imported Thai and Vietnamese goods. Pub Street and airport-zone hospitality clusters rely on capital-based distributors for last-mile frozen delivery.
Sihanoukville Port Zone
Maritime gateway status creates frozen warehousing demand for Mekong-sourced seafood re-export. Cambodia's Ministry of Commerce oversees bonded cold storage licensing at the deepwater port. Kampong Som processing facilities deploy cryogenic tunnel freezing for shrimp and fish bound for Phnom Penh manufacturers.
Battambang Agricultural Belt
Rice-processing towns and provincial distributors source frozen meats from capital cold stores despite diesel transport cost pressure. The country's national food safety regulator extends documentation requirements to provincial wholesale nodes. Morning market traditions in Battambang city sustain fresh wet market substitution for price-sensitive protein buyers.
Kampong Cham Mekong Riverside
Riverine fishing communities supply raw catch to blast-freezing facilities serving domestic food processors. Cambodia's Ministry of Commerce cold chain incentive schemes target provincial infrastructure loans outside the capital. National Road 7 distribution corridors link riverside processors to Phnom Penh manufacturing demand.
Cambodia Frozen Food Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue mobile commerce channels and provincial cold chain partnerships. The market structures around integrated poultry operators, multinational protein suppliers, and localized distribution networks. Three archetypes dominate: ASEAN-integrated conglomerates with captive supply chains, global meatpackers with quick-service specifications, and domestic distributors with provincial penetration. Competitive moves concentrate on cold storage capacity expansion and pre-certified compliance documentation investments.
Within the ASEAN-integrated tier, Charoen Pokphand Foods Public Company Limited exemplifies conglomerate positioning through poultry operations spanning Thailand and Cambodia. Tyson Foods, Inc. represents multinational meatpacker archetype with frozen protein portfolios calibrated to foodservice specifications. Khmer Angkor Food Co., Ltd. anchors the domestic distributor archetype through localized networks reaching provincial towns beyond the capital corridor.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| DiraFrost |
| Betagro Co., Ltd. |
| Les Vergers Boiron |
| Natural Garden |
| Ajinomoto Co., Ltd. |
| Unilever PLC |
| Khmer Angkor Food Co., Ltd. |
| Charoen Pokphand Foods Public Company Limited |
| Others |
Value Chain & Pricing Dynamics
Diesel fuel costs cascade through Cambodia's frozen food pricing architecture, compressing margins for provincial distributors moving refrigerated containers from Phnom Penh cold stores to Battambang and Kampong Cham while capital-based hospitality buyers absorb premium positioning for blast-frozen Mekong seafood.
Pricing Analysis
Volume throughput concentrates in wholesale bulk packs where per-kilogram cost minimization dominates procurement decisions, while premium margins attach to individually quick-frozen seafood portions for Phnom Penh hotel chains. Price differentiation hinges on cold chain certification grade and geographic delivery radius from blast-freezing facilities. Pricing pressure stems from diesel transport volatility inflating logistics costs for secondary city distribution. Food processing manufacturers exhibit highest price sensitivity due to ingredient cost efficiency priorities, whereas Siem Reap hospitality clusters show lowest sensitivity for presentation-grade protein specifications.
Supply Chain Analysis
Regional distribution centers in Phnom Penh's Chamkarmon and Toul Kork districts anchor hub-and-spoke patterns radiating to provincial nodes. Supply concentration rests on Thailand and Vietnam as dominant frozen meat sources crossing through Poipet and Bavet checkpoints, with domestic Mekong Delta catch feeding Kampong Som processing facilities. Raw material dependencies include cryogenic nitrogen for tunnel freezing, diesel for refrigerated transport, and imported poultry genetics for breeding stock. Single-source vulnerability concentrates in ammonia-based industrial freezing system maintenance skills hoarded in the capital. Distribution runs through wholesale channels for volume, with mobile commerce building dedicated cold-box fleets for urban last-mile compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cambodia's frozen food sector is becoming a vertical-integration race where captive cold storage capacity and pre-certified import documentation determine competitive survival. Players are pursuing upstream control over blast-freezing infrastructure to lock in margin capture.
For Market Incumbents: Cement supply contract dominance by expanding bonded cold storage licensing at Sihanoukville port ahead of competitor entry. Integrate backward into cryogenic tunnel equipment partnerships to reduce maintenance dependency on Phnom Penh technician pools. Charoen Pokphand's integrated poultry model demonstrates how captive breeding-to-processing control neutralizes Thai import documentation volatility at Bavet checkpoints.
For New Entrants and Emerging Players: Cambodia's Ministry of Commerce cold chain incentive schemes open a window for provincial blast-freezing facility development outside the capital corridor. Target Battambang and Kampong Cham as underpenetrated distribution nodes where diesel transport costs have discouraged incumbent investment. Pursue mobile commerce direct-to-consumer angles that bypass traditional wet market intermediaries in Phnom Penh's Boeung Keng Kang district.
For Investors and Strategic Acquirers: Sihanoukville port cold storage gap closure is the leading indicator that infrastructure maturity is accelerating and first-mover premiums are compressing. Position acquisition screening around domestic distributors with provincial networks and pre-certified FSSAI-aligned import compliance histories. Watch for HACCP certification timeline reductions as the signal that Cambodian processors are achieving export-grade food safety management scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Cold Storage Buildout | Sihanoukville port licensing creates captive warehousing for Mekong seafood re-export. |
| Cryogenic Tunnel Deployment | Nitrogen freezing technology extends shelf stability without chemical preservatives for domestic processors. |
| Pre-Certified Supplier Consolidation | FSSAI-aligned documentation investments reduce Bavet and Poipet checkpoint disqualification risk. |
| Mobile Commerce Channel Entry | Two-hour cold-box delivery fleets bypass traditional Psar Thmei wholesale intermediaries. |
| Provincial Distribution Partnership | Battambang and Kampong Cham nodes capture price-sensitive buyers outside capital corridors. |
Study Parameters
Independent corroboration across cold chain infrastructure assessments, ASEAN trade flow databases, and Cambodia Ministry of Commerce regulatory filings underwrites the qualitative findings in this study. Primary interviews with hospitality procurement managers, provincial distribution operators, blast-freezing facility engineers, and mobile commerce logistics specialists combined with secondary validation from customs records, hotel industry supply chain disclosures, and food safety regulator documentation. Bottom-up demand modeling across restaurants, food processing manufacturers, and household segments triangulated against top-down market sizing from import volume tracking and cold storage capacity estimates.
Comparable historical periods anchored the forecast window to pre-pandemic baseline growth trajectories and post-recovery normalization patterns. Segmentation modeling across product type, distribution channel, end user, and packaging format dimensions incorporated cold chain maturity gradients and urban income stratification patterns. CAGRs were derived from trend extrapolation adjusted for infrastructure buildout pacing and regulatory compliance timeline evolution. Forecast inputs included diesel price volatility scenarios and mobile commerce penetration curves for Phnom Penh middle-class households.
The model assumes a particular technology adoption path; alternative pathways for ammonia-to-CO2 refrigeration conversion or solar-powered cold transport would alter the outlook for provincial delivery cost structures. Forecasts reflect documented assumptions around ASEAN Free Trade Area tariff stability and Cambodia's national food safety regulator enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Canned Vegetables Market