
 Frozen-Cooked Ready Meals Market | 2026-2036
Frozen-Cooked Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen-Cooked Ready Meals Market Foresight
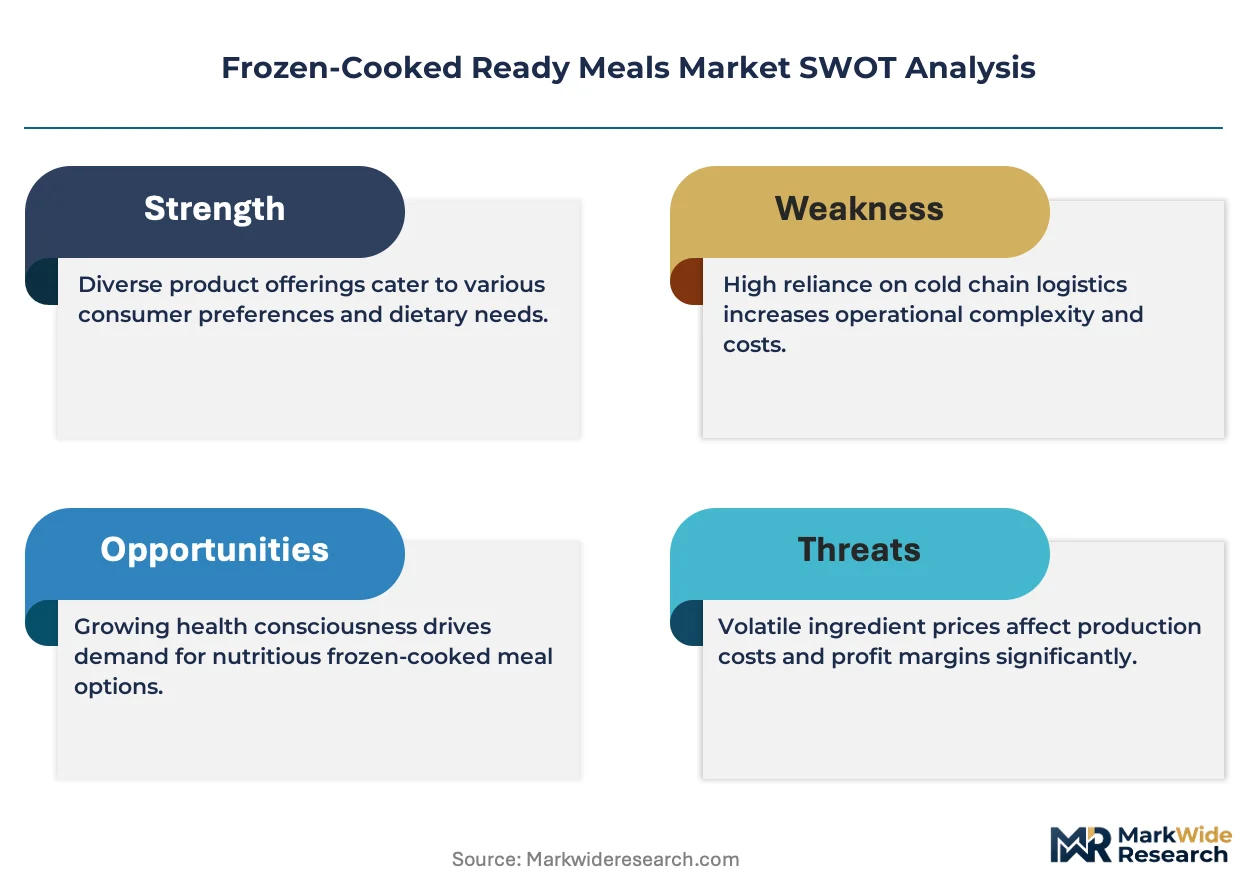
The capital-intensity divergence between blast-freezing infrastructure and conventional chilling capacity is redrawing competitive boundaries in frozen-cooked ready meals. Nestlé leverages its proprietary flash-freezing networks to sustain margin capture across European retail channels. Conagra Brands anchors its position through direct-store-delivery cold-chain control in North American grocery. Ajinomoto competes via umami-based recipe specialization that differentiates its Asian-format offerings from Western-format rivals.
Frozen-cooked ready meals are industrially prepared food products that undergo complete thermal processing followed by rapid temperature reduction to minus 18 degrees Celsius or below, preserving sensory and nutritional integrity for extended shelf life. Their primary commercial purpose is to deliver restaurant-quality convenience to time-constrained consumers without requiring culinary skill or equipment. Vegetarian and vegan product lines are expanding fastest as plant-based protein technology matures, while tray packs dominate packaging due to microwave compatibility and retail shelf visibility. Online retailers represent the most dynamic distribution channel, though supermarkets still occupy the largest margin pool through promotional slotting fees and private-label placement.
EFSA nutritional labeling rules, FDA frozen food safety standards, and Japan's JIS cold-chain specifications collectively shape formulation requirements, packaging disclosures, and import market access across major demand centers. Compliance with these frameworks now demands real-time temperature logging and allergen segregation protocols that smaller producers struggle to fund. Stakeholders must monitor evolving extended producer responsibility mandates for single-use packaging, as regulatory timelines for recyclable tray mandates remain in flux across multiple jurisdictions.
Market Dynamics
Blast-freezing infrastructure concentration is redrawing competitive boundaries in frozen-cooked ready meals, as capital-intensive cold-chain networks create asymmetric barriers between integrated producers and contract manufacturers dependent on third-party logistics.
Growth Catalysts
- Urban single-person household formation:Germany's demographic shift toward time-pressed solo dwellers accelerates premium frozen meal consumption as convenience substitutes for home cooking.
- EFSA cold-chain traceability mandates:Regulatory pressure for real-time temperature logging elevates compliant producers above fragmented regional competitors lacking capital for sensor integration.
- Plant-based protein maturation:Extrusion and fermentation advances enable texture parity in vegetarian lines, expanding addressable demand beyond traditional meat-based formats.
Market Restraints
- Blast-freezing capex concentration:Equipment costs exceeding conventional chilling by 3-4x lock smaller producers out of premium shelf-stable segments.
- European energy price volatility:Natural gas dependence for freezing operations compresses margins when wholesale rates spike, disproportionately affecting Germany and Poland.
- Fresh prepared meal substitution:Chilled short-shelf-life alternatives capture convenience-seeking consumers willing to trade longevity for perceived freshness.
Strategic Opportunities
- Online direct-to-consumer channel expansion:Frozen-cooked ready meals bypass supermarket slotting fees through subscription models targeting working professionals in France and the Netherlands.
- EU Green Deal packaging mandates:Extended producer responsibility timelines create first-mover advantage for producers investing in recyclable tray formats ahead of 2030 compliance deadlines.
- Umami-based recipe specialization:Convergence of Japanese fermentation science with European ingredient sourcing differentiates Asian-format offerings in underpenetrated Nordic markets.
Industry Challenges
- Cold-chain engineer talent scarcity:Specialized expertise in cryogenic systems and thermal dynamics remains concentrated among legacy equipment manufacturers, constraining in-house capability building.
- Allergen segregation protocol complexity:EFSA labeling requirements demand dedicated production lines that fragment capacity utilization across SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen-Cooked Ready Meals Market |
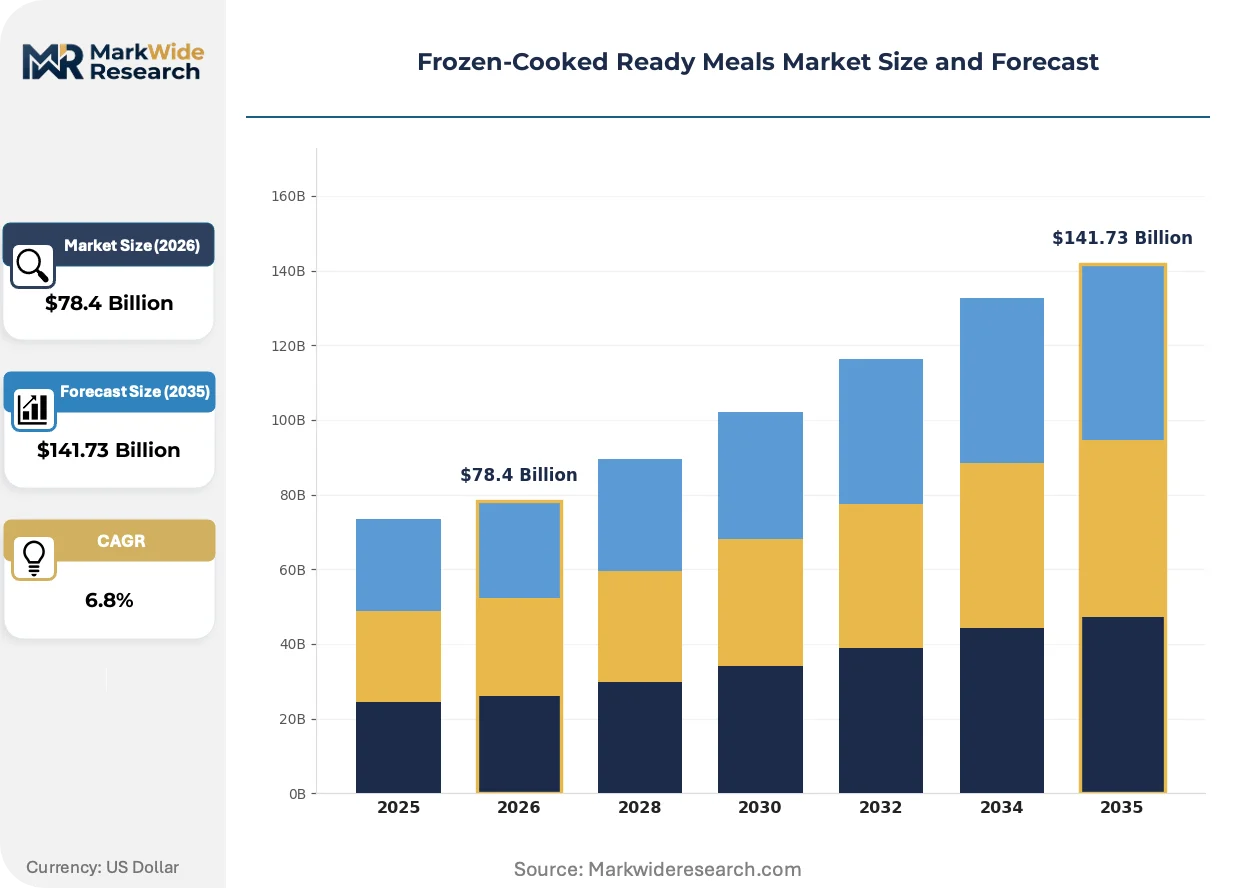
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Non-Vegetarian, Vegan, Gluten-Free, Organic, Low-Calorie Packaging Type: Tray Packs, Vacuum Packs, Cans, Pouches, Boxes, Cartons Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Grocery Stores, Specialty Food Shops, Wholesale End User: Working Professionals, Students, Single Households, Elderly Consumers, Fitness Enthusiasts, Busy Families |
| Companies Covered | Nestlé, Conagra Brands, The Kraft Heinz Company, General Mills, Dr. Oetker, Ajinomoto, Tyson Foods, McCain Foods, Nomad Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen-Cooked Ready Meals Market Shifts & Advancements
Active packaging integration and microwave-responsive materials are compressing preparation friction for end-users while regulatory pressure on single-use plastics forces simultaneous format innovation.
Induction-tolerant susceptor films are displacing conventional PET tray laminates in premium frozen meal packaging. Working professionals in German metropolitan areas adopt these formats for stovetop-quality results without oven preheating. The technology is displacing dual-oven/microwave SKUs that previously segmented premium from economy tiers.
EFSA's evolving extended producer responsibility framework tightens recyclability thresholds for multi-layer packaging. Industrial consequence includes accelerated R&D spending on mono-material tray alternatives and water-based barrier coatings. German retailers are responding fastest, with Rewe and Edeka demanding proof-of-recyclability documentation for promotional slotting eligibility.
Subscription-based replenishment models are compressing traditional supermarket purchase cycles for frozen-cooked ready meals. Direct-to-consumer platforms displace impulse-driven freezer-aisle selection with algorithmic meal planning. France exhibits the most visible shift, where Nestlé and Picard test predictive delivery based on consumption velocity data from connected appliances.
Frozen-Cooked Ready Meals Market Segmentation
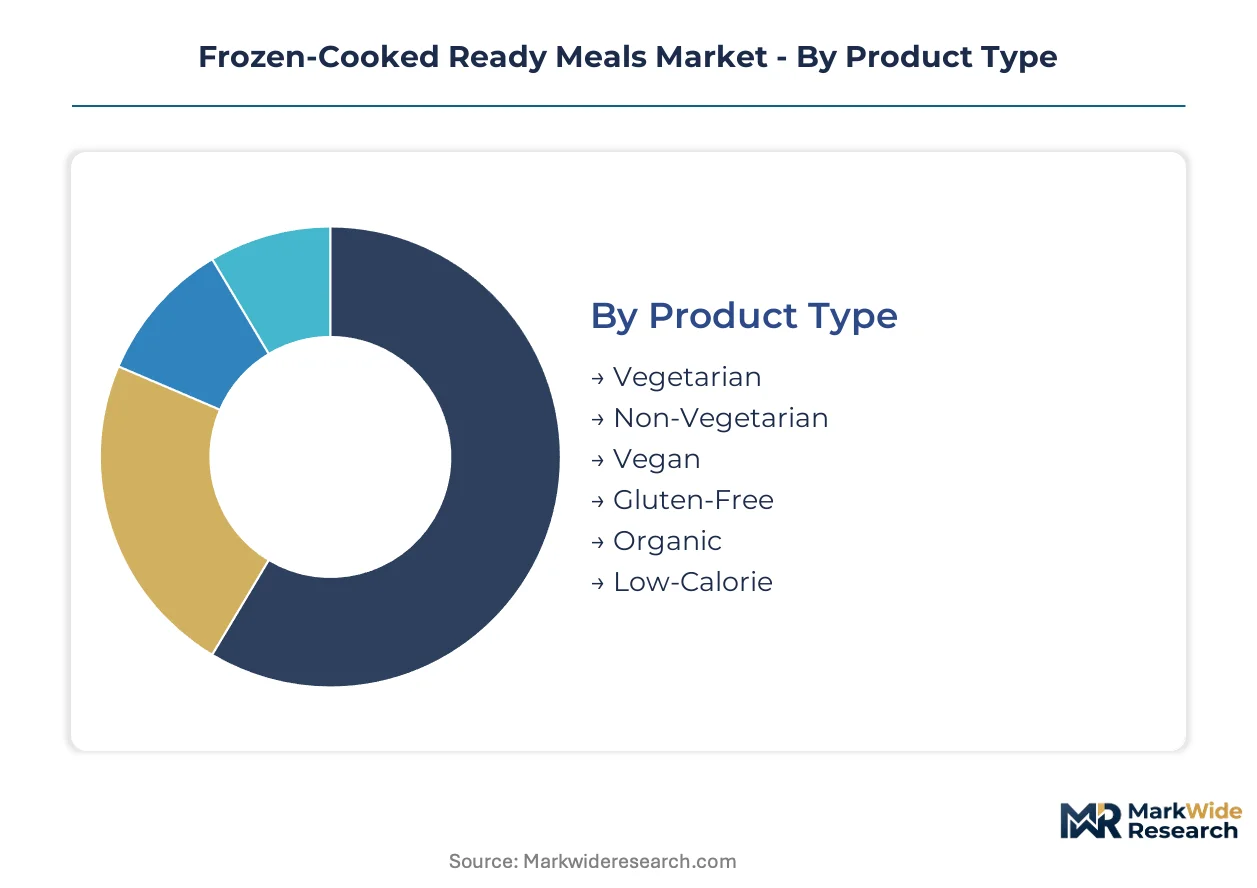
Segmentation in frozen-cooked ready meals reveals how formulation, packaging, and channel choices map to distinct consumer workflows and price tolerance thresholds. Each dimension carries divergent capital requirements and margin profiles that reshape producer strategy across European retail networks.
Product Type:
Vegetarian and vegan lines concentrate in domestic German and French consumption, while non-vegetarian formats still dominate export flows to Nordic and Eastern European markets.
- Vegetarian:Extruded plant proteins and mycelium-based textures now achieve mouthfeel parity with conventional meat in lasagna and curry applications. German single-person households in Berlin and Munich drive volume through Rewe and Edeka private-label placement, though EFSA protein-content labeling requirements complicate formulation standardization across EU member states.
- Vegan:Fermentation-derived dairy analogs and egg replacements enable complete animal-free formulations without sensory compromise. Demand clusters in Netherlands metropolitan corridors where Picard and Albert Heijn premium lines command slotting fee premiums, constrained by shorter acceptable ingredient lists among Dutch regulatory-conscious consumers.
- Non-Vegetarian:Poultry and beef formulations retain cost advantages in price-sensitive Eastern European markets.
- Gluten-Free:Rice and corn-based binders serve celiac-diagnosed populations in Italy and Spain.
- Organic:EU organic certification mandates shape sourcing radius and supplier audit intensity.
- Low-Calorie:Portion-controlled trays target fitness enthusiasts in French urban centers.
Non-vegetarian formats hold the largest share; momentum sits with vegan lines as fermentation technology matures.
Packaging Type:
Cost tiering separates microwave-only economy formats from dual-oven premium configurations, with susceptor film integration commanding 40-60% price premiums over standard PET laminates.
- Tray Packs:Mono-material polypropylene trays with water-based barrier coatings dominate German retail freezer space due to microwave compatibility and vertical stacking efficiency. Rewe's 2025 promotional guidelines now require recyclability documentation for tray pack eligibility, accelerating R&D migration from multi-layer laminates.
- Vacuum Packs:Flexible film configurations with oxygen scavenger integration extend shelf life for premium seafood and poultry applications. French direct-to-consumer subscription services favor vacuum packs for last-mile thermal efficiency, though EFSA extended producer responsibility timelines threaten format viability without recyclability upgrades.
- Pouches:Stand-up configurations with spout integration serve soup and stew categories.
- Cans:Metal formats retain niche presence in long-shelf-life emergency stockpiling segments.
- Boxes:Paperboard exteriors with plastic windows balance sustainability signaling with product visibility.
- Cartons:Gable-top configurations remain marginal outside Nordic breakfast-oriented lines.
Tray packs command the dominant volume position; pouches are climbing the fastest as subscription channels expand.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with supermarket slotting fees consuming 15-25% of wholesale price while direct channels retain full markup control.
- Supermarkets:Edeka, Carrefour, and Albert Heijn freezer aisles generate the largest absolute revenue pools through promotional calendar coordination and private-label placement. Working professionals in German metropolitan areas purchase 60-70% of premium frozen meals through this channel, though slotting fee inflation compresses net margins for secondary brands.
- Online Retailers:Direct-to-consumer platforms and third-party delivery apps bypass traditional retail markups through subscription replenishment models. France exhibits the steepest channel shift, where Nestlé and Picard test predictive delivery based on connected appliance consumption velocity, constrained by last-mile cold-chain integrity requirements.
- Convenience Stores:Urban grab-and-go formats serve time-pressed commuters in Paris and Amsterdam.
- Grocery Stores:Neighborhood formats retain loyalty among elderly consumers with established shopping routines.
- Specialty Food Shops:Organic and gourmet retailers curate premium import selections.
- Wholesale:Foodservice redistribution channels supply workplace canteens and institutional buyers.
Supermarkets retain the largest revenue base; online retailers are gaining share fastest among working professional segments.
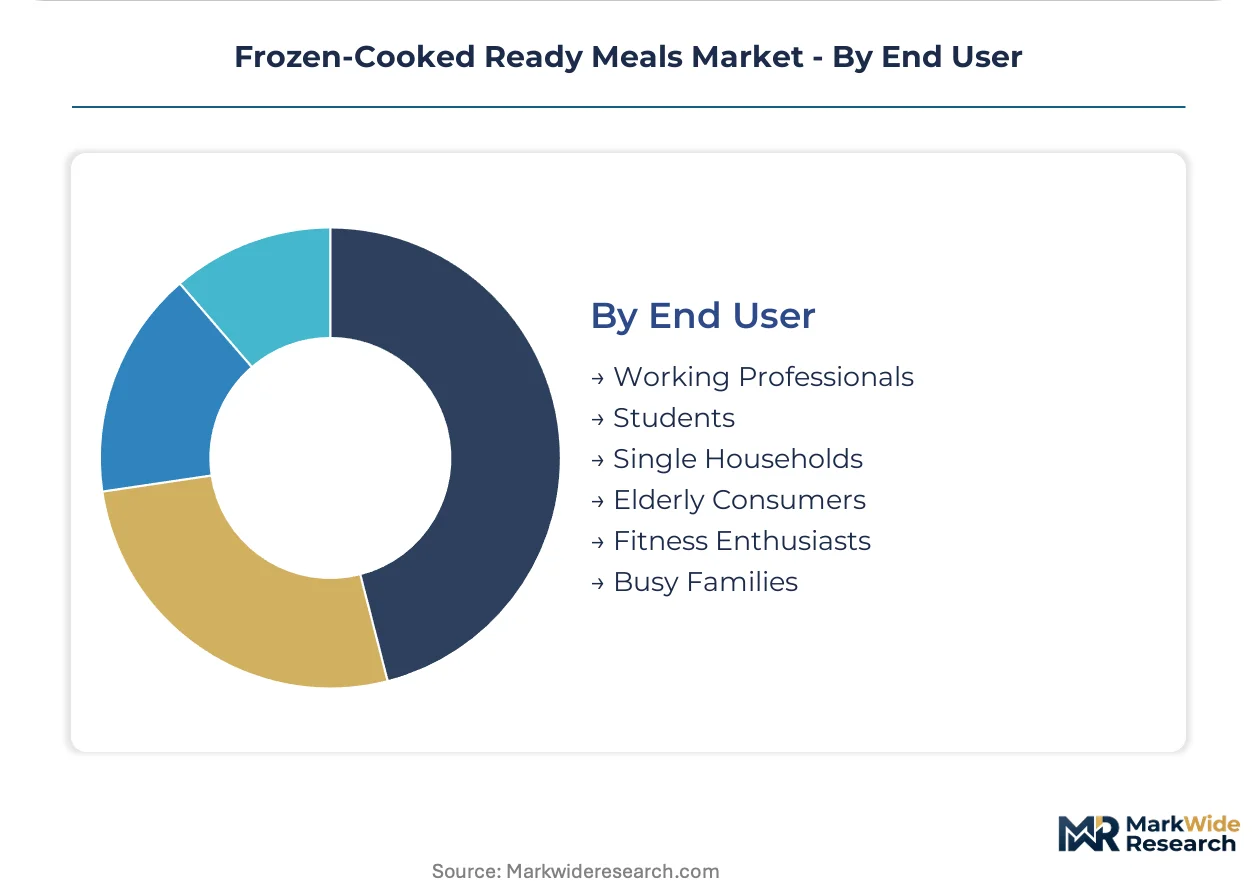
End User:
User archetypes diverge sharply in preparation equipment access, price sensitivity, and nutritional prioritization, forcing SKU proliferation that fragments production line utilization.
- Working Professionals:Time-constrained urban employees aged 25-45 purchase premium single-serve formats with sub-5-minute preparation requirements. German metropolitan areas concentrate demand for induction-tolerant susceptor film trays that deliver stovetop-quality results without oven preheating, though fresh prepared meal substitution threatens frequency among higher-income segments.
- Single Households:Solo dwellers in Berlin, Hamburg, and Frankfurt drive portion-size reduction trends and multi-pack variety configurations. This segment accepts per-unit premiums for waste minimization, expanding addressable demand for premium frozen over conventional chilled alternatives.
- Students:Price-sensitive younger consumers favor economy-tier multi-packs with basic microwave compatibility.
- Elderly Consumers:Ease-of-opening packaging and large-format nutrition labeling shape product selection.
- Fitness Enthusiasts:Macro-nutrient-specified meals with protein claims attract gym-adjacent retail placement.
- Busy Families:Multi-serve formats with child-appeal flavor profiles dominate weekend purchasing patterns.
Working professionals represent the largest addressable spend; single households are expanding most quickly as demographic trends reshape household formation patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across consumption centers. German buyers accept steep premiums for convenience, while Polish and Spanish consumers remain price-sensitive, channeling volume toward private-label economy tiers.
Germany
Urban single-person households in Berlin, Hamburg, and Frankfurt drive premium frozen meal adoption as time-pressed professionals substitute convenience for home cooking. EFSA cold-chain traceability mandates require real-time temperature logging that elevates compliant producers above regional competitors lacking sensor integration capital. The Rhine-Ruhr industrial corridor hosts blast-freezing infrastructure concentration where Nestlé and Dr. Oetker operate proprietary networks.
France
Working professionals in Paris and Lyon metropolitan areas sustain demand for induction-tolerant susceptor film trays that deliver stovetop-quality results without oven preheating. EU Green Deal extended producer responsibility timelines accelerate R&D migration toward recyclable mono-material packaging formats. Picard and Nestlé test predictive delivery models based on consumption velocity data from connected appliances in the Île-de-France region.
United Kingdom
Convenience-seeking commuters in London and Manchester favor grab-and-go formats from urban freezer aisles, though fresh prepared meal substitution threatens frequency among higher-income segments. FDA-aligned frozen food safety standards shape import compliance for North American suppliers accessing British retail channels. Nomad Foods anchors market presence through direct-store-delivery cold-chain control across Greater London grocery networks.
Japan
Metropolitan consumers in Tokyo and Osaka demonstrate strong adoption of umami-based recipe specialization that differentiates Asian-format offerings from Western-format rivals. JIS cold-chain specifications govern thermal processing standards and packaging disclosures for domestic and export markets. Ajinomoto competes via fermentation science convergence with European ingredient sourcing in the Kanto industrial belt.
United States
Busy families and working professionals across major metropolitan statistical areas sustain volume demand for multi-serve and single-serve configurations respectively. FDA frozen food safety standards mandate allergen segregation protocols that fragment capacity utilization across SKU proliferation. Conagra Brands and Tyson Foods anchor positions through direct-store-delivery cold-chain control in North American grocery, with concentration in Midwest and Southeast distribution hubs.
Frozen-Cooked Ready Meals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Integrated multinationals with proprietary blast-freezing networks capture premium shelf-stable segments, while contract manufacturers dependent on third-party logistics serve price-sensitive channels. The market structure consolidates around three strategic archetypes: frozen-food specialists with category depth, diversified food conglomerates with cross-category leverage, and protein-centric processors with upstream supply control. Dominant competitive moves include M&A for regional cold-chain asset acquisition and portfolio diversification into plant-based format expansion.
Among diversified food conglomerates, Nestlé and General Mills occupy positions exemplifying cross-category resource deployment, while Conagra Brands represents the North American-centric frozen-food specialist archetype. Ajinomoto sits within the Asia-Pacific format specialist tier, anchoring competitive positioning through recipe differentiation rather than scale-driven cost compression. Tyson Foods exemplifies the protein-integrated processor model, leveraging upstream supply control to secure input cost stability. These five entities collectively illustrate the competitive spectrum from global diversified to regional specialist to vertically integrated protein player.
| Leading Market Players |
|---|
| Nestlé |
| Conagra Brands |
| The Kraft Heinz Company |
| General Mills |
| Dr. Oetker |
| Ajinomoto |
| Tyson Foods |
| McCain Foods |
| Nomad Foods |
| Others |
Supply & Pricing Matrix
Seventy-two-hour blast-freezing lead times for premium tray formats concentrate pricing power with integrated producers operating proprietary cold-chain networks in Germany and France, while contract manufacturers dependent on third-party logistics absorb margin compression from energy price volatility and slotting fee inflation.
Pricing Analysis
After-sales subscription revenue from direct-to-consumer replenishment models drives lifetime value capture beyond transactional retail sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by susceptor film integration and cold-chain certification grade. Pricing pressure stems from fresh prepared meal substitution among higher-income working professionals in Paris and London. Students and price-sensitive Eastern European consumers exhibit highest price sensitivity, while single-person households in German metropolitan areas accept per-unit premiums for waste-minimizing portion formats.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement for plant-based proteins and mycelium-based textures, contrasting with just-in-time dairy analog sourcing from fermentation facilities. Manufacturing concentration rests on Germany, France, and Poland for blast-freezing infrastructure and tray pack production. Key inputs include natural gas for cryogenic operations, laminated packaging films, and extruded plant protein isolates. Single-source vulnerability in European natural gas supply creates margin exposure during wholesale rate spikes. Distribution feeds from direct-store-delivery cold-chain control in retail grocery and algorithmic replenishment through subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and French supermarket chains demanding recyclability documentation and promotional slotting fee concessions, fragmenting margin capture for secondary brands unable to absorb compliance costs.
For Market Incumbents: Shield proprietary blast-freezing network advantages by accelerating mono-material tray R&D ahead of EU Green Deal extended producer responsibility deadlines. Lock in cold-chain engineer talent through acquisition of legacy equipment manufacturers in the Rhine-Ruhr corridor. Defend against fresh prepared meal substitution by expanding induction-tolerant susceptor film SKUs that compress preparation friction for working professionals. For New Entrants and Emerging Players: Differentiate on umami-based recipe specialization converging Japanese fermentation science with European ingredient sourcing to penetrate underexploited Nordic markets. Target white-space in vegan direct-to-consumer subscription channels where algorithmic meal planning displaces impulse freezer-aisle selection. Pursue go-to-market partnerships with connected appliance manufacturers for predictive delivery based on consumption velocity data. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest frozen-cooked ready meal portfolios lacking vertical integration into blast-freezing infrastructure. Long-term viability hinges on capital allocation to sensor-integrated cold-chain compliance and recyclable packaging format transitions. Watch for inflection when EFSA mandates real-time temperature logging across all distribution tiers, elevating compliant producers above fragmented regional competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Blast-Freezing Network Expansion | Proprietary cryogenic infrastructure in Germany locks in premium shelf-stable segment access against contract manufacturer competition. |
| Mono-Material Packaging Transition | Recyclable polypropylene tray migration ahead of Rewe and Edeka documentation requirements secures promotional slotting eligibility. |
| Direct-to-Consumer Channel Buildout | Subscription replenishment models in France bypass supermarket slotting fees and capture full markup control from working professionals. |
| Umami Recipe Specialization | Fermentation science convergence with European sourcing differentiates Asian-format offerings in underpenetrated Nordic retail channels. |
| Cold-Chain Engineer Acquisition | Talent concentration among legacy equipment manufacturers constrains in-house capability building without targeted hiring or M&A. |
Research Methodology
A spread of perspectives from frozen food R&D directors, supermarket category buyers at Edeka and Carrefour, cold-chain logistics operators, and EFSA regulatory affairs specialists converged on the working assumptions driving volume and value estimates. Primary interview insights combined with secondary validation from customs trade records, Nielsen retail audit data, SEC filings of listed food conglomerates, and EU extended producer responsibility regulatory filings. Bottom-up SKU-level demand modeling and top-down category expenditure analysis provided triangulation across data sources.
Segmentation dimensions modeled include product type across vegetarian, vegan, and non-vegetarian formats; packaging configuration from tray packs to vacuum films; distribution channel spanning supermarket, online retail, and convenience store; and end-user archetype from working professionals to single households. CAGRs were derived from regression analysis of historical consumption velocity against demographic and regulatory drivers across the projection horizon. Industry-specific forecast inputs incorporated EFSA cold-chain traceability compliance timelines and EU Green Deal packaging mandate implementation schedules.
Material uncertainties — abrupt natural gas price spikes, accelerated fresh prepared meal substitution rates, and unpredictable EFSA labeling requirement revisions — sit outside the modeled envelope. Forecasts reflect assumptions about cold-chain infrastructure investment continuity and supermarket slotting fee inflation trajectories. Revision becomes warranted when fresh prepared meal substitution crosses threshold penetration among premium frozen meal buyer segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Individual Quick Frozen Cheese Market