
 Deli Meat Market | 2026-2036
Deli Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Deli Meat Market Analysis
Asset-light co-manufacturing and private-label leasing arrangements is fragmenting competitive control across the deli meat value chain. Tyson Foods Inc. sustains broad protein throughput across turkey, pork, and beef deli lines. WH Group Limited anchors global capacity through its vertically integrated pork processing network. Hormel Foods Corp. specializes in branded refrigerated deli trays and natural-ingredient positioning for premium retail channels.
Deli meat comprises cured, cooked, or smoked animal proteins—typically pork, turkey, beef, or chicken—sliced to standardized thicknesses between 0.5 mm and 3.0 mm for immediate consumption without further preparation. These products serve commercial foodservice, retail prepared-meal sections, and direct consumer purchase through chilled distribution chains requiring maintenance at 0°C to 4°C. Turkey and salami segments command the largest volume positions, with organic and premium quality grades capturing disproportionate margin pools as retailers allocate expanded shelf space to clean-label positioning. Vacuum-sealed packaging dominates institutional procurement for extended shelf-life requirements, while resealable bags and pre-sliced formats compete for household repeat-purchase frequency in supermarket channels.
The USDA Food Safety and Inspection Service enforces pathogen-reduction and labeling standards that dictate facility certification requirements for interstate commerce, while the FDA oversees sodium and nitrite additive thresholds under nutrition-labeling regulations. EFSA and national regulators across Europe enforce stricter nitrosamine limits and clean-label declarations that reshape formulation R&D priorities for export-oriented processors. Stakeholders must monitor evolving front-of-package warning systems and sodium cap proposals that threaten conventional processed-meat positioning in key retail markets.
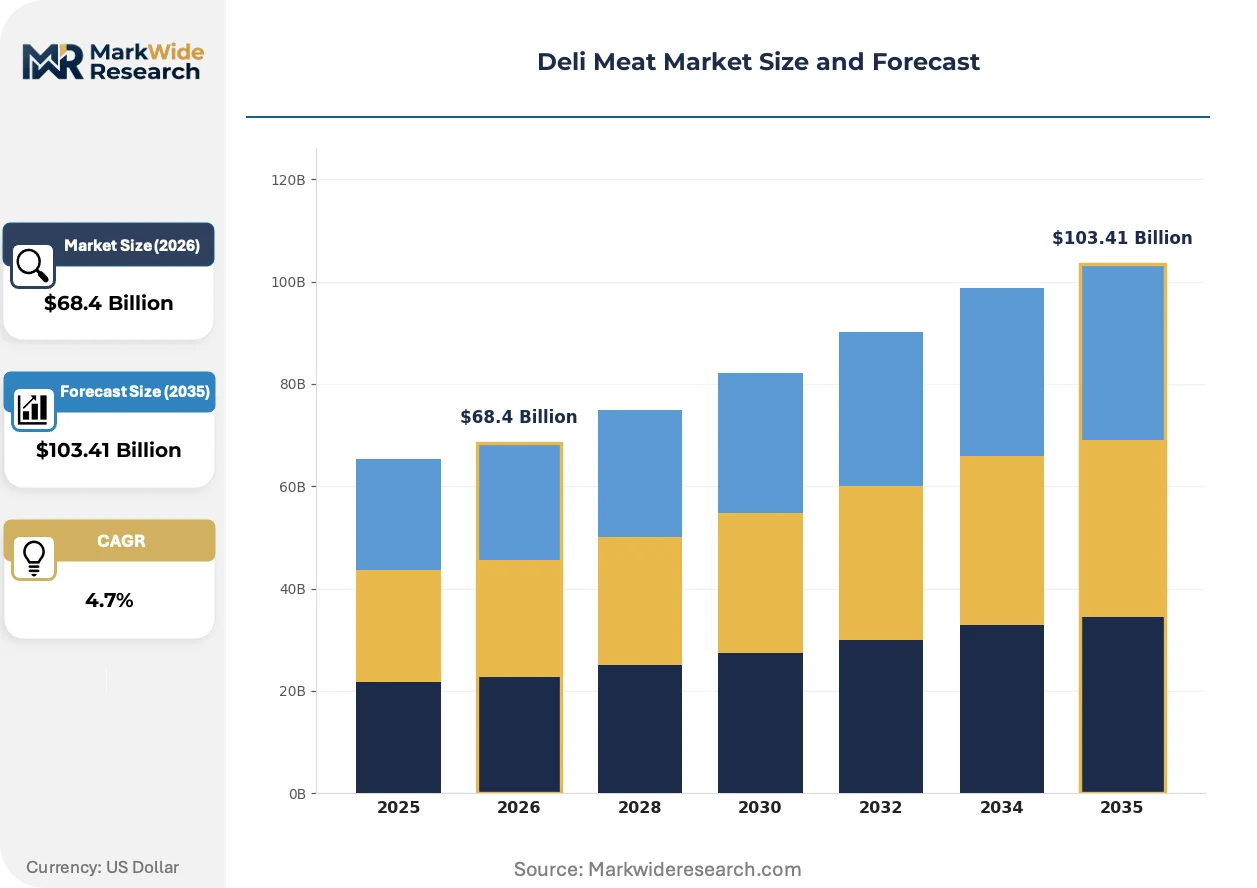
Market Dynamics
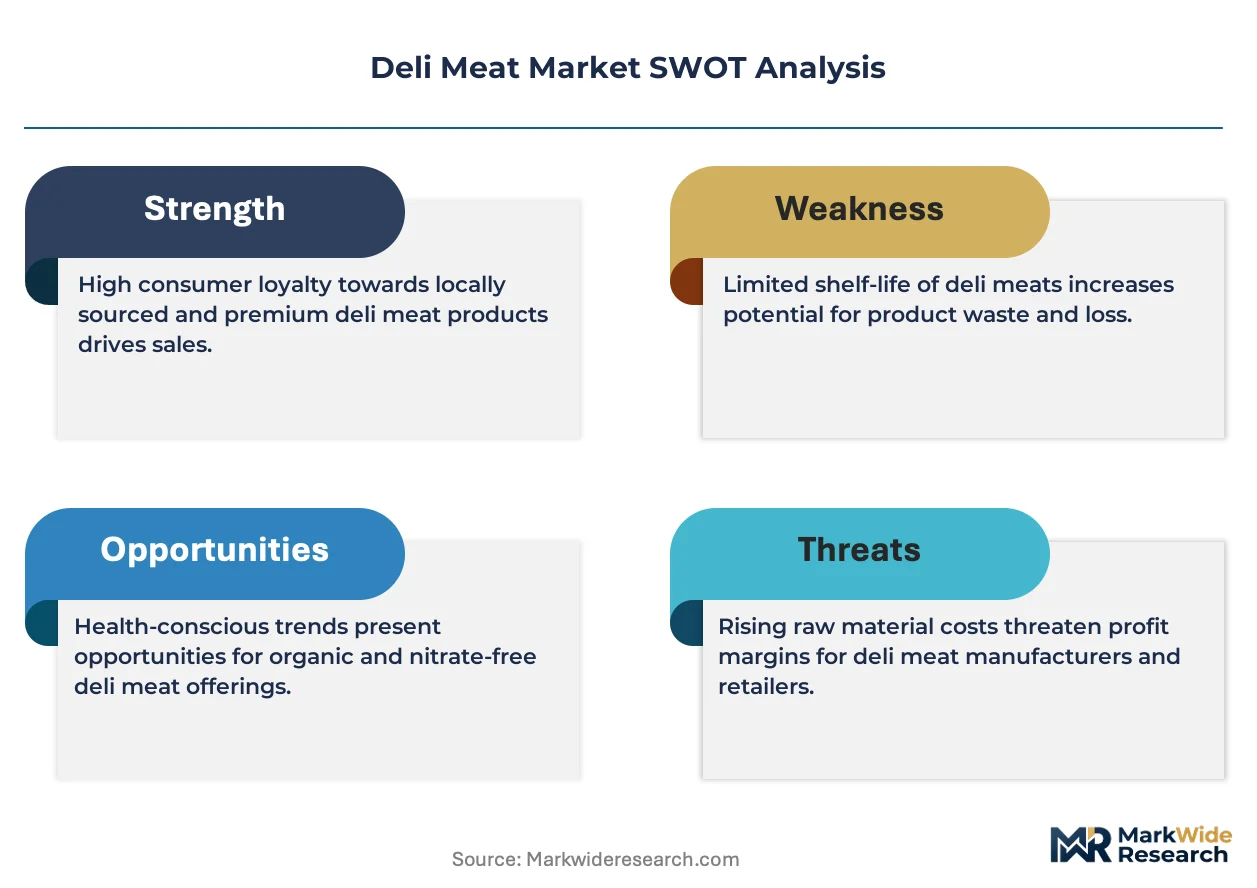
Sodium-reduction mandates from the FDA and USDA are forcing processors to reformulate cured meat recipes, compressing formulation cycles and accelerating clean-label R&D spend across North American and European manufacturing networks.
Growth Catalysts
- Retail Foodservice Expansion:Supermarket operators are expanding prepared protein offerings in grab-and-go formats, creating dedicated chilled deli sections that absorb higher-margin sliced products. This channel shift lifts household penetration rates for pre-portioned deli meats.
- EFSA Nitrosamine Limits:Stricter European nitrosamine thresholds are accelerating natural-curing alternatives using celery powder and fermentation-derived nitrites, opening premium positioning for export-oriented processors.
- German Charcuterie Demand:Germany's sustained per-capita consumption of sliced deli products anchors volume throughput for specialized slicing and packaging equipment, supporting capital investment in high-speed portioning lines.
Market Restraints
- Feed Input Volatility:Corn and soybean meal price swings directly compress margins for turkey and pork processors, with protein conversion ratios amplifying cost pass-through challenges to retail channels.
- Cold Chain Concentration:Refrigerated distribution capacity concentrates among third-party logistics providers in the Midwest and Lower Saxony, creating bottleneck risks during peak summer demand periods.
- Plant-Based Substitution:Pea-protein and mycoprotein deli slices are capturing shelf space in urban retail clusters, displacing conventional animal protein volumes in premium positioning tiers.
Strategic Opportunities
- India Cold-Chain Buildout:FSSAI modernization of chilled distribution standards creates first-mover positioning for vacuum-sealed export formats targeting organized retail in Mumbai and Bangalore.
- Dual-Label Convergence:USDA Organic certification combined with non-GMO verification is hybridizing into single-package claims, reducing label complexity and unlocking co-manufacturing partnerships.
- Direct-to-Institutional Channels:Healthcare and education foodservice operators are bypassing broadline distributors to contract directly with processors for clean-label deli programs, compressing margin extraction by intermediaries.
Industry Challenges
- Clean-Label Talent Scarcity:Food scientists skilled in natural preservation and fermentation-derived curing agents command premium compensation, constraining R&D throughput at mid-cap processors.
- Multi-Jurisdiction Certification:Simultaneous USDA, EFSA, and FSSAI compliance requirements extend product launch timelines by 8-14 months for export-oriented formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deli Meat Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turkey, Ham, Salami, Roast Beef Packaging Type: Vacuum-Sealed, Resealable Bags, Pre-Sliced, Bulk Distribution Channel: Supermarkets, Delicatessens, Online Retailers, Convenience Stores Quality Grade: Premium, Standard, Organic, Processed |
| Companies Covered | WH Group Limited, Jennie-O Turkey, Tyson Foods Inc., Tofurky, True Story Foods, JBS S.A., The Kraft Heinz Company, Carnegie Deli, Hormel Foods Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deli Meat Market Emerging Trajectories
High-pressure processing and natural fermentation are displacing conventional thermal pasteurization, enabling extended shelf-life without synthetic preservatives while reshaping capital allocation across manufacturing footprints.
High-pressure processing technology applies isostatic pressure between 400 and 600 MPa to inactivate pathogens without thermal degradation. Retailers in Germany and the Netherlands are adopting HPP-treated deli turkey for private-label lines at accelerating rates. This technology is hybridizing clean-label positioning with institutional shelf-life requirements, compressing the trade-off between ingredient transparency and distribution reach.
REACH regulation amendments on nitrosamine precursor labeling are compelling European processors to disclose curing-agent origins on front-of-package panels. Industrial consequence includes reformulation away from conventional sodium nitrite toward cultured celery juice concentrates. Premium retail channels in France and Italy are responding fastest, with clean-cured salami and prosciutto lines absorbing 15-20% price premiums.
Hospital and corporate cafeteria operators are consolidating protein procurement through group purchasing organizations, unbundling deli meat from broadline distribution contracts. This purchasing concentration is displacing traditional foodservice distributor margins and forcing processors to build direct sales capabilities. The shift is most visible in US healthcare systems and UK National Health Service catering frameworks.
Deli Meat Market Segmentation
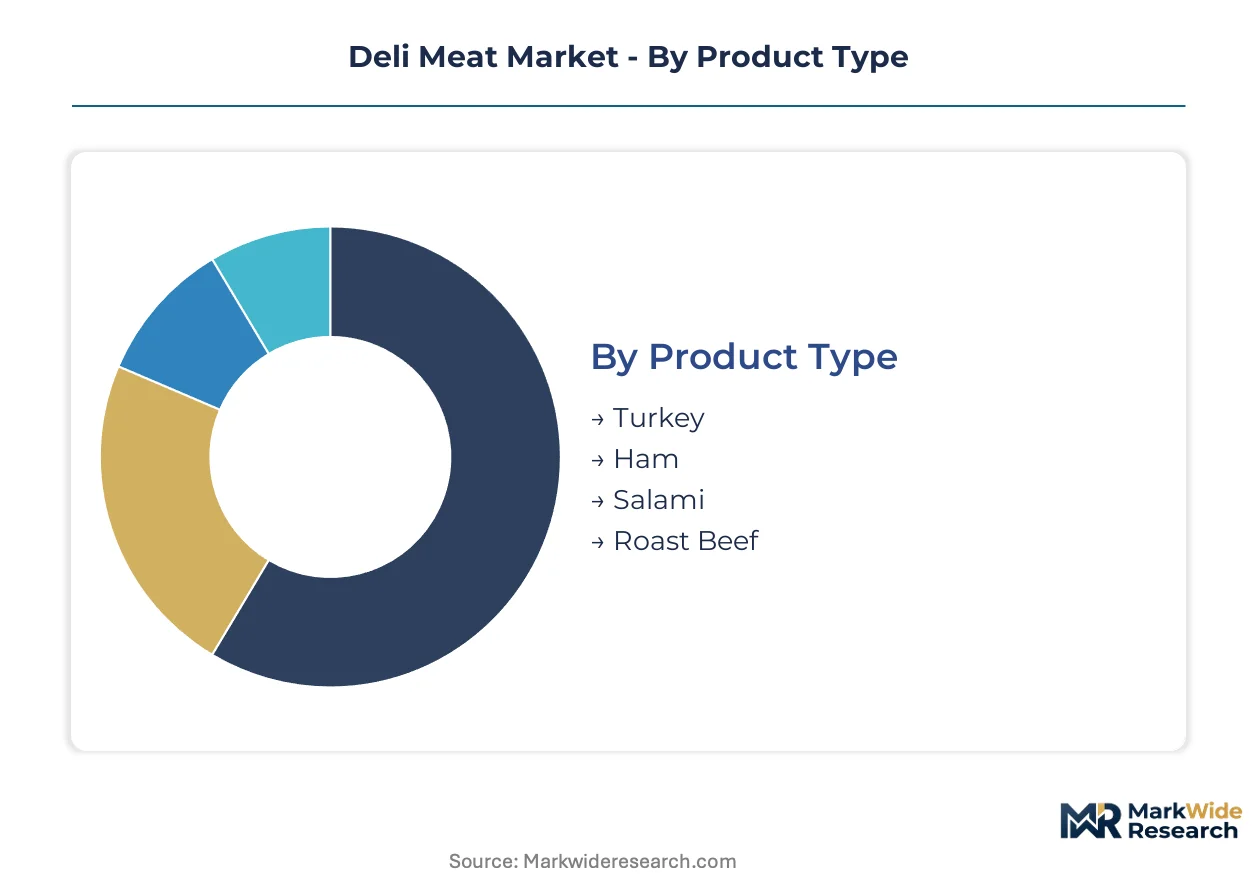
Deli meat segmentation reflects divergent consumption occasions across immediate household consumption, institutional procurement, and foodservice preparation. Product formulations, packaging formats, and channel access tiers map directly to price sensitivity, shelf-life requirements, and clean-label preferences that reshape processor R&D priorities.
Product Type:
Product type segmentation traces protein source differentiation across poultry, pork, and beef curing traditions, with each species carrying distinct cost structures, religious dietary constraints, and regional consumption anchors.
- Turkey:Lean white-muscle protein processed through brine injection and thermal pasteurization to achieve moisture retention without excessive sodium load. Demand concentrates in US healthcare and education foodservice channels where USDA sodium-reduction guidelines drive procurement specifications toward lower-sodium poultry options.
- Salami:Fermented pork or beef sausage undergoing controlled bacterial culture development and drying to achieve shelf-stable acidity without refrigeration dependency. Italian and German retail channels sustain premium positioning for regional Protected Designation of Origin varieties, with EFSA nitrosamine thresholds accelerating natural-curing formulation shifts.
- Ham:Cured pork leg processed through wet or dry curing methods, with water-binding regulations dictating protein-content minimums in US interstate commerce.
- Roast Beef:Whole-muscle beef cooked to precise internal temperatures and sliced for sandwich applications, commanding price premiums in UK and US premium retail tiers.
The dominant share belongs to Turkey, while Salami is closing the gap fastest.
Packaging Type:
Packaging decisions balance shelf-life extension against household convenience and sustainability positioning, with format selection directly determining distribution radius and retail channel compatibility.
- Vacuum-Sealed:Barrier-film evacuation eliminating oxygen contact to suppress aerobic spoilage organisms and oxidative rancidity, extending refrigerated shelf life to 60-90 days. Institutional procurement in Germany and the Netherlands mandates this format for centralized kitchen delivery, with high-pressure processing hybridization enabling clean-label claims without synthetic preservatives.
- Pre-Sliced:Automated portioning to standardized thicknesses eliminating household preparation friction and enabling precise portion control for calorie-conscious consumers. US supermarket prepared-meal sections and UK meal-kit providers drive volume for this format, with resealable overwrap addressing repeat-use convenience.
- Resealable Bags:Zip-seal or adhesive-strip closures permitting partial consumption without compromising remaining product integrity, capturing household repeat-purchase frequency.
- Bulk:Unsliced whole-muscle or chub formats targeting foodservice operators with in-house slicing capacity and lower per-unit procurement costs.
Vacuum-Sealed commands institutional commitment, though Pre-Sliced is expanding most quickly into household penetration.
Distribution Channel:
Channel segmentation tracks cold-chain infrastructure maturity and consumer mission type, with each route imposing distinct margin structures and brand-building requirements.
- Supermarkets:Full-service retail with dedicated chilled deli counters and grab-and-go prepared sections, absorbing higher-margin branded and private-label sliced products. German retailers Edeka and Rewe anchor volume throughput for specialized slicing equipment, while US operators expand meal-solution adjacencies.
- Online Retailers:Direct-to-consumer fulfillment requiring insulated packaging and time-definite delivery, capturing urban household convenience demand in UK and French metropolitan clusters.
- Delicatessens:Service-oriented specialty retail emphasizing artisanal sourcing and custom portioning, sustaining premium price realization in Italian and Spanish traditional retail.
- Convenience Stores:Limited assortment focused on immediate consumption occasions, with refrigerated sandwich and snack applications driving turnover velocity.
Supermarkets retain the volume anchor position, while Online Retailers are gaining share fastest.
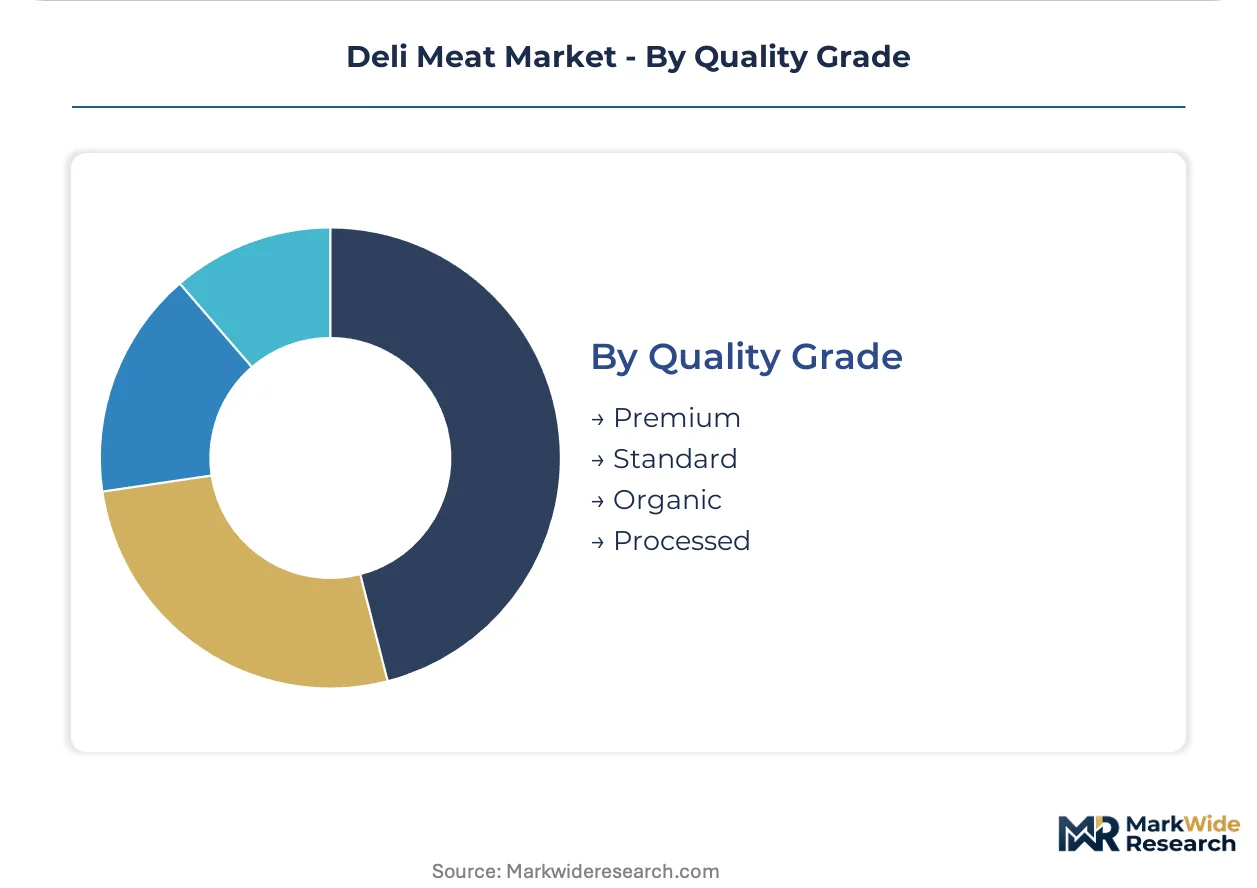
Quality Grade:
Quality tiering reflects certification complexity and ingredient transparency, with grade selection determining margin pools and manufacturing facility qualification requirements.
- Premium:Heritage breed sourcing, extended aging protocols, and minimal processing with no artificial additives, commanding 15-20% price premiums in French and Italian retail. EFSA clean-label declarations and REACH nitrosamine precursor disclosures reinforce positioning for export-oriented European processors.
- Organic:USDA or EU organic certification requiring feed and husbandry compliance, with dual-label convergence toward non-GMO verification simplifying package claims. US natural-foods retailers and German Bio-Supermärkte allocate expanded shelf space to this tier.
- Standard:Conventionally processed products meeting baseline regulatory requirements without specialty certification, serving price-sensitive household volume.
- Processed:Formulated products with extended ingredient lists including binders, extenders, and flavor enhancers, concentrated in mass-market value tiers.
Premium holds the margin leadership position, while Organic is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented processors in Germany and the United States dominate international deli meat trade flows, while import-dependent markets in Asia-Pacific and the Middle East absorb premium vacuum-sealed formats. Cold-chain infrastructure gaps in emerging economies constrain distribution radius for temperature-sensitive sliced products.
Germany
Charcuterie traditions sustain per-capita consumption levels unmatched elsewhere, with EFSA nitrosamine thresholds accelerating natural-curing formulation shifts across Bavarian and Lower Saxon processing clusters. Berlin-Brandenburg anchors specialized slicing equipment manufacturing, supporting capital deployment in high-speed portioning lines for export markets.
United States
USDA sodium-reduction guidelines drive healthcare and education procurement toward lower-sodium turkey options, while FDA oversight of nitrite additive thresholds compresses formulation cycles. Midwest cold-chain concentration among third-party logistics providers creates bottleneck risks during peak summer demand periods.
China
Rising urban household income is expanding chilled deli section footprints in organized retail across Shanghai and Beijing, though domestic pork price volatility constrains margin stability. SAMR enforcement of labeling standards extends product launch timelines for imported formulations seeking multi-channel distribution.
India
FSSAI modernization of chilled distribution standards creates first-mover positioning for vacuum-sealed export formats targeting organized retail in Mumbai and Bangalore. Poultry-based deli products bypass religious dietary constraints that limit pork penetration, with Maharashtra and Karnataka hosting initial cold-chain buildout.
United Kingdom
NHS catering frameworks are consolidating protein procurement through group purchasing organizations, displacing traditional foodservice distributor margins. Roast beef deli lines command price premiums in premium retail tiers, with London-Southeast retail clusters allocating expanded shelf space to clean-label positioning.
Deli Meat Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated protein processors and fragmenting across specialized co-manufacturers serving private-label leasing arrangements. Strategic archetypes span scale-driven broadline protein houses, premium natural-curing specialists, and plant-based alternative developers. Dominant competitive moves include backward integration into captive livestock supply and technology licensing for high-pressure processing equipment.
Among US-based protein conglomerates, Tyson Foods Inc. and Hormel Foods Corp. exemplify scale-driven throughput across multiple species lines, while WH Group Limited anchors global pork processing capacity through its vertically integrated network. These three occupy positions spanning conventional mass-market supply and premium natural-ingredient positioning for differentiated retail channels.
| Leading Market Players |
|---|
| WH Group Limited |
| Jennie-O Turkey |
| Tyson Foods Inc. |
| Tofurky |
| True Story Foods |
| JBS S.A. |
| The Kraft Heinz Company |
| Carnegie Deli |
| Hormel Foods Corp. |
| Others |
Supply Flow & Price Mechanics
Feed input volatility in corn and soybean meal markets determines both the spread between premium organic and standard conventional tiers and the geographic shape of cold-chain infrastructure investment across North America and Europe. This commodity risk vector compresses processor margins unevenly, forcing cost pass-through differentiation that stratifies pricing while concentrating supply chain control among vertically integrated protein houses with captive feed sourcing.
Pricing Analysis
Foodservice procurement directors anchor contract-based long-term offtake structures for institutional volumes, while retail channels operate on spot-adjacent transactional pricing with quarterly adjustments. Price differentiation rests on quality grade certification and volume scale, with USDA Organic and EFSA clean-label tiers commanding substantial premiums over standard formulations. Pricing pressure stems from plant-based substitution in urban retail clusters, eroding share in premium positioning tiers. Mass-market value buyers exhibit highest price sensitivity, whereas healthcare and education foodservice operators prioritize sodium-reduction compliance over unit cost.
Supply Chain Analysis
Export-control regimes on high-pressure processing equipment limit technology transfer to emerging markets, constraining clean-label production capacity expansion outside Germany, the United States, and the Netherlands. Raw material flows draw from Midwest grain belts, Brazilian soybean complexes, and Lower Saxon livestock clusters. Single-source vulnerability concentrates in third-party refrigerated logistics providers operating peak summer distribution. Downstream distribution runs through supermarket prepared-meal sections, direct-to-institutional healthcare contracts, and broadline foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment leasing and maintenance contracts for high-speed slicing and portioning lines expand faster than hardware sales, creating recurring revenue layers that outpace capital equipment growth across German and US processing clusters.
For Market Incumbents: Entrench control through backward integration into captive turkey and pork supply chains, insulating margin structures from feed volatility. Accelerate certification investment for simultaneous USDA, EFSA, and FSSAI compliance to compress export launch timelines and preempt mid-cap competitors lacking regulatory bandwidth. For New Entrants and Emerging Players: Pursue white-space positioning in India's organized retail cold-chain buildout, where FSSAI modernization creates first-mover vacuum-sealed export opportunities. Target Maharashtra and Karnataka with poultry-based formulations bypassing religious dietary constraints, deploying direct-to-institutional sales models that circumvent established distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors natural-curing technology specialists with proven celery powder and fermentation-derived nitrite capabilities. Long-term viability centers on clean-label R&D assets and high-pressure processing equipment licensing portfolios. Watch EFSA nitrosamine threshold enforcement as the signal indicating acceleration or deceleration of premium tier absorption.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Equipment Licensing | Enables clean-label shelf-life extension without synthetic preservatives, unlocking institutional procurement in Germany and the Netherlands. |
| Backward Integration into Captive Livestock Supply | Insulates processors from corn and soybean meal volatility while securing protein conversion ratio control. |
| Dual-Label Certification Convergence | Combines USDA Organic with non-GMO verification to reduce package complexity and accelerate co-manufacturing partnerships. |
| Direct-to-Institutional Channel Development | Bypasses broadline distributor margins by contracting with NHS and US healthcare system GPOs for clean-label deli programs. |
| Natural-Curing R&D Capacity Expansion | Addresses talent scarcity in fermentation-derived curing agents while meeting EFSA nitrosamine limits for European export positioning. |
Methodological Framework
A standing panel of protein procurement managers at healthcare GPOs, supermarket category buyers, cold-chain logistics operators, and natural-curing R&D scientists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from USDA FSIS enforcement records, EFSA scientific opinions on nitrosamine thresholds, FSSAI chilled distribution standards, and customs trade data on vacuum-sealed export flows. Bottom-up volume modeling across turkey, salami, ham, and roast beef segments triangulated with top-down market sizing from processor throughput disclosures.
Scenario bracketing around feed input volatility, regulatory enforcement intensity, and plant-based substitution rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include protein source, packaging format, distribution channel, and quality grade tier. CAGRs were derived from spline interpolation of annual volume estimates, with forecast inputs incorporating cold-chain infrastructure buildout timelines in India and sodium-reduction mandate compliance trajectories in North America.
Sensitivities concentrate around corn and soybean price shocks, EFSA nitrosamine limit amendments, and FSSAI enforcement pace in Indian organized retail. Forecasts reflect documented assumptions on regulatory stability and protein substitution elasticities. Material shifts in FDA sodium cap proposals or breakthroughs in mycoprotein texture replication would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Dehydrated Potato Market