
 Kidney/Renal Function Test Market | 2026-2036
Kidney/Renal Function Test Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney/Renal Function Test Market Intelligence
The integration of biosensors and microfluidics into point-of-care (POC) devices is reshaping how renal function diagnostics are delivered. Siemens Healthineers leverages its extensive diagnostic portfolio to offer integrated solutions for nephrology departments. Abbott competes on the strength of its i-STAT handheld platform, providing rapid results in critical care settings. F. Hoffmann-La Roche Ltd focuses on high-throughput laboratory systems and a broad menu of immunoassays for large diagnostic centers.
Kidney function tests are in vitro diagnostic procedures assessing renal health by measuring biomarkers like creatinine and blood urea nitrogen. Their purpose is to calculate metrics such as the estimated glomerular filtration rate (eGFR) for early detection and monitoring of kidney disease. Serum creatinine and blood urea nitrogen tests remain foundational, while comprehensive electrolyte panels see greater use for nuanced patient management. Diagnostic laboratories constitute the largest end-user segment, but specialized centers and home care settings represent the fastest-growing channels.
Regulatory frameworks from bodies like the US FDA and the European Medicines Agency (EMA) mandate stringent validation for test accuracy and clinical utility. In China, the NMPA's approval processes and GB standards govern market access for both domestic and imported diagnostic devices. A key strategic decision for manufacturers will be aligning product development with shifting reimbursement policies for point-of-care versus traditional laboratory-based assays.
Market Dynamics
The central force shaping the kidney function test market is the decentralization of diagnostics. This shift is driven by the convergence of biosensor technology enabling point-of-care devices and the clinical imperative for continuous monitoring of chronic kidney disease.
Growth Catalysts
- Technology Miniaturization:The development of biosensor-based and microfluidic point-of-care devices enables rapid testing outside traditional laboratories, accelerating adoption within home care and specialized clinic settings for chronic disease management.
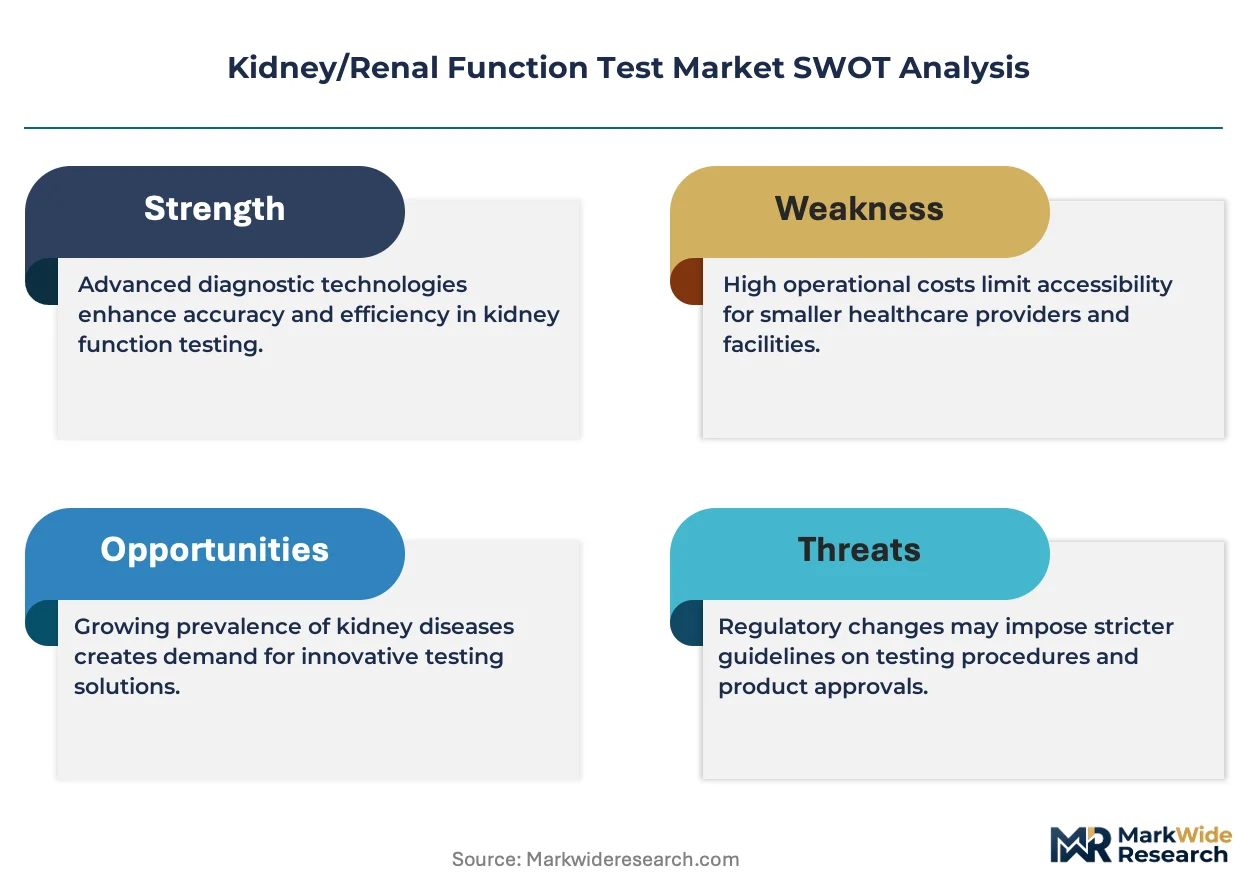
- Demographic Pressures:High prevalence of diabetes and hypertension in countries with aging populations, particularly Germany and Japan, creates a sustained and concentrated demand for routine renal function screening and monitoring.
- Reimbursement Policy Evolution:Shifting reimbursement policies that increasingly favor preventative care and remote patient monitoring are creating financial incentives for healthcare providers to adopt more frequent, point-of-care renal testing protocols.
Market Restraints
- Reimbursement Gaps:Disparities in reimbursement coverage between established central laboratory tests and newer point-of-care assays can limit the economic viability for clinics and home care agencies to adopt the latter.
- Clinical Validation Hurdles:Stringent clinical validation protocols mandated by regulatory bodies like the US FDA and under the EU's MDR framework create high-cost, lengthy development cycles that can act as barriers to market entry.
- Substitution by Integrated Panels:The inclusion of creatinine and BUN tests within broad, low-cost chemistry panels in large laboratories can limit the demand for standalone renal function tests in hospital-wide screening contexts.
Strategic Opportunities
- Digital Health Integration:Combining point-of-care renal test devices with telehealth platforms and mobile health applications offers an opportunity to create integrated remote monitoring ecosystems for chronic kidney disease patients.
- Novel Biomarker Development:There is a significant opportunity to develop and commercialize tests for emerging biomarkers beyond creatinine, such as cystatin C, to provide more accurate eGFR calculations for specific patient populations.
- Expansion in Emerging Markets:Underpenetrated markets in Southeast Asia and Latin America, where healthcare infrastructure is expanding and awareness of chronic kidney disease is rising, represent a key geographic growth opportunity.
Industry Challenges
- Data Interoperability:A primary operational challenge is ensuring seamless integration of data from diverse point-of-care testing devices into existing hospital electronic health record (EHR) and laboratory information systems (LIMS).
- Quality Control in Decentralized Settings:Maintaining analytical quality and consistency for tests performed by non-laboratory personnel in clinics or home settings presents a significant training and logistical challenge for manufacturers and providers.
- Standardization of eGFR:A lack of universal standardization for estimated glomerular filtration rate (eGFR) calculation formulas across different diagnostic platforms can lead to clinical discrepancies and complicate longitudinal patient tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney/Renal Function Test Market |
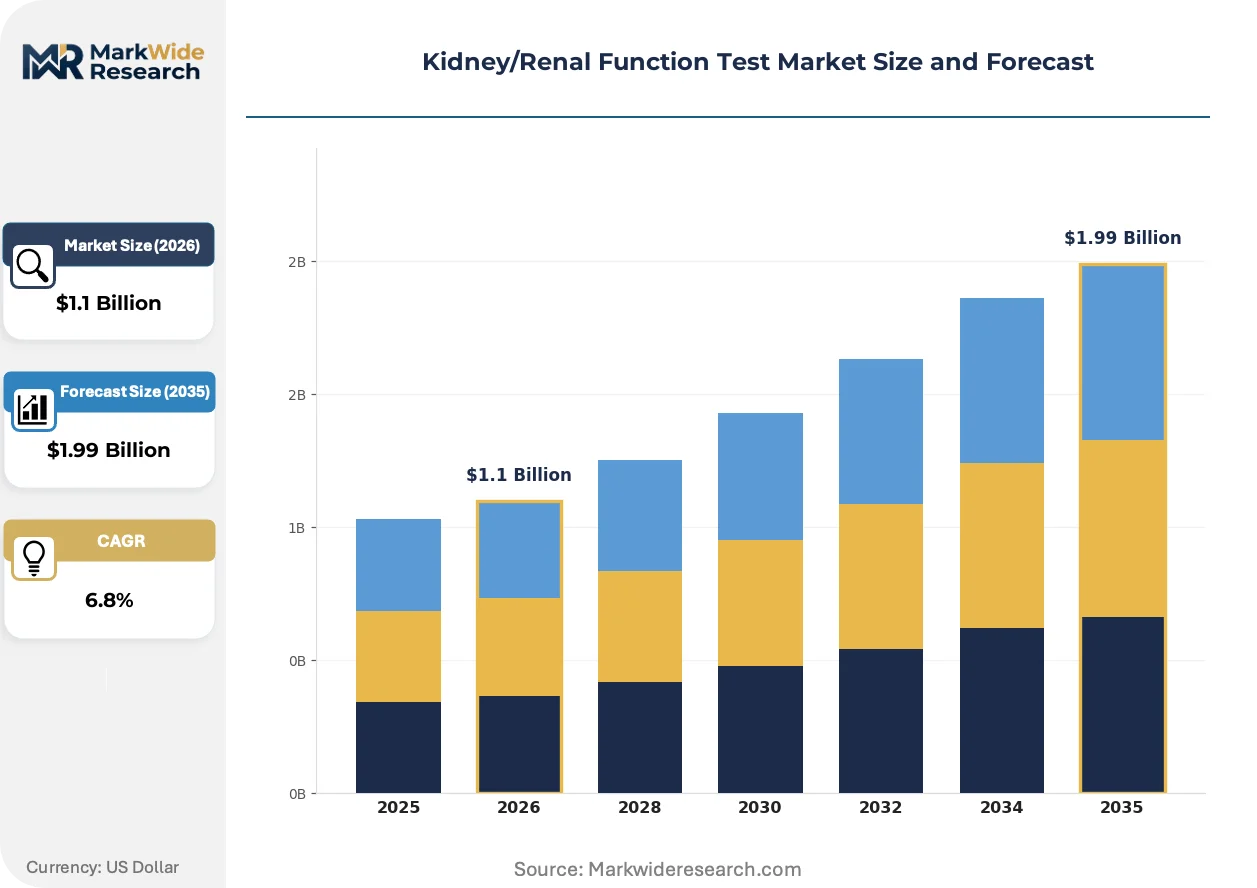
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serum Creatinine, Blood Urea Nitrogen, Glomerular Filtration Rate, Urinalysis, Electrolyte Panel Technology: Enzymatic Assays, Colorimetric Methods, Immunoassays, Biosensors, Chromatography Techniques End User: Diagnostic Laboratories, Pathology Clinics, Specialized Centers, Home Care Providers, Research Institutions Application: Chronic Kidney Disease Monitoring, Acute Renal Failure Detection, Transplant Evaluation, Drug Toxicity Screening, Hypertension Management |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott, Siemens Healthineers, Danaher, Sysmex Corporation, Beckman Coulter, Bio-Rad Laboratories, Nova Biomedical, Quest Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney/Renal Function Test Market Strategic Shifts & Innovations
A fundamental transition toward decentralized testing is redefining the delivery of renal diagnostics. This move from centralized laboratories to patient-proximate settings is driven by technological advancements and evolving clinical care models for chronic disease management.
Biosensor technology, which uses biological components to detect specific chemical substances, is the core product innovation. Home care agencies and specialized nephrology clinics are adopting these portable devices to enable real-time patient monitoring. The entire diagnostic workflow for chronic kidney disease is migrating from reliance on batch processing in central labs to continuous, data-driven management via point-of-care platforms.
Regulatory frameworks are adapting to these new technologies, with a heightened focus on clinical evidence. The European Union's In Vitro Diagnostic Regulation (IVDR) mandates more rigorous performance data and post-market surveillance for all devices. This directly impacts manufacturers of point-of-care renal tests, who must now generate extensive clinical utility data to secure and maintain market access in Europe.
A clear behavioral shift is underway as healthcare providers increasingly prioritize rapid turnaround time for actionable data over the lowest per-test cost. This disrupts the traditional procurement model where large, centralized labs held purchasing power, empowering clinical departments like critical care to influence technology acquisition. This change is most prominent in integrated health systems in the United States and Germany, where value-based care incentivizes timely intervention.
Kidney/Renal Function Test Market Segmentation
Segmentation provides a granular view of the Kidney/Renal Function Test Market, revealing distinct demand patterns and technological preferences across different use cases and operational environments. Understanding these segments is crucial for manufacturers to tailor product development and market entry strategies effectively.
Test Type:
The spectrum of kidney function tests spans foundational screening to comprehensive metabolic assessment.
- Serum Creatinine:Measures a waste product from muscle metabolism, primarily used to estimate glomerular filtration rate (eGFR) for kidney function assessment. Demand concentrates in primary care settings for routine screening and chronic kidney disease management.
- Blood Urea Nitrogen:Quantifies nitrogen in urea, a metabolic waste product, indicating kidney and liver function. Its demand is high in emergency departments for acute renal failure detection and in critical care for patient monitoring.
- Glomerular Filtration Rate:Calculates the rate at which kidneys filter blood, providing a key indicator of kidney health.
- Urinalysis:Involves physical, chemical, and microscopic examination of urine to detect various kidney disorders.
- Electrolyte Panel:Assesses levels of essential minerals like sodium and potassium, crucial for fluid balance and kidney function.
The dominant share belongs to Serum Creatinine, while Electrolyte Panel is closing the gap fastest.
Technology:
Technology choices in renal diagnostics dictate precision, throughput, and point-of-care capability for various clinical needs.
- Biosensors:Utilize biological recognition elements integrated with transducers to detect biomarkers rapidly at the point of care. Home care providers and specialized clinics increasingly adopt these devices for real-time chronic kidney disease monitoring.
- Immunoassays:Employ antibody-antigen reactions to detect specific kidney biomarkers with high sensitivity and specificity. Large diagnostic centers leverage these for high-throughput screening and complex biomarker analysis.
- Enzymatic Assays:Measure specific enzyme activity or substrate concentration related to kidney function.
- Colorimetric Methods:Rely on color changes in chemical reactions to quantify kidney function markers like creatinine.
- Chromatography Techniques:Separate and identify components in complex samples, offering highly accurate quantification for research and specialized diagnostics.
Traditional Colorimetric Methods maintain a significant installed base, but Biosensors are expanding most quickly.
End User:
End-user segments reflect diverse operational scales and patient care models, from centralized analysis to decentralized monitoring.
- Diagnostic Laboratories:Centralized facilities performing high volumes of kidney function tests using automated systems. These laboratories constitute the largest end-user segment due to their extensive testing capabilities and cost efficiencies.
- Home Care Providers:Deliver renal function testing services directly to patients' residences, primarily for chronic kidney disease monitoring. This segment represents a rapidly expanding channel driven by technology miniaturization and remote patient management needs.
- Pathology Clinics:Offer specialized diagnostic services, often integrating renal function tests with broader patient pathology profiles.
- Specialized Centers:Focus on specific medical areas like nephrology or critical care, requiring rapid and precise kidney function assessments.
- Research Institutions:Utilize kidney function tests for clinical trials, biomarker discovery, and understanding disease mechanisms.
Diagnostic Laboratories retain the largest volume of tests, yet Home Care Providers are gaining share fastest.
Application:
Applications for kidney function tests range across varying levels of clinical urgency, from long-term disease management to immediate diagnostic needs.
- Chronic Kidney Disease Monitoring:Involves routine testing to track disease progression, manage complications, and adjust treatment plans for patients with long-term kidney impairment. This application drives sustained demand, particularly in aging populations with high diabetes prevalence.
- Acute Renal Failure Detection:Requires rapid and accurate kidney function tests to identify sudden and severe loss of kidney function. Critical care settings and emergency departments prioritize swift results for timely intervention.
- Transplant Evaluation:Utilizes kidney function tests to assess donor compatibility and monitor recipient kidney health post-transplantation.
- Drug Toxicity Screening:Employs renal function tests to evaluate potential kidney damage caused by pharmaceutical agents during drug development or patient treatment.
- Hypertension Management:Integrates kidney function tests to assess renal involvement in high blood pressure and guide therapeutic strategies.
Chronic Kidney Disease Monitoring represents the largest application volume, while Acute Renal Failure Detection demands the highest diagnostic speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device exports from the United States frequently target European and Asian markets, driven by advanced diagnostic technologies. Germany and Japan represent significant buyer geographies for kidney function tests. This trade pattern reflects both technological innovation and demographic pressures in these regions.
United States
High diabetes prevalence drives demand for chronic kidney disease monitoring. The US FDA mandates stringent validation for new diagnostic devices before market entry. Major diagnostic companies in cities like San Diego frequently develop novel biosensor technologies for renal health.
Germany
An aging population and high diabetes rates create sustained demand for renal function screening. The EU's IVDR framework requires rigorous performance data for all in vitro diagnostic devices. Specialized nephrology centers in Munich adopt advanced point-of-care testing platforms.
Japan
Demographic shifts towards an older population necessitate extensive monitoring for kidney health. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees approval processes for diagnostic tests. Research institutions in Tokyo actively develop new biomarkers for early kidney disease detection.
China
Expanding healthcare infrastructure and rising chronic disease awareness fuel demand for kidney function tests. The NMPA's approval processes and GB standards govern market access for diagnostic devices. Diagnostic laboratories in Shanghai are rapidly adopting high-throughput testing systems.
India
Growing prevalence of diabetes and hypertension increases the need for routine renal screening. The Central Drugs Standard Control Organization (CDSCO) regulates the import and manufacture of diagnostic kits. Metropolitan areas like Bangalore see increasing demand for specialized kidney care clinics.
Kidney/Renal Function Test Market Key Industry Players
Channel-controlling players compete with product-specialist players across the kidney function test market. The market exhibits a tiered structure, with large, diversified diagnostic companies alongside focused technology innovators. Strategic archetypes include integrated solution providers, point-of-care device specialists, and high-throughput laboratory system manufacturers. Portfolio diversification and strategic partnerships represent dominant competitive moves among these entities.
At the scale-driven end, F. Hoffmann-La Roche Ltd exemplifies companies with broad diagnostic offerings, supporting large-scale laboratory operations. This Swiss-based entity leverages its extensive global footprint to serve diverse healthcare needs. Siemens Healthineers also occupies a position among major diagnostic providers, serving various healthcare settings globally with comprehensive solutions. Abbott represents a significant player focusing on platforms that deliver rapid diagnostic results, catering to critical care environments and point-of-care demands. These entities consistently invest in research to maintain their competitive edge in a dynamic market.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Siemens Healthineers |
| Danaher |
| Sysmex Corporation |
| Beckman Coulter |
| Bio-Rad Laboratories |
| Nova Biomedical |
| Quest Diagnostics |
| Others |
Cost & Logistics Intelligence
Specialized biosensor component manufacturing, often concentrated in specific Asian and North American regions, significantly influences where margin pools accumulate downstream for advanced point-of-care renal tests. This upstream concentration dictates the cost structure for device manufacturers.
Pricing Analysis
Technology-generation pricing gaps persist between established colorimetric methods and newer biosensor-based point-of-care devices. The dominant pricing model is a hybrid, combining transactional per-test fees for laboratory volumes with platform-based subscriptions for integrated home care solutions. Price differentiation stems from rapid turnaround times and advanced regulatory approvals like US FDA clearance. Pricing softness arises from disparities in reimbursement coverage for novel point-of-care assays, making diagnostic laboratories highly price-sensitive for high-volume screening.
Supply Chain Analysis
Export-control regimes, particularly those governing advanced microelectronics and specialized chemicals, limit the free flow of critical biosensor components. Geographic supply concentration for these inputs centers on China, the United States, and Germany for precision manufacturing. Key raw material dependencies include specialized polymers for microfluidic chips and immunoassay reagents. Single-source vulnerability for these specialized biosensor components represents a significant supply chain risk, with distribution running through direct sales channels and specialized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Kidney/Renal Function Test Market is at a platform-economics inflection, driven by the emergence of integrated remote monitoring ecosystems connecting point-of-care devices with telehealth platforms.
For Market Incumbents: Build data interoperability moats by investing in seamless integration capabilities for diverse point-of-care devices into existing electronic health records (EHR). Consolidate integrated diagnostic portfolios to counter emerging biomarker startups. Focus R&D on novel biomarker development to maintain a competitive edge against rapid POC device innovators. Expand channel control in the rapidly growing home care segment.
For New Entrants and Emerging Players: Pursue white-space opportunities in novel biomarker tests for more accurate eGFR calculations. Target underpenetrated markets in Southeast Asia by offering cost-effective, portable diagnostic solutions. Partner with digital health platforms to create integrated remote monitoring ecosystems for chronic kidney disease patients. Focus on specific patient populations requiring continuous, decentralized monitoring.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established diagnostic companies facing pressure from decentralized testing trends. The market offers long-term viability due to sustained demand from aging populations and rising chronic disease prevalence. Identify specialized point-of-care device manufacturers or digital health integration platforms as prime acquisition targets. A critical signal to watch is the evolution of reimbursement policies favoring remote patient monitoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Securing US FDA or EU IVDR clearance is crucial for market access and device credibility. |
| Platform Integration | Seamlessly connecting point-of-care devices with telehealth and EHR systems enhances patient management. |
| Novel Biomarker Development | Identifying new indicators beyond creatinine offers more precise kidney function assessment. |
| Hospital System Partnership | Collaborating with large healthcare networks expands market reach and clinical adoption. |
| Reimbursement Strategy | Aligning product offerings with evolving payer policies ensures economic viability for providers. |
Research Approach
Operator-level perspectives from nephrologists, lab directors, home care agency administrators, and diagnostic device engineers anchored the qualitative base. This study combined extensive primary interviews with rigorous secondary validation across diverse data sources. Secondary sources included US FDA filings, European Medicines Agency guidelines, NMPA approval documents, and relevant industry association reports. Bottom-up and top-down triangulation ensured comprehensive market sizing and segmentation accuracy.
Scenario-bracketing framing informed the quantitative modeling, integrating historical data extrapolation with forward-looking projections across the analysis window. Segmentation dimensions modeled included test type, technology, end-user, application, and regional regulatory compliance. Compound annual growth rates were derived from projected shifts in market size and test volume. Key forecast inputs included chronic kidney disease prevalence rates and point-of-care device adoption curves.
Sensitivities concentrate around unforeseen shifts in reimbursement policies or novel diagnostic breakthroughs. Forecasts reflect underlying assumptions on technology adoption rates and regulatory stability. Material shifts in regulatory frameworks or clinical practice guidelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Hemodialysis Services Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Renal Artery Embolization Market
Nephrology
US Dialysis Market
Nephrology
Plasmapheresis Market
Nephrology
Blood Dialyzer Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market