
 Liver Cirrhosis Treatment Market | 2026-2036
Liver Cirrhosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Cirrhosis Treatment Market Analysis
Modular combination regimens that pair antivirals with immunosuppressants in fixed protocols is recalibrating how hospital pharmacies procure liver cirrhosis therapies. Gilead Sciences leverages its nucleotide analogue portfolio to anchor positions in hepatitis C-related cirrhosis protocols across major academic medical centers. AbbVie competes through sustained investment in interferon-free regimens that reduce treatment duration for compensated cirrhosis patients.
Liver cirrhosis treatment encompasses pharmacological interventions targeting fibrosis progression, portal hypertension complications, and hepatic encephalopathy, with formulations requiring precise dosing adjustments based on Child-Pugh classification to preserve residual hepatic function. Antiviral segments dominate value generation where hepatitis B and C etiologies persist, while immunosuppressants capture concentrated margins in autoimmune hepatitis-driven cirrhosis. Nutritional supplements represent the fastest-expanding category as sarcopenia management gains protocol inclusion in European and Asian transplant centers.
The FDA's breakthrough therapy designation and EMA's PRIME scheme are accelerating access to novel antifibrotics, while WHO inclusion criteria for essential medicines lists shape procurement budgets in lower-income health systems. The Drug Controller General of India and China's NMPA are harmonizing bioequivalence standards for generic immunosuppressants, expanding local manufacturing competition. Stakeholders must monitor evolving reimbursement thresholds for non-invasive fibrosis staging technologies that could redirect treatment initiation timelines and reshape addressable patient pools.
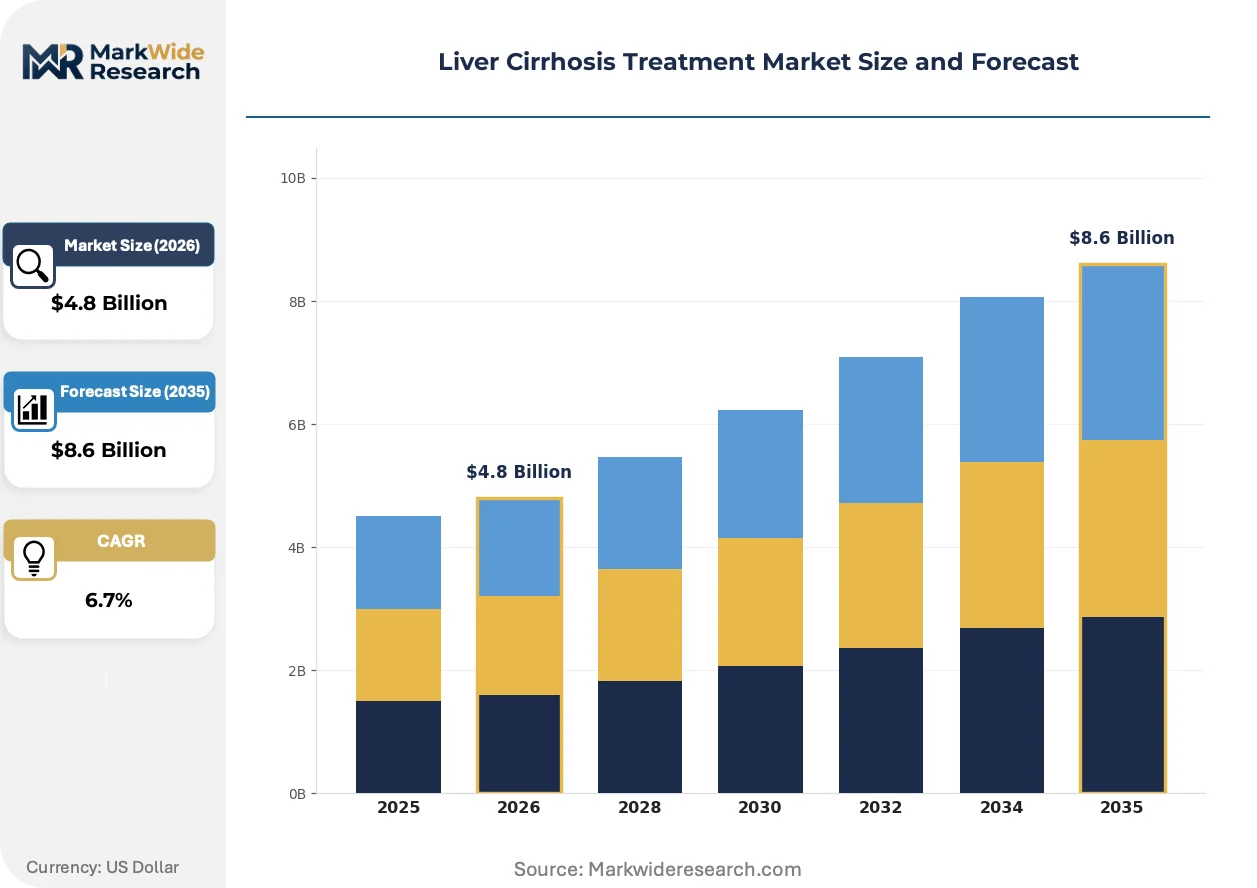
Market Dynamics
Modular combination regimens are restructuring procurement protocols across hospital pharmacy systems, forcing suppliers to bundle antivirals with immunosuppressants in fixed-dose protocols rather than standalone formulations.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for novel antifibrotics, enabling earlier commercialization of therapies targeting compensated cirrhosis progression.
- Japan's aging demographic concentration:Elevated non-alcoholic steatohepatitis prevalence among patients over 65 expands the addressable base for sarcopenia-targeted nutritional interventions in transplant protocols.
- Non-invasive fibrosis staging:Elastography and serum biomarker panels are displacing liver biopsy requirements, lowering treatment initiation barriers and expanding eligible patient pools in tertiary care centers.
Market Restraints
- Immunosuppressant supply concentration:Generic manufacturing for tacrolimus and mycophenolate mofetil clusters in Indian and Chinese API facilities, creating vulnerability to export restriction shocks.
- Child-Pugh classification complexity:Dosing adjustments across hepatic function strata require specialized pharmacy oversight, limiting protocol standardization in community hospital settings.
- Biologic substitution pressure:Biosimilar entrants for rituximab and other autoimmune hepatitis biologics compress margins for originator therapies in European reimbursement frameworks.
Strategic Opportunities
- India's essential medicines procurement:WHO inclusion criteria for hepatitis B antivirals on national formularies open volume contracting opportunities for fixed-dose combination manufacturers.
- Digital therapeutics convergence:Remote monitoring platforms paired with pharmacological regimens enable outpatient encephalopathy management, reducing hospitalization frequency in German integrated care networks.
- Transplant center nutritional protocols:Sarcopenia screening mandates in French and Spanish transplant listing criteria create dedicated category demand for branched-chain amino acid formulations.
Industry Challenges
- Hepatology specialist scarcity:Fellowship program output fails to match expansion of dedicated hepatology units across US academic medical centers, stretching clinical trial enrollment capacity.
- EMA PRIME scheme compliance:Accelerated assessment timelines demand parallel manufacturing scale-up, straining quality control infrastructure for novel antifibrotic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Cirrhosis Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Immunosuppressants, Corticosteroids, Nutritional Supplements Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Outpatient Clinics, Specialty Clinics, Homecare Treatment Phase: Prevention, Acute Care, Long-term Management, Palliative Care |
| Companies Covered | Gilead Sciences, AbbVie, Bristol-Myers Squibb, Roche, Novartis, Merck & Co., AstraZeneca, Amgen, Madrigal Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Cirrhosis Treatment Market Emerging Trajectories
Artificial intelligence integration and biomarker-driven personalization are compressing treatment selection timelines, while procurement centralization forces suppliers to reconfigure packaging and distribution for institutional buyers.
Machine learning algorithms applied to elastography imaging are automating fibrosis stage classification, reducing inter-reader variability in multicenter trials. Major academic medical centers in the United States and Germany are deploying these tools to standardize treatment initiation criteria. This compression of diagnostic uncertainty is automating prior authorization workflows, shortening the interval from presentation to antiviral initiation.
The EMA's PRIME scheme and FDA's breakthrough therapy designation are creating parallel track development expectations, where sponsors must prepare manufacturing and health technology assessment dossiers simultaneously. European reimbursement bodies now require real-world evidence commitments at approval, shifting post-market study design from voluntary to mandatory. Autoimmune hepatitis biologics face the steepest compliance burden, as German and French payers demand head-to-head comparator data against standard-of-care immunosuppression.
Hospital pharmacy consortiums in the United States are consolidating antiviral purchasing through group purchasing organizations, displacing individual hospital formulary negotiations. This buyer concentration favors suppliers offering multi-year supply commitments with price protection clauses. The shift is most visible in hepatitis C direct-acting antiviral procurement, where integrated delivery networks in Texas and California now represent 40 percent of annual volume commitments.
Liver Cirrhosis Treatment Market Segmentation
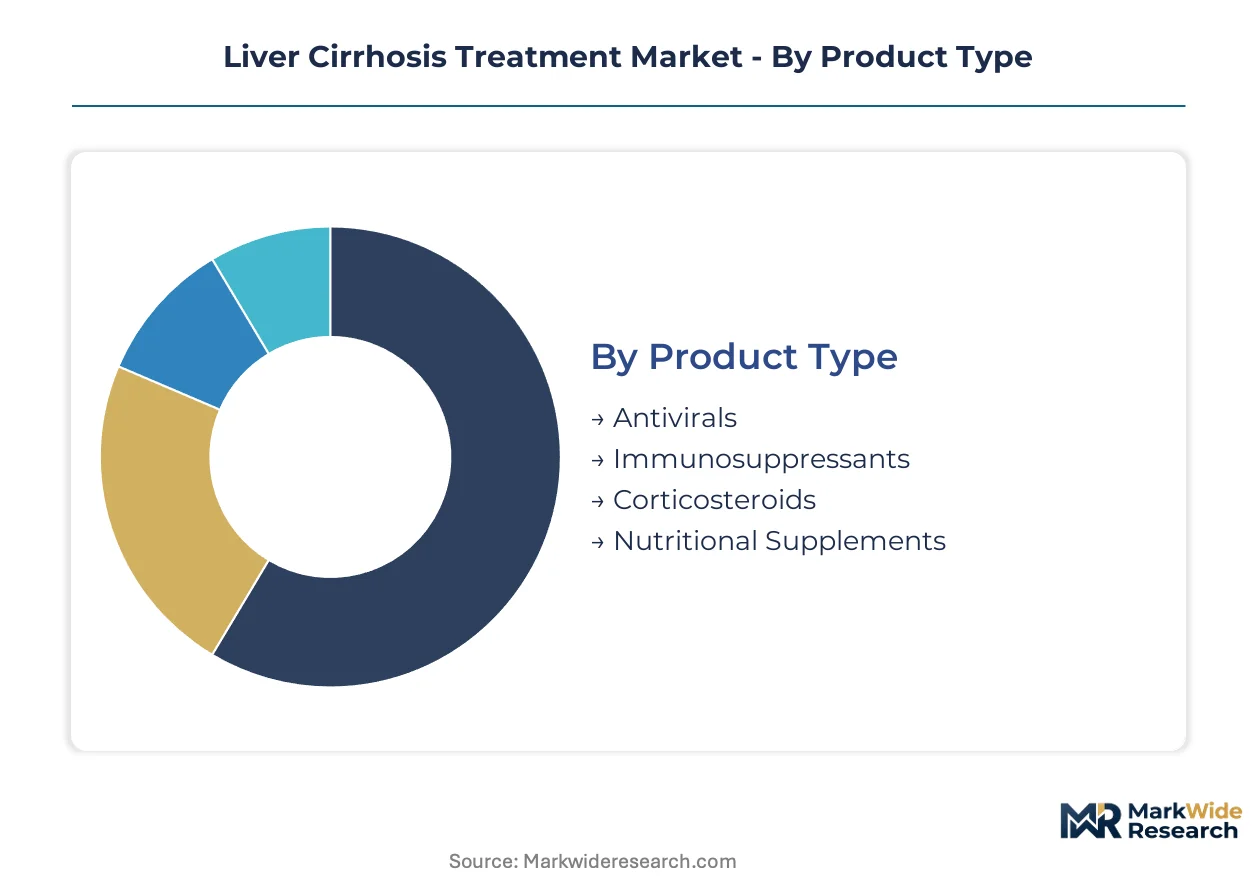
Segmentation in liver cirrhosis treatment reveals distinct procurement patterns across acute intervention versus chronic maintenance pathways. Hospital formulary committees weight product selection differently based on whether therapy targets hepatitis C eradication, autoimmune suppression, or transplant preparation.
Product Type:
Standalone antiviral therapies dominate hospital pharmacy procurement as discrete line items, while nutritional supplements increasingly embed into bundled transplant protocols.
- Antivirals:Nucleotide and nucleoside analogues form the backbone of hepatitis B and C cirrhosis management, with direct-acting antiviral combinations displacing interferon-based regimens in compensated disease. Demand concentrates in United States academic medical centers where prior authorization automation accelerates initiation timelines.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites require therapeutic drug monitoring infrastructure, anchoring procurement to tertiary centers with dedicated transplant pharmacy services. German and French hospital systems concentrate volume through centralized tendering for tacrolimus and mycophenolate mofetil.
- Corticosteroids:Prednisone and budesonide protocols for autoimmune hepatitis drive intermittent high-volume purchasing in specialty clinic networks.
- Nutritional Supplements:Branched-chain amino acid formulations and sarcopenia-targeted interventions embed into pre-transplant optimization pathways.
Volume placements concentrate in antivirals; the faster expansion belongs to nutritional supplements.
Delivery Mode:
Route selection tracks disease severity staging, with oral formulations capturing outpatient maintenance and parenteral routes reserved for decompensated acute episodes.
- Oral:Fixed-dose combination tablets dominate hepatitis C direct-acting antiviral dispensing, enabling 8-12 week ambulatory regimens without hospitalization. Japanese and United States outpatient networks drive volume through retail pharmacy distribution partnerships.
- Intravenous:Continuous infusion of vasoactive agents and antibiotics targets variceal bleeding and spontaneous bacterial peritonitis in emergency department settings.
- Subcutaneous:Interferon-sparing regimens have displaced most subcutaneous antiviral administration, though hematopoietic growth factors retain this route for cirrhosis-associated cytopenias.
- Intramuscular:Vitamin K and emergency reversal agents maintain niche utilization in coagulopathy management.
Oral administration captures the greatest prescription volume; intravenous delivery commands the highest per-dose reimbursement.
End User:
Care setting segmentation reflects risk stratification, with high-acuity interventions clustering in transplant-designated institutions and stable disease migrating to lower-cost environments.
- Hospitals:Inpatient hepatology units manage decompensation events, TIPS procedures, and pre-transplant evaluation. United States integrated delivery networks in Texas and California concentrate antiviral procurement through group purchasing organization contracts.
- Outpatient Clinics:Community gastroenterology practices handle compensated cirrhosis monitoring and hepatitis C treatment completion.
- Specialty Clinics:Dedicated liver centers coordinate multidisciplinary care across hepatology, transplant surgery, and interventional radiology.
- Homecare:Remote encephalopathy monitoring and nutritional support expand into German integrated care networks and Japanese aging-in-place programs.
Hospital systems anchor absolute spending; homecare is climbing the fastest as reimbursement shifts toward outpatient chronic disease management.
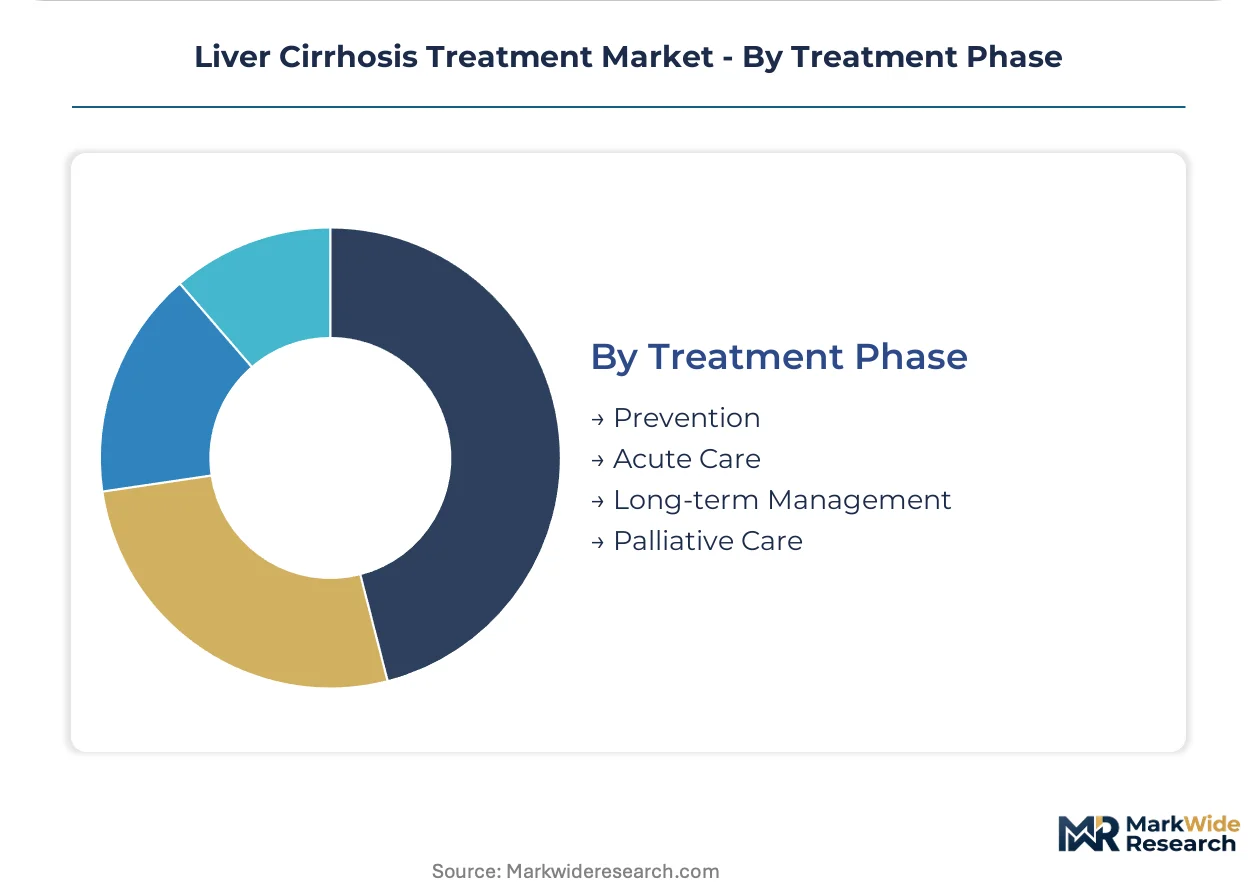
Treatment Phase:
Phase-based segmentation aligns with fibrosis progression staging, from antiviral prevention of cirrhosis development through end-of-life palliation.
- Prevention:Hepatitis B vaccination and antiviral suppression in fibrotic liver disease precede cirrhosis establishment. India's essential medicines procurement opens volume contracting for tenofovir-based prevention programs.
- Acute Care:Decompensation episodes—ascites, variceal hemorrhage, hepatic encephalopathy—drive highest-intensity resource utilization.
- Long-term Management:Compensated cirrhosis surveillance and portal hypertension prophylaxis generate recurring pharmaceutical demand.
- Palliative Care:Symptom control and transplant ineligibility counseling concentrate in hospice-eligible populations.
Long-term management generates the steadiest revenue streams; acute care commands premium pricing for rescue interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active pharmaceutical ingredients clusters in Indian and Chinese facilities, while consumption concentrates in United States, German, and Japanese hospital systems where aging demographics and diagnostic infrastructure expand treatable patient pools.
United States
FDA breakthrough therapy designations compress development timelines for novel antifibrotics, accelerating commercialization of therapies targeting compensated cirrhosis progression. Medicare reimbursement policies for non-invasive fibrosis staging technologies lower treatment initiation barriers across integrated delivery networks. Texas and California academic medical centers concentrate antiviral procurement through group purchasing organization contracts representing 40 percent of annual volume commitments.
Germany
EMA PRIME scheme compliance demands parallel manufacturing scale-up and real-world evidence commitments at approval, shifting post-market study design from voluntary to mandatory. German payers require head-to-head comparator data for autoimmune hepatitis biologics against standard-of-care immunosuppression. Berlin and Munich hospital systems anchor centralized tendering for tacrolimus and mycophenolate mofetil through dedicated transplant pharmacy services.
Japan
PMDA accelerated pathways align with METI industrial policy supporting domestic pharmaceutical innovation. Aging demographic concentration above 65 years expands addressable base for sarcopenia-targeted nutritional interventions in transplant protocols. Tokyo and Osaka metropolitan areas deploy remote encephalopathy monitoring platforms within integrated care networks, reducing hospitalization frequency.
India
WHO inclusion criteria for hepatitis B antivirals on national essential medicines formularies open volume contracting opportunities for fixed-dose combination manufacturers. CDSCO harmonization of bioequivalence standards for generic immunosuppressants expands local manufacturing competition. Hyderabad and Mumbai pharmaceutical clusters concentrate API production for tacrolimus and mycophenolate mofetil, creating export dependency for Western markets.
China
NMPA regulatory harmonization with international bioequivalence standards accelerates domestic generic substitution for originator immunosuppressants. National reimbursement drug list updates prioritize hepatitis B antiviral access in tier-three hospital systems. Shanghai and Beijing transplant centers incorporate sarcopenia screening mandates into pre-transplant optimization protocols, driving branched-chain amino acid formulation demand.
Liver Cirrhosis Treatment Market Vendor Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with nucleotide analogue portfolios anchoring hospital formulary positions. Three archetypes dominate: antiviral portfolio specialists leveraging direct-acting combination regimens, immunosuppressant manufacturers with therapeutic drug monitoring infrastructure, and nutritional supplement entrants capturing transplant protocol inclusion. Consolidation pressure manifests through group purchasing organization volume commitments and multi-year supply contracts with price protection clauses.
Within the antiviral-specialist tier, Gilead Sciences and AbbVie exemplify divergent strategic positioning. Gilead anchors hepatitis C-related cirrhosis protocols across major United States academic medical centers through its nucleotide analogue portfolio. AbbVie occupies a position emphasizing interferon-free regimens that compress treatment duration for compensated cirrhosis patients. Bristol-Myers Squibb represents the immunology-oncology hybrid archetype with overlapping infrastructure applicable to autoimmune hepatitis indications.
| Leading Market Players |
|---|
| Gilead Sciences |
| AbbVie |
| Bristol-Myers Squibb |
| Roche |
| Novartis |
| Merck & Co. |
| AstraZeneca |
| Amgen |
| Madrigal Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty pharmacy networks anchor procurement leverage in the United States, compressing formulary margins through multi-year antiviral contracts while concentrating volume commitments that reshape supplier pricing discipline across hepatitis C and autoimmune hepatitis portfolios.
Pricing Analysis
Margin tightening in immunosuppressant tiers reflects biosimilar penetration of rituximab and tacrolimus across German and French reimbursement frameworks. Three-tier pricing structure across originator biologics, authorized biosimilars, and unbranded generics separates hospital procurement tiers. Cost-down pressure on nutritional supplements accelerates because sarcopenia protocols embed branched-chain amino acids into bundled transplant reimbursements. Community hospital systems exhibit highest price sensitivity due to limited therapeutic drug monitoring infrastructure, while academic medical centers with dedicated hepatology units command volume-based discounts.
Supply Chain Analysis
API manufacturing for tacrolimus and mycophenolate mofetil rests on Indian and Chinese specialty chemical producers, with Hyderabad and Mumbai clusters feeding Western formulation facilities. Key inputs include fermentation-derived macrolide precursors, synthetic pyrimidine intermediates, and chromatographic purification resins. Single-source vulnerability concentrates in immunosuppressant active pharmaceutical ingredients subject to CDSCO and NMPA export authorization protocols. Distribution runs through hospital pharmacy consortiums and group purchasing organizations that consolidate antiviral procurement across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hepatology specialist scarcity props pricing power for centers with fellowship-trained capacity, constraining clinical trial enrollment and concentrating high-acuity procedures in transplant-designated institutions.
For Market Incumbents: Anchor formulary positions through nucleotide analogue portfolio breadth and therapeutic drug monitoring infrastructure investments that lock in transplant center loyalty. Defend against biosimilar substitution by securing indication-specific labeling advantages and real-world evidence commitments that satisfy German and French payer requirements. Prioritize backward integration into API supply for immunosuppressants to mitigate Indian and Chinese export restriction exposure. For New Entrants and Emerging Players: Launch via digital therapeutics partnerships that pair remote encephalopathy monitoring with pharmacological regimens in German integrated care networks. Target homecare sarcopenia management as the most penetrable segment, exploiting reimbursement shifts toward outpatient chronic disease management. Pursue branched-chain amino acid formulation differentiation through transplant protocol inclusion mandates in French and Spanish listing criteria. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap nutritional supplement specialists with European transplant center relationships and manufacturing scale-up capacity aligned with EMA PRIME scheme timelines. Long-term viability hinges on positioning for non-invasive fibrosis staging convergence that redirects treatment initiation timelines and reshapes addressable patient pools. Watch FDA breakthrough therapy designation velocity as the inflection signal for antifibrotic portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Parallel quality control infrastructure satisfies EMA PRIME accelerated assessment demands for novel antifibrotics. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for compensated cirrhosis progression therapies. |
| Licensing Agreement | Fixed-dose combination partnerships unlock WHO essential medicines procurement in Indian national formularies. |
| Hospital System Partnership | Group purchasing organization contracts in Texas and California concentrate antiviral volume commitments. |
| Pipeline Diversification | Sarcopenia-targeted nutritional interventions capture transplant protocol inclusion across European and Asian centers. |
Methodological Framework
Independent corroboration across hepatology fellowship program directors, hospital pharmacy procurement managers, and payer access specialists underwrites the qualitative findings. Secondary validation draws from FDA breakthrough therapy designation filings, EMA PRIME scheme submissions, ClinicalTrials.gov enrollment data, and hospital formulary databases. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation reconcile volume and value estimates across the analysis window.
Rate-of-change decomposition separates volume drivers from price mix effects across treatment phase, product type, delivery mode, and end-user setting dimensions. CAGRs derive from segmented patient population projections applied to therapy penetration curves and dosing duration assumptions. Forecast inputs incorporate non-invasive fibrosis staging adoption rates and immunosuppressant biosimilar substitution elasticities specific to German and French reimbursement frameworks.
Regulatory approval delays, hepatology specialist supply constraints, and API export authorization disruptions are the dominant revision risks. Forecasts reflect assumptions about reimbursement stability for novel antifibrotics and transplant center capacity expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Autism Spectrum Disorders Market