
 Kidney Function Tests Market | 2026-2036
Kidney Function Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Function Tests Market Intelligence
Ireland's expansion of its medical device manufacturing capacity is reshaping competitive positioning for European market supply chains. F. Hoffmann-La Roche Ltd leverages its extensive portfolio of immunoassay systems to maintain a dominant share in high-throughput hospital laboratories. Abbott Laboratories specializes in point-of-care diagnostics, targeting decentralized testing environments like physician offices and expanding homecare settings. Siemens Healthineers sustains its market presence through a broad range of automated urinalysis and clinical chemistry analyzers for centralized labs.
Kidney function tests encompass a range of diagnostic procedures used to assess renal health and disease. These tests measure levels of specific biomarkers, such as creatinine and urea in blood or urine, to evaluate glomerular filtration and tubular function. Creatinine and blood urea nitrogen tests represent the foundational, high-volume segment, primarily conducted in hospitals and large diagnostic laboratories. For transplant monitoring applications, more advanced immunoassay-based tests are gaining traction over traditional spectrophotometry methods due to higher sensitivity.
Regulatory oversight from bodies like the US FDA and the European Medicines Agency (EMA) mandates stringent analytical and clinical validation for new diagnostic assays. In China, the NMPA's evolving requirements for local clinical trial data and adherence to GB standards influence market entry strategies for foreign manufacturers. Navigating this multi-layered regulatory landscape while ensuring data integrity from decentralized testing platforms is a critical operational challenge for device manufacturers and laboratories.
Market Dynamics
The decentralization of diagnostics is the central force shaping the kidney function test market. A confluence of patient demand for home-based monitoring and the commercial availability of sensitive, portable sensors is shifting testing volume away from exclusively high-throughput hospital laboratories.
Growth Catalysts
- Advancements in Sensor Technology:The commercialization of highly sensitive electrochemical sensors enhances the accuracy and speed of point-of-care diagnostic tools, enabling wider use in physician offices and homecare settings for chronic condition management.
- Rising Disease Prevalence:An increasing global incidence of chronic kidney disease and associated conditions like diabetes and hypertension expands the patient pool requiring routine monitoring, directly driving demand for creatinine and blood urea nitrogen tests.
- Public Health Investment:Government initiatives aimed at improving public health infrastructure and preventive care, particularly in countries like China, are expanding access to diagnostic services and creating a larger market for foundational kidney function screening.
Market Restraints
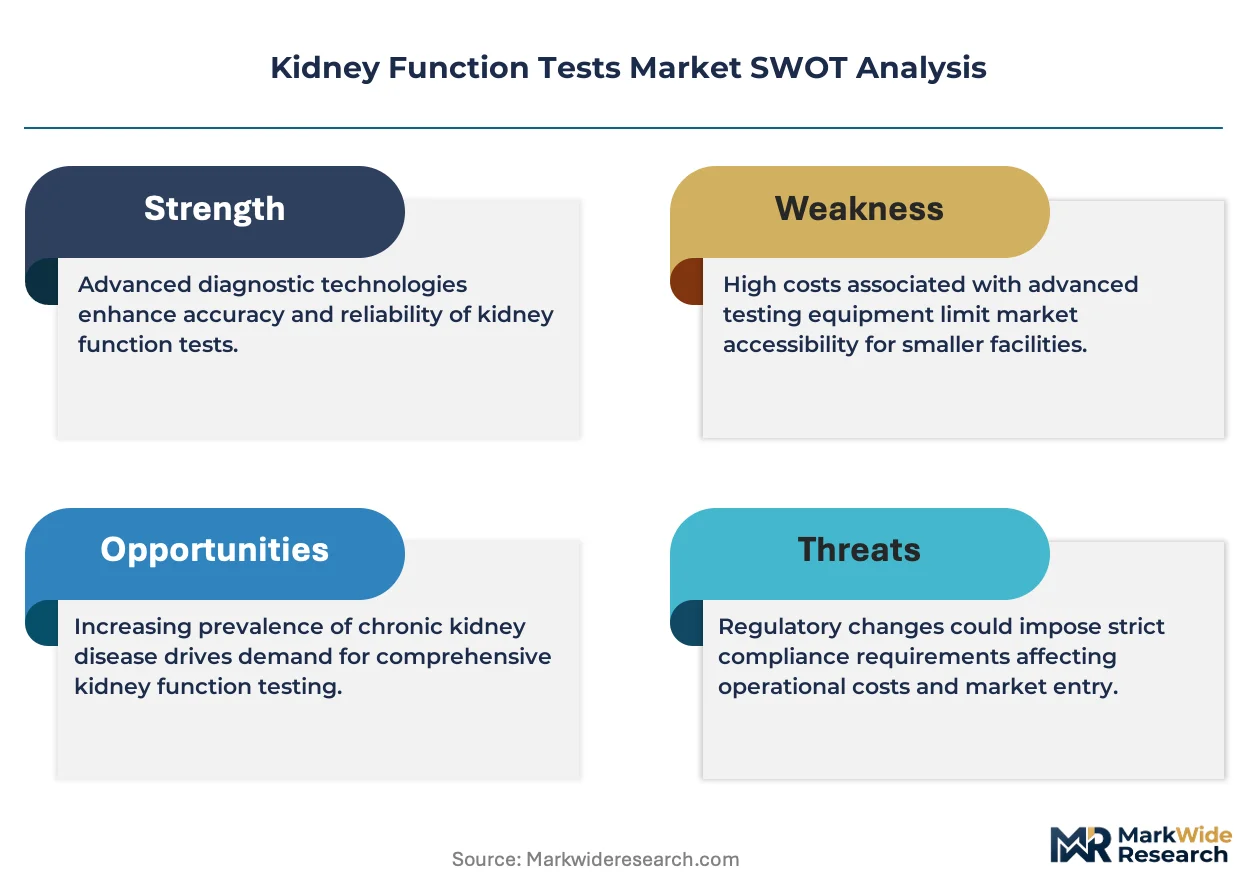
- Reimbursement Uncertainty:Inconsistent or limited reimbursement policies for newer, more expensive point-of-care and home-use kidney function tests in some healthcare systems can hinder their adoption compared to established laboratory-based methods.
- Stringent Regulatory Hurdles:The rigorous analytical and clinical validation requirements mandated by regulatory bodies such as the US FDA and EMA create long and costly development cycles for new diagnostic assays, acting as a barrier to market entry.
- Dominance of Traditional Methods:In many high-volume, cost-sensitive laboratories, foundational spectrophotometry methods for creatinine and urea testing remain entrenched due to their low cost and established workflows, slowing the uptake of advanced immunoassays.
Strategic Opportunities
- Digital Health Integration:Integrating test results from point-of-care and home devices with electronic health records and telehealth platforms offers a significant opportunity to provide continuous, data-driven patient management and predictive analytics for renal disease progression.
- Emerging Biomarker Development:Research into novel biomarkers beyond creatinine and urea presents an opportunity to develop more sensitive and specific tests for early detection of acute kidney injury or monitoring specific disease pathways.
- Geographic Expansion in Asia:Growing healthcare expenditure and improving diagnostic infrastructure in Southeast Asian nations provide a key opportunity for market expansion, particularly for cost-effective point-of-care and automated laboratory solutions.
Industry Challenges
- Data Management and Interoperability:Ensuring the security, integrity, and seamless integration of patient data generated from a diverse and growing ecosystem of decentralized testing platforms into central laboratory information systems is a major operational hurdle.
- Quality Control in Decentralized Settings:Maintaining consistent quality control and user proficiency for point-of-care and home-use devices presents a significant challenge for manufacturers and healthcare providers, impacting the reliability of results.
- Navigating Evolving Standards:Manufacturers face the complex task of adapting market entry strategies to accommodate evolving regional regulations, such as China's NMPA requirements for local clinical trial data and adherence to specific GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Function Tests Market |
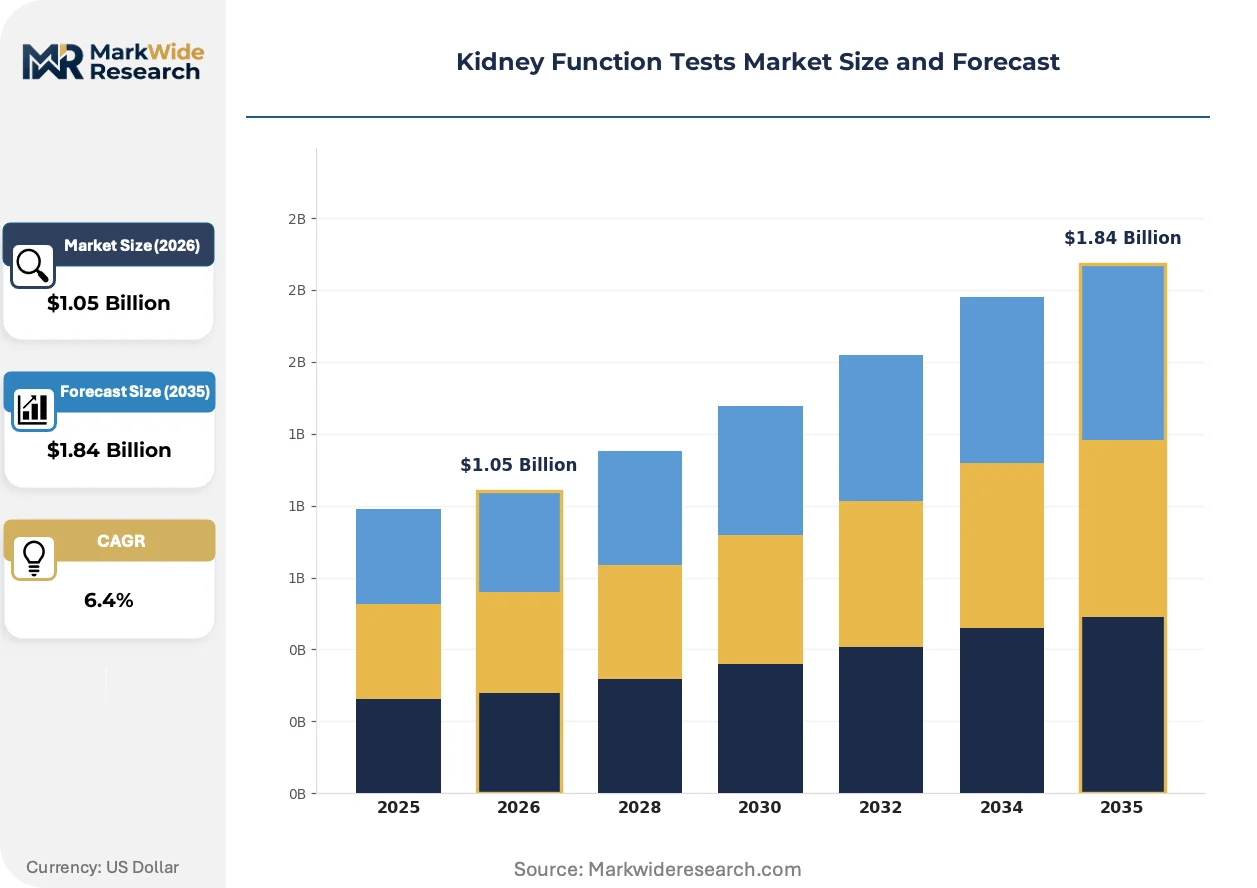
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urinalysis Test, Blood Urea Nitrogen Test, Creatinine Test, Glomerular Filtration Rate Test End User: Hospitals, Diagnostic Laboratories, Homecare Settings, Research Institutions Technology: Immunoassay, Chromatography, Spectrophotometry, Electrochemical Sensors Application: Chronic Kidney Disease, Acute Kidney Injury, Drug Monitoring, Transplant Monitoring |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers, Quest Diagnostics, Sysmex Corporation, Danaher, Randox Laboratories, Laboratory Corporation of America Holdings, Nova Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Function Tests Market Strategic Shifts & Innovations
The convergence of diagnostic miniaturization with digital connectivity is fundamentally altering the landscape for renal health assessment. This shift enables a more patient-centric model, moving routine monitoring from centralized facilities to distributed points of care, including the home.
Microfluidic and electrochemical sensor technologies provide the foundation for next-generation point-of-care devices. These systems allow for precise measurement of biomarkers like creatinine from a small sample of blood. Large diagnostic laboratories and specialty clinics are adopting these platforms for rapid-turnaround testing, especially in emergency departments and for transplant patient monitoring. The maturation of this technology is rendering obsolete the necessity for all routine monitoring to endure the delays of central lab batch processing.
A global tightening of regulatory expectations is influencing device design and validation protocols. The European Union's In Vitro Diagnostic Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance. This directly impacts manufacturers of both new and existing kidney function assays, compelling them to generate more extensive performance data. Immunoassay-based tests, particularly for specialized applications like transplant monitoring, are most affected by this heightened scrutiny.
A notable behavioral shift is occurring in how large healthcare systems acquire diagnostic technology. Hospitals are increasingly favoring comprehensive service agreements over one-time capital purchases of individual clinical chemistry or urinalysis analyzers. This trend disrupts the traditional sales model, requiring vendors to offer integrated solutions that include instrumentation, reagents, maintenance, and data management. This is most visible in North American and European hospital networks seeking to optimize laboratory operational efficiency.
Kidney Function Tests Market Segmentation
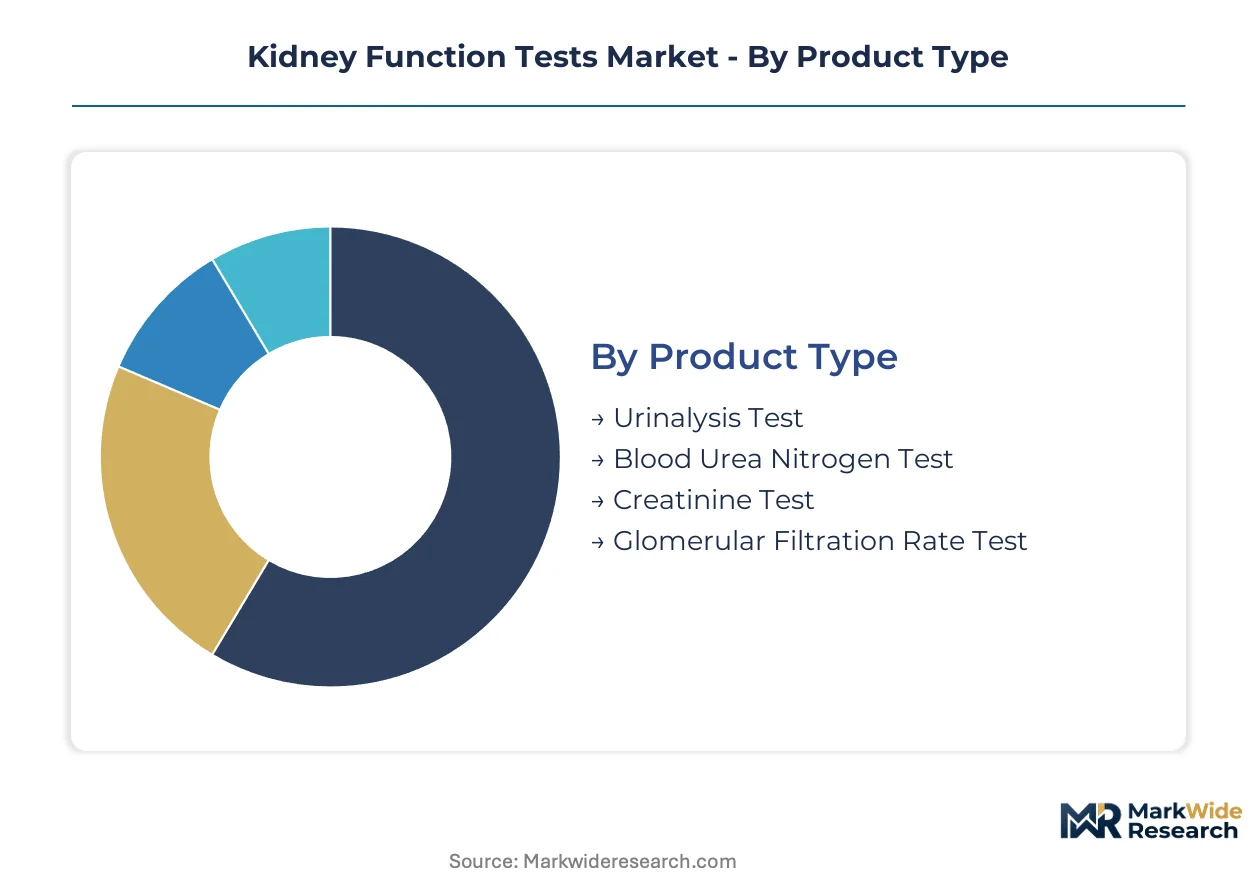
Understanding the segmentation of the kidney function tests market reveals how diverse diagnostic needs are met across various clinical settings. This granular view highlights the specialized requirements that influence product development, service delivery, and market penetration strategies for manufacturers.
Product Type:
The after-sales-service intensity for kidney function tests varies significantly across product types, influencing vendor support models and procurement decisions for healthcare providers.
- Creatinine Test:This foundational blood test measures creatinine levels to assess glomerular filtration rate, serving as a primary indicator of kidney function. Demand concentrates in hospitals and large diagnostic laboratories for routine screening and chronic disease management, driven by high prevalence of kidney disease.
- Blood Urea Nitrogen Test:A common blood test measuring urea nitrogen, it evaluates kidney and liver function, often performed alongside creatinine for a comprehensive renal health assessment. This test sees substantial demand in emergency departments and primary care settings, supported by its rapid turnaround time.
- Urinalysis Test:This broad screening test examines urine for various substances, indicating potential kidney issues, infections, or other systemic diseases.
- Glomerular Filtration Rate Test:These tests directly or indirectly estimate the rate at which blood is filtered by the kidneys, providing a more precise measure of renal impairment.
By volume, Creatinine Test leads. By growth pace, Glomerular Filtration Rate Test is ahead.
End User:
The cost tier for kidney function testing is heavily influenced by the end-user setting, dictating instrument complexity and reagent pricing strategies across the market.
- Hospitals:These facilities represent a major end-user segment, performing a high volume of both routine and specialized kidney function tests for inpatients and outpatients. Hospitals often prioritize integrated systems capable of high throughput and diverse test menus.
- Diagnostic Laboratories:Centralized diagnostic laboratories process vast quantities of samples from various healthcare providers, benefiting from economies of scale and automation for kidney function assays. These labs focus on efficiency and robust quality control for high-volume testing.
- Homecare Settings:Patients with chronic conditions increasingly utilize portable devices for self-monitoring of kidney function, enhancing patient engagement and convenience.
- Research Institutions:These entities employ advanced kidney function tests for biomarker discovery, drug development, and understanding disease mechanisms.
Diagnostic Laboratories and Hospitals together manage the majority of testing volume.
Technology:
Each technology platform within kidney function testing finds specific application niches, from high-throughput screening to specialized biomarker detection.
- Spectrophotometry:This traditional method measures the absorption of light by chemical reactions, remaining a cost-effective and widely adopted technology for high-volume creatinine and urea testing. Spectrophotometry dominates in resource-constrained settings and established central laboratories due to its proven reliability.
- Electrochemical Sensors:These advanced sensors detect specific biomarkers through electrical signals, enabling highly sensitive and miniaturized point-of-care devices for rapid results. Demand for electrochemical sensors is rapidly expanding in homecare and decentralized clinical environments for chronic disease monitoring.
- Immunoassay:These tests use antigen-antibody reactions to detect specific biomarkers with high sensitivity, particularly valuable for advanced applications like transplant monitoring.
- Chromatography:This separation technique is used for precise quantification of various kidney function biomarkers, often for research or confirmatory testing.
Supply concentration for traditional Spectrophotometry remains high, while Electrochemical Sensors exhibit a more distributed innovation landscape.
Application:
The volume of kidney function tests performed is directly correlated with specific medical applications, with chronic conditions driving consistent demand across various settings.
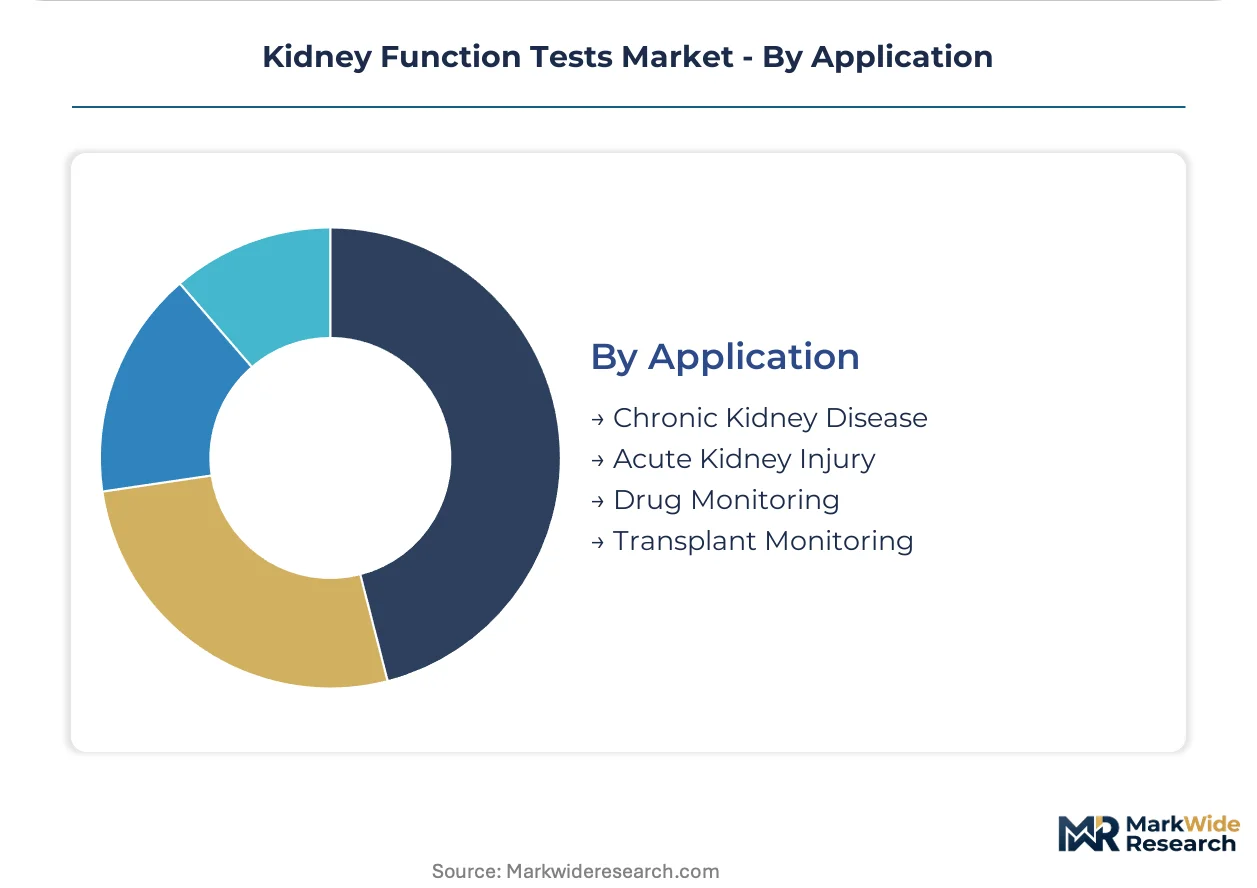
- Chronic Kidney Disease:This application segment focuses on long-term monitoring and early detection of progressive kidney damage, necessitating frequent and routine kidney function tests. The global rise in diabetes and hypertension directly contributes to the substantial and sustained demand for these tests.
- Transplant Monitoring:Advanced kidney function tests are critical for monitoring organ rejection and graft function in transplant recipients, requiring highly sensitive and specific biomarker detection. Immunoassay-based tests are gaining traction in this specialized application due to their enhanced precision.
- Acute Kidney Injury:Rapid diagnostic tests are crucial for identifying sudden kidney damage, enabling timely intervention and management in critical care settings.
- Drug Monitoring:Kidney function tests are essential for adjusting drug dosages and monitoring potential nephrotoxic effects of medications, particularly in oncology and infectious disease treatment.
Chronic Kidney Disease testing represents a mature segment, whereas Transplant Monitoring applications are rapidly evolving.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA regulations significantly influence the global kidney function tests market, particularly regarding market entry strategies. The country's substantial patient pool and government investments in public health drive demand. This dynamic interplay of regulation and market size shapes regional development across key geographies.
China
Demand for kidney function tests in China is rapidly expanding due to the increasing prevalence of chronic kidney disease and government-led public health initiatives. The NMPA's evolving requirements for local clinical trial data and adherence to GB standards shape market access. Major diagnostic manufacturing hubs in the Yangtze River Delta innovate localized point-of-care solutions.
United States
The United States market sees high demand for both routine and advanced kidney function tests, driven by a large aging population and widespread chronic conditions. Regulatory oversight from the US FDA mandates stringent analytical and clinical validation for new diagnostic assays. Biotechnology clusters in Boston and California develop novel biomarkers and diagnostic platforms.
Germany
Germany's robust healthcare infrastructure and focus on preventive care sustain consistent demand for kidney function diagnostics. The European Medicines Agency (EMA) and EU IVDR impose stricter requirements for clinical evidence and post-market surveillance. Diagnostic companies in Bavaria and North Rhine-Westphalia are key suppliers for high-throughput hospital laboratories.
Japan
Japan's advanced healthcare system and significant elderly population contribute to steady demand for kidney function tests, especially for chronic disease management. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous approval processes for diagnostic devices. Research institutions in the Tokyo metropolitan area actively explore new diagnostic technologies.
India
India's kidney function tests market is experiencing growth fueled by improving diagnostic infrastructure and a rising incidence of chronic kidney disease. The Central Drugs Standard Control Organization (CDSCO) regulates the import and manufacture of diagnostic kits, influencing market entry. Major medical device manufacturing zones near Mumbai and Chennai expand local production capabilities.
Kidney Function Tests Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the kidney function tests market. The market exhibits a tiered structure, with established multinational corporations holding significant shares in high-throughput laboratory segments. Specialized diagnostics providers focus on niche applications like point-of-care testing and advanced biomarker detection. Strategic partnerships and targeted M&A activities are dominant competitive moves, alongside continuous portfolio diversification.
Within the high-throughput laboratory and immunoassay systems tier, F. Hoffmann-La Roche Ltd leverages its extensive portfolio to maintain a dominant share in hospital laboratories. This company's offerings cater to large-scale testing needs. Abbott Laboratories exemplifies a focus on decentralized testing environments, specializing in point-of-care diagnostics for physician offices and expanding homecare settings, addressing the shift towards patient-centric care. Siemens Healthineers occupies a strong position through its broad range of automated urinalysis and clinical chemistry analyzers, sustaining its market presence in centralized laboratory settings with comprehensive solutions.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers |
| Quest Diagnostics |
| Sysmex Corporation |
| Danaher |
| Randox Laboratories |
| Laboratory Corporation of America Holdings |
| Nova Biomedical |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly evolving NMPA and EU IVDR requirements, determine both pricing tier spreads and the supply chain shape for kidney function tests. This mandates localized validation and manufacturing strategies, influencing cost structures and market access. The stringent regulatory landscape creates barriers for new entrants while favoring established manufacturers with robust compliance infrastructures.
Pricing Analysis
Geographic price spreads for kidney function tests vary significantly, reflecting regional reimbursement policies and market maturity. Contract-based long-term offtake agreements dominate for high-volume tests in centralized laboratories. Price differentiation stems from assay sensitivity, regulatory certification (e.g., FDA approval, CE marking), and comprehensive after-sales service bundles for instrumentation. Pricing softness stems from the entrenched low-cost spectrophotometry methods in many established laboratories. Diagnostic laboratories and resource-constrained settings represent the most price-sensitive buyers, while specialized transplant monitoring applications show less sensitivity due to critical patient outcomes.
Supply Chain Analysis
Upstream feedstock dependencies for kidney function tests primarily involve specialized reagents, electrochemical sensor components, and microfluidic assemblies. Supply concentrations for these critical inputs are noted in China for general chemicals and in countries like Germany and the United States for advanced diagnostic components. A structural risk involves single-source vulnerability for highly specialized immunoassay reagents, impacting production continuity. Downstream distribution primarily runs through direct sales channels to large hospital networks and diagnostic laboratory groups, supplemented by specialized distributors for point-of-care and homecare devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fragmentation opportunity in kidney function tests is significant, driven by the decentralization of diagnostics and patient demand for home-based monitoring. This shift creates distinct niches for specialized solutions beyond traditional laboratory testing.
For Market Incumbents: Insulate core market share by investing in comprehensive service agreements that bundle instrumentation, reagents, and advanced data integration capabilities for hospital systems. Expand R&D into novel biomarkers for early disease detection, countering the threat from emerging point-of-care entrants. Reinforce channel control within centralized laboratories through robust supply chain management and technical support. Focus on securing long-term contracts with major healthcare providers to stabilize revenue streams against reimbursement uncertainty.
For New Entrants and Emerging Players: Build out specialized electrochemical sensor technologies for homecare and physician office settings, leveraging the demand for decentralized testing. Target underpenetrated geographic markets, particularly in Southeast Asian nations, with cost-effective and user-friendly point-of-care solutions. A go-to-market angle focused on seamless integration with digital health platforms and telehealth services offers a distinct competitive advantage. Prioritize regulatory approval for specific high-volume applications like routine creatinine monitoring.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized diagnostics providers with strong intellectual property in next-generation technologies. Long-term viability is underpinned by the increasing global incidence of chronic kidney disease and the shift towards preventive care. Identify acquisition targets with established regulatory pathways in key regions, particularly those developing novel biomarkers or advanced point-of-care platforms. The signal to watch is the clarification of reimbursement policies for home-based kidney function tests, which will unlock significant market potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secure long-term contracts and integrate advanced immunoassay systems within established networks. |
| Software Companion Development | Enhance data management and interoperability for decentralized kidney function test results. |
| Reimbursement Strategy | Advocate for favorable policies covering novel point-of-care diagnostics in target markets. |
| Electrochemical Sensor R&D | Drive miniaturization and accuracy for next-generation home-use monitoring devices. |
| NMPA Regulatory Navigation | Expedite market access for innovative kidney function assays in China. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and scientific publications on renal diagnostics. This approach integrates insights from interviews with nephrologists, hospital purchasing managers, diagnostic laboratory directors, and device manufacturers' R&D leads. Bottom-up data aggregation from segmented markets is validated against top-down total market estimates for comprehensive accuracy.
Forecast inputs considering historical trends, market dynamics, and projected technology adoption inform the quantitative modeling across the projection horizon. The analytical framework segments the market by product type, end-user, technology, application, and regional prevalence of chronic kidney disease. Compound annual growth rates are derived from these inputs, alongside specific considerations for disease incidence rates and regulatory approval timelines for new assays.
Stress conditions across reimbursement policy shifts and major public health crises were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and sustained healthcare expenditure growth. Cross-checking against national health statistics and major diagnostic provider reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Clinical Diagnostics Market