
 Complement 3 Glomerulopathy (C3G) Treatment Market | 2026-2036
Complement 3 Glomerulopathy (C3G) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Complement 3 Glomerulopathy (C3G) Treatment Market Outlook
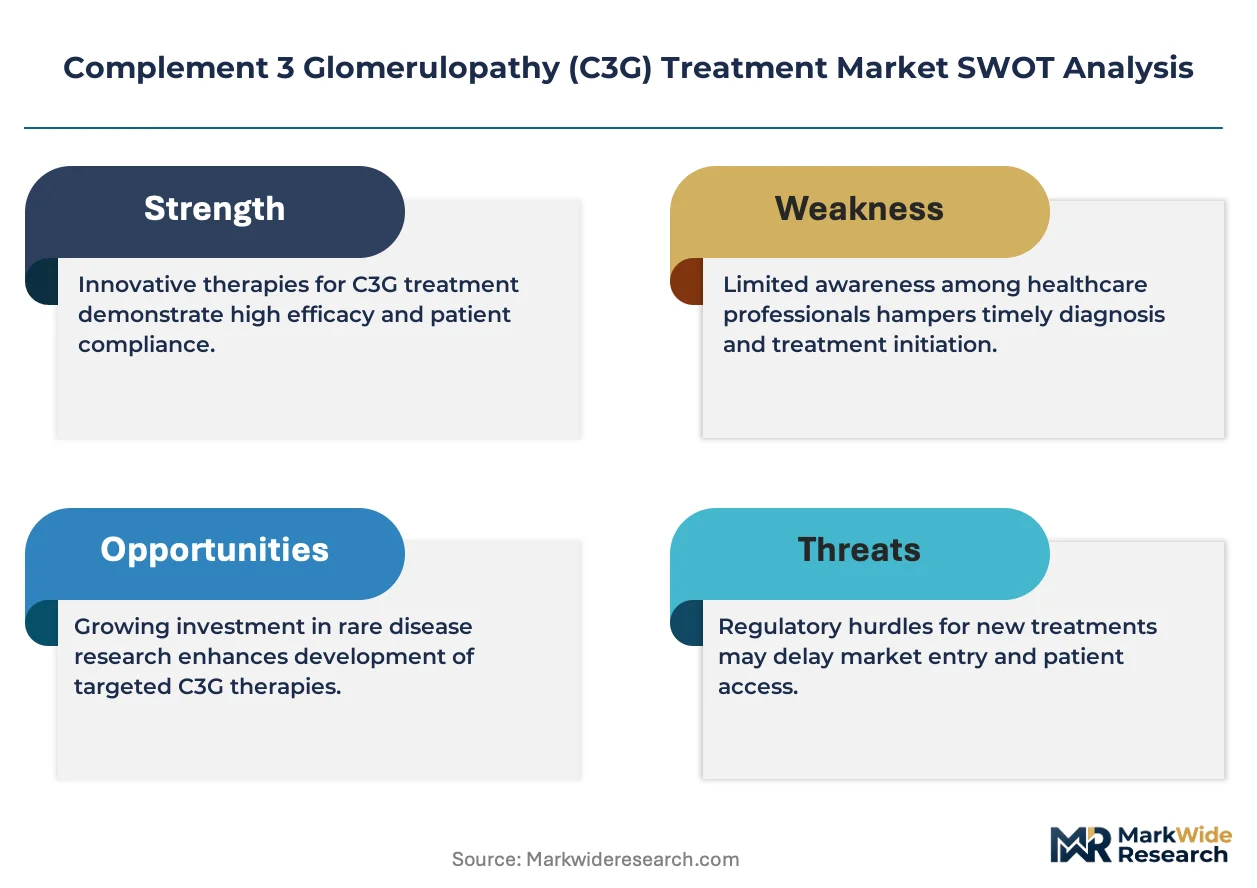
Project finance structures tailored to rare-disease biologics are reshaping competitive entry in C3G therapeutics, lowering capital barriers for development-stage firms. Alexion Pharmaceuticals leverages its complement-inhibitor manufacturing infrastructure to sustain cost advantages across production scales. Novartis AG anchors its position through nephrology-focused clinical trial networks that accelerate patient recruitment. Amyndas Pharmaceuticals differentiates via peptide-based complement modulation technology that occupies a distinct mechanistic niche.
Complement 3 Glomerulopathy (C3G) treatment encompasses therapeutic interventions targeting dysregulated alternative complement pathway activation that damages glomerular structures, with monoclonal antibodies and small molecule inhibitors designed to block C3 convertase activity or prevent membrane attack complex formation. These therapies aim to preserve renal function and delay progression to end-stage kidney disease in patients with confirmed C3G histopathology. Monoclonal antibodies command the deepest margin pools due to premium pricing and chronic administration protocols, while complement inhibitors represent the fastest-expanding category as next-generation C5 and C3-targeted agents advance through late-stage development. Small molecule inhibitors retain importance in cost-sensitive reimbursement environments where oral administration reduces infusion center dependency.
FDA orphan drug incentives and EMA PRIME eligibility criteria shape development prioritization, with both frameworks offering protocol assistance and fee waivers that reduce regulatory capital requirements for C3G indications. The European MDR and FDA's evolving gene-therapy guidance create compliance complexity for companies pursuing RNA-interference or gene-editing platforms in complement modulation. Stakeholders must monitor payer evidence requirements for renal endpoints, as health technology assessment bodies increasingly demand hard kidney-function outcomes rather than biomarker surrogates for rare disease therapies.
Market Dynamics
Specialty nephrology clinics are consolidating referral pathways for C3G patients, concentrating treatment decisions within a shrinking network of academic medical centers that control access to novel complement inhibitors.
Growth Catalysts
- FDA Orphan Drug Designation:Fee waivers and protocol assistance compress regulatory capital requirements for developers targeting C3G indications.
- EMA PRIME Eligibility:Accelerated assessment pathways reduce time-to-market for biologics addressing unmet renal disease needs.
- Peptide-based complement modulation:Distinct mechanistic approaches open therapeutic niches beyond monoclonal antibody dominance.
Market Restraints
- Infusion center dependency:Parenteral administration of complement inhibitors locks treatment delivery to hospital-based infrastructure.
- Biomarker surrogate limitations:Health technology assessment bodies reject proteinuria endpoints in favor of hard kidney-function outcomes.
- Manufacturing scale constraints:Alexion's captive production infrastructure limits third-party access to cost-efficient complement inhibitor supply.
Strategic Opportunities
- Oral small molecule inhibitors:Administration route innovation reduces site-of-care requirements and expands addressable patient populations.
- RNA-interference platforms:Gene-silencing technologies enable durable complement pathway suppression with reduced dosing frequency.
- Nephrology-focused clinical trial networks:Novartis-backed recruitment infrastructure accelerates patient identification across multiple sites.
Industry Challenges
- Histopathology confirmation requirements:Renal biopsy mandates delay treatment initiation and complicate pediatric enrollment.
- Gene-therapy guidance uncertainty:FDA's evolving framework for complement modulation creates compliance complexity for platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complement 3 Glomerulopathy (C3G) Treatment Market |
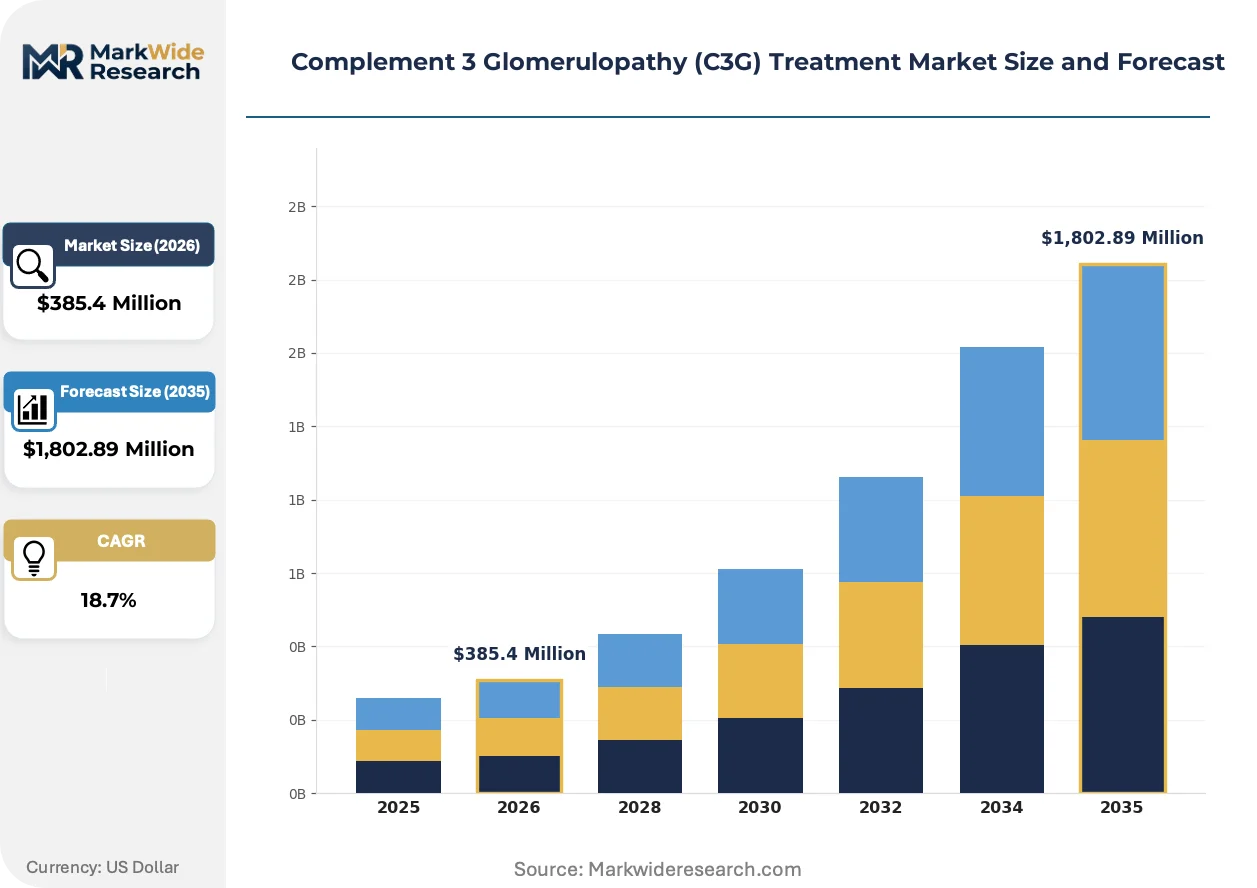
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Complement Inhibitors, Steroids End User: Hospitals, Outpatient Clinics, Specialty Clinics, Homecare Settings Treatment Approach: Immunosuppressive Therapy, Supportive Care, Plasma Exchange, Renal Replacement Therapy Administration Route: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | Novartis AG, Alexion Pharmaceuticals, Apellis Pharmaceuticals, Omeros Corporation, Amgen, Arrowhead Pharmaceuticals, Amyndas Pharmaceuticals, Kira Pharmaceuticals, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complement 3 Glomerulopathy (C3G) Treatment Market Strategic Shifts
Next-generation complement therapeutics are compressing development timelines through mechanistic diversification, while regulatory frameworks and procurement models simultaneously reshape competitive entry conditions.
Subcutaneous C5 inhibitor formulations are rendering obsolete the infusion center bottleneck that has constrained patient access to complement blockade. Nephrology practices in the United States are adopting self-administration protocols at accelerating pace. This delivery innovation is enabling home-based chronic management and expanding prescriber willingness to initiate therapy earlier in disease progression.
EMA's Medical Device Regulation creates compliance complexity for companion diagnostics used in C3G patient stratification. Manufacturers must navigate dual regulatory pathways for therapeutic-diagnostic combinations. Renal biopsy processing workflows face the steepest adaptation requirements as notified body oversight intensifies across European reference laboratories.
Specialty pharmacy distribution is displacing traditional buy-and-bill oncology models for complement inhibitors. Payers are mandating white-bag shipment to infusion centers to capture rebate value and control site-of-care costs. This channel restructuring is most visible in United States commercial insurance networks, where pharmacy benefit managers have consolidated renal rare disease contracting.
Complement 3 Glomerulopathy (C3G) Treatment Market Segmentation
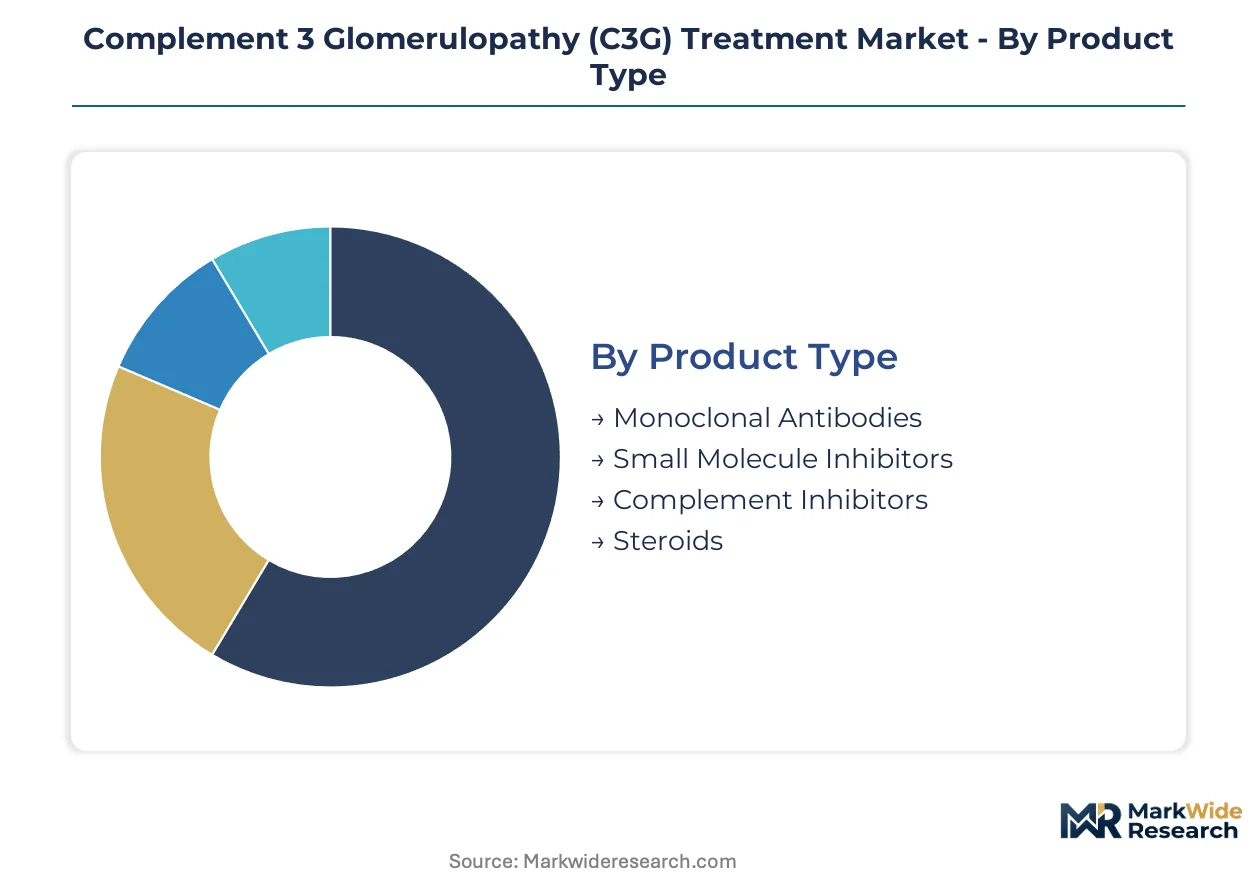
Treatment modalities for Complement 3 Glomerulopathy fragment across mechanistic classes, care settings, and delivery formats. Each segmentation axis reveals distinct margin structures, reimbursement pathways, and competitive entry barriers that shape portfolio prioritization for developers.
Product Type:
Mature biologic platforms anchor revenue concentration while emerging modalities reshape competitive positioning.
- Monoclonal Antibodies:Engineered immunoglobulins targeting C5 or C3 convertase components deliver sustained complement pathway blockade through high-affinity binding. Nephrology centers in the United States concentrate demand for these agents, driven by FDA orphan drug incentives that compress regulatory timelines and enable premium pricing for chronic administration protocols.
- Complement Inhibitors:Synthetic and biologic modulators of alternative pathway activation—including C3-targeted agents and factor B inhibitors—represent mechanistic diversification beyond C5 blockade. Specialty clinics in Germany and France are expanding adoption as EMA PRIME eligibility accelerates market access for novel renal disease therapeutics.
- Small Molecule Inhibitors:Oral bioavailable compounds targeting complement proteases or anaphylatoxin receptors.
- Steroids:Corticosteroid regimens for immunosuppressive induction in biopsy-confirmed cases.
Monoclonal antibodies handle the majority of throughput; complement inhibitors are climbing the fastest on share.
End User:
Site-of-care economics and infusion infrastructure requirements stratify patient access across delivery settings.
- Hospitals:Academic medical centers with embedded nephrology divisions manage complex C3G cases requiring biopsy confirmation, plasma exchange capability, and multidisciplinary coordination. These institutions in the United States control referral pathways for novel complement inhibitors, leveraging established relationships with specialty pharmacy distributors.
- Specialty Clinics:Dedicated renal disease centers concentrate expertise in rare glomerular disorders and maintain direct pipelines to clinical trial networks. Outpatient clinics in the United Kingdom are consolidating patient volumes as NHS England rare disease pathways mature.
- Outpatient Clinics:General nephrology practices handling stable patients on maintenance therapy.
- Homecare Settings:Subcutaneous self-administration protocols enabling chronic management outside institutional settings.
Hospitals retain the dominant patient volume; specialty clinics are expanding most quickly as referral networks consolidate.
Treatment Approach:
Clinical decision trees branch across disease severity, histopathology patterns, and transplant candidacy status.
- Immunosuppressive Therapy:Corticosteroid and calcineurin inhibitor regimens targeting underlying autoimmune drivers in C3G with monoclonal gammopathy or autoantibody positivity. Centers in Italy and Spain are refining protocols based on C3NeF titer monitoring.
- Plasma Exchange:Extracorporeal removal of pathogenic antibodies or complement components in rapidly progressive cases. Academic hospitals in the United States maintain capacity for urgent intervention in pediatric and adult patients with acute kidney injury.
- Supportive Care:Blood pressure management, proteinuria reduction, and cardiovascular risk modification.
- Renal Replacement Therapy:Dialysis and transplantation for end-stage kidney disease progression.
Immunosuppressive therapy carries the highest procedure volume; plasma exchange is gaining share fastest in acute presentations.
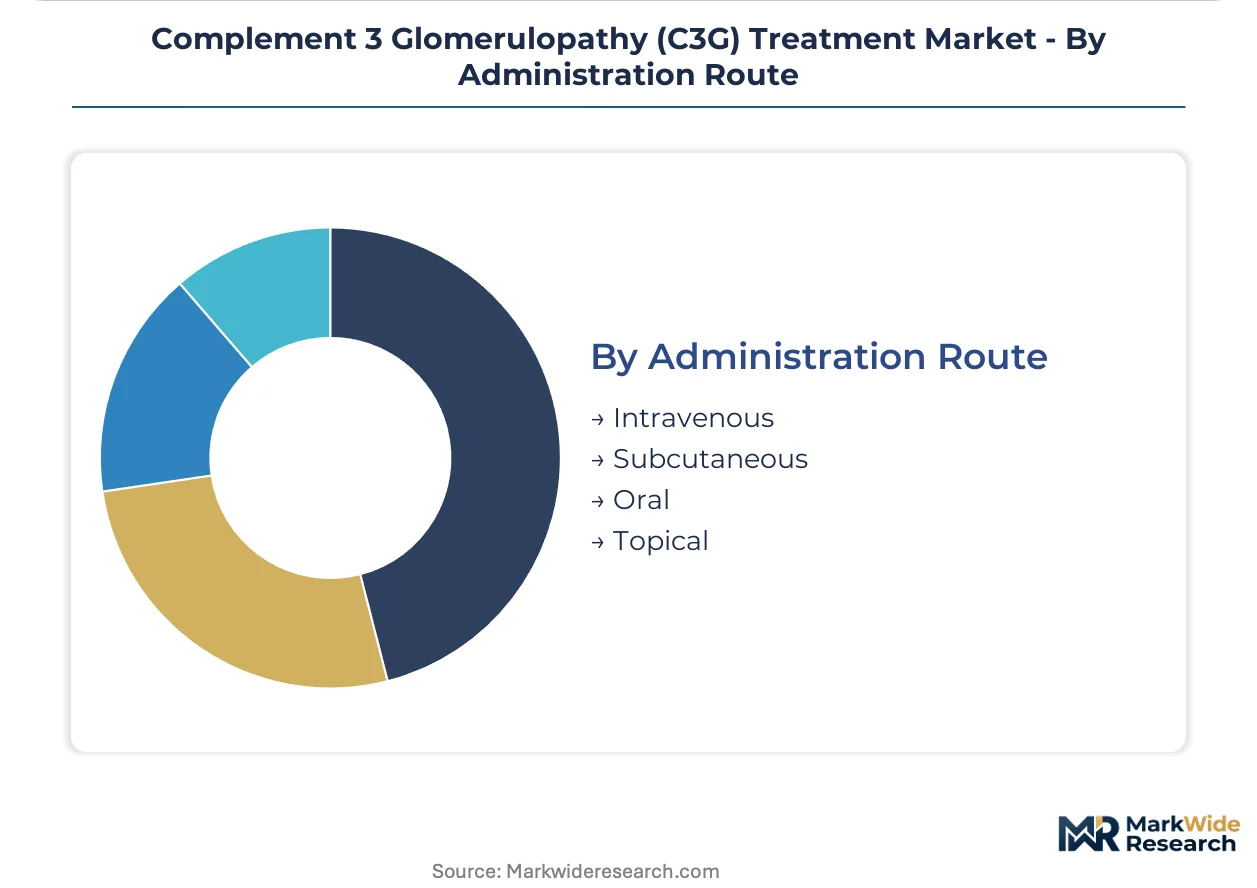
Administration Route:
Delivery format innovation is compressing site-of-care requirements and reshaping payer cost structures.
- Intravenous:Infusion center-based delivery of complement inhibitors and biologics requiring controlled administration. Hospital outpatient departments in the United States dominate this channel, though white-bag specialty pharmacy distribution is displacing traditional buy-and-bill models.
- Subcutaneous:Self-administered formulations reducing infusion center dependency and enabling home-based chronic management. Nephrology practices across the United States are adopting patient training protocols for C5 inhibitor pen devices.
- Oral:Small molecule inhibitors enabling administration without healthcare facility contact.
- Topical:Localized delivery formats for adjunctive symptom management.
Intravenous maintains the largest installed base; subcutaneous formulations are expanding most quickly as self-administration protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for complement therapeutics tilts toward the United States, while European markets balance domestic manufacturing with cross-border procurement. Export flows concentrate through Swiss and German distribution hubs serving EMA-regulated territories.
United States
Academic medical centers in Boston and New York drive demand for novel C3G therapeutics through established nephrology divisions. FDA orphan drug designation programs compress regulatory timelines for rare renal disease indications. The Research Triangle Park cluster in North Carolina anchors clinical trial operations for complement inhibitor developers.
Germany
Specialty renal clinics in Munich and Heidelberg consolidate patient volumes for complement pathway disorders under centralized rare disease pathways. EMA PRIME eligibility accelerates market access for biologics addressing unmet nephrology needs. The Frankfurt Rhine-Main biopharma corridor hosts manufacturing infrastructure for monoclonal antibody production.
United Kingdom
NHS England rare disease pathways mature in London and Manchester, streamlining referral networks for C3G diagnosis and treatment. NICE technology appraisals increasingly demand hard kidney-function endpoints over biomarker surrogates. The Cambridge life sciences cluster supports early-phase complement therapeutic development.
France
Reference centers for rare renal diseases in Paris and Lyon coordinate national patient registries for C3G epidemiology tracking. ANSM oversight aligns with EMA accelerated assessment frameworks for orphan indications. The Lyon biotech cluster specializes in peptide-based complement modulation technologies.
Japan
PMDA Sakigake designation programs attract complement inhibitor developers targeting Asian patient populations. Tokyo and Osaka academic hospitals maintain plasma exchange capacity for rapidly progressive glomerulonephritis cases. The Kanto region concentrates nephrology clinical trial sites for Asia-Pacific regulatory submissions.
Complement 3 Glomerulopathy (C3G) Treatment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the value chain. The C3G therapeutic space exhibits concentrated structure around complement pathway expertise, with large-cap biopharma entities leveraging manufacturing scale against mid-tier developers pursuing mechanistic differentiation. Two strategic archetypes dominate: vertically integrated rare disease specialists with captive production infrastructure, and platform-technology firms licensing RNA-interference or gene-editing modalities. Competitive moves center on nephrology-focused clinical trial network expansion and subcutaneous formulation development to reduce infusion center dependency.
Within the rare disease specialist tier, Alexion Pharmaceuticals and Novartis AG exemplify platform integrators with established complement inhibitor portfolios and nephrology clinical infrastructure. Amyndas Pharmaceuticals occupies a distinct position among peptide-based complement modulation specialists, representing the mechanistic diversification archetype that challenges monoclonal antibody dominance in C3G therapeutics.
| Leading Market Players |
|---|
| Novartis AG |
| Alexion Pharmaceuticals |
| Apellis Pharmaceuticals |
| Omeros Corporation |
| Amgen |
| Arrowhead Pharmaceuticals |
| Amyndas Pharmaceuticals |
| Kira Pharmaceuticals |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in monoclonal antibody production infrastructure across the United States and Germany is compressing contract manufacturing margins while simultaneously enabling price flexibility for developers of novel C3G therapeutics. This utilization dynamic rewards vertically integrated rare disease specialists with captive production assets, while forcing third-party developers to absorb higher COGS or surrender pricing power.
Pricing Analysis
Industrial OEM buyers anchor the pricing structure for complement inhibitor biologics through long-term offtake agreements with academic medical centers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA orphan drug designation status, EMA PRIME eligibility, and infusion center dependency. Cost compression in the standard tier is intensifying because white-bag specialty pharmacy distribution is displacing traditional buy-and-bill models. Pediatric nephrology centers exhibit highest price sensitivity due to biopsy confirmation requirements and delayed treatment initiation protocols.
Supply Chain Analysis
Upstream plasma fractionation capacity and recombinant protein expression systems in the United States, Switzerland, and Ireland feed the biologic active pharmaceutical ingredient pipeline for C3G therapeutics. Manufacturing draws from Chinese hamster ovary cell lines, single-use bioreactor systems, and affinity chromatography resins. Single-source vulnerability concentrates in Alexion's captive complement inhibitor production infrastructure. Distribution runs through specialty pharmacy networks with white-bag shipment mandates to infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The C3G treatment market represents a high-growth disruption propelled by FDA orphan drug designation compressing regulatory timelines for complement pathway modulators. This inflection rewards early movers with nephrology-focused clinical infrastructure and mechanistic diversification beyond C5 blockade.
For Market Incumbents: Insulate manufacturing margins through backward integration into plasma fractionation or recombinant expression capacity in the Research Triangle Park cluster. Lock in formulary position at academic medical centers by embedding clinical trial networks before subcutaneous formulation proliferation erodes infusion center dependency. Threat substitution from oral small molecule inhibitors demands preemptive portfolio diversification into C3-targeted agents. For New Entrants and Emerging Players: Establish a beachhead in peptide-based complement modulation, where Amyndas Pharmaceuticals has validated mechanistic differentiation without direct C5 inhibitor competition. Target the United Kingdom NHS England rare disease pathway as the most penetrable geography given NICE technology appraisal maturation and centralized referral consolidation. Lead with RNA-interference platform messaging to capture investor attention and accelerate partnership timelines with nephrology-focused contract research organizations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across subcutaneous formulation development as self-administration protocols reduce site-of-care infrastructure requirements. Five-to-ten year viability hinges on regulatory exclusivity durability rather than manufacturing scale. Prioritize acquisition targets with EMA PRIME eligibility and FDA orphan drug designation in hand. Watch FDA gene-therapy guidance evolution as the critical inflection signal for platform-technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Self-administration protocols at nephrology practices in the United States are displacing infusion center dependency. |
| Nephrology Clinical Trial Network Expansion | Novartis-backed recruitment infrastructure accelerates patient identification across Boston and New York academic centers. |
| Peptide-Based Complement Modulation | Amyndas Pharmaceuticals validates mechanistic diversification beyond monoclonal antibody dominance in C3G therapeutics. |
| Specialty Pharmacy Distribution Consolidation | White-bag shipment mandates to infusion centers capture rebate value for pharmacy benefit managers. |
| EMA PRIME Eligibility Pursuit | Accelerated assessment pathways reduce time-to-market for biologics addressing unmet renal disease needs in Germany and France. |
Study Parameters
The analysis maps monoclonal antibodies, complement inhibitors, small molecule inhibitors, and peptide-based modulators, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down revenue triangulation anchored the market sizing framework.
Assumptions around FDA orphan drug incentive continuity, EMA PRIME eligibility criteria stability, and infusion center infrastructure capacity were held fixed across the projection horizon, while C3NeF testing penetration and subcutaneous adoption curves were varied. Segmentation dimensions modeled include treatment modality, administration route, end-user setting, and regional regulatory cluster. CAGRs derived from patient prevalence projections, treatment initiation rates, and pricing trajectory assumptions for biologic versus small molecule modalities.
Stress conditions across FDA gene-therapy guidance uncertainty, EMA MDR compliance complexity for companion diagnostics, and payer evidence requirement shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledged sensitivity to regulatory timeline compression and health technology assessment body endpoint preferences. Cross-checking against CMS Medicare rare disease spending data and NHS England commissioning datasets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Nephrotic Syndrome Market
Nephrology
US Dialysis Services Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Hemodialyzer Market
Nephrology
Dialysis Centers Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
US Dialysis Centers Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Kidney Transplant Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Global Renal Medical Devices and Services Market