
 ICU-Acquired Acute Kidney Treatment Market | 2026-2036
ICU-Acquired Acute Kidney Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
ICU-Acquired Acute Kidney Treatment Market Foresight
The premium-commodity divide in ICU-Acquired Acute Kidney Treatment is shifting toward membrane biocompatibility and automated dosing precision versus basic ultrafiltration capacity. Baxter International leverages its integrated CRRT platform to anchor high-acuity hospital contracts across North America. Fresenius Medical Care sustains manufacturing scale that dominates consumables supply for dialysis circuits. Asahi Kasei Medical specializes in hollow-fiber membrane technology that differentiates its hemofilters in Japan and European markets.
ICU-Acquired Acute Kidney Treatment encompasses renal support interventions initiated after critical illness triggers acute kidney injury, typically employing extracorporeal blood purification with ultrafiltration rates of 20-35 ml/kg/hour and biocompatible synthetic membranes to manage fluid overload and uremic toxins in hemodynamically unstable patients. Continuous Renal Replacement Therapy leads the product type landscape due to its tolerance in hypotensive ICU populations, while Automated Systems within delivery mode represent the fastest-growing configuration as intensivists prioritize reduced nursing burden and protocolized anticoagulation. Dialysis Machines retain mature margin pools through recurring consumables, whereas Non-Invasive Methods remain underdeveloped for this acute indication.
The FDA governs 510(k) clearance pathways for CRRT devices and dialyzers, while the EU Medical Device Regulation imposes clinical evidence requirements that extend market access timelines for new hemofiltration platforms. Japan's PMDA maintains distinct pharmaceutical-medical device hybrid oversight for anticoagulant integration in automated systems. Stakeholders must monitor evolving reimbursement thresholds for continuous versus intermittent modalities as health technology assessment bodies recalibrate value metrics for ICU length-of-stay reduction.
Market Dynamics
Automated dosing precision and membrane biocompatibility are displacing basic ultrafiltration capacity as the primary competitive differentiator in ICU renal support, forcing manufacturers to reallocate R&D toward integrated CRRT platforms rather than standalone dialysis machines.
Growth Catalysts
- FDA 510(k) pathway evolution:Streamlined clearance for next-generation hemofilters accelerates product cycles for US-based device manufacturers targeting critical care units.
- Germany's ICU infrastructure investment:Federal hospital modernization programs expand dedicated renal support capacity in tertiary centers across Bavaria and North Rhine-Westphalia.
- Synthetic membrane technology:Polysulfone and polyethersulfone hollow-fiber advances improve solute clearance efficiency in continuous renal replacement circuits.
Market Restraints
- EU MDR clinical evidence requirements:Extended market access timelines for new hemofiltration platforms delay commercialization by 18-24 months compared to prior CE-marking procedures.
- Consumables supply concentration:Dialysis circuit manufacturing clusters in Bad Homburg and Tokyo create geographic vulnerability for North American hospital procurement.
- Intermittent hemodialysis substitution:Cost-conscious health systems in Southern Europe retain older modalities for hemodynamically stable patients, limiting CRRT penetration.
Strategic Opportunities
- Japan's super-aging prefectures:Aomori and Akita present concentrated demand for automated anticoagulation systems as nursing ratios tighten in rural ICU settings.
- Anticoagulant-device convergence:Regional citrate protocols integrated into delivery platforms reduce bleeding complications and extend treatment windows.
- Home-based acute transition:Portable ultrafiltration devices for post-ICU recovery create channel expansion beyond traditional hospital procurement.
Industry Challenges
- Intensivist-nephrologist coordination protocols:Skill gaps in CRRT prescription standardization generate treatment variability across US academic medical centers.
- Legacy EMR integration:Data interoperability between automated renal replacement systems and hospital information networks requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ICU-Acquired Acute Kidney Treatment Market |
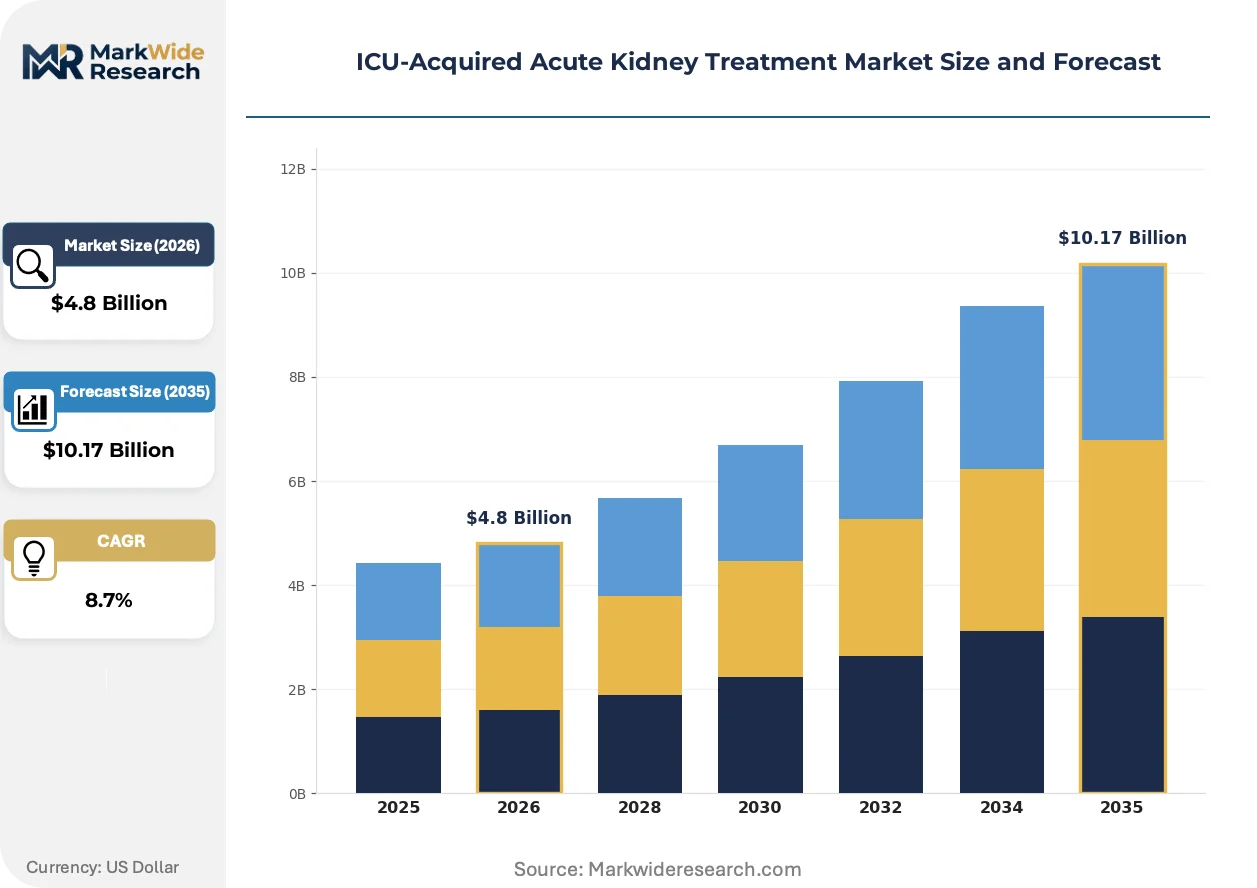
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialysis Machines, Continuous Renal Replacement Therapy, Hemofiltration Devices, Peritoneal Dialysis Therapy Area: Critical Care Nephrology, Fluid Management, Electrolyte Monitoring, Volume Control End User: ICUs, Emergency Departments, Nephrology Clinics, Home Care Providers Delivery Mode: Invasive Techniques, Non-Invasive Methods, Automated Systems, Manual Intervention |
| Companies Covered | Asahi Kasei Medical, Medtronic, Baxter International, Infomed SA, Nipro Corporation, Fresenius Medical Care, Nikkiso Co. Ltd., Medica S.p.A, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ICU-Acquired Acute Kidney Treatment Market Shifts & Advancements
Membrane chemistry and automation architecture are converging to redefine performance benchmarks in extracorporeal blood purification, with regulatory bodies recalibrating safety thresholds in parallel.
Polymethyl methacrylate membranes with enhanced adsorptive capacity for endotoxin and inflammatory mediators are expanding into sepsis-associated acute kidney injury protocols. Tertiary ICU departments in university hospitals adopt these surfaces at twice the rate of community facilities. The technology is expanding into indications beyond traditional uremic toxin management, compressing the addressable market for standard cellulose triacetate filters.
Japan's PMDA maintains distinct pharmaceutical-medical device hybrid oversight for anticoagulant integration in automated systems. Manufacturers must submit combined clinical evidence for citrate-calcium balancing algorithms alongside hardware clearance. European hemofiltration platforms face the steepest compliance burden, as PMDA reciprocity agreements exclude most EU-notified body certifications.
Hospital procurement departments now unbundle after-sales service contracts from device acquisition, selecting third-party clinical engineering firms for preventive maintenance. Original equipment manufacturers respond with subscription-based software updates and remote monitoring packages. This pattern appears most pronounced in German Krankenhaus procurement, where regional purchasing cooperatives extract 15-20% service cost reductions through competitive tendering.
ICU-Acquired Acute Kidney Treatment Market Segmentation
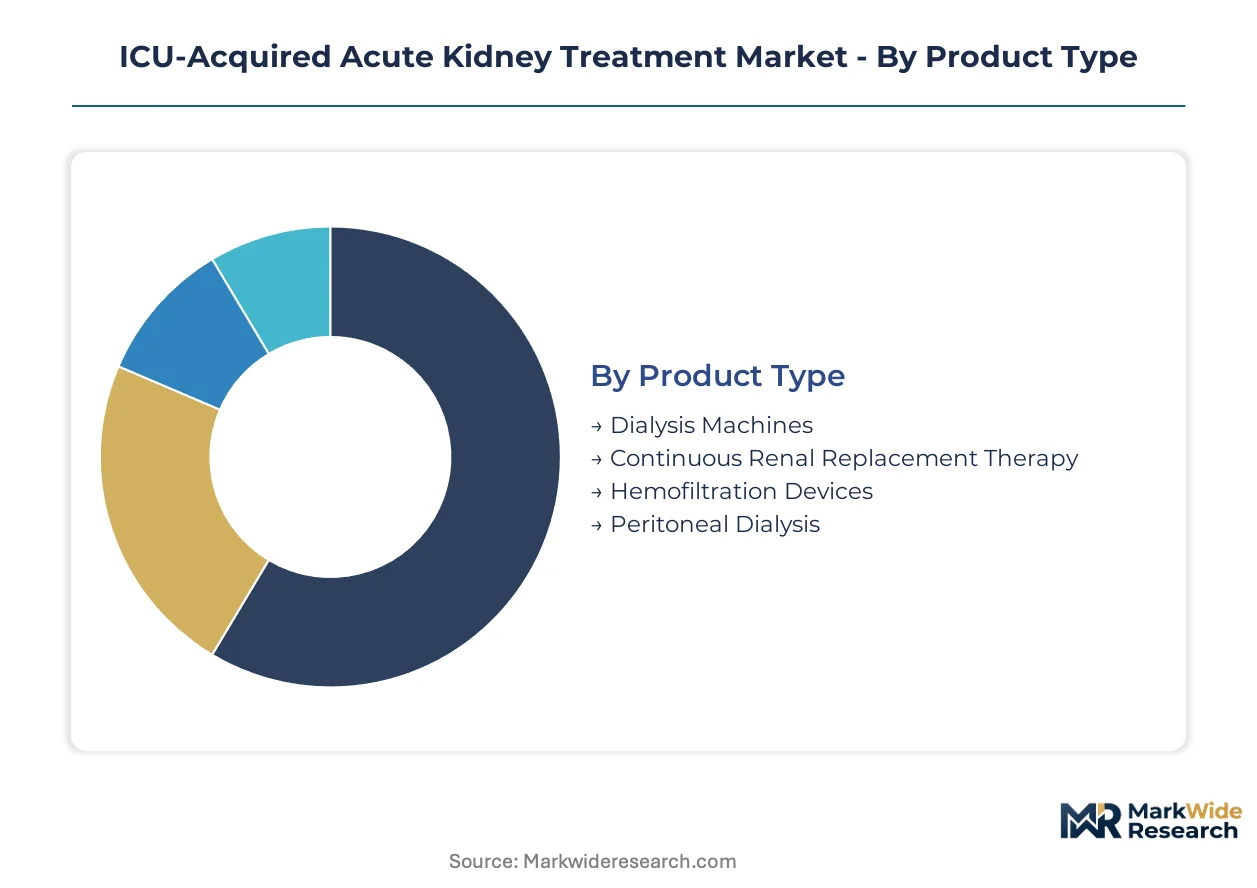
Segmentation in ICU-Acquired Acute Kidney Treatment reveals how clinical workflow constraints and hemodynamic instability drive technology selection. Understanding these divisions exposes where manufacturers capture premium pricing versus where procurement departments enforce commoditization.
Product Type:
Volume sales concentrate in established dialysis platforms while premium margins migrate toward integrated continuous systems that reduce nursing burden.
- Dialysis Machines:Intermittent hemodialysis equipment with blood flow rates of 200-400 ml/minute serves hemodynamically stable patients in step-down units. Demand clusters in Southern European health systems where cost containment preserves older modalities despite ICU length-of-stay penalties.
- Continuous Renal Replacement Therapy:Extracorporeal circuits delivering 20-35 ml/kg/hour ultrafiltration tolerate hypotensive populations that crash during conventional dialysis. German tertiary centers and Japanese university hospitals anchor demand as federal modernization programs expand dedicated CRRT capacity.
- Hemofiltration Devices:Standalone convection-based systems target specific solute clearance profiles without diffusive dialysis membranes.
- Peritoneal Dialysis:Catheter-based intraperitoneal fluid exchange retains niche application in pediatric ICUs and resource-limited settings without extracorporeal infrastructure.
Today's leader: Continuous Renal Replacement Therapy. Tomorrow's challenger: Hemofiltration Devices with adsorptive membrane surfaces.
Therapy Area:
Application focus determines whether vendors compete on clinical outcomes data or operational efficiency metrics.
- Critical Care Nephrology:Integrated management of acute kidney injury with multi-organ failure protocols demands coordinated intensivist-nephrologist workflows. Academic medical centers in the United States drive adoption of standardized prescription algorithms to reduce treatment variability.
- Fluid Management:Ultrafiltration precision for volume overload in sepsis and cardiac surgery recovery represents the highest-frequency CRRT indication. Japanese super-aging prefectures with tightening nursing ratios prioritize automated fluid balance systems.
- Electrolyte Monitoring:Real-time ionized calcium and potassium surveillance prevents arrhythmia during citrate anticoagulation.
- Volume Control:Negative fluid balance targets in acute respiratory distress syndrome require precise hourly ultrafiltration titration.
The steepest expansion trajectory sits with Fluid Management as ICU length-of-stay reduction becomes a reimbursable outcome metric.
End User:
Customer type segmentation exposes divergent procurement authority and technical sophistication across care settings.
- ICUs:Dedicated critical care units with 24-hour intensivist coverage generate the highest CRRT utilization rates and consumables throughput. Bavarian and North Rhine-Westphalian hospital networks anchor European demand through federal infrastructure investment.
- Emergency Departments:Resuscitation bays initiating early renal support require portable, rapid-deployment systems with simplified priming protocols. Urban trauma centers in Japan and Germany pilot these configurations for crush injury and rhabdomyolysis protocols.
- Nephrology Clinics:Outpatient dialysis providers expanding into acute transitional care create channel conflict with traditional hospital suppliers.
- Home Care Providers:Post-ICU recovery settings with portable ultrafiltration devices remain underdeveloped for this acute indication.
Procurement consolidation favors ICUs with standardized protocols. Emergency Departments are gaining share fastest as early renal support protocols expand.
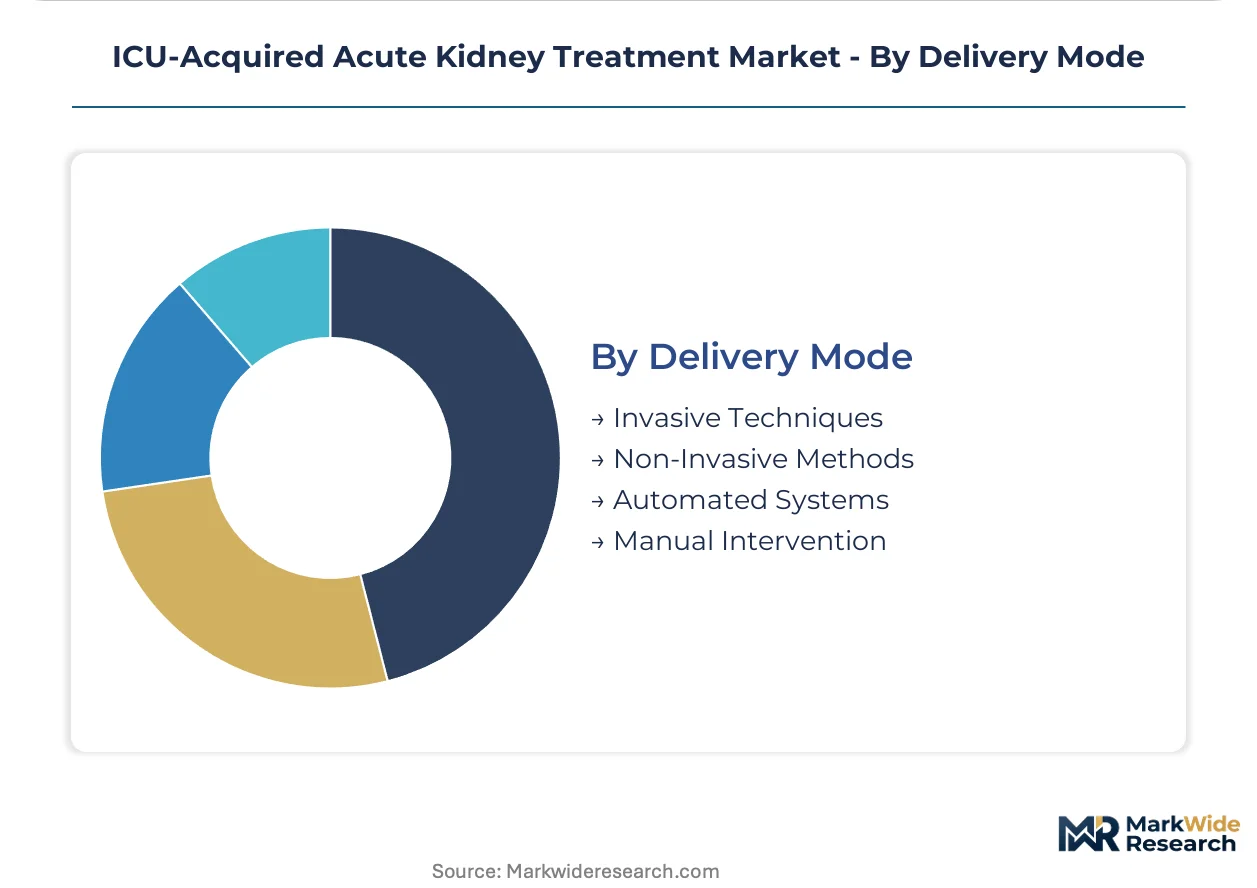
Delivery Mode:
Automation intensity separates premium configurations from labor-dependent alternatives that face nursing shortage constraints.
- Automated Systems:Integrated platforms with citrate-calcium balancing algorithms and protocolized anticoagulation reduce bedside intervention frequency. PMDA hybrid oversight requirements for pharmaceutical-device combinations create regulatory moats for compliant manufacturers in Japan.
- Invasive Techniques:Central venous catheter-based extracorporeal circuits remain the clinical standard despite bleeding and infection risks. FDA 510(k) pathway evolution streamlines clearance for next-generation catheter designs with antimicrobial surfaces.
- Non-Invasive Methods:Peritoneal and external ultrafiltration approaches avoid vascular access but deliver inferior solute clearance for uremic toxin management.
- Manual Intervention:Nurse-driven dose adjustments and heparin titration persist in undercapitalized facilities without automated platform investment.
Automated Systems command the premium tier. Manual Intervention faces steepest share erosion as workforce constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Intensivist and nephrology specialist concentrations in tertiary medical centers anchor demand geography for ICU renal support systems. Federal hospital modernization programs and aging demographics determine where automated CRRT platforms penetrate fastest.
United States
Academic medical centers in Boston and Baltimore drive adoption of protocolized anticoagulation algorithms. FDA 510(k) pathway evolution streamlines clearance for next-generation hemofilters with antimicrobial catheter surfaces. The Southeast corridor from Atlanta to Durham anchors manufacturing clusters for dialysis circuit consumables serving domestic hospital procurement.
Germany
Federal infrastructure investment in Bavarian and North Rhine-Westphalian tertiary centers expands dedicated CRRT capacity. EU MDR clinical evidence requirements extend market access timelines for new hemofiltration platforms by 18-24 months. Bad Homburg concentrates dialysis circuit manufacturing that supplies European hospital networks.
Japan
Super-aging prefectures of Aomori and Akita generate concentrated demand for automated anticoagulation systems as ICU nursing ratios tighten. PMDA maintains distinct pharmaceutical-medical device hybrid oversight for citrate-calcium balancing algorithms. Tokyo and Osaka university hospitals pilot portable rapid-deployment configurations for trauma resuscitation protocols.
United Kingdom
NHS England's critical care capacity expansion targets standardized renal support in London and Manchester academic centers. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines for new device approvals. The Oxford-Cambridge arc concentrates clinical research infrastructure for sepsis-associated acute kidney injury protocols.
France
ANSM oversight of dialysis device safety shapes product development priorities for Parisian and Lyon-based hospital networks. Regional health agencies in Île-de-France negotiate bundled procurement for integrated CRRT platforms with remote monitoring capabilities. The Strasbourg corridor anchors cross-border supply relationships with German Baden-Württemberg manufacturing clusters.
ICU-Acquired Acute Kidney Treatment Market Competitive Landscape
Top-tier vendors anchor high-acuity hospital contracts, while mid-scale specialists occupy membrane technology and regional service niches. The vendor base stratifies across integrated platform providers, hollow-fiber membrane specialists, and consumables-scale manufacturers. Strategic archetypes include technology licensors with patent moats, regional fabricators with government procurement relationships, and diversified medical device conglomerates with cross-selling infrastructure. Competitive moves concentrate on automated dosing precision capabilities and third-party clinical engineering service unbundling.
Among diversified medical technology conglomerates, Baxter International and Medtronic exemplify platform-integrated positioning, while Fresenius Medical Care occupies a scale-driven archetype in consumables supply. Asahi Kasei Medical represents the membrane specialization vector with hollow-fiber technology differentiation. B. Braun Melsungen AG and Nipro Corporation sit within regional European and Asian procurement channels respectively. These anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic actions.
| Leading Market Players |
|---|
| Asahi Kasei Medical |
| Medtronic |
| Baxter International |
| Infomed SA |
| Nipro Corporation |
| Fresenius Medical Care |
| Nikkiso Co. Ltd. |
| Medica S.p.A |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Premium automated CRRT platforms with integrated citrate-calcium balancing algorithms command three-to-five-fold price multiples over basic intermittent dialysis machines, with this bifurcation mapping directly onto supply chain configurations where membrane manufacturing concentrates in Japan and Germany while final system assembly localizes near major hospital procurement clusters in the United States and Bavaria.
Pricing Analysis
The bundled-versus-unbundled service split now defines competitive positioning across the ICU renal support landscape. Original equipment manufacturers face procurement departments that separate device acquisition from after-sales maintenance contracts, selecting third-party clinical engineering firms for preventive service. Three-tier pricing structure across premium automated systems, standard CRRT platforms, and economy intermittent machines reflects membrane biocompatibility grades and FDA clearance tiers. Pricing pressure stems from German regional purchasing cooperatives extracting service cost reductions through competitive tendering. Cost-conscious health systems in Southern Europe exhibit highest price sensitivity, while Japanese university hospitals prioritize automated anticoagulation precision over acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for dialyzer refurbishment and CRRT circuit remanufacturing remain underdeveloped, creating stranded asset risk for high-value consumables. Manufacturing gravity centers on Bad Homburg in Germany for dialysis circuit production, Tokyo and Osaka for hollow-fiber membrane fabrication, and the Southeast United States for antimicrobial catheter component assembly. Polysulfone and polyethersulfone resin supplies draw from petrochemical complexes in Belgium and Japan. Single-source vulnerability concentrates in specialized hollow-fiber spinning equipment. Distribution runs through regional hospital purchasing cooperatives in Germany and group purchasing organizations in the United States, with direct-to-hospital contracts dominating Japanese procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ICU-Acquired Acute Kidney Treatment market represents a late-cycle quality story as intensivist demand shifts decisively toward automated platforms with protocolized anticoagulation and integrated fluid balance surveillance.
For Market Incumbents: Hedge against service contract unbundling by developing subscription-based software update architectures and remote monitoring packages that embed recurring revenue streams independent of hardware replacement cycles. Deepen backward integration into hollow-fiber membrane production to defend margin position against Asahi Kasei Medical's technology licensing expansion. Prioritize FDA 510(k) pathway investments for next-generation hemofilters with adsorptive endotoxin capacity. For New Entrants and Emerging Players: Adsorptive membrane surfaces for sepsis-associated acute kidney injury present the most penetrable technology wedge, with tertiary ICU departments adopting polymethyl methacrylate filters at twice community hospital rates. Target Japan's super-aging prefectures of Aomori and Akita where automated anticoagulation systems face nursing ratio constraints and limited incumbent service infrastructure. Pursue hospital system partnerships emphasizing reduced ICU length-of-stay outcomes rather than device-centric value propositions. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR clinical evidence requirements extend market access timelines and strand subscale manufacturers without regulatory affairs capacity. Long-term viability favors platform-integrated vendors with software companion development capabilities and hospital system partnership depth over pure-play membrane specialists. Monitor PMDA reciprocity agreement evolution as the critical signal for European manufacturer entry into Japanese automated system procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Anchor high-acuity contracts through outcomes-based ICU length-of-stay reduction guarantees with German tertiary networks. |
| FDA Submission | Accelerate 510(k) clearance for antimicrobial catheter surfaces targeting Boston and Baltimore academic medical centers. |
| CE Marking Pathway | Navigate EU MDR clinical evidence requirements for hemofiltration platforms serving Bavarian hospital modernization programs. |
| Software Companion Development | Build citrate-calcium balancing algorithms that satisfy PMDA hybrid pharmaceutical-device oversight in Japanese super-aging prefectures. |
| Reimbursement Strategy | Align automated CRRT platform value metrics with NHS England critical care capacity expansion targets in Manchester and London. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and France, with primary inputs from each market combining structured interviews with intensivists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation through FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up demand modeling for CRRT device installations and consumables throughput triangulates against top-down market sizing from manufacturer revenue disclosures and trade flow analysis.
Granularity-level framing applies product type segmentation at the machine configuration level, delivery mode at automation intensity tiers, and end user at facility acuity classification across the projection horizon. CAGRs derive from installed base expansion rates and consumables consumption intensity by patient severity score. Forecast inputs incorporate federal hospital modernization program commitments in Germany, PMDA regulatory pathway evolution for anticoagulant-device combinations, and NHS England critical care capacity targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, intermittent hemodialysis substitution rates in cost-constrained health systems, and intensivist-nephrologist coordination protocol standardization. Practitioners should monitor PMDA reciprocity agreement negotiations, German regional purchasing cooperative tender outcomes, and FDA guidance evolution on dialysis device safety for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Chronic Kidney Disease Market
Nephrology
Renal Denervation Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Renal Anemia Treatment Market
Nephrology
End Stage Renal Disease Market
Nephrology
Proteinuria Treatment Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Kidney Transplant Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Hemodialysis Services Market
Nephrology
Plasmapheresis Market
Nephrology
Lupus Nephritis Treatment Market