
 Renal Artery Embolization Market | 2026-2036
Renal Artery Embolization Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Artery Embolization Market Analytics
Procedure support and imaging software subscriptions is shifting how vendors monetize renal artery embolization workflows beyond hardware sales. Boston Scientific Corporation leverages its interventional oncology portfolio to anchor premium positioning in embolization platforms. Medtronic sustains broad hospital system penetration through integrated catheter and navigation ecosystems. Cook Medical specializes in custom embolic coil configurations for complex renal anatomies.
Renal artery embolization denotes the percutaneous, image-guided occlusion of renal arterial supply using particulate agents, coils, or liquid sclerosants, typically performed under fluoroscopic or CT guidance with microcatheter delivery systems. The procedure serves primarily to devascularize renal tumors, manage traumatic hemorrhage, or reduce kidney volume prior to transplantation. Embolic agents command the largest product type share due to recurring consumption per procedure, while image-guided therapy represents the fastest-expanding technology segment as hybrid operating rooms proliferate. Hospitals absorb the majority of end-user value, though outpatient facilities gain traction for elective renal denervation adjuncts.
The FDA regulates embolic agents as combination devices or drugs depending on mechanism, while the EU MDR imposes stricter clinical evidence requirements on permanent implantable coils. ISO 13485 certification governs quality management for manufacturers serving both jurisdictions, creating compliance cost barriers for new entrants. Stakeholders must weigh reimbursement pathway clarity against capital requirements for next-generation biodegradable embolic platforms.
Market Dynamics
Hybrid operating room capital investment is compressing procedure timelines and redistributing value from standalone imaging centers toward integrated hospital campuses with interventional radiology infrastructure.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements for permanent implantable coils are accelerating documentation standards that favor established manufacturers with robust quality systems.
- Trauma center designation expansion:Level I trauma centers across the United States are embedding interventional radiology teams for renal hemorrhage control, embedding embolization into standard trauma protocols.
- Bioresorbable polymer platforms:Next-generation embolic materials that degrade post-procedure are reducing long-term implant burden and opening pediatric and transplant-prep indications previously closed to permanent agents.
Market Restraints
- Platinum-iridium alloy supply concentration:Coil manufacturing depends on refined precious metal feedstocks concentrated in South African and Russian mining operations, exposing producers to geopolitical input volatility.
- Interventionalist training pipeline constraints:The specialized dual competency in diagnostic angiography and microcatheter navigation limits procedure expansion in community hospital settings without fellowship-trained staff.
- Reimbursement pathway fragmentation:CMS coding distinctions between diagnostic and therapeutic angiography create prior authorization friction that delays elective tumor embolization scheduling.
Strategic Opportunities
- Outpatient-based lab expansion:Ambulatory surgical centers in Texas and Florida are securing state waivers for complex interventional oncology procedures, bypassing hospital facility fees.
- Contrast-induced nephropathy protocols:CO2 angiography and gadolinium-sparing imaging workflows are creating competitive differentiation for centers serving chronic kidney disease populations.
- Navigation-robotics convergence:Electromagnetic tracking integrated with pre-procedural 3D segmentation is reducing fluoroscopy time and operator radiation exposure in high-volume centers.
Industry Challenges
- Cross-modality credentialing complexity:Staff must maintain simultaneous privileges in CT, MRI, and angiography suites, multiplying continuing education requirements and scheduling conflicts.
- Single-use device waste regulations:California and EU extended producer responsibility frameworks are forcing re-evaluation of coil packaging and sterilization workflows without compromising aseptic technique.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Artery Embolization Market |
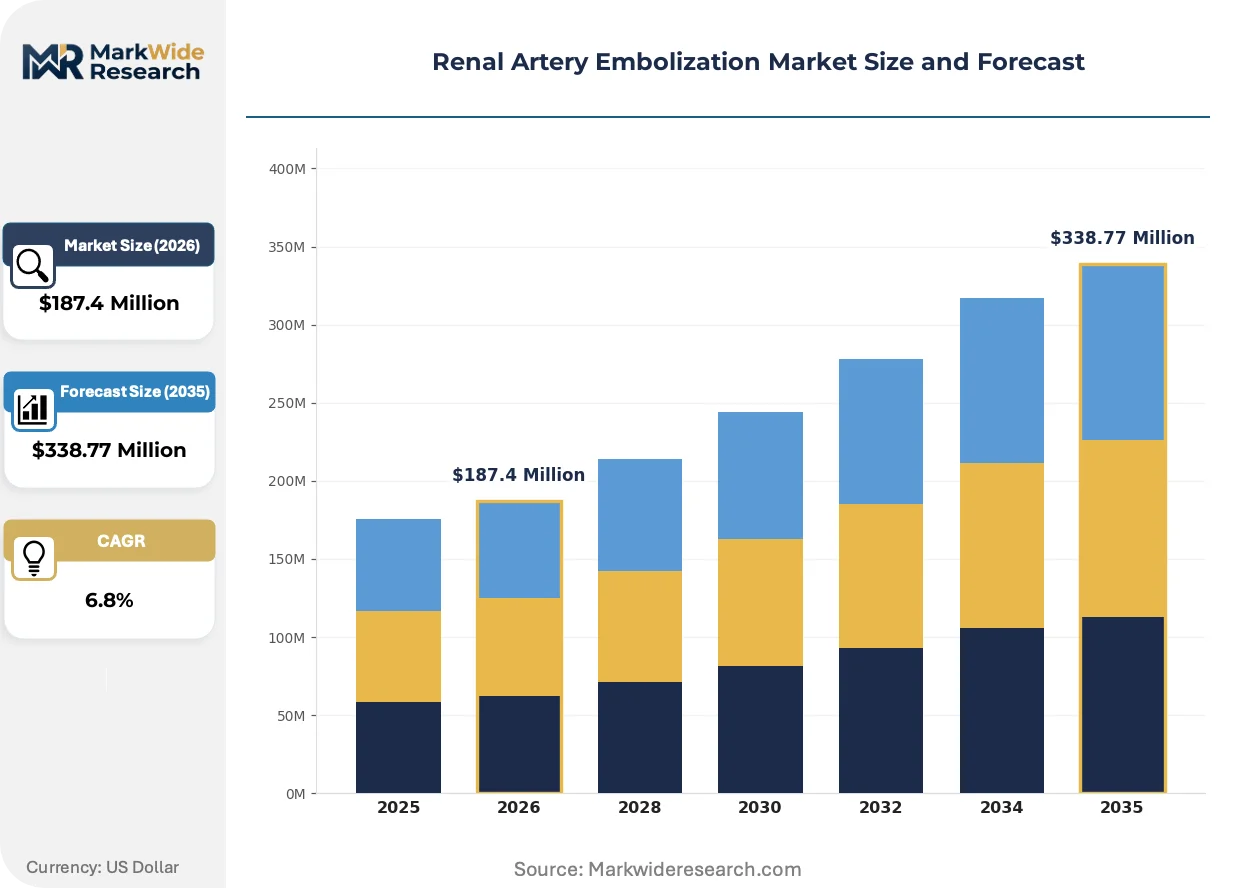
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embolic Agents, Coils, Gelatin Sponge, Alcohol End User: Hospitals, Clinics, Academic Institutions, Outpatient Facilities Procedure Type: Transcatheter Embolization, Embolization Techniques, Minimally Invasive Surgery, Surgical Intervention Technology: Image-Guided Therapy, Fluoroscopy, CT Imaging, MRI |
| Companies Covered | Boston Scientific Corporation, Medtronic, Cook Medical, Stryker Corporation, Terumo Corporation, Penumbra, Inc., Merit Medical Systems, Inc., Johnson & Johnson, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Artery Embolization Market Evolving Landscape
Image-guided therapy platforms are absorbing software functionality that previously required separate PACS workstations, collapsing procurement decisions into single-vendor ecosystem commitments.
Microcatheter-directed drug-eluting bead embolization is overtaking conventional bland particle injection in academic medical centers treating hepatocellular carcinoma with renal extension. Interventional oncologists at tertiary centers are adopting calibrated-dose platforms that pair irinotecan or doxorubicin loading with calibrated particle size. This convergence of locoregional chemotherapy and mechanical occlusion is compressing the traditional boundary between embolization and systemic therapy planning.
FDA breakthrough device designation pathways for biodegradable embolic agents are compressing premarket review timelines for platforms demonstrating complete resorption within 90 days. Manufacturers submitting renal artery-specific indications are leveraging predicate device strategies from peripheral vascular embolization clearances. The agency's evolving stance on combination product classification is creating regulatory clarity that accelerates chemistry-manufacturing-controls documentation for polymer-based platforms.
Hospital procurement committees are consolidating vendor contracts around bundled embolization procedure kits that include microcatheters, guidewires, and embolic agents under single-source agreements. This purchasing pattern is displacing the historical practice of separate negotiations with coil, particle, and delivery device suppliers. The shift is most visible in integrated delivery networks across the Midwestern United States, where standardization committees are mandating approved device lists to reduce inventory complexity and capture volume-based rebates.
Renal Artery Embolization Market Segmentation
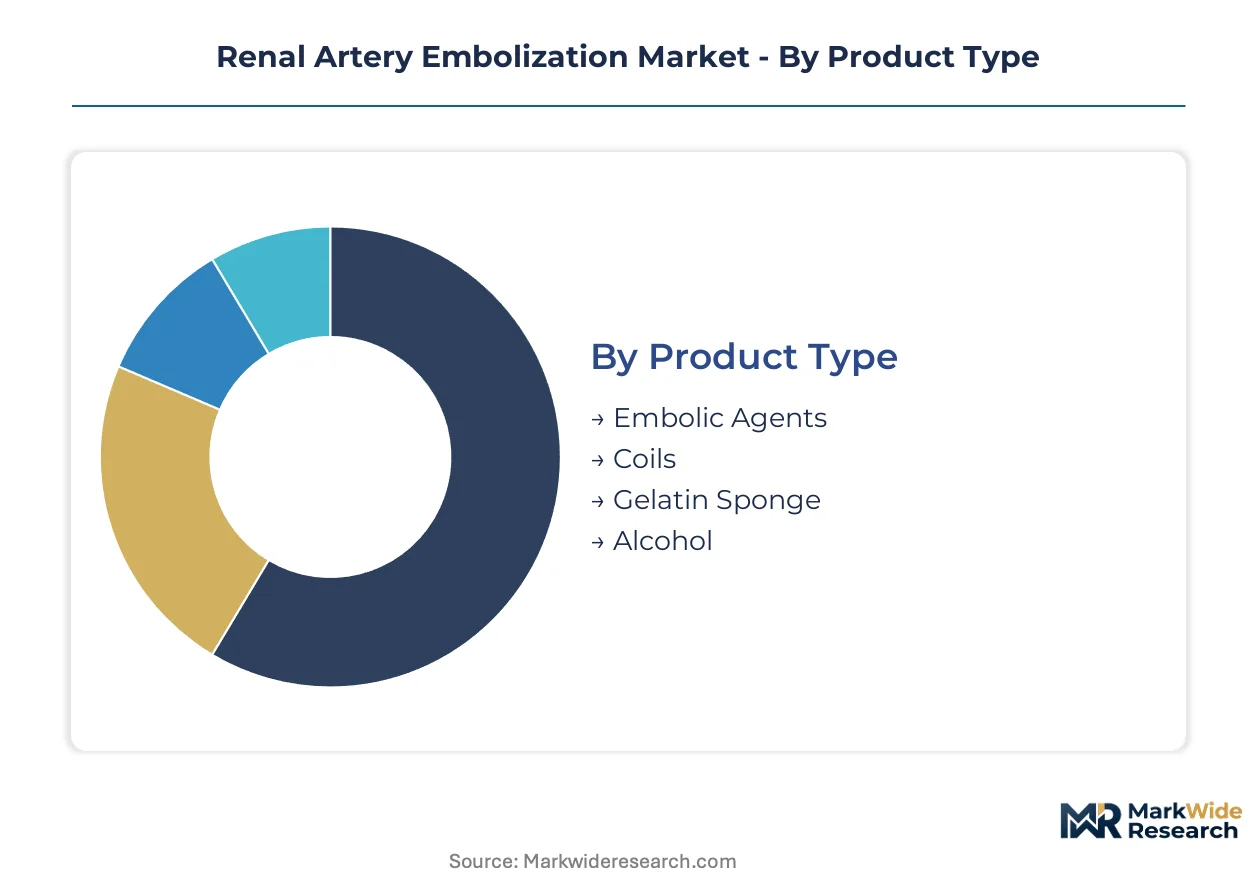
Renal artery embolization vendors configure product portfolios around procedural workflow economics, where consumable recurrence rates and capital equipment depreciation cycles determine account profitability. Segmentation clarity enables targeted positioning across academic medical centers with hybrid operating rooms versus community hospitals with basic angiography suites.
Product Type:
Capital intensity varies sharply across this category, with coil manufacturing requiring precious metal refining infrastructure and sterile polymer synthesis demanding cleanroom investment.
- Embolic Agents:Particulate polyvinyl alcohol and trisacryl gelatin microspheres constitute the workhorse materials for tumor devascularization. Demand clusters at high-volume interventional oncology programs in the United States, where recurring consumption per procedure sustains pricing power against commodity alternatives.
- Coils:Platinum-iridium and nitinol constructs deliver permanent mechanical occlusion for traumatic hemorrhage control. Massachusetts General Hospital and Cleveland Clinic anchor North American demand for complex detachable coil configurations that command premium placement fees.
- Gelatin Sponge:Absorbable temporary embolic derived from porcine collagen serves pre-transplant kidney volume reduction protocols.
- Alcohol:Absolute ethanol provides low-cost chemical ablation for select angiomyolipoma cases in resource-constrained settings.
Embolic agents absorb the bulk of installed capacity; coils are expanding most quickly through trauma center designation mandates.
End User:
Procurement authority concentrates differently across this dimension, with integrated delivery networks centralizing purchasing for hospitals while individual physicians drive clinic-level decisions.
- Hospitals:Tertiary and quaternary centers with interventional radiology residency programs perform the majority of complex tumor embolizations. Texas Medical Center and Mayo Clinic Rochester anchor procedural volume through embedded hybrid operating room infrastructure.
- Outpatient Facilities:Ambulatory surgical centers in Florida and Arizona are securing state waivers for elective renal denervation adjuncts, bypassing hospital facility fees. Regulatory arbitrage between site-of-service payment differentials accelerates capital deployment to freestanding settings.
- Clinics:Urology and interventional radiology group practices handle follow-up imaging and patient triage.
- Academic Institutions:NIH-funded research hospitals conduct biodegradable agent trials under FDA breakthrough pathways.
Hospitals retain dominant reimbursement capture; outpatient facilities are gaining share fastest through site-neutral payment policy shifts.
Procedure Type:
Volume distribution tracks operator training pipeline constraints, with fellowship-trained interventionalists concentrating in academic settings that favor advanced techniques.
- Transcatheter Embolization:Microcatheter-directed delivery under fluoroscopic guidance constitutes the standard approach for renal tumor and trauma indications. Johns Hopkins and Stanford Health Care anchor demand for steerable microcatheter platforms that reduce procedure time.
- Minimally Invasive Surgery:Laparoscopic-assisted embolization hybrid procedures address complex hilar anatomy. University of Michigan and UCLA Medical Center drive adoption through combined urology-interventional radiology service lines.
- Embolization Techniques:Bland, chemoembolization, and radioembolization protocols segment by oncologic indication.
- Surgical Intervention:Open conversion remains reserved for hemodynamic instability refractory to endovascular rescue.
Transcatheter embolization commands the majority of procedural volume; minimally invasive surgery is climbing the fastest through hybrid operating room proliferation.
Technology:
Margin profiles diverge across this category, with hardware platforms generating depreciation schedules against software subscriptions that yield recurring revenue.
- Image-Guided Therapy:Integrated angiography-CT-MRI platforms with 3D roadmapping and needle guidance represent the capital frontier. Siemens Healthineers and GE Healthcare compete for hybrid operating room installations at NewYork-Presbyterian and Cedars-Sinai.
- Fluoroscopy:Digital subtraction angiography remains the workhorse modality for real-time catheter navigation. Community hospitals in the Midwest and Southeast maintain installed bases that limit near-term replacement cycles.
- CT Imaging:Cone-beam CT integration enables immediate post-procedure perfusion assessment.
- MRI:MR-conditional devices and real-time thermometry support emerging ablation-embolization combination protocols.
Fluoroscopy retains the largest installed base; image-guided therapy is gaining share fastest through replacement demand at flagship academic centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Medical Center anchors procedural volume through embedded hybrid operating room infrastructure that compresses embolization timelines for renal tumor indications.
United States
Level I trauma center designation expansion embeds interventional radiology teams for renal hemorrhage control across major academic medical centers. FDA breakthrough device pathways for biodegradable embolic agents compress premarket review timelines for polymer-based platforms. Cleveland Clinic and Massachusetts General Hospital anchor demand for complex detachable coil configurations.
Germany
EU MDR clinical evidence mandates accelerate documentation standards that favor established manufacturers with robust quality systems. ISO 13485 certification governs quality management for manufacturers serving both EU and US jurisdictions. Siemens Healthineers competes for hybrid operating room installations at flagship centers in Munich and Berlin.
Japan
PMDA oversight shapes product development timelines for embolic agent classifications and image-guided device clearances. METI industrial policy supports navigation-robotics convergence in high-volume centers. Tokyo and Osaka medical clusters drive adoption of electromagnetic tracking integrated with pre-procedural segmentation.
China
NMPA regulation of combination devices creates compliance cost barriers for new entrants seeking renal artery-specific indications. Dual carbon goals pressure single-use device waste re-evaluation without compromising aseptic technique. Beijing and Shanghai tertiary hospitals absorb the majority of end-user value through centralized procurement.
United Kingdom
NHS England site-neutral payment policy shifts redistribute value toward outpatient facilities for elective renal denervation adjuncts. MHRA post-market surveillance aligns with EU MDR stricter requirements on permanent implantable coils. London teaching hospitals maintain simultaneous privileges across CT, MRI, and angiography suites.
Renal Artery Embolization Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the renal artery embolization landscape. The vendor base concentrates around diversified medical technology conglomerates with interventional oncology portfolios and specialized embolization device manufacturers with precious metal refining infrastructure. Three archetypes dominate: integrated catheter-navigation ecosystems, custom coil configuration specialists, and image-guided therapy platform vendors. Competitive moves center on bundled procedure kit consolidation and hybrid operating room installation partnerships.
Within the integrated ecosystem tier, Boston Scientific Corporation and Medtronic occupy positions anchored by broad hospital system penetration and interventional oncology portfolio depth. Cook Medical exemplifies the specialized configuration archetype through its focus on complex renal anatomies. These three entities represent distinct competitive vectors—platform breadth, navigation integration, and anatomical customization—that define procurement committee evaluation criteria across integrated delivery networks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Cook Medical |
| Stryker Corporation |
| Terumo Corporation |
| Penumbra, Inc. |
| Merit Medical Systems, Inc. |
| Johnson & Johnson |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Premium coil configurations for complex renal anatomies command placement fees that standard particulate agents cannot match, bifurcating procurement decisions between academic medical centers with hybrid operating room infrastructure and community hospitals constrained by basic angiography suites. This tier divergence concentrates pricing power with manufacturers possessing precious metal refining capabilities while compressing margins for commodity embolic suppliers serving cost-sensitive outpatient facilities.
Pricing Analysis
Margin tightening in standard particulate tiers reflects procurement committee consolidation around bundled procedure kits that collapse separate negotiations for microcatheters, guidewires, and embolic agents into single-source agreements. Three-tier pricing structure across premium, standard, and economy levels tracks FDA breakthrough designation status, ISO 13485 certification grade, and volume scale commitments through integrated delivery networks. Cost-down pressure on absorbable temporary embolics accelerates because state waiver expansions for ambulatory surgical centers bypass hospital facility fees. Community hospitals in the Midwest and Southeast exhibit highest price sensitivity due to limited interventional radiology residency programs, while quaternary centers at Texas Medical Center and Mayo Clinic Rochester absorb premium placement fees with least negotiation leverage.
Supply Chain Analysis
Reverse logistics for explanted platinum-iridium coils remain underdeveloped, with remanufacturing flows concentrated among specialized precious metal reclaimers rather than original equipment manufacturers. Manufacturing draws from South African and Russian mining operations for refined platinum-iridium feedstocks, sterile polymer synthesis cleanrooms in Germany and the United States, and nitinol shape-memory alloy production anchored in Japanese and Chinese facilities. Single-source vulnerability in precious metal refining exposes coil producers to geopolitical input volatility without qualified secondary suppliers. Distribution runs through hospital procurement committees at integrated delivery networks, GPO contracts managers, and direct-to-hospital agreements for hybrid operating room installation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into precious metal refining and sterile polymer synthesis represents the decisive competitive lever as manufacturers seek captive supply of coil feedstocks and embolic agent raw materials.
For Market Incumbents: Deploy hybrid operating room installation partnerships to lock in multi-year consumable commitments from flagship academic centers. Consolidate vendor contracts around bundled procedure kits before outpatient facility expansion erodes hospital capture rates. Counter regulatory arbitrage from state waiver expansions by embedding subscription-based imaging software that creates switching costs. Threat from biodegradable agent platforms with FDA breakthrough designation compresses timelines for permanent coil manufacturers to demonstrate long-term implant burden advantages. For New Entrants and Emerging Players: Enter via CO2 angiography and gadolinium-sparing imaging workflows targeting chronic kidney disease populations underserved by contrast-dependent incumbents. White-space concentration in Florida and Arizona ambulatory surgical centers offers lowest barrier to state waiver procurement. Bioresorbable polymer platforms for pediatric and transplant-prep indications remain penetrable given limited predicate device competition. Go-to-market angle should emphasize electromagnetic tracking integration with pre-procedural 3D segmentation to reduce fluoroscopy time. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medical technology conglomerates seeking interventional oncology portfolio depth. Long-term viability hinges on navigation-robotics convergence platforms that collapse procedure timelines and operator radiation exposure. Acquisition target archetype: specialized coil configuration manufacturers with precious metal refining infrastructure and ISO 13485 certification serving EU MDR clinical evidence mandates. Signal to watch is FDA evolving stance on combination product classification for polymer-based platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates premarket review timelines for biodegradable embolic agents demonstrating complete resorption. |
| EU MDR Clinical Evidence Pathway | Fulfills stricter post-market surveillance requirements for permanent implantable coils across German and UK markets. |
| Hospital System Partnership | Secures multi-year bundled procedure kit contracts with Texas Medical Center and Mayo Clinic Rochester. |
| Software Companion Development | Integrates 3D roadmapping and needle guidance functionality into image-guided therapy platforms at Cedars-Sinai. |
| Reimbursement Strategy | Clarifies CMS coding distinctions between diagnostic and therapeutic angiography to reduce prior authorization friction. |
Research Methodology
Multi-period observation of procedural volume trends, regulatory submission timelines, and hybrid operating room installation rates anchored the trend analysis, supplemented by interviews with interventional radiologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare claims data. Bottom-up triangulation of consumable recurrence rates per procedure converged with top-down assessment of capital equipment depreciation cycles across integrated delivery networks.
Input-output matrices modeled volume and value projections across product type, end user, procedure type, and technology segments throughout the forecast period. CAGRs were derived from installed base replacement demand, trauma center designation expansion trajectories, and site-neutral payment policy shift impacts. Industry-specific forecast inputs included interventionalist training pipeline constraints and bioresorbable polymer platform adoption curves at NIH-funded research hospitals.
Revisions become necessary when EU MDR clinical evidence mandates extend documentation timelines, platinum-iridium supply disruptions materialize, or CMS reimbursement pathway restructuring alters site-of-service economics. Forecasts reflect assumptions regarding continued hybrid operating room capital deployment and sustained FDA breakthrough designation velocity for biodegradable agents. Practitioners should monitor PMDA oversight developments in Japan and NMPA combination device rulings in China for early signals of regulatory convergence or divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Nephrotic Syndrome Market
Nephrology
Blood Dialyzer Market
Nephrology
Hemodialysis Services Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
US Dialysis Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Proteinuria Treatment Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
US Dialysis Centers Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Kidney/Renal Function Test Market