
 Global Automated Border Control Market | 2026-2036
Global Automated Border Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Border Control Market Intelligence
The consolidation of component suppliers in Asia is recalibrating the supply chain for European system integrators. This shift pressures major providers to secure key hardware like advanced sensors and processors. Thales Group leverages its extensive defense and aerospace portfolio to integrate secure solutions. IDEMIA specializes in augmented identity technologies for government clients, while NEC Corporation competes with its advanced facial recognition algorithms and global project experience.
Automated border control systems use biometric data to autonomously verify a traveler's identity against their electronic travel documents. These systems must comply with standards like ICAO 9303 for interoperability. Their primary purpose is to enhance security and streamline passenger flow at international transit points. While eGates represent the most deployed product format, facial recognition technology is displacing legacy fingerprint systems due to its contactless nature and speed.
Regulatory frameworks fundamentally shape system design and data management protocols. The EU's GDPR imposes strict rules on handling personal biometric data, while directives from the US Department of Homeland Security mandate biometric exit programs. ISO standards on biometric data interchange formats ensure cross-border compatibility. Stakeholders must continuously navigate the evolving balance between national security objectives and individual privacy protections.
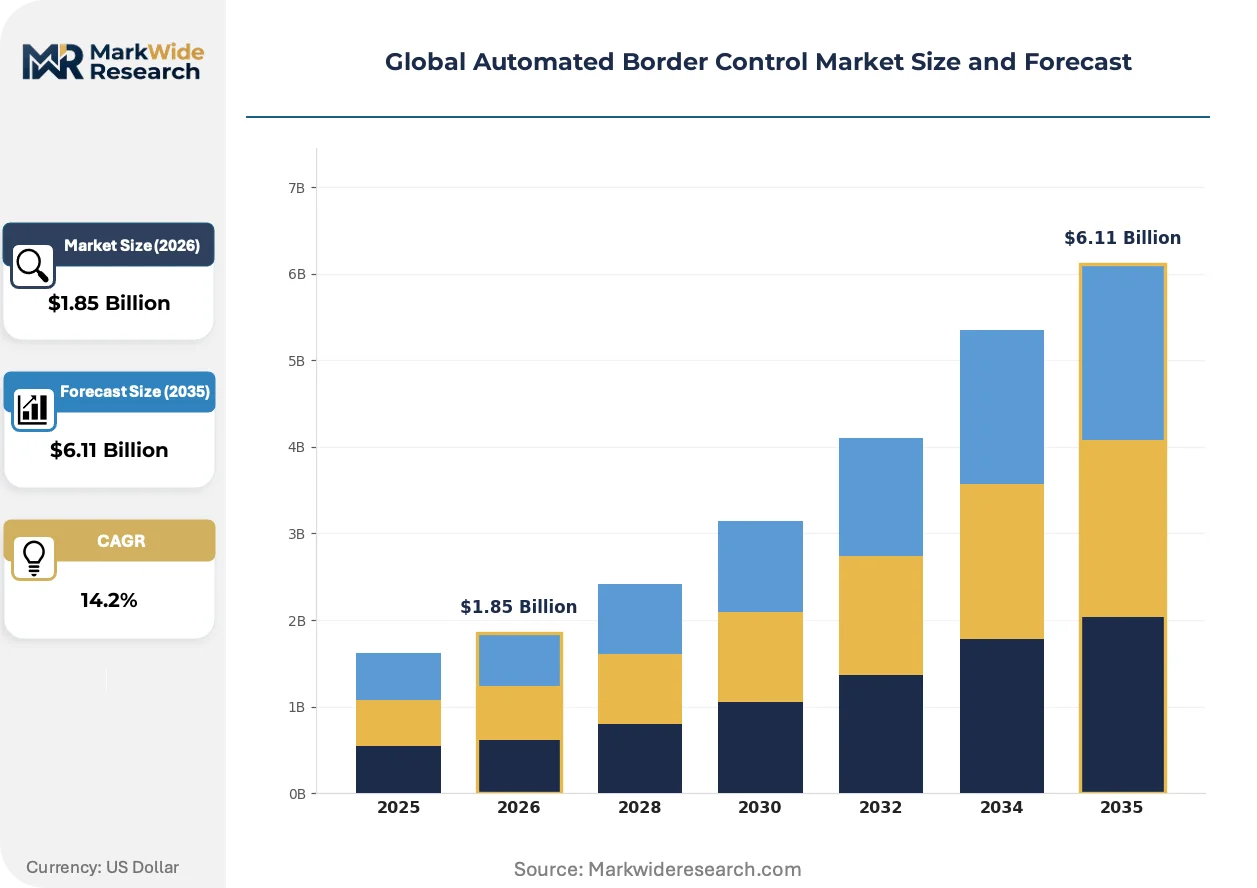
Market Dynamics
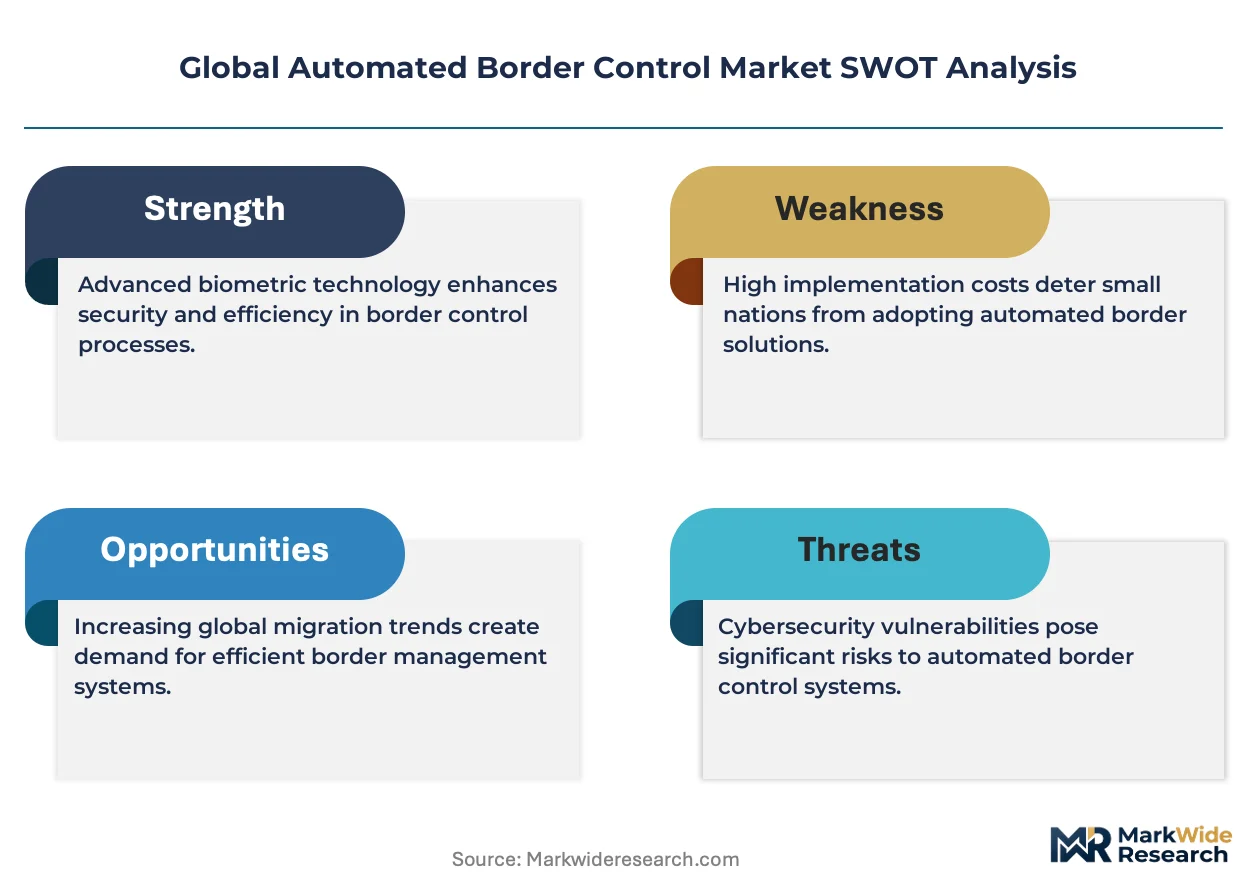
The drive for enhanced passenger throughput in high-traffic airports is accelerating the adoption of automated systems. This trend is coupled with government security mandates, such as biometric exit programs, creating a dual-sided demand for efficient and secure border control solutions.
Growth Catalysts
- Multi-modal Biometrics:The fusion of facial and iris recognition improves verification accuracy and resilience to spoofing, helping systems meet stringent ICAO 9303 interoperability standards for electronic travel documents.
- Airport Infrastructure Upgrades:Major aviation hubs in the UAE and Singapore are embedding automated gates into new terminal designs, driving large-scale, integrated deployments from the ground up.
- Government Security Mandates:The US Department of Homeland Security's biometric entry-exit requirement compels the installation of compliant systems across air, land, and sea ports of entry.
Market Restraints
- High Initial Capex:The significant cost of eGates, biometric scanners, and underlying IT infrastructure presents a substantial financial barrier for airport operators and government agencies, slowing deployment.
- Biometric Mismatch Rates:Environmental factors like poor lighting or changes in traveler appearance can cause false rejections, requiring manual overrides that diminish the system's efficiency gains.
- Data Privacy Compliance:The EU's GDPR imposes strict rules on processing personal biometric data, increasing the complexity and cost of system design and data management protocols.
Strategic Opportunities
- Land and Sea Border Modernization:Extending automated verification beyond airports to high-volume land crossings and cruise terminals represents a major growth area for system vendors.
- Digital Travel Credentials (DTC):The emergence of ICAO-compliant DTCs stored on mobile devices enables new solutions for a completely contactless, self-service passenger journey from curb to gate.
- Emerging Aviation Markets:Greenfield airport projects in Southeast Asia and South America provide opportunities to install fully integrated, next-generation border control systems without legacy constraints.
Industry Challenges
- Legacy System Integration:Connecting new biometric solutions with disparate, often proprietary, government databases and existing airport IT infrastructure remains a primary technical hurdle.
- Inter-Agency Data Sharing Protocols:Establishing secure and standardized protocols for real-time biometric data exchange between different national security agencies is a complex political and technical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Border Control Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Readers, eGates, Kiosks, Surveillance Cameras, Access Control Systems Technology: Facial Recognition, Fingerprint Scanning, Iris Recognition, RFID, Voice Recognition Application: Airport Terminals, Seaports, Land Borders, Immigration Checkpoints, Customs Inspection End User: Government Agencies, Law Enforcement, Border Security Forces, Customs Officials, Immigration Authorities |
| Companies Covered | Vision-Box, Secunet Security Networks AG, Thales Group, Gunnebo Group, Atos SE, IDEMIA, SITA, Accenture, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Border Control Market Strategic Shifts & Innovations
The pursuit of a seamless, touchless passenger journey is reshaping system design toward integrated identity management platforms. This evolution occurs within a tightening web of data governance rules that dictate how biometric information is collected, stored, and shared.
Multi-modal biometric platforms combine facial and iris recognition into a single, streamlined verification process for travelers. Airport operators in key global hubs are adopting these systems to manage higher passenger volumes without requiring physical terminal expansions. This integrated approach is absorbing the functions of separate manual document checks, creating a more fluid and automated passenger flow through the border.
The European Union's Entry/Exit System (EES) regulation mandates the capture of biometric data from non-EU nationals at all external Schengen borders. This directive creates a large, synchronized procurement cycle as member states must deploy compliant automated border control infrastructure. System vendors are most affected, needing to certify their eGates and kiosks against the EES technical specifications.
Airport authorities are shifting procurement from standalone hardware components to acquiring end-to-end identity management solutions as a service. This model transfers the responsibility for system maintenance, software updates, and performance guarantees from the airport to the technology provider. This trend is most prominent in North American and European airports seeking to control technology lifecycle costs and ensure compliance.
Global Automated Border Control Market Segmentation
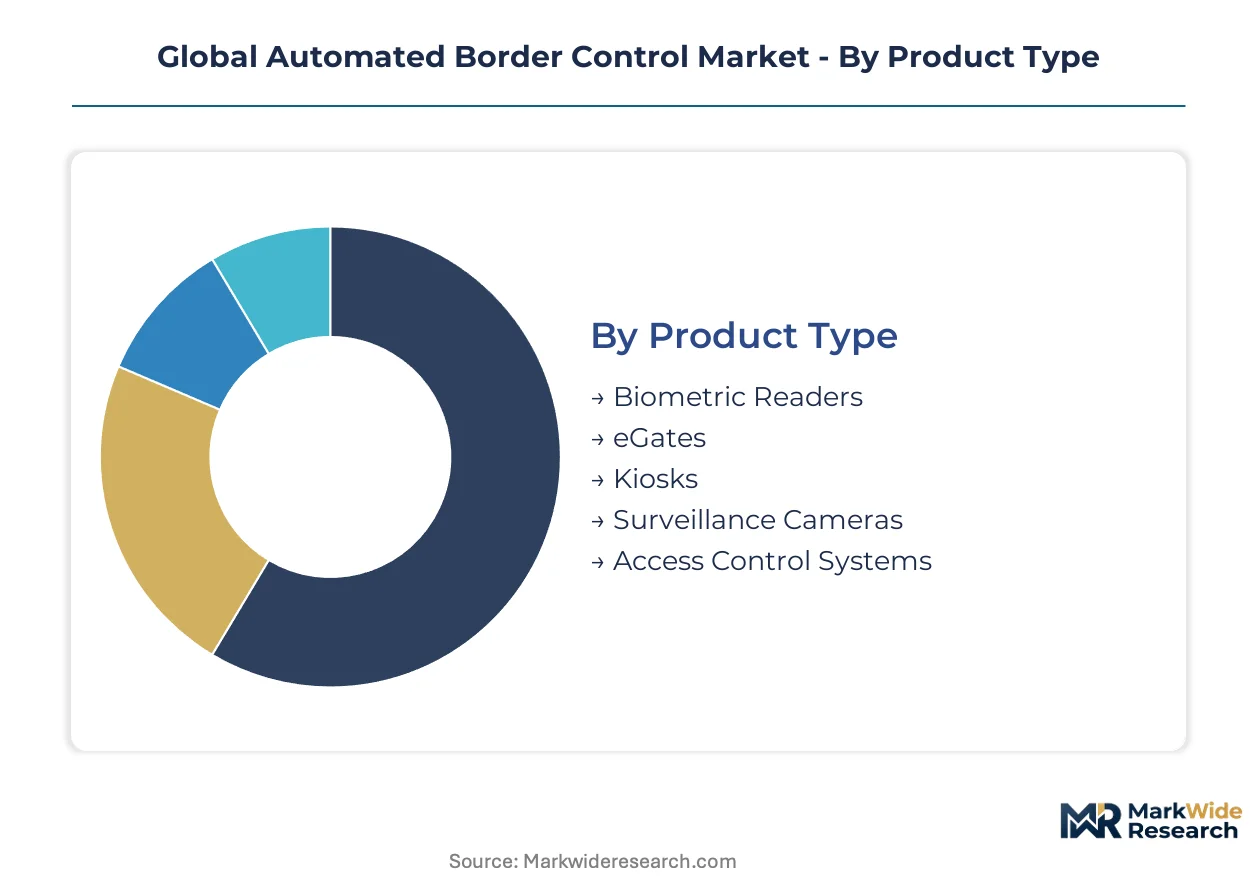
The segmentation of the automated border control market reflects the diverse operational requirements and technological capabilities necessary for securing international transit points. Understanding these distinct categories clarifies how different solutions address specific security mandates and passenger flow challenges across various deployment environments.
Product Type:
Compliance with international standards like ICAO 9303 dictates design and functionality for automated border control product types.
- eGates:These automated gates use biometrics and electronic travel documents for self-service identity verification, allowing expedited passage. High-traffic airport terminals in the UAE and Singapore concentrate demand, improving passenger throughput.
- Kiosks:Self-service terminals facilitate biometric enrollment, data capture, and document scanning, often preceding an eGate. Major US aviation hubs utilize kiosks for biometric entry-exit programs, ensuring DHS compliance.
- Biometric Readers:Devices capture unique biological characteristics such as fingerprints or faces for identity confirmation.
- Surveillance Cameras:High-resolution cameras monitor border control areas, providing visual data for security and operational oversight.
- Access Control Systems:These manage and restrict entry to sensitive zones within border facilities using biometric and credential checks.
Leading the category by volume: eGates. Growing fastest: Kiosks.
Technology:
The selection of biometric technology depends on the application environment, balancing speed, accuracy, and contactless operation.
- Facial Recognition:This technology identifies individuals by analyzing unique facial features from live feeds or images, offering contactless and rapid verification. Global airport environments concentrate demand, displacing legacy fingerprint systems due to speed.
- Iris Recognition:This method uses iris patterns for highly accurate and secure identification, integrated into multi-modal systems. Major aviation hubs in Singapore deploy iris recognition with facial biometrics to meet ICAO 9303 interoperability standards.
- Fingerprint Scanning:This traditional biometric technology captures and matches unique ridge patterns on a person's fingers.
- RFID:Radio-frequency identification systems automatically identify and track tags attached to objects or travel documents.
- Voice Recognition:This technology analyzes unique vocal characteristics for identity verification, enabling hands-free authentication.
Evolution towards multi-modal biometrics highlights increasing integration of facial and iris recognition for enhanced verification.
Application:
Each application area presents unique operational requirements, from high-volume passenger throughput in airports to robust solutions at land borders.
- Airport Terminals:Applications streamline passenger processing, enhancing security and managing high volumes of international travelers via eGates and biometric kiosks. Major global aviation hubs, including the United States, prioritize these for efficiency and biometric exit compliance.
- Land Borders:Automated systems manage vehicle and pedestrian traffic, performing identity checks and ensuring immigration and customs compliance. Modernization of land crossings, particularly along the US-Canada border, drives significant vendor growth.
- Seaports:Automated systems manage passenger and crew movements for cruise lines and cargo, ensuring maritime security.
- Immigration Checkpoints:Dedicated areas verify traveler identities and entry eligibility using biometric data against national databases.
- Customs Inspection:Automated systems assist officials in verifying goods and passenger declarations, enhancing security screening.
Extending automated verification beyond airports to land and sea borders represents a strategic opportunity.
End User:
The diverse mandates of end-user organizations shape specific features and integration requirements for automated border control systems.
- Government Agencies:Entities like the US Department of Homeland Security procure and deploy automated border control systems to fulfill national security objectives and implement biometric entry-exit programs. Decisions involve large-scale, integrated solutions requiring high security.
- Border Security Forces:These personnel operate and rely on automated systems for real-time identity verification and threat detection at international crossing points. They require robust, user-friendly interfaces integrated with existing databases for operational efficiency.
- Law Enforcement:Police and security forces use automated biometric tools for identity checks and criminal identification.
- Customs Officials:These authorities use automated systems to verify traveler identities and declarations for efficient customs processing.
- Immigration Authorities:Agencies leverage automated border control to manage legal entry and enforce immigration laws via biometrics.
Effective inter-agency data sharing protocols are critical for maximizing security and efficiency across all end-user segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major aviation hubs globally anchor the deployment of automated border control systems. The drive for enhanced passenger throughput, coupled with stringent security mandates, fuels demand for advanced biometric solutions. This concentration of demand is particularly evident in key international transit points.
United States
The United States drives significant demand for automated border control systems in its high-traffic airports, particularly for efficiency and security. The US Department of Homeland Security's biometric entry-exit program mandates the installation of compliant systems across ports of entry. Major US aviation hubs like Atlanta and Chicago integrate kiosks for biometric enrollment and identity verification.
United Arab Emirates
New terminal designs and high passenger volumes propel the adoption of automated gates in the United Arab Emirates. National security objectives drive significant investment in advanced systems for international transit points. Dubai International Airport and other UAE hubs embed automated gates from the ground up to streamline passenger flow.
Singapore
Singaporean aviation authorities prioritize a seamless passenger journey and ICAO 9303 interoperability standards. Singapore's immigration authorities focus on multi-modal biometrics for secure and efficient processing at its borders. Changi Airport leads in deploying integrated facial and iris recognition systems to manage high volumes of international travelers.
Germany
European Union directives, such as the Entry/Exit System (EES) regulation, mandate biometric data capture at external Schengen borders, impacting Germany. The EU's GDPR imposes strict rules on handling personal biometric data, increasing system design complexity. Frankfurt Airport and other German international airports are deploying compliant automated border control infrastructure.
China
China's extensive airport expansion projects and focus on smart border initiatives create substantial opportunities for automated systems. National policies support the development and deployment of advanced biometric technologies for border security. Major Chinese cities like Beijing and Shanghai are investing in automated border control solutions for their international airports.
Global Automated Border Control Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated identity management platforms for broader application. The market exhibits a tiered structure, with large defense and aerospace conglomerates alongside specialized biometric technology firms and IT service providers. Strategic partnerships and technology licensing are prevalent competitive moves, allowing companies to expand their solution portfolios and geographic reach. Geographic expansion into emerging aviation markets also represents a significant growth strategy for many vendors.
Among major global technology providers, Thales Group, a French multinational, exemplifies a conglomerate leveraging its extensive defense and aerospace portfolio to integrate secure solutions across various sectors. IDEMIA, also a French company, occupies a position as a specialist in augmented identity technologies, primarily serving government clients with robust biometric verification systems. Japan-based NEC Corporation sits within the tier of technology firms known for advanced facial recognition algorithms and global project experience, often anchoring large-scale automated border control deployments in diverse international markets.
| Leading Market Players |
|---|
| Vision-Box |
| Secunet Security Networks AG |
| Thales Group |
| Gunnebo Group |
| Atos SE |
| IDEMIA |
| SITA |
| Accenture |
| NEC Corporation |
| Others |
Cost & Logistics Intelligence
Government security mandates, such as the US Department of Homeland Security's biometric exit program, necessitate compliant system deployments. This demand-side pressure compels suppliers to focus on certified, secure solutions, which often influences pricing for advanced biometric components and integrated platforms.
Pricing Analysis
Warranty and service bundling often differentiates offerings, with higher-tier packages including comprehensive maintenance and software updates. Project-based contracts dominate the market, reflecting the bespoke nature of large-scale infrastructure deployments. Customization level and the inclusion of after-sales service are primary price differentiation drivers. Pricing pressure stems from intense competition among system integrators for major government and airport contracts. Airport operators exhibit high price sensitivity due to significant initial capital expenditure requirements.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly mandated by government buyers to mitigate supply chain risks. The supply chain for advanced sensors and processors concentrates in Asia, particularly from manufacturers in China, South Korea, and Japan. Key dependencies include specialized biometric modules, high-resolution cameras, and secure processing units. Single-source vulnerability for advanced biometric sensors represents a structural risk. Distribution runs through direct sales channels to government agencies and airport authorities, often involving complex system integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated border control market is undergoing a significant technology-transition phase. Facial recognition technology is rapidly displacing legacy fingerprint systems, driving demand for new infrastructure and integrated platforms.
For Market Incumbents: Anchor existing client relationships by offering comprehensive identity management solutions as a service. Integrate multi-modal biometrics capabilities to counter emerging specialized biometric firms focusing on niche applications. Invest in R&D for advanced AI-driven anomaly detection to stay ahead of evolving security threats. Secure strategic partnerships with software providers to enhance integration with diverse airport IT infrastructures.
For New Entrants and Emerging Players: Launch via strategic partnerships with established system integrators to access large-scale government procurement cycles. Target land and sea border modernization projects, which represent an underpenetrated segment compared to airports. Focus on developing ICAO-compliant Digital Travel Credentials (DTC) integration solutions for a contactless passenger journey. Offer flexible, modular solutions that can integrate with existing legacy systems in emerging aviation markets.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented capabilities in identity management software. Long-term viability is strong, driven by persistent government security mandates and passenger throughput demands. Target specialized software firms with robust data privacy compliance expertise or manufacturers of unique biometric sensor technologies. Accelerated adoption of Digital Travel Credentials in major aviation hubs is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate systems for a seamless, unified identity management experience across transit points. |
| Strategic Partnership | Expands solution portfolios and geographic reach, particularly for complex, large-scale deployments. |
| Geographic Expansion | Captures opportunities in greenfield airport projects and land border modernization in new regions. |
| Product Launch | Introduces next-generation biometric readers and eGates with enhanced accuracy and speed capabilities. |
| Service Model Shift | Transforms procurement from capital expenditure to operational expenditure for airport authorities. |
Research Approach
Independent corroboration across primary interviews, secondary research, and quantitative modeling underwrites the qualitative findings in this study. The methodology involved in-depth discussions with airport operators, government agency officials, system integrators, and biometric technology developers. Secondary data sources included ICAO documents, EU EES technical specifications, national border control agency reports, and industry association publications. Bottom-up and top-down triangulation ensured robust market sizing and segmentation across all parameters.
The forecast window was anchored to historical reference periods, establishing a consistent baseline for future projections. The analytical framework modeled market dynamics across product type, technology, application, end-user, and regional regulatory mandates. Compound annual growth rates were derived through a comprehensive analysis of historical trends and projected future demand. Passenger traffic growth rates and government budget allocations for security served as key industry-specific forecast inputs.
Geopolitical shifts, data privacy regulations, and technological breakthroughs are the dominant revision risks for market projections. Forecasts reflect assumptions documented regarding market evolution and regulatory stability. Deviation in government spending priorities or a major shift in biometric technology standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
India Access Control Hardware Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
RFID Locks Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Port Security Systems Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Canada Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Asia-Pacific Card-Based Access Control Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Europe Smart Lock Market
Access Control Systems
Electronic Cylinder Lock Credentials Market