
 Global Industrial Access Control Market | 2026-2036
Global Industrial Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Access Control Market Outlook
Biometric-grade authentication is reorganizing procurement priorities across heavy industry. ASSA ABLOY leverages its electromechanical lock portfolio to dominate European manufacturing sites. Siemens anchors automation-integrated access decisions through its building management ecosystem. Honeywell International Inc. competes on cyber-physical convergence, embedding encryption directly into reader hardware.
Industrial access control comprises credential verification systems, biometric sensors, and networked door controllers engineered to IEC 60947-5-1 electrical endurance standards, designed to restrict unauthorized entry to hazardous production zones and safeguard intellectual property within operational technology environments. Biometric technology leads in high-assurance deployments where fingerprint and facial recognition eliminate credential sharing, while RFID sustains volume across logistics yards requiring rapid vehicle throughput. Cloud-based deployment is accelerating fastest among multi-site manufacturers seeking centralized policy administration, though on-premises systems retain margin pools in defense and critical infrastructure governed by air-gapped security mandates.
FDA facility security directives, OSHA machine-guarding provisions, and EU AI Act biometric governance collectively tighten compliance thresholds for authentication systems deployed in pharmaceutical cleanrooms and automated warehouses. IEC 62443 certification is becoming a non-negotiable filter for vendor selection in energy and chemical sectors. Stakeholders must weigh cloud migration speed against emerging biometric data localization requirements before committing to platform architecture.
Market Dynamics
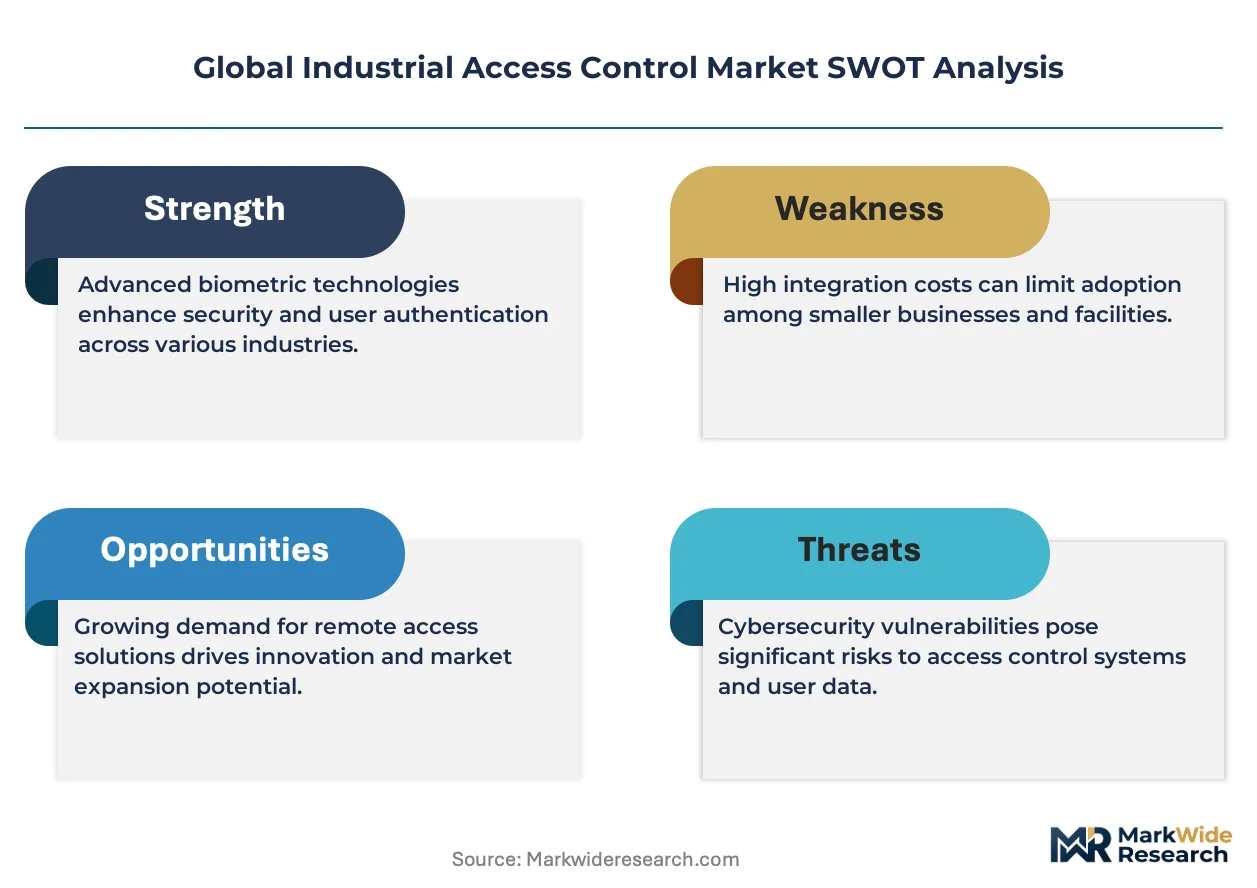
Cloud migration is fragmenting vendor control as multi-site manufacturers demand centralized policy administration while defense contractors enforce air-gapped mandates, creating parallel procurement channels with diverging technical specifications and margin structures.
Growth Catalysts
- NIST Cybersecurity Framework:US critical infrastructure operators face escalating authentication mandates for operational technology environments, accelerating hardware refresh cycles in energy and chemical facilities.
- Data center physical security:Hyperscale cloud providers are expanding perimeter budgets as server density increases, driving demand for biometric-grade reader systems at facility entry points.
- German industrial automation clusters:BASF chemical complexes and automotive manufacturing sites require hardened IEC 62443-certified systems, concentrating procurement volume in Rhine-Ruhr and Baden-Württemberg production zones.
Market Restraints
- Semiconductor supply concentration:Reader controller chipsets depend on Taiwan and South Korea foundry capacity, exposing lead times to geopolitical disruption and allocation rationing.
- Biometric data localization mandates:EU AI Act governance and emerging national data sovereignty laws are fragmenting cloud architecture decisions, forcing redundant regional deployments.
- Legacy electromechanical installed base:Decades of mechanical lock infrastructure in heavy industry creates high retrofit friction and extended replacement cycles.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for electronics and pharmaceutical production are creating greenfield facility demand for integrated access-building management systems.
- Mobile credential convergence:Smartphone-based authentication paired with Bluetooth Low Energy readers is displacing physical card programs in logistics and warehousing applications.
- Saudi giga-project construction:NEOM and Red Sea tourism developments specify biometric perimeter systems at scale, attracting vendor localization commitments.
Industry Challenges
- IEC 62443 certification timelines:Multi-stage security level validation for energy sector deployments extends sales-to-revenue recognition to 18-24 months, compressing working capital efficiency.
- Cyber-physical integration expertise:Scarce engineering talent capable of bridging IT network security and OT device hardening limits deployment velocity for converged systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Access Control Market |
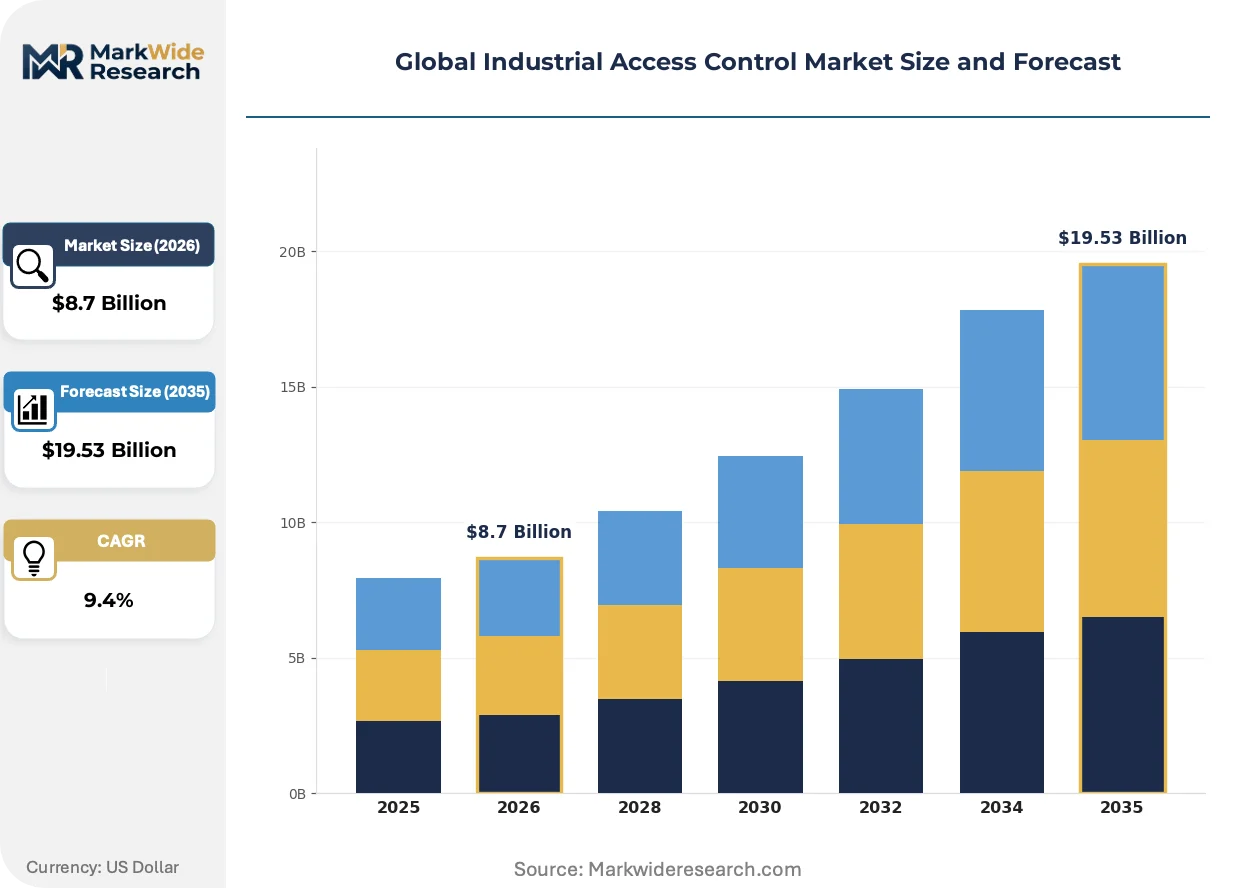
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric, RFID, Smart Cards, Keypads Application: Facility Management, Data Centers, Manufacturing Plants, Corporate Offices End User: Government, Healthcare, Education, Logistics Deployment: On-premises, Cloud-based, Hybrid, Mobile |
| Companies Covered | ASSA ABLOY, Honeywell International Inc., Johnson Controls, Allegion plc, Bosch Security Systems, Schneider Electric, Siemens, dormakaba Group, HID Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Access Control Market Strategic Shifts
Authentication hardware is splitting into two performance tiers as cloud-native architectures diverge from hardened on-premises mandates, reshaping R&D allocation and vendor specialization strategies.
Edge-computing access controllers with embedded encryption engines are bifurcating the reader market. High-assurance deployments in chemical and nuclear facilities adopt these devices to eliminate network-traversal risks for credential data. Volume logistics and warehousing segments retain centralized controller architectures to minimize per-door hardware costs. The technology is bifurcating vendor portfolios into cyber-physical specialists versus cost-optimized hardware suppliers.
EU AI Act biometric governance is tightening algorithmic transparency requirements for facial recognition systems deployed in European pharmaceutical cleanrooms and automated warehouses. Industrial buyers now demand documentation of training data provenance and bias testing protocols before procurement approval. German chemical operators and French automotive plants are prioritizing vendors with pre-submitted conformity assessments to compress deployment timelines.
Subscription-based access-as-a-service models are displacing perpetual license structures among mid-market manufacturers with limited IT security staffing. Channel partners in the US Midwest and Southeast are bundling hardware, software, and remote monitoring into multi-year contracts. Food processing and beverage packaging verticals show strongest uptake, preferring operational expenditure treatment for compliance-sensitive infrastructure.
Global Industrial Access Control Market Segmentation
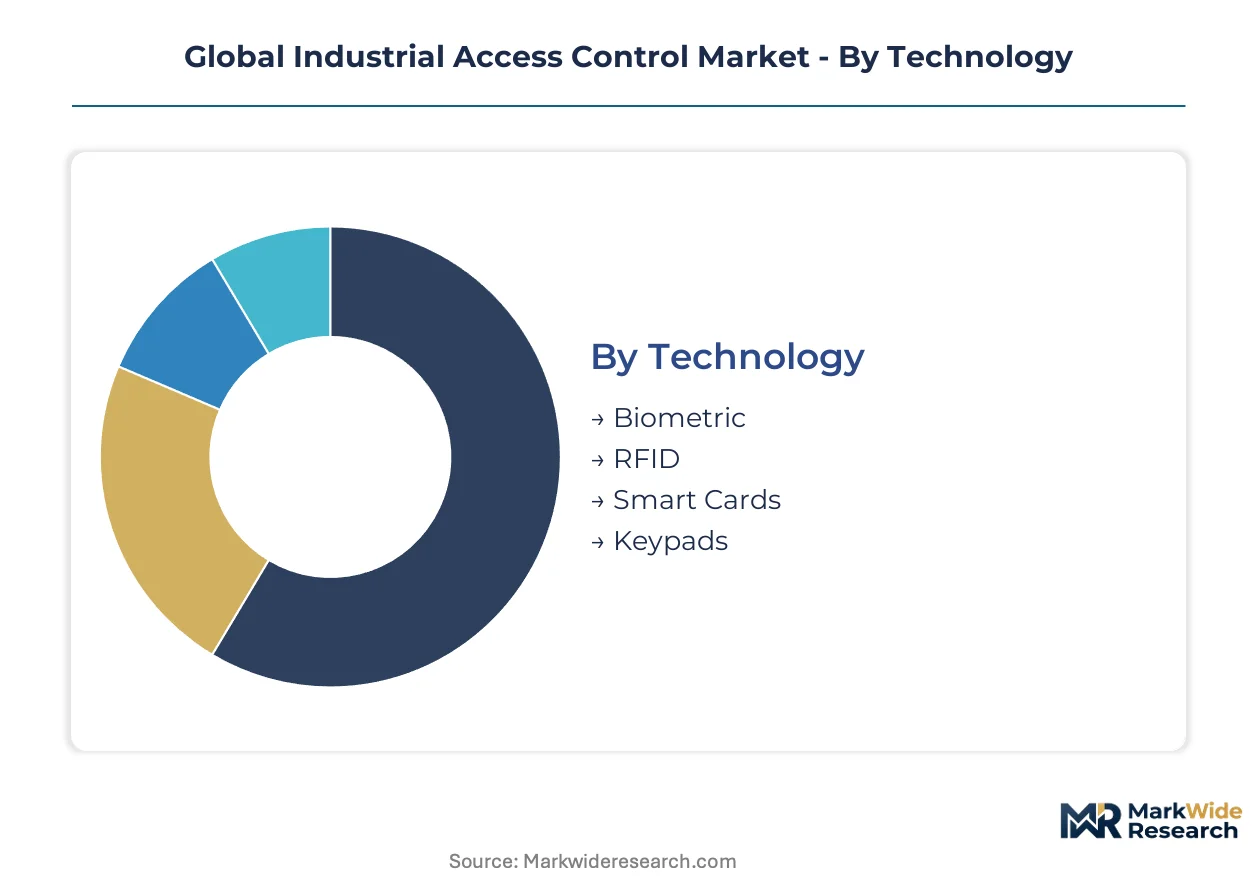
Technology choices in industrial access control determine compliance posture and total cost of ownership across hazardous environments. Procurement committees weigh biometric assurance against RFID throughput depending on facility risk profiles and workforce mobility patterns.
Technology:
Biometric systems face substitution pressure from mobile credential platforms in logistics corridors, while RFID defends its installed base through vehicle-gate integration and legacy compatibility.
- Biometric:Fingerprint and facial recognition sensors eliminate credential sharing in pharmaceutical cleanrooms and nuclear containment zones. German chemical operators under EU AI Act mandates prioritize vendors with documented algorithmic transparency and bias testing protocols.
- RFID:Passive and active radio-frequency tags enable rapid vehicle throughput at logistics yard gates without requiring line-of-sight authentication. Manufacturing plants in India's PLI scheme corridors specify UHF RFID for automated warehouse entry systems.
- Smart Cards:Contact and contactless credential formats persist in corporate office retrofits where physical card programs retain administrative familiarity.
- Keypads:PIN-entry systems defend niche positions in utility substations requiring authentication without credential infrastructure.
RFID anchors the volume base while biometric technology gains share at the steepest rate.
Application:
Cost tiering separates high-assurance facility management from standardized manufacturing plant deployments.
- Facility Management:Integrated building management systems coordinate access with HVAC and fire safety protocols through IEC 62443-certified controllers. Data centers in Northern Virginia and Frankfurt expand perimeter budgets as server density increases.
- Data Centers:Hyperscale cloud providers deploy multi-factor authentication at every entry point with biometric-grade readers and mantrap configurations. NIST cybersecurity frameworks mandate hardware refresh cycles for critical infrastructure operators.
- Manufacturing Plants:Hardened perimeter systems protect intellectual property in operational technology environments with air-gapped security mandates.
- Corporate Offices:Subscription-based access-as-a-service models displace perpetual licenses among mid-market manufacturers with limited IT security staffing.
Facility management commands premium pricing while data center applications expand most quickly.
End User:
Customer type determines procurement channel and certification requirements.
- Government:Defense contractors enforce air-gapped mandates with multi-stage IEC 62443 security level validation extending sales cycles.
- Healthcare:FDA facility security directives tighten authentication thresholds for pharmaceutical cleanrooms.
- Education:Campus-wide systems balance credential convenience with budget constraints across distributed building portfolios.
- Logistics:Mobile credential convergence with Bluetooth Low Energy readers displaces physical card programs in warehousing applications.
Logistics drives volume throughput while government segments impose the strictest compliance filters.
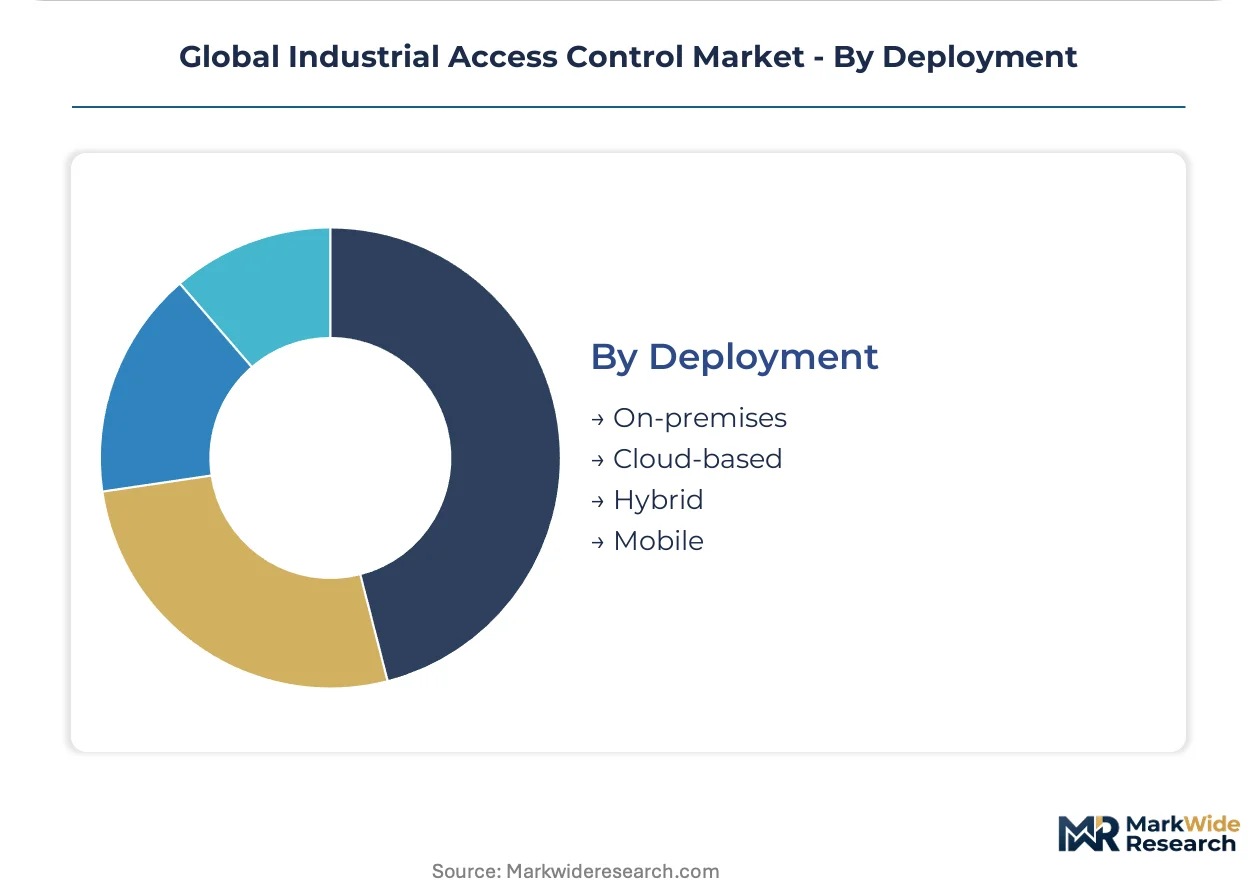
Deployment:
Maturity curves separate established on-premises architectures from emerging cloud-native alternatives.
- On-premises:Air-gapped controllers retain margin pools in defense and energy sectors governed by data sovereignty requirements.
- Cloud-based:Centralized policy administration attracts multi-site manufacturers seeking operational expenditure treatment for compliance infrastructure.
- Hybrid:Edge-computing controllers with embedded encryption engines bifurcate the reader market between cyber-physical specialists and cost-optimized suppliers.
- Mobile:Smartphone-based authentication paired with Bluetooth Low Energy readers creates redundant regional deployments under biometric data localization mandates.
On-premises deployment retains the installed base while cloud-based architectures climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity, driving procurement toward cost-optimized RFID and mobile credential platforms. German and US operators absorb premium pricing for IEC 62443-certified biometric systems without volume elasticity. Chinese demand splits between state-mandated security upgrades and private manufacturing cost discipline.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives biometric-grade reader procurement at unprecedented density. NIST Cybersecurity Framework mandates force energy sector operators into hardware refresh cycles for operational technology environments. Defense contractors in California and Texas maintain air-gapped on-premises architectures with multi-stage security validation protocols.
Germany
BASF chemical complexes and automotive manufacturing clusters in Baden-Württemberg require hardened perimeter systems with embedded encryption engines. EU AI Act biometric governance tightens algorithmic transparency requirements for facial recognition deployments in pharmaceutical cleanrooms. Rhine-Ruhr industrial zones concentrate IEC 62443 certification demand among electromechanical lock vendors.
China
State-owned energy and chemical facilities mandate security upgrades under national critical infrastructure protection directives. MIIT standards for industrial control system authentication accelerate domestic controller chipset development. Yangtze River Delta manufacturing corridors deploy hybrid cloud-on-premises architectures to satisfy data sovereignty requirements.
India
PLI scheme incentives for electronics and pharmaceutical production create greenfield demand for integrated access-building management systems. BIS certification requirements for security equipment tighten vendor qualification thresholds. Gujarat and Maharashtra manufacturing corridors specify UHF RFID for automated warehouse entry at volume scale.
Saudi Arabia
NEOM and Red Sea tourism giga-projects specify biometric perimeter systems at construction scale exceeding any previous regional deployment. SFDA facility security directives for pharmaceutical production align with EU-equivalent authentication thresholds. Riyadh-based system integrators demand vendor localization commitments as contract prerequisites.
Global Industrial Access Control Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure with limited overlap between premium biometric specialists and volume RFID suppliers. Consolidation pressure concentrates among electromechanical incumbents seeking cyber-physical capabilities, while cloud-native entrants fragment the mid-market with subscription pricing. Three archetypes dominate: European industrial automation conglomerates with building management ecosystems, specialized electromechanical security groups with lock manufacturing heritage, and North American cyber-physical convergence specialists. Competitive moves center on IEC 62443 certification pre-submission to compress German sales cycles and mobile credential platform partnerships to displace physical card programs.
Within the automation-integrated tier, Siemens and Schneider Electric exemplify the building management ecosystem approach, bundling access control with HVAC and fire safety protocols through certified controllers. ASSA ABLOY and dormakaba Group occupy positions among European electromechanical specialists, leveraging lock manufacturing heritage to anchor physical security decisions at industrial sites. Honeywell International Inc. represents the cyber-physical convergence archetype, embedding encryption directly into reader hardware to bridge IT network security and OT device hardening requirements.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Honeywell International Inc. |
| Johnson Controls |
| Allegion plc |
| Bosch Security Systems |
| Schneider Electric |
| Siemens |
| dormakaba Group |
| HID Global Corporation |
| Others |
Value Chain & Pricing Dynamics
Edge-computing controller substitution for centralized architectures is redrawing supply geography toward Taiwan and South Korea foundries while compressing hardware margins and elevating software attach rates as the primary profit pool.
Pricing Analysis
After-sales service contracts and remote monitoring subscriptions now drive lifetime value beyond initial hardware deployment. Three-tier pricing structure across premium IEC 62443-certified, standard enterprise-grade, and economy RFID-basic levels separates defense contractors from logistics operators. Cost compression in economy tiers is intensifying because Indian and Southeast Asian buyers demand volume-scale discounts without certification premiums. Logistics and warehousing segments exhibit acute price sensitivity, while German chemical operators absorb premium pricing for embedded encryption engines without volume elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability fluctuations at Busan and Shanghai are elevating inbound logistics costs for reader controller chipsets. Semiconductor fabrication concentrates in Taiwan and South Korea, with secondary controller assembly in China and Mexico. Raw material dependencies include silicon wafers, rare-earth magnets for electromechanical locks, and copper for PoE-enabled readers. Single-source vulnerability in Taiwan foundry capacity exposes lead times to geopolitical disruption. Distribution runs through system integrators in Riyadh, Frankfurt, and Dallas-Fort Worth who bundle hardware with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial access control is restructuring as a service-attach opportunity where subscription-based remote monitoring and compliance-as-a-service layers expand faster than hardware shipments, rewarding vendors who front-load recurring revenue architecture.
For Market Incumbents: Shield installed base relationships through IEC 62443 pre-certification investments that compress German sales cycles and create switching costs against cloud-native entrants. Deepen backward integration into controller chipset design to reduce Taiwan foundry dependency. Prioritize mobile credential platform partnerships to displace physical card programs before emerging players capture logistics retrofit volume. For New Entrants and Emerging Players: IEC 62443 certification fast-track through German notified bodies unlocks BASF and automotive cluster procurement committees currently dominated by ASSA ABLOY and Siemens. Target India's PLI scheme corridors where greenfield electronics and pharmaceutical facilities lack legacy electromechanical infrastructure. Pursue access-as-a-service positioning with operational expenditure treatment for mid-market food processing verticals underserved by perpetual license incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electromechanical specialists seeking cyber-physical capabilities to defend against automation-integrated conglomerates. Five-to-ten year viability hinges on cloud-native architecture migration speed versus on-premises margin pool persistence. Monitor IEC 62443 certification queue lengths as inflection indicator for German market access velocity and working capital efficiency compression.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Fast-Track | German chemical operators demand pre-submitted conformity assessments to compress 18-24 month validation timelines. |
| Mobile Credential Platform Integration | Bluetooth Low Energy reader pairings displace physical card programs in logistics and warehousing applications. |
| Edge-Computing Controller Development | Embedded encryption engines eliminate network-traversal risks for credential data in nuclear and chemical facilities. |
| Access-as-a-Service Subscription Launch | Operational expenditure treatment attracts mid-market manufacturers with limited IT security staffing in food processing. |
| Vendor Localization Commitment | Riyadh-based system integrators require Saudi-based support infrastructure for NEOM and Red Sea giga-project contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with physical security directors, OT cybersecurity engineers, and facility procurement managers at industrial sites, combined with secondary validation against SEC filings, customs trade records, IEC certification databases, and hyperscaler data center capex disclosures. Bottom-up triangulation across facility-level deployment data and top-down reconciliation against vendor revenue disclosures anchored volume and value estimates.
Across the projection horizon, the analytical framework modeled technology substitution curves, deployment architecture migration rates, and certification timeline compression effects. Segmentation dimensions included authentication modality, deployment model, end-user vertical, and regional regulatory cluster. CAGRs were derived from fitted adoption curves incorporating NIST framework mandate acceleration and EU AI Act biometric governance compliance costs.
Underlying assumptions cover sustained Taiwan foundry capacity allocation, stable NIST and IEC regulatory trajectory, and linear cloud migration speed among multi-site manufacturers, with deviation risk concentrated in geopolitical semiconductor disruption and biometric data localization mandate fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
GCC Home Security Systems Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Global Commercial Security System Market
Access Control Systems
Electronic Cylinder Lock Credentials Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
United Kingdom Access Control Market
Access Control Systems
Automated Barriers and Bollards Market