
 Europe Airport Passenger Screening Systems Market | 2026-2036
Europe Airport Passenger Screening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airport Passenger Screening Systems Market Foresight
France is tilting toward next-generation passenger screening infrastructure with major deployment commitments at Paris-Charles de Gaulle. Smiths Detection leverages its computed tomography portfolio to anchor supply relationships across French hub airports. L3Harris Technologies sustains its position through millimeter wave body scanner installations at high-throughput terminals. CEIA specializes in walk-through metal detection systems and competes on certification depth under EASA protocols.
Europe airport passenger screening systems comprise integrated security architectures combining X-ray machines, body scanners, explosives detectors, and metal detectors with detection thresholds measured in parts per billion for trace contraband. These systems serve the primary commercial purpose of threat interception at aviation access points while maintaining passenger flow rates above 600 persons per hour per lane. Computed tomography technology leads product type transitions as airports replace legacy 2-D X-ray cabin baggage systems with 3-D volumetric reconstruction platforms. Millimeter wave body scanners represent the fastest-growing technology segment, driven by privacy-compliant passive screening architectures that eliminate physical pat-down requirements. Threat detection applications command premium positioning within the application matrix, reflecting heightened EU focus on insider risk and evolving explosive device concealment methods.
EASA security regulations, the EU Aviation Security Regulation 2015/1998, and national civil aviation authorities in Germany, France, and Italy collectively mandate minimum detection performance standards and certification renewal cycles for deployed screening equipment. REACH compliance and CE marking requirements additionally constrain material selection and electromagnetic emissions profiles for manufactured systems. Stakeholders must monitor the EU AI Act's emerging classification framework for automated threat recognition algorithms, as algorithmic decision-making in passenger screening faces pending conformity obligations that will reshape procurement specifications and vendor liability structures.
Market Dynamics
Computed tomography cabin baggage scanners are compressing replacement cycles across European hub airports as EASA mandates drive hardware refresh timelines. Frankfurt, Munich, and Paris-Charles de Gaulle terminals now prioritize 3-D volumetric reconstruction platforms over legacy 2-D X-ray architectures.
Growth Catalysts
- EU Aviation Security Regulation 2015/1998:Mandatory detection performance standards force systematic equipment upgrades at Category A airports. Certification renewal cycles accelerate procurement frequency for millimeter wave and CT systems.
- Hub airport traffic density:Frankfurt and Munich terminals process passenger volumes exceeding 600 persons per hour per lane. Throughput requirements justify premium screening infrastructure investments.
- Computed tomography technology maturation:3-D volumetric reconstruction platforms eliminate liquid removal requirements. Passenger experience improvements reduce checkpoint congestion during peak scheduling windows.
Market Restraints
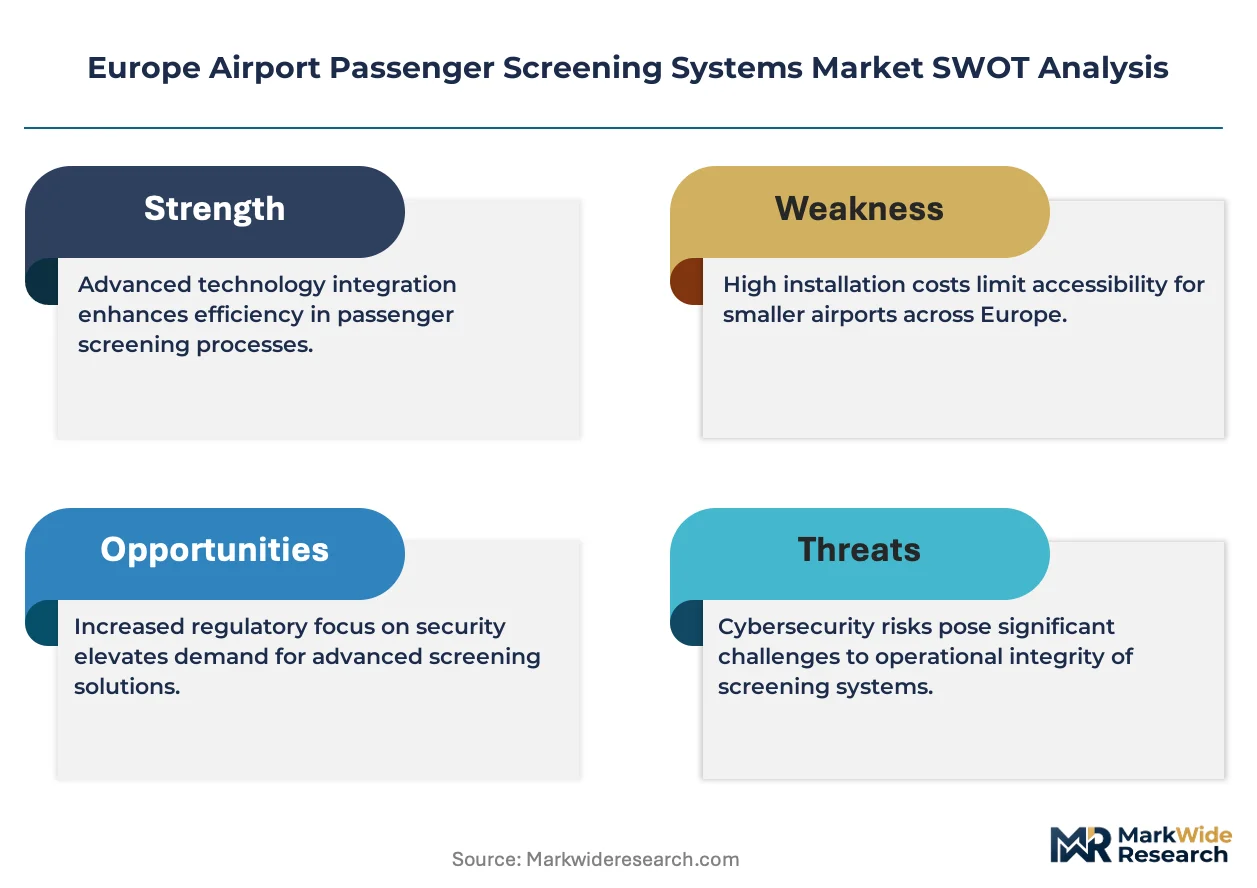
- Neodymium and specialized sensor supply concentration:Rare earth processing dependencies constrain millimeter wave scanner production scaling. European downstream manufacturers face input bottlenecks from concentrated upstream geographies.
- REACH compliance material constraints:Electromagnetic shielding compounds face restricted substance thresholds. Alternative material qualification timelines extend product development cycles by 18-24 months.
- Passive millimeter wave technical limitations:Current architectures struggle with layered clothing penetration in cold-climate operations. Detection confidence thresholds degrade against novel concealment geometries.
Strategic Opportunities
- Italian secondary airport modernization:Milan Malpensa and Rome Fiumicino lag German and French deployment rates. Terminal expansion programs create procurement windows for integrated screening architectures.
- EU AI Act algorithmic classification:Automated threat recognition systems face pending conformity obligations. First-mover vendors capturing certification precedence will reshape procurement specifications.
- Millimeter wave and biometric convergence:Identity verification integration with passive screening architectures enables seamless passenger flow. Combined platforms reduce lane staffing requirements while maintaining detection thresholds.
Industry Challenges
- Explosives trace detection calibration expertise:Parts-per-billion threshold maintenance requires specialized technician training. Talent scarcity in analytical chemistry functions constrains operational readiness at regional airports.
- Legacy 2-D X-ray integration complexity:Hold baggage systems and cabin baggage platforms operate on incompatible software architectures. Middleware development for unified command centers demands capital allocation without immediate throughput gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airport Passenger Screening Systems Market |
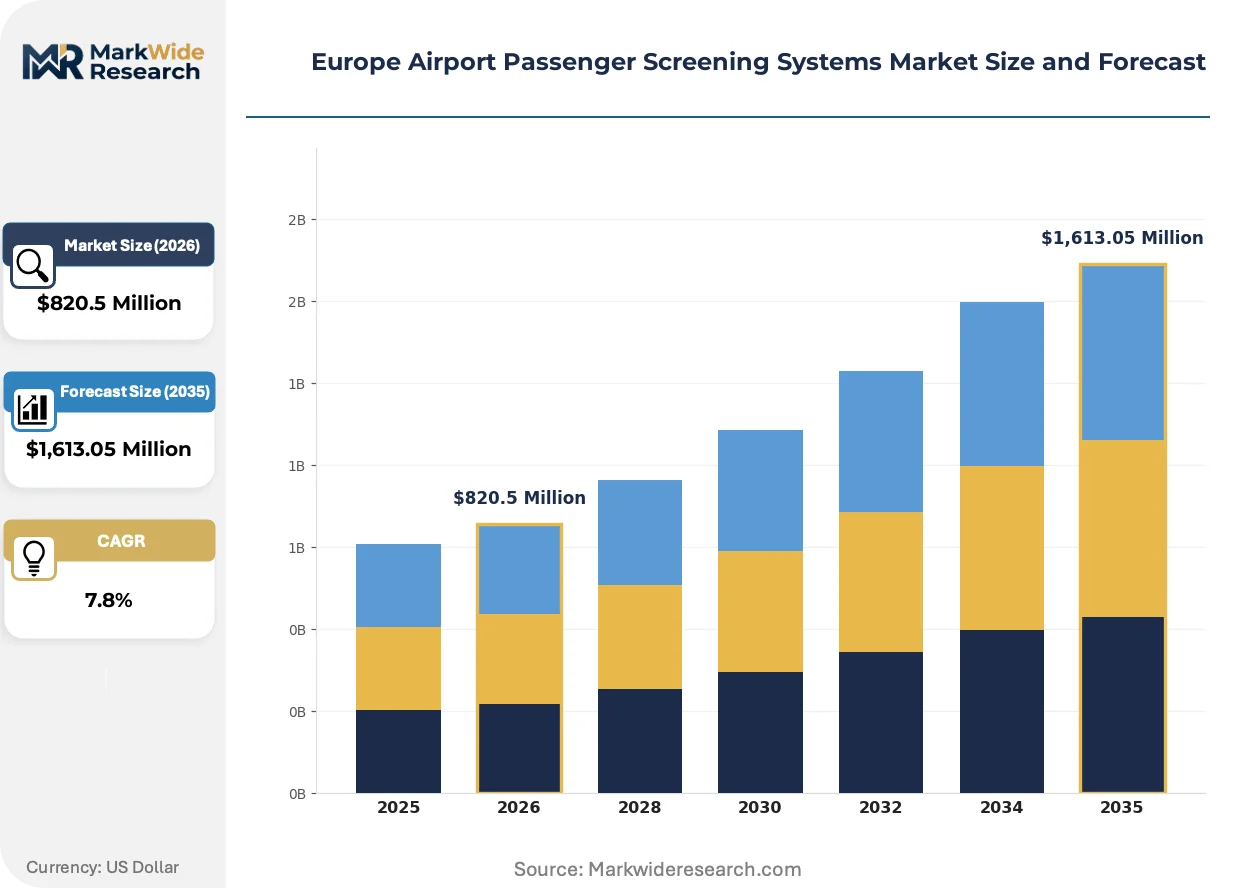
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,613.05 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Machines, Body Scanners, Explosives Detectors, Metal Detectors Technology: Computed Tomography, Millimeter Wave, Backscatter, Ion Mobility Spectrometry End User: Airports, Security Agencies, Airlines, Government Authorities Application: Passenger Screening, Baggage Screening, Cargo Inspection, Threat Detection |
| Companies Covered | Smiths Detection, L3Harris Technologies, Rapiscan Systems, Leidos Holdings, Inc., OSI Systems, Inc., Nuctech Company Limited, Garrett Electronics Inc., CEIA, Vanderlande Industries B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airport Passenger Screening Systems Market Shifts & Advancements
Digital twin architectures are penetrating airport security operations, enabling predictive maintenance and scenario simulation before physical deployment. Three distinct vectors are compressing innovation cycles across hardware, software, and service layers.
Computed tomography reconstruction software is virtualizing threat detection workflows across European hub terminals. Frankfurt Airport's Terminal 1 modernization deploys server-based image analysis that decouples algorithm updates from hardware replacement. This architecture compresses detection capability refresh cycles from seven-year hardware rotations to quarterly software deployments.
EU AI Act classification requirements for automated decision-making systems are reshaping vendor liability structures. Algorithmic threat recognition modules now face conformity assessment obligations equivalent to medical device software. German and French procurement specifications increasingly mandate explainable AI documentation for checkpoint deployments.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts across Scandinavian and Benelux airports. Oslo, Copenhagen, and Amsterdam Schiphol now source detection hardware, software licensing, and technical support through separate tender processes. This pattern forces original equipment manufacturers to defend position through software subscription retention rather than captive maintenance lock-in.
Europe Airport Passenger Screening Systems Market Segmentation
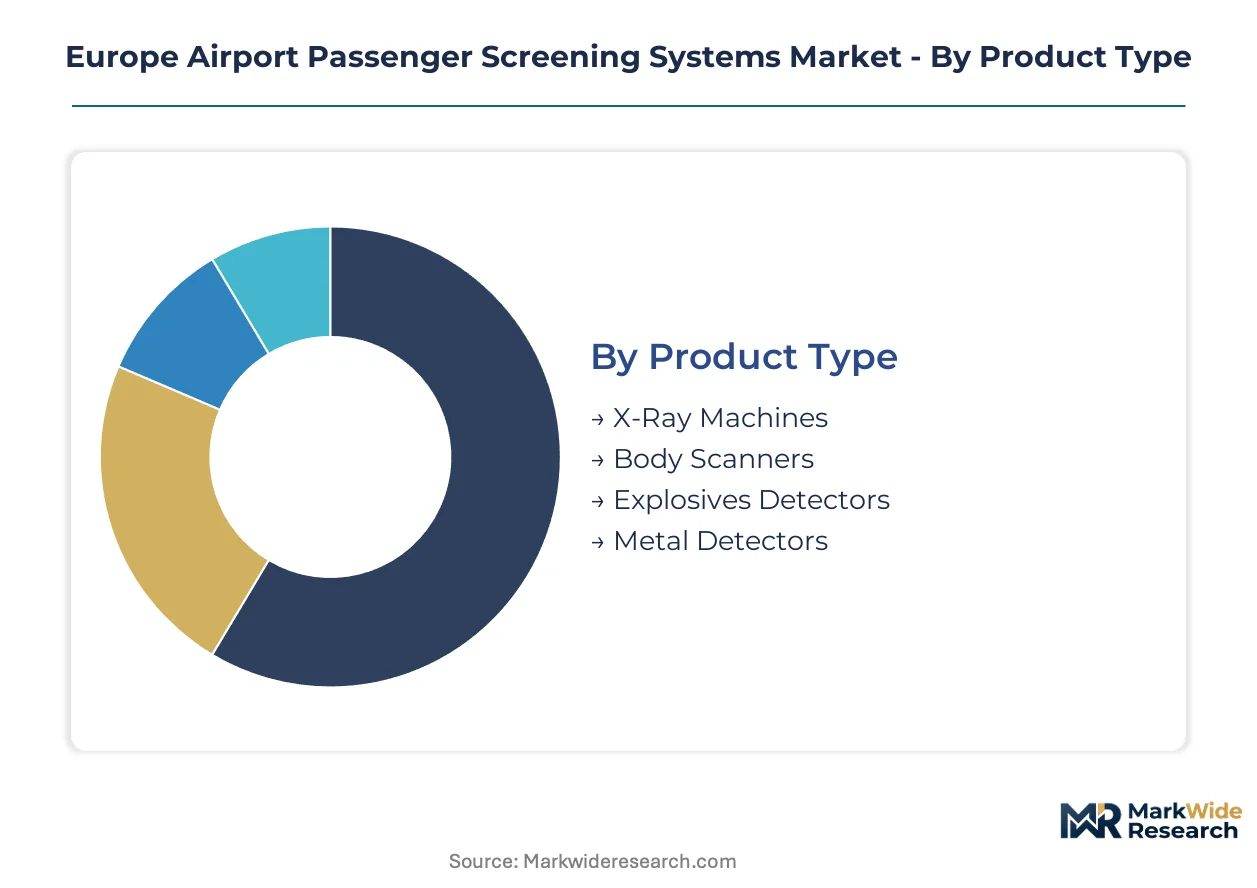
Europe's airport passenger screening systems market fragments across four distinct dimensions that shape procurement specifications and deployment architectures. Each segmentation layer reveals divergent technology requirements, certification obligations, and buyer concentration patterns across the region's hub and secondary airports.
Product Type:
Cost tiers separate basic detection hardware from integrated screening architectures requiring multi-million euro terminal investments.
- Computed Tomography Cabin Baggage Scanners:3-D volumetric reconstruction platforms eliminate liquid removal protocols and accelerate throughput. Frankfurt and Munich airports prioritize these systems for Terminal 1 and Terminal 2 modernization programs under EASA-mandated refresh cycles.
- Millimeter Wave Body Scanners:Privacy-compliant passive screening architectures detect concealed objects under clothing without physical pat-downs. Paris-Charles de Gaulle and London Heathrow deploy these at high-volume checkpoints where passenger flow exceeds 600 persons per hour per lane.
- X-Ray Machines:Legacy 2-D cabin baggage systems face replacement pressure from CT platforms but remain operational at regional European airports with constrained capital budgets.
- Explosives Detectors:Trace detection systems operate at parts-per-billion sensitivity thresholds for contraband identification, requiring specialized calibration expertise that concentrates at Category A airports.
- Metal Detectors:Walk-through systems anchor perimeter screening layers with EASA certification renewal cycles driving periodic hardware refresh at Italian and Spanish terminals.
X-Ray machines command the established base. The steepest expansion runs through computed tomography cabin baggage scanners.
Technology:
Application requirements dictate technology selection, with threat detection precision and passenger throughput operating as competing design constraints.
- Computed Tomography:Server-based image analysis decouples algorithm updates from hardware replacement, compressing capability refresh cycles. Frankfurt Airport's Terminal 1 deployment exemplifies this software-defined architecture.
- Millimeter Wave:Passive screening eliminates radiation exposure concerns while maintaining detection confidence against metallic and non-metallic threats. Cold-climate operations in Scandinavian airports expose current limitations with layered clothing penetration.
- Backscatter:Low-dose X-ray reflection technology serves secondary screening roles where millimeter wave systems generate ambiguous returns.
- Ion Mobility Spectrometry:Explosives trace detection relies on this analytical chemistry foundation, with calibration expertise scarcity constraining operational readiness at regional airports.
Backscatter anchors niche deployment. The steepest climb belongs to millimeter wave systems.
End User:
Customer type determines procurement authority, budget scale, and integration complexity across European aviation security infrastructure.
- Airports:Terminal operators at Frankfurt, Munich, and Paris-Charles de Gaulle execute multi-year modernization programs with integrated screening architectures. Direct procurement authority enables unified command center deployments.
- Security Agencies:National aviation security services mandate detection performance standards and certification protocols under EU Aviation Security Regulation 2015/1998.
- Airlines:Premium carriers invest in passenger experience optimization through expedited screening lanes, though hardware ownership remains concentrated at airport operators.
- Government Authorities:National civil aviation authorities in Germany, France, and Italy enforce EASA compliance and equipment approval timelines.
Government authorities set the regulatory framework. The steepest procurement volume concentrates at airports.
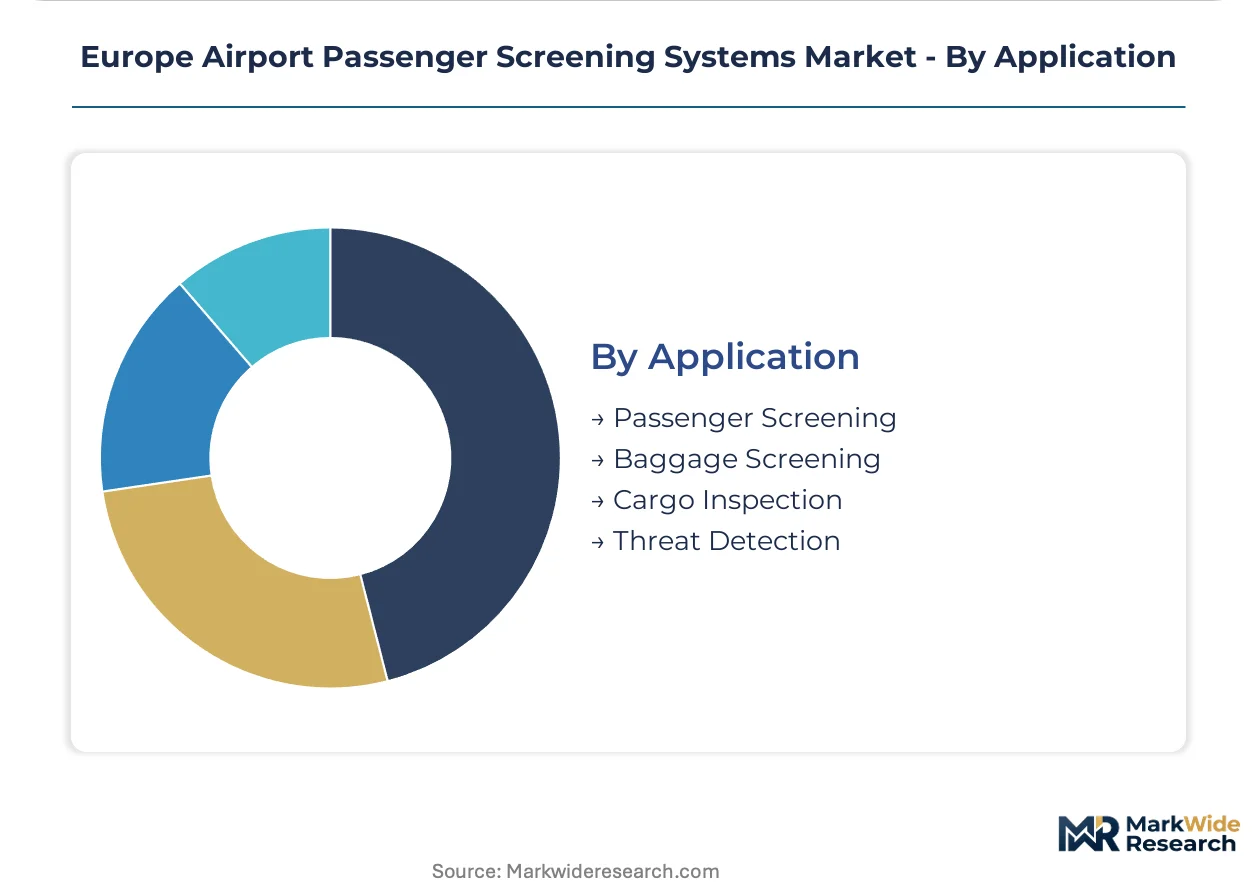
Application:
Volume throughput requirements and threat severity differentiate screening priorities across passenger, baggage, and cargo channels.
- Passenger Screening:Checkpoint architectures must balance detection confidence against flow rates above 600 persons per hour per lane. Millimeter wave and metal detection systems dominate this channel at London Heathrow and Amsterdam Schiphol.
- Baggage Screening:Hold baggage and cabin baggage systems operate on incompatible software architectures, complicating unified command center integration. CT platforms are displacing 2-D X-ray systems under EASA mandates.
- Cargo Inspection:Air freight screening operates at lower throughput requirements with higher detection depth specifications for consolidated shipments.
- Threat Detection:Premium positioning reflects EU focus on insider risk and evolving explosive device concealment methods, driving algorithmic threat recognition investments.
Baggage screening commands the installed base. The steepest expansion trajectory runs through threat detection applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA security mandates anchor procurement intensity across Germany, where Frankfurt and Munich airports drive replacement cycles for computed tomography cabin baggage scanners. National civil aviation authorities in France, the United Kingdom, Italy, and the Netherlands enforce certification standards that compress equipment refresh timelines.
Germany
Frankfurt Airport's Terminal 1 and Munich Airport's Terminal 2 execute multi-year modernization programs with integrated screening architectures. The German Federal Aviation Office enforces EASA compliance timelines that accelerate millimeter wave scanner deployments. Bavaria and Hesse concentrate hub airport procurement volume exceeding 600 persons per hour per lane throughput requirements.
France
Paris-Charles de Gaulle commits to next-generation passenger screening infrastructure with major deployment timelines for 3-D volumetric reconstruction platforms. ANSM and CNIL oversight shapes privacy-compliant passive screening specifications under GDPR and EU AI Act emerging frameworks. Île-de-France anchors French hub airport demand with terminal expansion programs driving CT scanner procurement.
United Kingdom
London Heathrow maintains high-throughput checkpoint operations requiring millimeter wave body scanner installations at passenger flow peaks. The UK Civil Aviation Authority mandates detection performance standards aligned with EU Aviation Security Regulation 2015/1998 retention post-Brexit. London and Southeast England concentrate screening infrastructure investment with unified command center deployments.
Italy
Milan Malpensa and Rome Fiumicino lag German and French deployment rates, creating procurement windows for integrated screening architectures. ENAC enforces national certification protocols under EASA security frameworks with equipment approval timelines. Lombardy and Lazio represent secondary airport modernization opportunities as terminal expansion programs accelerate.
Netherlands
Amsterdam Schiphol sources detection hardware, software licensing, and technical support through separate tender processes fragmenting traditional contracts. The Human Environment and Transport Inspectorate enforces REACH compliance and CE marking requirements for deployed systems. Randstad concentrates Dutch hub airport procurement with service unbundling patterns spreading to Benelux regional airports.
Europe Airport Passenger Screening Systems Market Competitive Landscape
Defense-electronics conglomerates and specialized security-technology developers split the market between integrated system architectures and component-specialist supply positions. Consolidation pressure concentrates around EASA certification depth and software-defined detection capabilities. Three archetypes dominate: full-spectrum platform vendors, millimeter wave scanner specialists, and trace-detection calibration service providers. Competitive moves center on algorithmic threat recognition certification precedence under EU AI Act frameworks and CT reconstruction software licensing unbundling from hardware sales.
Within the full-spectrum platform tier, Smiths Detection and L3Harris Technologies exemplify integrated security architecture vendors with established supply relationships across German and French hub airports. CEIA occupies a specialist position in walk-through metal detection systems with certification depth under EASA protocols. These three companies anchor competitive positioning around EASA-mandated refresh cycles and digital twin architecture deployments.
| Leading Market Players |
|---|
| Smiths Detection |
| L3Harris Technologies |
| Rapiscan Systems |
| Leidos Holdings, Inc. |
| OSI Systems, Inc. |
| Nuctech Company Limited |
| Garrett Electronics Inc. |
| CEIA |
| Vanderlande Industries B.V. |
| Others |
Supply & Pricing Matrix
Neodymium supply concentration in Chinese rare earth processing facilities determines both tier spreads for millimeter wave scanners and European manufacturers' backward integration imperatives. REACH compliance costs for electromagnetic shielding compounds compress margins at the standard tier while premium CT platforms command pricing power through EASA certification depth.
Pricing Analysis
German hub airports pay 15-25% premiums over Italian secondary terminals for equivalent CT cabin baggage systems due to throughput specification stringency. Three-tier pricing structure across EASA-certified premium, CE-marked standard, and non-certified economy levels separates procurement pools. Pricing pressure stems from service unbundling at Scandinavian airports fragmenting traditional bundled contracts. Regional airports exhibit highest price sensitivity due to constrained capital budgets and lower passenger volumes.
Supply Chain Analysis
Extended payment terms from German and French airport operators strain component suppliers' working capital, forcing supply-chain finance facility adoption. Manufacturing concentrates in Germany, France, and the United States for final assembly, with rare earth magnet processing anchored in China. Sensor arrays and specialized shielding materials draw from concentrated upstream geographies. Single-source vulnerability in neodymium supply creates tariff exposure risk. Distribution runs through direct OEM relationships with terminal operators and security integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EASA certification entrenchment creates switching costs that lock hub airports into established vendor relationships. Network effects in algorithmic threat recognition training data compound incumbency advantages.
For Market Incumbents: Harden software-defined detection capabilities through server-based CT reconstruction architectures that decouple hardware refresh from algorithm updates. Deepen EASA certification precedence under EU AI Act frameworks before conformity obligations crystallize. Vertical integration into rare earth magnet sourcing mitigates supply chokepoint exposure from Chinese processing concentration. For New Entrants and Emerging Players: Build out calibration service capabilities for explosives trace detection systems where analytical chemistry talent scarcity constrains operational readiness at regional Italian and Spanish airports. Italian secondary terminals represent the most penetrable geography given lagging deployment rates against German benchmarks. Partner with existing security integrators rather than pursuing direct terminal operator relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors algorithmic certification first-movers with established EASA relationships. Long-term viability hinges on software subscription retention rather than captive hardware-maintenance lock-in. Target acquisition archetypes include millimeter wave scanner specialists with cold-climate detection patents and digital twin architecture developers. Watch EU AI Act implementation timelines as the critical inflection signal for procurement specification reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Certification Precedence | First-mover algorithmic approval under EU AI Act frameworks reshapes vendor liability structures. |
| Software Licensing Unbundling | Separate tender processes for detection hardware and algorithm subscriptions fragment traditional contracts. |
| Digital Twin Deployment | Predictive maintenance architectures at Frankfurt Terminal 1 compress operational readiness costs. |
| Rare Earth Supply Diversification | Backward integration into magnet sourcing reduces dependency on Chinese processing concentration. |
| Biometric-Converged Screening | Identity-verification integration with millimeter wave platforms enables seamless passenger flow architectures. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Airport security directors, EASA certification officers, terminal procurement managers, and explosives trace calibration technicians provided operational perspective. Secondary sources include EU Aviation Security Regulation 2015/1998 implementation documents, EASA certification databases, national civil aviation authority filings, and REACH compliance registries. Bottom-up equipment deployment tallies triangulate against top-down terminal modernization budget aggregations.
Calibration against historical replacement cycle data and announced procurement timelines informs the projection framework. Segmentation dimensions span product type, technology architecture, end-user authority, and application channel across the analysis window. CAGRs derive from equipment refresh elasticity to EASA mandate timelines and hub airport traffic density trajectories. Forecast inputs incorporate CT scanner deployment schedules at Frankfurt and Munich, plus millimeter wave penetration rates at Paris-Charles de Gaulle.
Stress conditions across rare earth supply disruption, EU AI Act implementation delays, and hub airport traffic collapse were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology maturation curves. Macroeconomic contraction, accelerated regulatory deviation, or breakthrough detection technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Locks Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Card-Based Electronic Access Control Systems Market