
 Japan Smart Lock Market | 2026-2036
Japan Smart Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Smart Lock Market Insights
Supplier consolidation toward multi-source electronic component procurement is restructuring how Japanese smart lock makers secure semiconductors and biometric sensors. MIWA Lock Co., Ltd. anchors traditional mechanical expertise while extending into electronic access systems. Qrio Inc. competes through cloud-native architecture and direct-to-consumer channels. ASSA ABLOY dominates premium commercial installations with its broad institutional relationships.
A smart lock is an electromechanical locking device that authenticates users through biometric sensors, numeric keypads, Bluetooth Low Energy, or Wi-Fi connectivity, typically incorporating AES-128 encryption and motor-driven deadbolt actuation for automated entry control. The primary purpose is to replace physical key management with credential-based access logging and remote authorization in residential, commercial, and institutional buildings. Bluetooth-enabled products lead unit shipments due to low power consumption and smartphone-native pairing, while biometric segments command higher margins from corporate and healthcare buyers seeking audit-trail compliance. Cloud-based deployment is expanding fastest among hospitality operators requiring centralized property management integration.
METI's cybersecurity guidelines for consumer IoT devices mandate password complexity requirements and vulnerability disclosure procedures, compelling firmware architecture changes across domestic suppliers. JIS standards for electronic locking mechanisms establish durability benchmarks and electromagnetic compatibility thresholds that influence product certification timelines. PMDA oversight intersects where smart locks protect pharmaceutical storage and clinical environments. Stakeholders must monitor whether METI extends mandatory third-party penetration testing to residential-grade devices, as this would reshape R&D budgets and vendor qualification criteria.
Market Dynamics
Japan's smart lock sector pivots on METI's cybersecurity mandates forcing firmware overhauls and encrypted protocol adoption across domestic suppliers, while hospitality chains in Tokyo and Osaka accelerate automated access deployments to compress labor costs.
Growth Catalysts
- Biometric authentication demand:Corporate and healthcare buyers prioritize fingerprint and facial recognition systems for audit-trail compliance, driving premium segment expansion.
- Cloud-native architecture adoption:Hospitality operators deploy centralized property management integration to streamline multi-location access control.
- Tokyo residential density:Tower complexes and commercial co-working spaces concentrate demand for smartphone-native entry systems with remote authorization capabilities.
Market Restraints
- Semiconductor supply concentration:Domestic makers face procurement bottlenecks for biometric sensors and motor drivers from concentrated Asian foundry networks.
- METI compliance friction:Mandatory password complexity requirements and vulnerability disclosure procedures extend product certification timelines.
- Mechanical lock substitution:Traditional key systems retain cost advantage in rural prefectures and aging building stock resistant to electrical retrofit.
Strategic Opportunities
- Osaka hospitality corridor:Underpenetrated mid-tier hotel chains present white space for automated check-in solutions with reduced front-desk staffing.
- PMDA-regulated environments:Pharmaceutical storage and clinical facilities require access systems meeting dual cybersecurity and contamination control standards.
- Bluetooth-WiFi convergence:Hybrid connectivity architectures enable seamless handoff between low-power local authentication and cloud-based remote management.
Industry Challenges
- Firmware engineering scarcity:Domestic talent pools lack depth in embedded security development for AES-128 implementation and penetration testing protocols.
- Legacy mechanical integration:Retrofit installations in existing MIWA and other traditional lock footprints demand custom mounting hardware and electrical routing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Smart Lock Market |
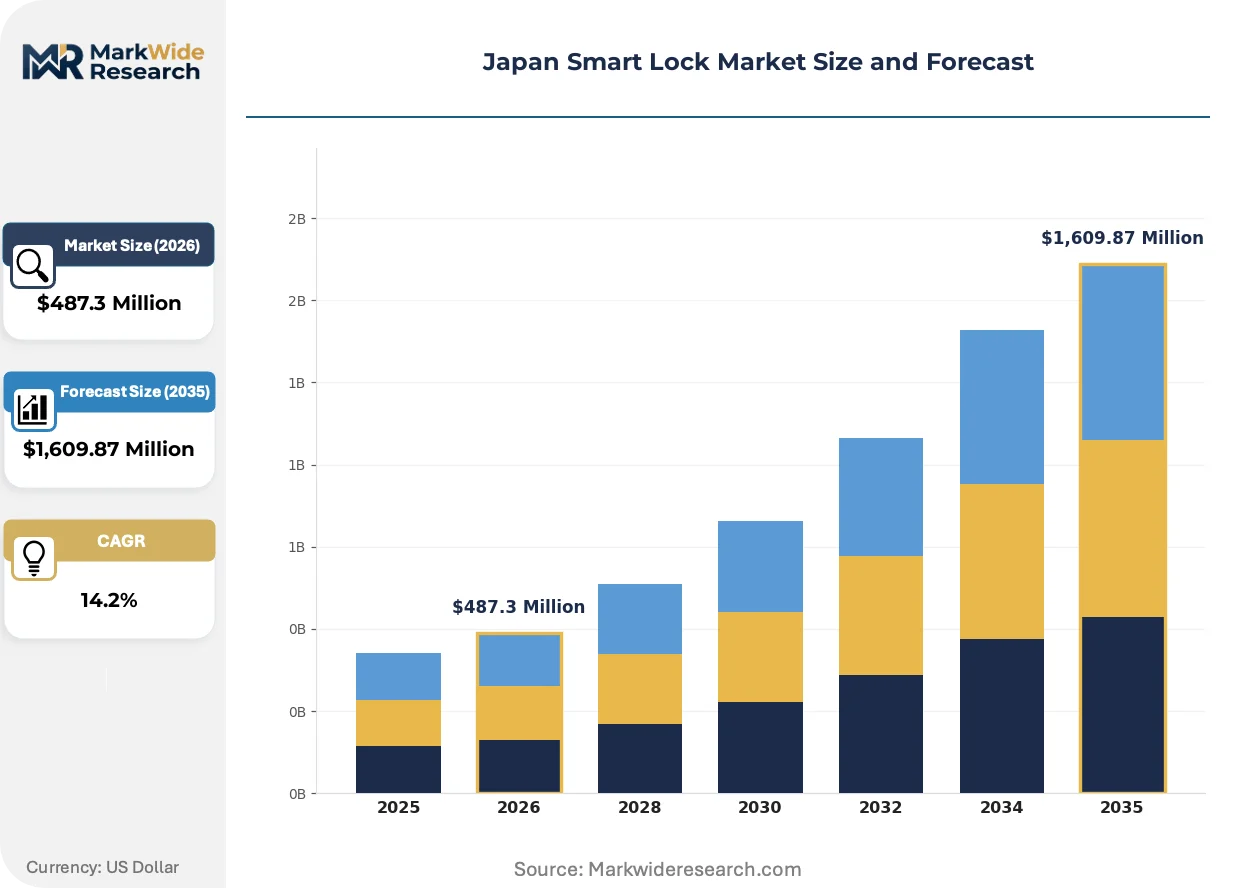
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint, Keypad, Bluetooth, Wi-Fi End User: Residential, Commercial, Hospitality, Healthcare Deployment: Cloud-based, On-premises, Hybrid, Remote Technology: Biometric, Electronic, Mechanical, Smart |
| Companies Covered | Qrio Inc., MIWA Lock Co., Ltd., ASSA ABLOY, Lockman Japan Co., Ltd., Honeywell, Keiden Co., Ltd., Enaspiration Co., Ltd., Kitos Asia, HomeShield Smart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Smart Lock Market Trends and Innovations
Japanese smart lock development centers on three vectors: cryptographic hardening against METI mandates, biometric sensor fusion for frictionless entry, and cloud-to-edge architectural unification for hospitality scale.
Matter-over-Thread connectivity is rewriting interoperability architecture for residential and commercial deployments. The protocol enables cross-brand smartphone and hub compatibility without proprietary bridges. Osaka co-working operators and Tokyo property managers are piloting unified access credentials across mixed-vendor environments. This standardization is compressing switching costs and fragmenting hardware loyalty.
METI's IoT security guidelines now mandate automatic update mechanisms and password prohibition of factory defaults for consumer-facing devices. Domestic manufacturers must rearchitect firmware pipelines to support over-the-air patching and vulnerability disclosure workflows. Residential-grade suppliers face the steepest compliance curves as they retrofit legacy product lines.
After-sales service unbundling is altering channel economics for installation and maintenance. Traditional security distributors now compete with direct-to-consumer brands offering subscription-based remote monitoring and troubleshooting. This shift is most visible in Tokyo's dense rental market, where landlords prioritize vendor-managed credential lifecycle over upfront hardware ownership.
Japan Smart Lock Market Segmentation
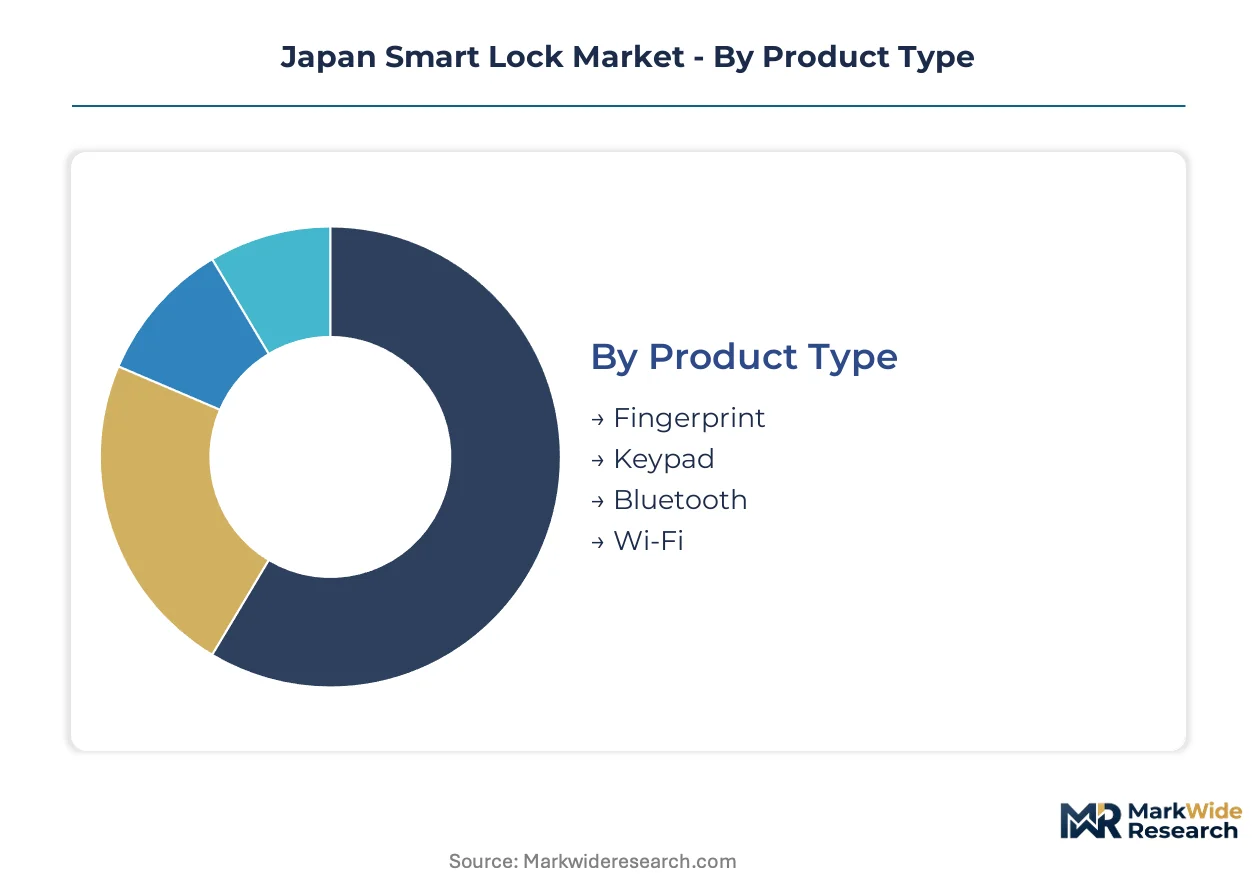
Smart lock segmentation in Japan reflects divergent technical requirements across Tokyo's dense residential towers, Osaka's hospitality corridors, and PMDA-regulated clinical environments. Each dimension—product type, end user, deployment mode, and underlying technology—carries distinct compliance obligations under METI's cybersecurity guidelines and JIS durability standards.
Product Type:
Standardization dominates at the low-power end of this spectrum, while biometric variants demand customized firmware pipelines for encryption compliance.
- Fingerprint:Capacitive and ultrasonic sensors capture biometric templates with liveness detection for spoof resistance. Corporate headquarters in Tokyo's Marunouchi district prioritize these systems for audit-trail compliance, though METI's vulnerability disclosure mandates extend firmware certification timelines.
- Keypad:Numeric entry systems with tamper-resistant housings and randomized digit layouts prevent shoulder-surfing attacks. Aging apartment stock in Osaka's residential zones favors these for retrofit compatibility where smartphone penetration lags among elderly tenants.
- Bluetooth:Low-energy protocols enable smartphone-native pairing with minimal power draw for battery-operated deadbolts.
- Wi-Fi:Direct cloud connectivity supports real-time remote authorization without hub intermediaries.
Most installed capacity flows through Bluetooth-enabled products. Expansion is steepest in fingerprint systems.
End User:
Cost tier stratification separates premium institutional buyers from price-sensitive residential adopters across Japan's prefectural markets.
- Residential:Tower complexes in Tokyo's 23 wards drive volume for smartphone-native entry with landlord-managed credential lifecycle. METI's password complexity rules hit this segment hardest as manufacturers retrofit legacy firmware.
- Commercial:Co-working operators in Shibuya and co-location data centers demand centralized access logging with API integration into building management systems. JIS electromagnetic compatibility thresholds filter out uncertified imports.
- Hospitality:Automated check-in compression targets mid-tier chains in Osaka's Umeda and Namba corridors.
- Healthcare:PMDA oversight applies where locks protect pharmaceutical cold storage and isolation wards.
Commercial deployments absorb the highest unit value. Hospitality applications are climbing the fastest.
Deployment:
Volume concentration favors architectures minimizing latency between credential verification and deadbolt actuation.
- Cloud-based:Centralized property management platforms enable multi-location credential synchronization and instant revocation. Hospitality chains with 50-plus properties across Honshu island deploy these for front-desk staffing reductions.
- On-premises:Local server installations satisfy data residency requirements for financial institutions in Tokyo's Otemachi district. Higher upfront hardware costs limit penetration outside regulated sectors.
- Hybrid:Edge caching with periodic cloud synchronization balances availability and remote manageability.
- Remote:Pure cloud dependency without local redundancy exposes operators to connectivity outages.
Hybrid architectures carry the dominant installed base. Cloud-native deployments are gaining share fastest.
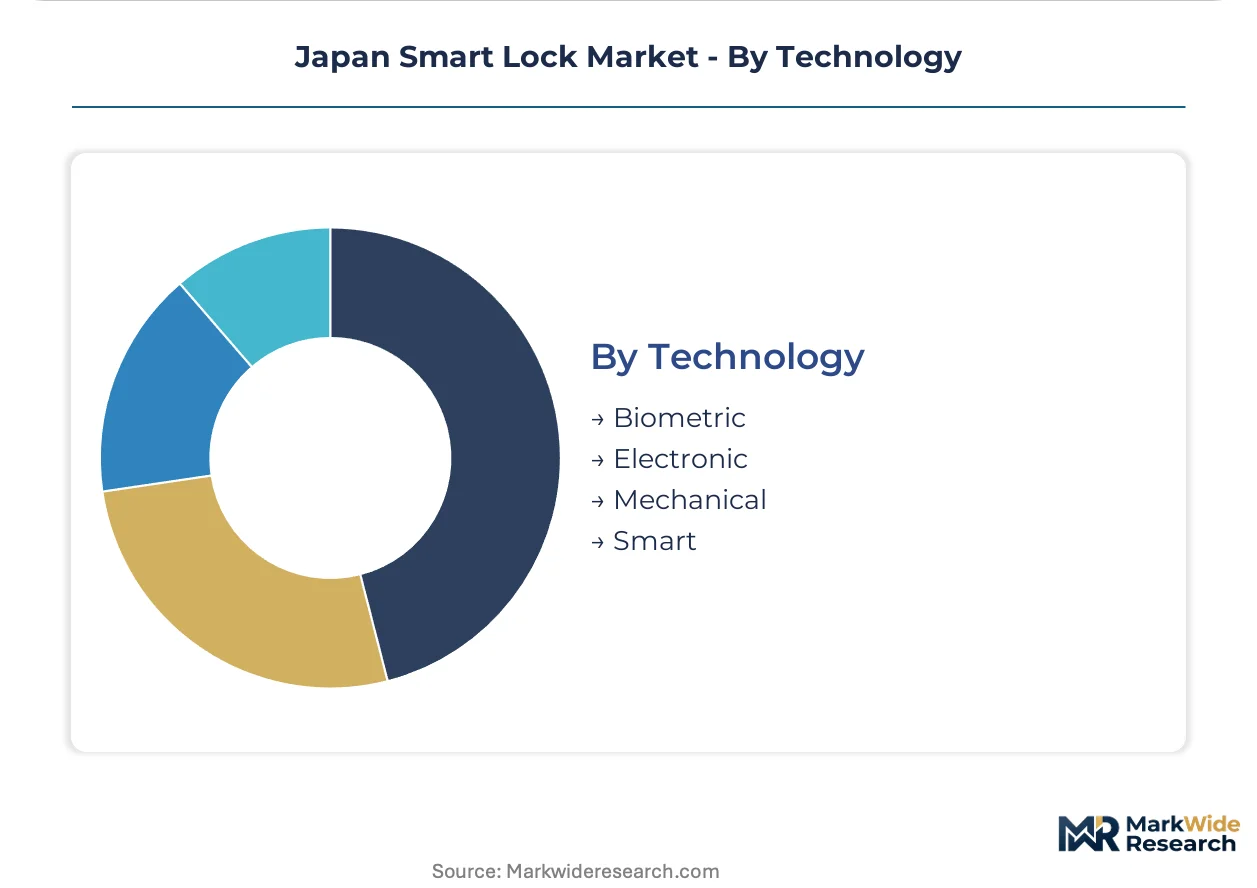
Technology:
Margin distribution inversely tracks mechanical component content, with fully electronic systems commanding premium pricing.
- Biometric:Multi-factor fusion of fingerprint and facial recognition with anti-spoofing algorithms. Corporate security budgets in Yokohama's Minato Mirai district absorb the hardware premium for compliance-grade audit trails.
- Electronic:Credential-based systems using RFID, NFC, or mobile tokens without biometric capture. Standard office buildings across Nagoya's Sakae district favor these for visitor management simplicity.
- Mechanical:Traditional key override retains relevance in earthquake-prone zones requiring non-electrical egress.
- Smart:Integrated platforms combining sensing, connectivity, and actuation in unified firmware stacks.
Electronic systems flow through the most installed capacity. Biometric platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's dense residential tower complexes concentrate the bulk of Japanese smart lock demand, with METI's cybersecurity mandates reshaping supplier compliance obligations across the archipelago.
Kanto/Tokyo
Corporate headquarters in Marunouchi and co-working operators in Shibuya drive biometric authentication demand for audit-trail compliance. METI's IoT security guidelines mandate automatic update mechanisms for consumer-facing devices. Tower complexes across Tokyo's 23 wards absorb the highest unit volumes for smartphone-native entry systems.
Kansai/Osaka
Hospitality chains in Umeda and Namba corridors accelerate automated check-in deployments to compress front-desk staffing costs. JIS standards for electronic locking mechanisms establish durability benchmarks that filter out uncertified imports. Mid-tier hotel properties present white space for cloud-native access solutions.
Chubu/Nagoya
Standard office buildings across Sakae district favor electronic credential-based systems for visitor management simplicity. PMDA oversight intersects where smart locks protect pharmaceutical storage facilities in the region's medical manufacturing corridor. Local property managers prioritize retrofit compatibility with aging building stock.
Kyushu
Regional commercial developments lag Tokyo in cloud-native adoption, creating latency between credential verification and deadbolt actuation. The national cybersecurity framework pushes domestic suppliers toward encrypted communication protocols. Fukuoka's emerging tech cluster pilots hybrid connectivity architectures for seamless local-to-cloud handoff.
Hokkaido
Traditional mechanical lock substitution retains cost advantage in rural prefectures resistant to electrical retrofit. Aging apartment stock favors keypad entry systems where smartphone penetration lags among elderly tenants. Sapporo's hospitality sector shows emerging interest in subscription-based remote monitoring models.
Japan Smart Lock Market Competitive Landscape
Global majors compete with regional champions across firmware architecture and channel strategy, producing a tiered structure where premium commercial installations diverge from price-sensitive residential volumes. Domestic incumbents leverage mechanical heritage while cloud-native entrants attack direct-to-consumer segments. Two archetypes dominate: traditional lock manufacturers extending into electronic access, and software-first platforms unbundling after-sales service. Competitive moves center on supplier consolidation for semiconductor procurement and firmware pipeline rearchitecture for METI compliance.
Within the domestic incumbent tier, MIWA Lock Co., Ltd. anchors traditional mechanical expertise, while Qrio Inc. occupies the cloud-native position with direct-to-consumer channel architecture. ASSA ABLOY exemplifies the global major archetype, leveraging institutional relationships across premium commercial installations. These three players collectively span the mechanical-to-digital transition spectrum reshaping Japanese access control procurement.
| Leading Market Players |
|---|
| Qrio Inc. |
| MIWA Lock Co., Ltd. |
| ASSA ABLOY |
| Lockman Japan Co., Ltd. |
| Honeywell |
| Keiden Co., Ltd. |
| Enaspiration Co., Ltd. |
| Kitos Asia |
| HomeShield Smart |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor sourcing from Taiwan and South Korea anchors both the supply position and pricing power for Japanese smart lock manufacturers facing METI's encryption mandates. Backward integration into firmware development pipelines separates premium biometric suppliers from commodity Bluetooth vendors competing on hardware margins alone.
Pricing Analysis
Input-cost pass-through from concentrated Asian foundry networks shapes margin structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade and after-sales service bundling. Cost compression in the residential tier intensifies because legacy firmware retrofit demands drain R&D budgets. Hospitality operators show least price sensitivity for cloud-native architectures with centralized property management integration.
Supply Chain Analysis
Dual-sourcing requirements for biometric sensors and motor drivers now dominate procurement protocols at MIWA Lock and Qrio as METI vulnerability disclosure deadlines approach. Semiconductor fabrication draws from Taiwan, South Korea, and Japan's domestic Kyushu cluster. AES-128 encryption chipsets and ultrasonic fingerprint modules constitute critical input dependencies. Single-source vulnerability in Taiwan Strait logistics exposes inventory buffers to disruption. Distribution runs through traditional security distributors competing against direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's smart lock market operates as a regulatory compounder where METI's IoT cybersecurity mandates continuously expand compliance-grade demand across residential and commercial segments.
For Market Incumbents: Anticipate firmware engineering scarcity by deepening captive development of embedded security talent pools against cloud-native entrants. Prioritize JIS certification maintenance as import filters tighten. Secure multi-year foundry allocation for biometric sensors before capacity constraints harden. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting Tokyo's dense rental tower market where landlord-managed credential lifecycle outperforms upfront hardware sales. Prioritize Osaka's underpenetrated mid-tier hospitality corridor for automated check-in white space. Differentiate through Matter-over-Thread interoperability to compress switching costs. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native software platforms because fragmented firmware pipelines struggle to amortize METI compliance costs across small-scale residential vendors. Five-to-ten year viability hinges on architectural unification between edge and cloud. Target acquisition archetype: hybrid connectivity specialists with hospitality PMS integration. Monitor METI's potential extension of mandatory third-party penetration testing to residential-grade devices as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Pipeline Rearchitecture | METI's automatic update mandates force over-the-air patching infrastructure investment across domestic suppliers. |
| Biometric Sensor Fusion Development | Multi-factor authentication combining fingerprint and facial recognition commands corporate security budgets in Marunouchi. |
| Cloud-Native Property Management Integration | Hospitality chains across Honshu island deploy centralized credential synchronization for front-desk staffing reductions. |
| Matter-over-Thread Certification | Cross-brand smartphone compatibility fragments hardware loyalty among Osaka co-working operators. |
| Subscription-Based After-Sales Unbundling | Vendor-managed credential lifecycle displaces upfront ownership in Tokyo's dense rental market. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with smart lock product managers, hospitality technology procurement officers, residential property managers, semiconductor supply planners, and METI regulatory affairs specialists with secondary validation against JIS certification databases, METI IoT security guideline filings, customs import records for electronic locking components, and hospitality chain capex disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-weighting across product type, end user, deployment architecture, and underlying authentication technology dimensions informed the analytical framework throughout the forecast period. CAGRs derived from fitted growth curves adjusted for regulatory milestone impacts and technology substitution rates. Specific inputs included METI compliance timeline assumptions and Bluetooth-WiFi convergence adoption curves in hospitality applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated METI mandate expansion. Projections reflect documented assumptions regarding firmware certification timelines and foundry capacity allocation. Deviation in METI's enforcement posture toward mandatory third-party penetration testing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Wireless Security System Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
North America Access Control Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
China Access Control Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market