
 Pedestrian Access Control System Market | 2026-2036
Pedestrian Access Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Pedestrian Access Control System Market Analytics
China is tilting toward domestic manufacturing scale for pedestrian access control hardware, with Shenzhen and Hangzhou emerging as production clusters. ASSA ABLOY Global Solutions leverages its Nordic engineering heritage to sustain premium positioning in European commercial buildings. Dormakaba Holding anchors its competitiveness through integrated door and access solutions across airport verticals. Honeywell competes by extending its building automation software into AI-powered crowd analytics for stadiums and transit hubs.
A pedestrian access control system comprises electromechanical turnstiles, barriers, bollards, and access gates that regulate human flow through credential verification, typically operating with cycle times under 0.4 seconds per passage and MTBF ratings exceeding 1.5 million cycles. These systems serve critical infrastructure by preventing unauthorized entry while maintaining throughput capacity during emergency egress scenarios. Biometric technology captures the fastest expansion trajectory as facial recognition and palm-vein modules displace card-based credentials in high-security government installations. Turnstiles retain the largest installed base across transportation hubs, though margin pools concentrate in wireless-enabled outdoor barrier systems where environmental sealing and vandal resistance command specification premiums.
FCC certification requirements govern wireless transmission protocols for US-deployed systems, while the EU AI Act imposes conformity assessment obligations on biometric subsystems sold into European member states. India's BIS mandates mechanical safety testing for motorized barriers deployed in metro rail environments, creating localized compliance barriers for imported equipment. Stakeholders must weigh biometric privacy litigation exposure against throughput efficiency gains when specifying next-generation credential platforms.
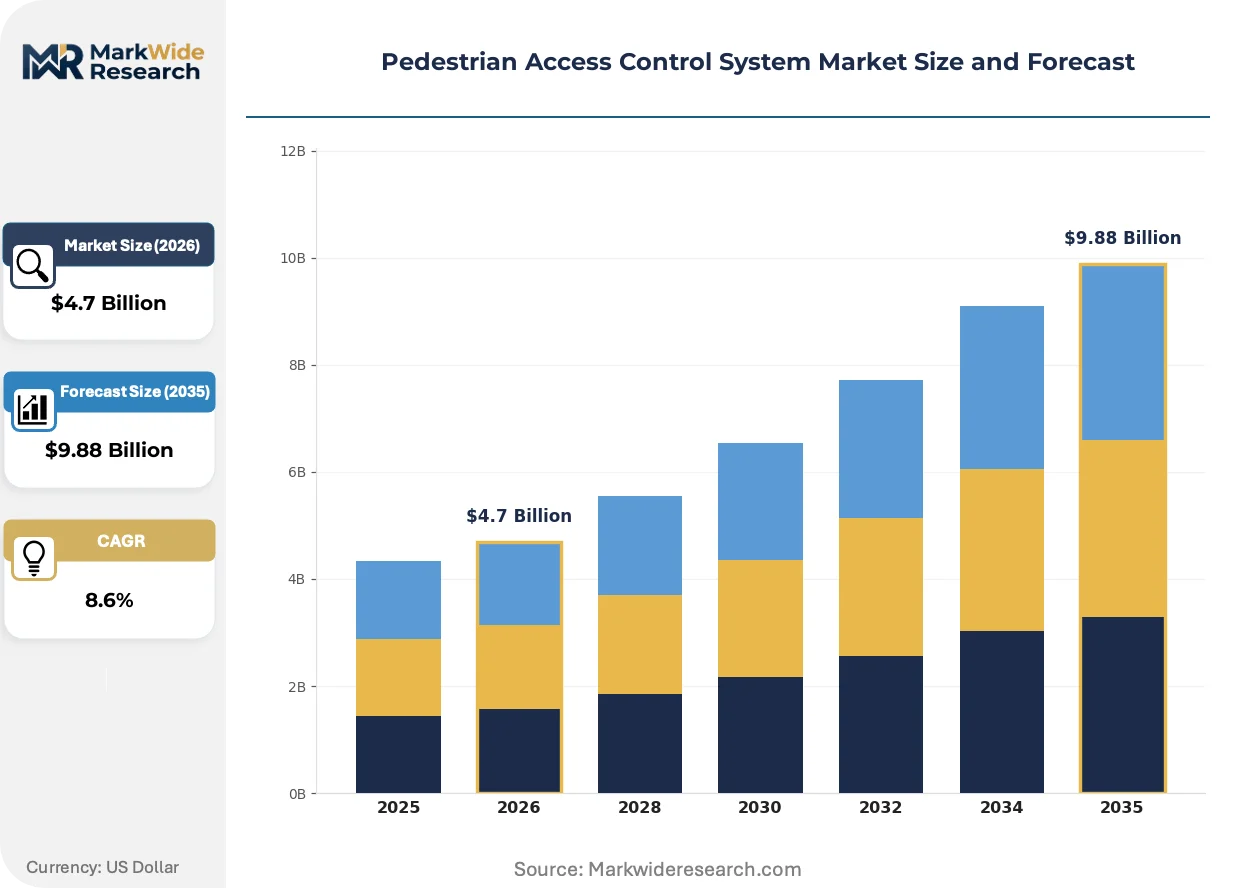
Market Dynamics
The EU AI Act's conformity assessment obligations for biometric subsystems are forcing specification changes across European government installations, while India's metro rail expansion concentrates demand for motorized barriers with BIS mechanical safety certification.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian transportation hubs are accelerating deployment of credential-verification turnstiles with cycle times under 0.4 seconds to manage passenger throughput.
- Biometric authentication convergence:Facial recognition and palm-vein modules are capturing specification share in high-security installations, displacing card-based credentials through faster verification speeds.
- FCC wireless certification pathways:US-deployed systems with environmental sealing and vandal resistance command specification premiums in outdoor stadium and transit applications.
Market Restraints
- Specialized component supply concentration:Electromechanical actuator production clusters in Shenzhen and Hangzhou create geographic dependency for motorized barrier manufacturers.
- Biometric privacy litigation exposure:EU GDPR and the EU AI Act impose strict data retention limits on facial recognition subsystems, increasing compliance overhead for system integrators.
- Legacy credential lock-in:Existing card-based access infrastructure in commercial buildings creates switching friction against wireless-enabled upgrade paths.
Strategic Opportunities
- India's metro rail corridors:BIS-mandated mechanical safety testing for motorized barriers creates localized specification windows for certified equipment suppliers.
- AI-powered crowd analytics convergence:Integration of building automation software with access control hardware is opening specification channels in stadium and transit hub verticals.
- After-sales service unbundling:MTBF-rated maintenance contracts for turnstile systems exceeding 1.5 million cycles are emerging as distinct revenue streams separate from hardware procurement.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FCC, EU AI Act, and BIS compliance requirements extend product validation cycles for multinational deployments.
- Legacy system integration complexity:Electromechanical turnstile retrofits must maintain emergency egress throughput while interfacing with obsolete credential databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedestrian Access Control System Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turnstiles, Barriers, Bollards, Access Gates Technology: Biometric, RFID, Keypad, Wireless End User: Government, Commercial Buildings, Transportation Hubs, Educational Institutions Installation Type: Indoor, Outdoor, Retrofit, New Construction |
| Companies Covered | ASSA ABLOY Global Solutions, Dormakaba Holding, Honeywell, Johnson Controls, Royal Boon Edam International B.V., Gunnebo Entrance Control, PERCo, Automatic Systems, ZKTeco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedestrian Access Control System Market Evolving Landscape
Credential verification architectures are undergoing fundamental restructuring as biometric modules and wireless protocols displace established card-based formats, with regulatory pressure accelerating specification divergence across major deployment geographies.
Edge-based facial recognition processors with on-device template matching are digitizing identity verification workflows in transportation hubs. Airport operators in the Asia-Pacific region are specifying these modules for passenger boarding gates to reduce credential-handling latency. The technology is digitizing throughput capacity planning by enabling real-time occupancy analytics without centralized data transmission.
The EU AI Act's risk-based classification system for biometric identification imposes mandatory conformity assessments on access control subsystems deployed in European public spaces. Manufacturers must now document algorithmic accuracy thresholds and bias mitigation protocols before CE marking. High-security government installations are responding by demanding palm-vein alternatives to facial recognition to reduce prohibited-uses exposure.
Buyers are fragmenting procurement decisions between hardware specification and software subscription tiers. Stadium operators are unbundling crowd analytics licenses from turnstile hardware purchases, creating separate vendor relationships for each layer. This pattern is most visible in US collegiate athletic facilities where capital budgets and operational technology spending sit under different approval authorities.
Pedestrian Access Control System Market Segmentation
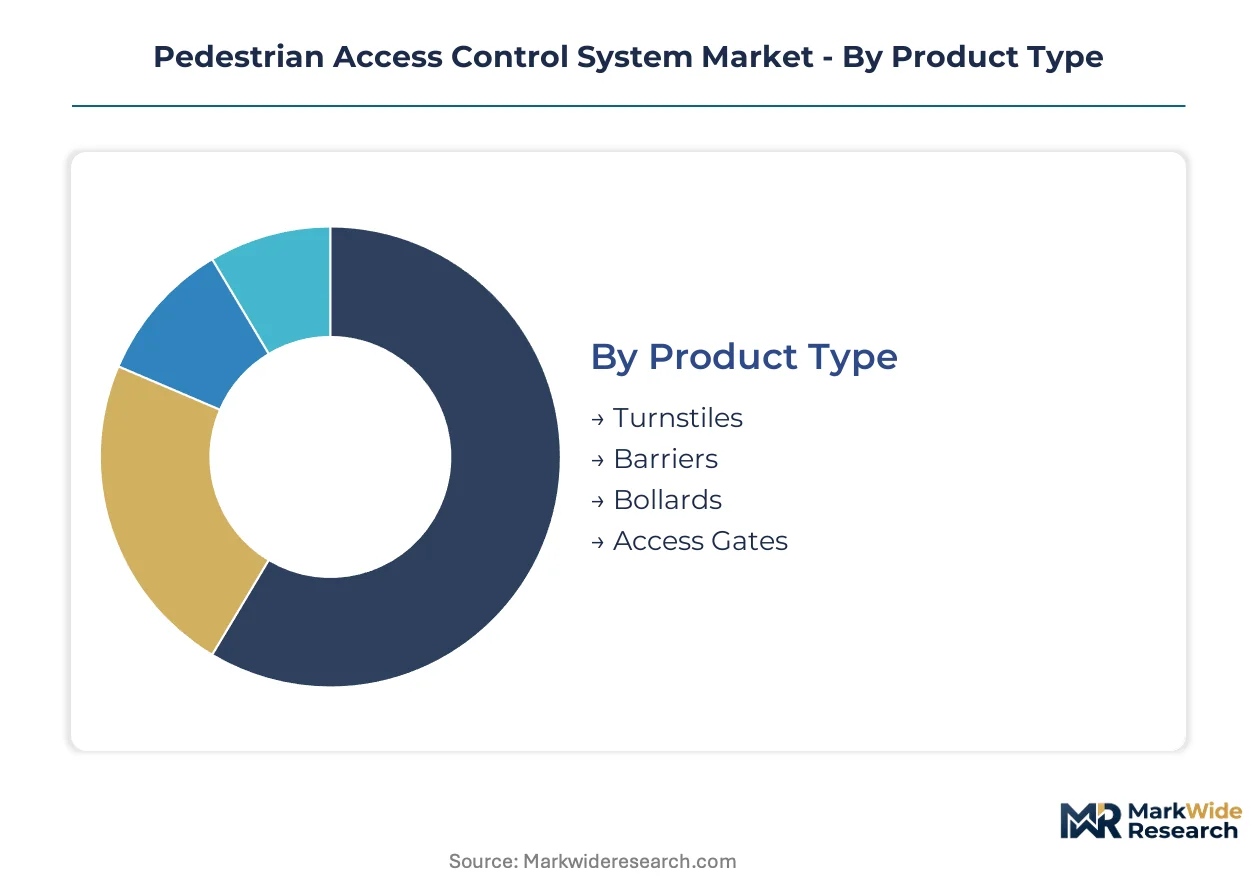
Pedestrian access control systems fragment across hardware form factors, credential technologies, deployment environments, and end-use security requirements. Each dimension carries distinct specification pressures, certification burdens, and margin structures that reshape vendor positioning and procurement patterns.
Product Type:
Physical form factors span the full use-case spectrum from high-throughput transit corridors to perimeter hardening and discrete entry points.
- Turnstiles:Tripod, full-height, and optical variants manage passenger flow with cycle times under 0.4 seconds. Transportation hubs in India specify these for metro rail corridors where BIS mechanical safety certification is mandatory for motorized units.
- Barriers:Swing, slide, and drop-arm configurations balance throughput with emergency egress compliance. Outdoor wireless-enabled barriers command specification premiums for environmental sealing and vandal resistance in US stadium deployments.
- Bollards:Fixed, removable, and retractable posts protect pedestrian zones from vehicle intrusion. Government installations favor crash-rated hydraulic bollards for perimeter security.
- Access Gates:Speed gates and flap barriers serve premium commercial buildings where aesthetic integration matters alongside credential verification speed.
The dominant share belongs to Turnstiles, while Barriers is closing the gap fastest.
Technology:
Credential verification architectures diverge sharply by security tier, throughput requirement, and regulatory exposure across deployment geographies.
- Biometric:Facial recognition and palm-vein modules capture specification share in high-security installations. EU AI Act conformity assessments are accelerating palm-vein adoption to reduce prohibited-uses exposure in European public spaces.
- RFID:Card and fob credentials retain the largest installed base across commercial buildings. Legacy infrastructure creates switching friction against wireless upgrade paths.
- Keypad:PIN-entry systems persist in cost-sensitive applications and as backup authentication layers. Educational institutions specify these for secondary verification at dormitory access points.
- Wireless:Bluetooth and NFC protocols enable smartphone-based credentialing. FCC certification requirements govern US deployment of these transmission protocols.
Biometric systems command the steepest expansion trajectory, though RFID maintains volume leadership through retrofit demand.
End User:
Security posture, throughput scale, and procurement authority vary dramatically across institutional buyer categories.
- Government:High-security installations demand biometric subsystems with documented algorithmic accuracy and bias mitigation protocols. EU AI Act risk classifications reshape specification requirements for facial recognition in European public spaces.
- Commercial Buildings:Office complexes prioritize aesthetic integration and building automation software convergence. Honeywell extends its automation platforms into AI-powered crowd analytics for this vertical.
- Transportation Hubs:Airports and metro rail systems specify turnstiles with MTBF ratings exceeding 1.5 million cycles. Southeast Asian smart city investments are accelerating deployment of credential-verification systems in this segment.
- Educational Institutions:Campuses balance access control with emergency egress requirements. US collegiate athletic facilities are unbundling crowd analytics licenses from hardware purchases.
Transportation Hubs generate the largest project scale, while Government installations drive the fastest technology upgrade cycles.
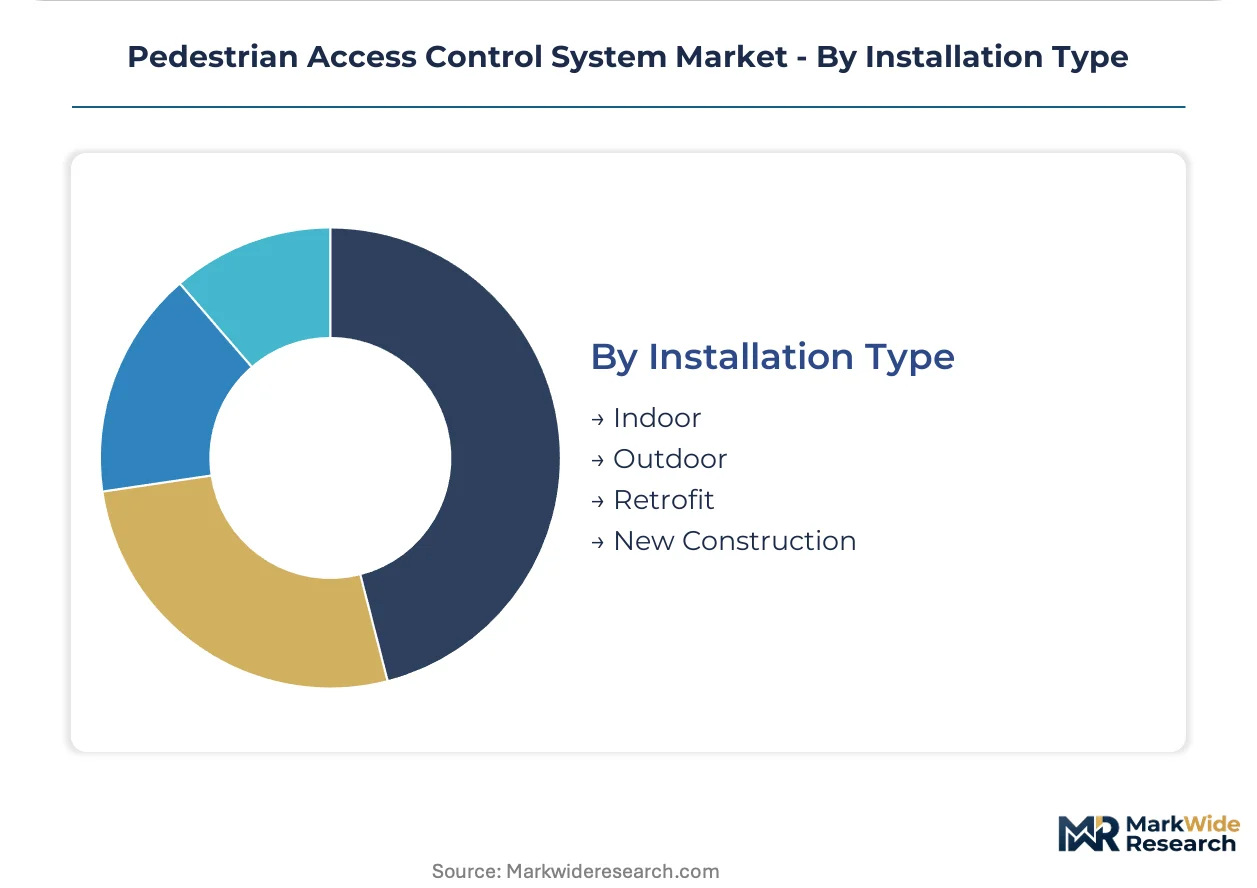
Installation Type:
Deployment context determines environmental sealing requirements, integration complexity, and revenue recognition timing.
- Indoor:Climate-controlled environments enable standard-duty electromechanical components. Commercial buildings represent the core demand pool with faster installation cycles.
- Outdoor:Environmental sealing and vandal resistance specifications add cost premiums. FCC-certified wireless protocols are required for US-deployed outdoor systems.
- Retrofit:Electromechanical turnstile replacements must interface with obsolete credential databases while maintaining emergency egress throughput. Legacy system integration complexity extends project timelines.
- New Construction:Greenfield deployments allow integrated door and access solution specification from foundation phase. Dormakaba anchors competitiveness through early-stage design involvement.
New Construction captures the dominant project value, though Retrofit is expanding most quickly through infrastructure renewal mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification requirements govern wireless transmission protocols for US-deployed systems, while the EU AI Act imposes conformity assessment obligations on biometric subsystems sold into European member states. India's BIS mandates mechanical safety testing for motorized barriers deployed in metro rail environments. Stakeholders must weigh biometric privacy litigation exposure against throughput efficiency gains when specifying next-generation credential platforms.
United States
Stadium operators and transit authorities drive demand for outdoor wireless-enabled barriers with environmental sealing specifications. FCC certification pathways create compliance timelines for Bluetooth and NFC credential transmission protocols. Texas and California transit hubs concentrate deployment of crowd analytics-integrated access systems.
Germany
Commercial building automation convergence sustains specification activity for integrated door and access solutions. The EU AI Act's risk-based classification system mandates documented algorithmic accuracy for biometric identification in public spaces. Bavaria and North Rhine-Westphalia anchor retrofit demand for legacy electromechanical turnstile replacements.
India
Metro rail expansion corridors concentrate demand for motorized barriers with cycle times under 0.4 seconds. BIS mechanical safety certification creates localized specification windows for turnstile suppliers. Maharashtra and Karnataka smart city investments accelerate deployment of credential-verification systems in transportation hubs.
China
Domestic manufacturing scale for pedestrian access control hardware tilts toward Shenzhen and Hangzhou production clusters. GB standards govern electromechanical safety for motorized barrier exports. Yangtze River Delta and Pearl River Delta cities drive volume demand for high-throughput optical turnstiles.
United Kingdom
Premium commercial buildings sustain specification activity for aesthetic-integrated speed gates and flap barriers. GDPR data retention limits reshape procurement decisions for facial recognition subsystems in public installations. London and Southeast England concentrate demand for building automation software convergence.
Pedestrian Access Control System Market Competitive Landscape
Capability concentration sits with Nordic and Swiss engineering specialists; scale advantage sits with diversified building automation conglomerates. The vendor base organizes around three strategic archetypes: integrated door-access solution providers, AI-powered crowd analytics extenders, and electromechanical hardware pure-plays. Dominant competitive moves include backward integration into electromechanical actuator production and geographic expansion through BIS-certified manufacturing footprints for Indian metro rail corridors.
Within the Nordic engineering heritage tier, ASSA ABLOY Global Solutions and Dormakaba Holding exemplify premium positioning through integrated specification channels. Honeywell occupies a position at the automation-software convergence vector, extending building control platforms into AI-powered analytics. These three anchors represent distinct competitive vectors: hardware heritage, integrated solutions, and software extension.
| Leading Market Players |
|---|
| ASSA ABLOY Global Solutions |
| Dormakaba Holding |
| Honeywell |
| Johnson Controls |
| Royal Boon Edam International B.V. |
| Gunnebo Entrance Control |
| PERCo |
| Automatic Systems |
| ZKTeco |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container cost dynamics amplify price differentiation between Shenzhen-produced electromechanical actuators and Nordic-engineered premium turnstiles, while BIS certification requirements for Indian metro deployments create localized pricing premiums that reward captive manufacturing footprints.
Pricing Analysis
Geographic price spreads between Chinese-manufactured optical turnstiles and European-integrated access systems exceed three-to-one ratios at equivalent throughput specifications. Three-tier pricing structure across premium, standard, and economy levels separates ASSA ABLOY's automation-converged solutions from Hangzhou-produced commodity barriers from unbundled after-sales contracts. Cost compression in standard-tier motorized barriers is intensifying because Shenzhen actuator suppliers are absorbing steel price volatility without contract escalation clauses. Educational institutions exhibit highest price sensitivity due to bifurcated capital-operational budgets, while airport authorities prioritize MTBF-rated maintenance bundling over unit acquisition costs.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn Industrial Internet and Jabil Circuit holding electromechanical assembly capacity across Shenzhen, Suzhou, and Penang facilities. Electromechanical actuator production draws from China, Taiwan, and Vietnam for precision motor windings, while stainless steel enclosures source from Indian and Turkish rolling mills. Single-source vulnerability concentrates in facial recognition module supply from Hikvision and Dahua subsidiaries subject to FCC entity list restrictions. Distribution runs through systems integrators with BIS-certified installation capabilities for Indian metro rail corridors, bypassing direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from smartphone-native credential platforms that bypass dedicated hardware entirely, forcing defensive repositioning around throughput reliability and emergency egress compliance that software-only alternatives cannot replicate.
For Market Incumbents: Entrench specification control by backward integration into electromechanical actuator production at Shenzhen-adjacent facilities to neutralize component cost volatility, while securing BIS mechanical safety certification for Indian manufacturing footprints ahead of metro rail tender waves. Biometric privacy litigation exposure in EU jurisdictions demands documented algorithmic bias mitigation protocols as a non-negotiable tender requirement. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, specifically Jakarta and Bangkok smart city corridors where aesthetic-integrated speed gates face limited incumbent lock-in. Palm-vein authentication modules for EU government installations offer regulatory arbitrage against facial recognition prohibitions. Channel partnership with regional building automation distributors accelerates specification access faster than direct OEM competition. For Investors and Strategic Acquirers: Electromechanical hardware pure-plays with captive actuator production and MTBF-rated service contract portfolios command scarcity premiums as automation conglomerates seek throughput-technology differentiation. Long-term viability hinges on biometric subsystem compliance capabilities across FCC, EU AI Act, and BIS regulatory clusters. The signal to monitor is BIS certification backlogs for Indian metro rail equipment, which indicate demand inflection ahead of capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Actuator Production | Shenzhen-adjacent motor winding facilities neutralize supply cost volatility for turnstile manufacturers. |
| BIS Certification Investment | Indian metro rail tenders mandate mechanical safety testing that creates localized specification windows. |
| AI-Powered Crowd Analytics Platform Launch | Honeywell's automation extension demonstrates software convergence opportunity in stadium verticals. |
| Palm-Vein Authentication Module Development | EU AI Act risk classifications accelerate demand for prohibited-uses-compliant biometric alternatives. |
| After-Sales Service Unbundling | US collegiate athletic facilities separate crowd analytics licenses from hardware capital budgets. |
Research Methodology
Initial hypotheses were tested against primary input from transit authority procurement directors, airport operations managers, systems integration specialists, and building automation engineers, and refined through secondary validation against SEC 10-K filings, BIS certification registries, EU AI Act conformity assessment databases, and smart city tender documentation. Bottom-up unit deployment estimates across metro rail corridors, airport terminals, and commercial building stock were triangulated against top-down infrastructure investment forecasts from national development authorities.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions spanning hardware form factor, credential technology tier, installation type, and end-use security classification. CAGRs were derived from installed base turnover rates and greenfield project pipelines rather than extrapolated trend fitting. Industry-specific forecast inputs incorporated MTBF degradation curves for electromechanical components and biometric subsystem regulatory approval timelines.
Practitioners should monitor EU AI Act enforcement patterns and BIS certification queue lengths for early signals of specification timeline compression. Forecasts reflect assumptions regarding sustained smart city infrastructure commitments and stable electromechanical component trade flows. Quarterly review of metro rail tender award velocities and facial recognition litigation dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Bluetooth Smart Lock Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
North America Smart Locks Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Italy Access Control Market
Access Control Systems
Digital Security Control Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market