
 Smart Entry System Market | 2026-2036
Smart Entry System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Entry System Market Analytics
Market Context
The Smart Entry System Market is recalibrating around a sharp divergence between premium biometric-authentication tiers and commodity keyless-entry hardware. ASSA ABLOY AB leverages its architectural hardware dominance to anchor high-margin commercial installations across European infrastructure projects. DENSO Corporation competes through automotive OEM integration, sustaining deep relationships with Japanese and German vehicle manufacturers. Bosch differentiates via sensor-to-cloud platforms that extend beyond physical access into building-energy management systems.
Technical Definition and Structural Segments
A smart entry system integrates electromechanical locking mechanisms with wireless communication protocols and identity-verification subsystems to authenticate and authorize physical access, typically operating across 2.4 GHz ISM bands with AES-128 encryption standards. Biometric Systems and RFID Readers capture the dominant margin pools, with Bluetooth-enabled Smart Locks representing the fastest-expanding installation category in residential retrofit channels. Zigbee and Z-Wave connectivity segments serve industrial and government end users where mesh-network reliability outweighs consumer-grade convenience priorities.
Regulatory Frame and Outlook
The EU Cyber Resilience Act and GDPR impose strict data-protection and breach-notification obligations on connected entry devices sold in Europe, while NHTSA guidelines in the United States shape automotive keyless-entry cybersecurity testing protocols. China's SAMR enforces GB standards for biometric data collection and storage in commercial access systems. Stakeholders must monitor evolving encryption-certification requirements across multiple jurisdictions to maintain product-market access and avoid compliance-driven redesign cycles.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating biometric authentication integration for fleet vehicles, while China's smart city infrastructure projects concentrate residential and commercial demand around retrofit-ready smart lock systems.
Growth Catalysts
- EU Cyber Resilience Act:Mandates breach-notification obligations and encryption-certification standards for connected entry devices sold in Europe, forcing manufacturers to upgrade firmware architecture.
- Biometric authentication:Fingerprint and facial-recognition modules are penetrating commercial real estate in Singapore and Dubai as landlords seek tenant-convenience differentiation.
- China's SAMR enforcement:GB standards for biometric data collection in commercial access systems are creating compliance-driven replacement cycles in Shanghai and Shenzhen smart city deployments.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate NFC and Bluetooth Low Energy chip fabrication, exposing smart lock manufacturers to allocation volatility.
- GDPR biometric friction:Strict data-protection obligations in Europe increase legal review timelines and limit cloud-storage architectures for facial-recognition systems.
- Mechanical fallback requirements:Fire-safety codes in Germany and France mandate physical key override capabilities, adding component cost and design complexity.
Strategic Opportunities
- India's residential retrofit channel:Urban middle-class housing complexes in Bangalore and Mumbai show low smart lock penetration but rising security-service subscriptions.
- Healthcare facility convergence:Patient-room access systems are integrating nurse-call and asset-tracking functions, creating bundled procurement opportunities.
- U.S. NHTSA cybersecurity testing:Automotive keyless-entry protocols are expanding to mandate over-the-air update capabilities, opening firmware-service revenue streams.
Industry Challenges
- Embedded systems security engineering:Shortage of firmware developers with AES-256 and side-channel attack mitigation expertise delays product certification.
- Legacy building integration:Pre-2000 electrical infrastructure in European commercial stock lacks power-over-ethernet capacity, requiring battery-dependent retrofit designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Entry System Market |
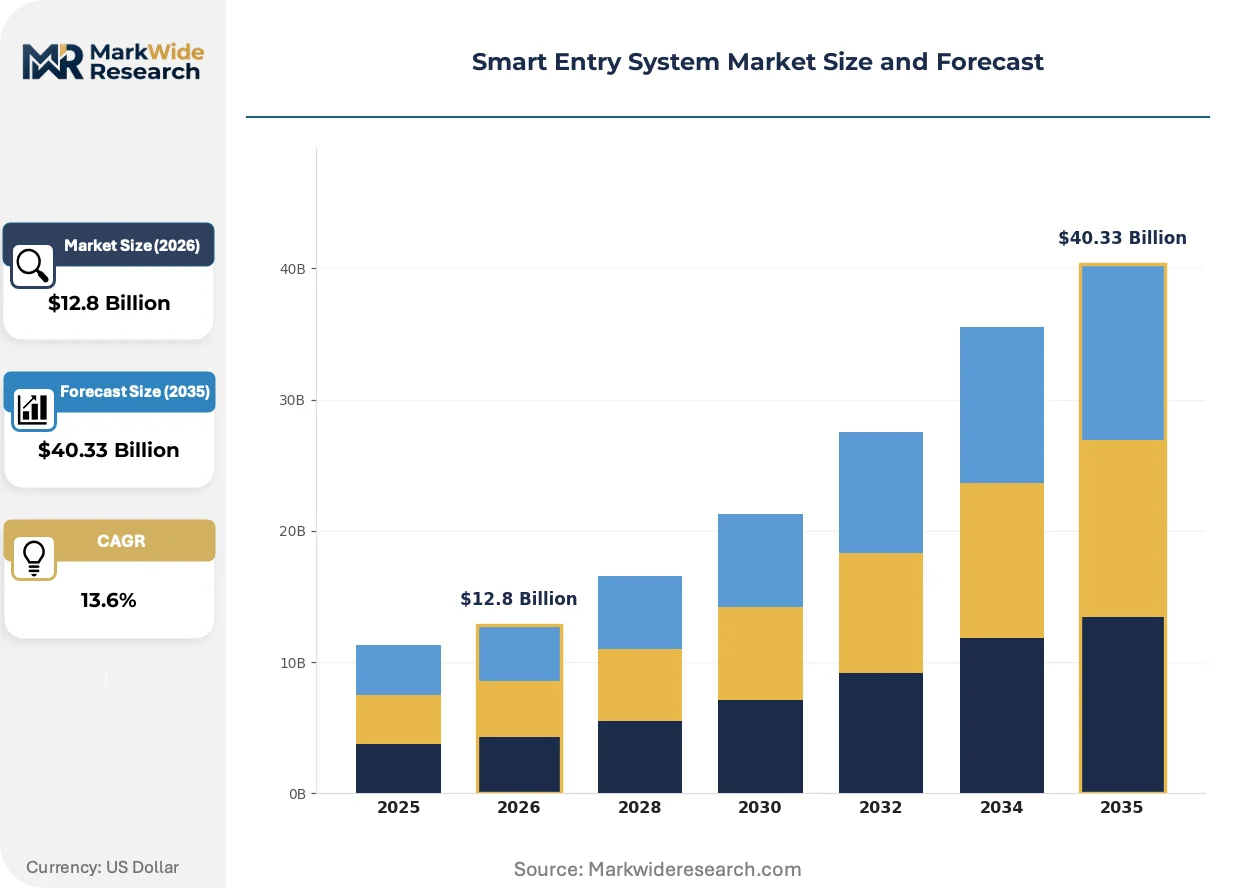
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $40.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Locks, Biometric Systems, RFID Readers, Keyless Entry Systems Technology: Bluetooth, Wi-Fi, Z-Wave, Zigbee End User: Residential, Commercial, Industrial, Government Application: Access Control, Home Security, Time Attendance, Visitor Management |
| Companies Covered | ASSA ABLOY AB, Continental AG, DENSO Corporation, Bosch, Valeo SA, Lear Corporation, NEC Corporation, Suprema Inc., Safran Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Entry System Market Evolving Landscape
Wireless protocol convergence and regulatory encryption mandates are compressing hardware margins while expanding software-service revenue pools across automotive and building-access segments.
Ultra-wideband positioning technology is integrating with Bluetooth Low Energy to deliver centimeter-accurate passive entry for vehicles and high-security facilities. German automotive suppliers are adopting this stack for hands-free trunk access. The technology is integrating biometric authentication with spatial awareness, enabling occupancy detection and personalized climate pre-conditioning.
China's SAMR is tightening GB standard enforcement on biometric data localization, requiring domestic cloud infrastructure for commercial access systems. Manufacturers serving the Chinese market must establish separate firmware branches. Smart city contractors in Beijing and Chengdu are selecting vendors with certified local data centers over multinational platforms.
Facility managers are unbundling hardware procurement from installation and maintenance contracts, shifting toward multi-year service agreements with guaranteed uptime. This compresses upfront equipment margins while locking in recurring revenue. The shift is most visible in Singapore's commercial real estate sector, where property technology platforms bundle access control with energy management dashboards.
Smart Entry System Market Segmentation
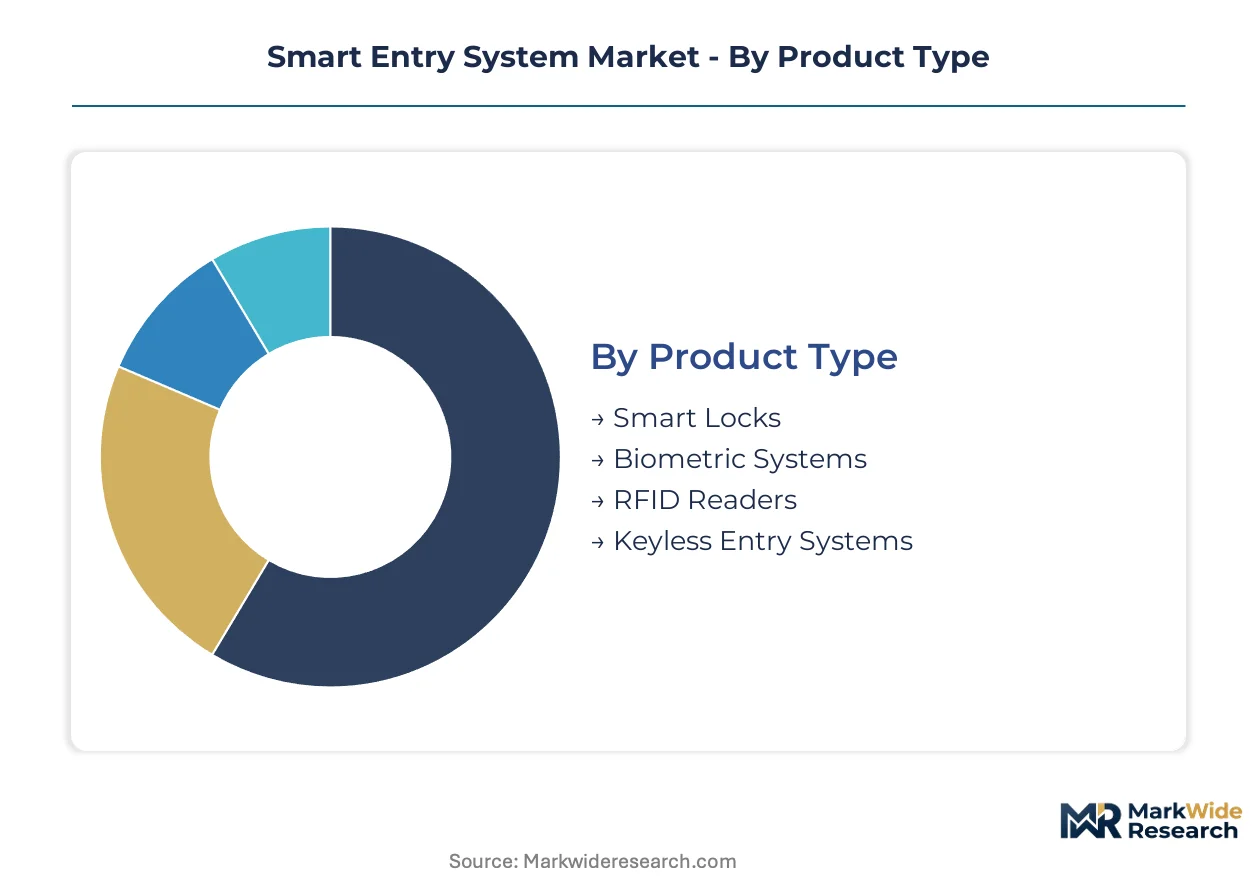
Smart entry system procurement splits sharply between retrofit-friendly consumer hardware and enterprise-grade biometric infrastructure. Vendors must engineer distinct firmware branches, certification pathways, and channel economics for each tier.
Product Type:
Standardized mass-market hardware dominates unit volumes while customized biometric installations command premium pricing and multi-year service contracts.
- Smart Locks:Battery-powered deadbolts and lever handles communicating via Bluetooth Low Energy or Wi-Fi. Residential retrofit demand in China's tier-2 cities and India's urban housing complexes concentrates volume here, though fire-safety override mandates in Germany and France add mechanical complexity.
- Biometric Systems:Fingerprint, facial-recognition, and iris-scanning modules with liveness detection and encrypted template storage. Singapore commercial landlords and Dubai property developers deploy these for tenant differentiation, while China's SAMR GB standards force domestic cloud localization.
- RFID Readers:Proximity and smart card readers for credential-based access in corporate campuses and healthcare facilities.
- Keyless Entry Systems:Automotive passive entry modules using ultra-wideband and low-frequency antenna arrays for hands-free vehicle access.
Most installed capacity flows through Smart Locks. Expansion is steepest in Biometric Systems.
Technology:
Protocol selection trades off power consumption, mesh reliability, and cloud connectivity depth against installation environment constraints.
- Bluetooth:Dominant in residential retrofit channels with smartphone-native pairing and low energy draw. ASSA ABLOY and DENSO leverage this for consumer smart locks and automotive passive entry respectively.
- Wi-Fi:Direct cloud connectivity without hub dependencies, preferred in North American DIY installations where router infrastructure is ubiquitous.
- Z-Wave:Sub-GHz mesh networking with proven building-penetration characteristics, standard in European commercial security integrations.
- Zigbee:IEEE 802.15.4-based mesh protocol with deterministic latency, favored by industrial and government end users requiring guaranteed uptime.
Bluetooth anchors current deployment volumes. Zigbee and Z-Wave are gaining share fastest in regulated commercial environments.
End User:
Customer type dictates encryption certification requirements, installation complexity, and recurring revenue potential from firmware maintenance.
- Residential:Price-sensitive consumers prioritizing smartphone convenience over hardened security. India's Bangalore and Mumbai markets show rising subscription attachment for monitoring services.
- Commercial:Office buildings, retail, and hospitality requiring audit trails and multi-credential flexibility. Singapore's property technology platforms bundle access with energy management dashboards.
- Industrial:Manufacturing and logistics facilities demanding ruggedized hardware and integration with SCADA or warehouse management systems.
- Government:Military, embassy, and critical infrastructure applications mandating FIPS 140-2 or Common Criteria certification with air-gapped operation modes.
Commercial installations generate the highest service contract attachment. Residential channels are expanding most quickly in emerging Asian markets.
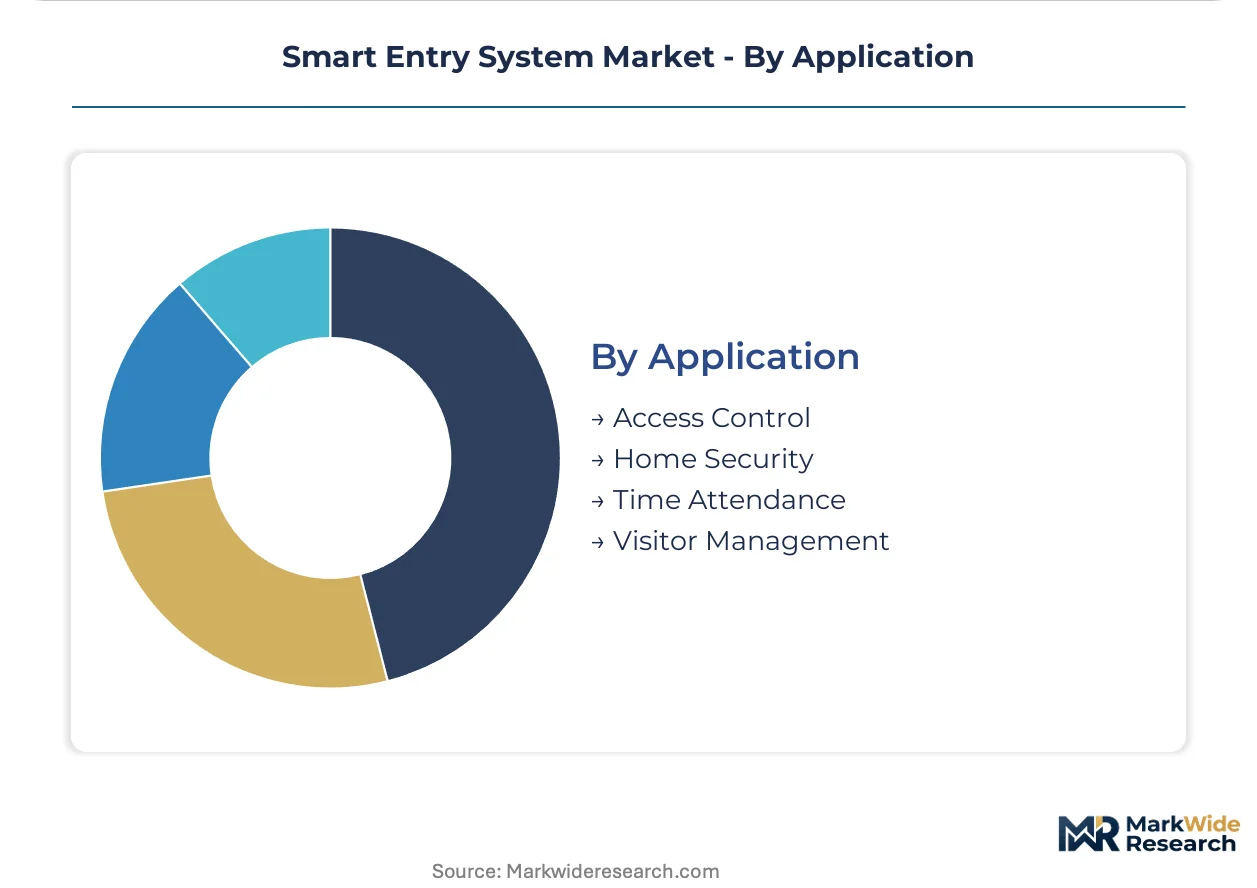
Application:
Use case specificity determines sensor fusion requirements and backend integration depth with building management or HR systems.
- Access Control:Door entry authorization with credential verification and audit logging. Bosch extends this into building-energy management through sensor-to-cloud platforms.
- Home Security:Perimeter monitoring with intrusion detection and remote alert capabilities, often bundled with video doorbells and camera systems.
- Time Attendance:Workforce clock-in/clock-out with biometric verification to prevent buddy-punching, integrating with payroll systems.
- Visitor Management:Temporary credential issuance, pre-registration workflows, and host notification systems for corporate reception areas.
Access Control absorbs the majority of hardware shipments. Visitor Management is climbing the fastest as hybrid work patterns reshape corporate reception requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Firmware engineers with AES-256 and embedded security expertise cluster in Germany's automotive corridor, Japan's Nagoya-Tokyo axis, and China's Shenzhen-Beijing tech belt. These talent concentrations anchor regional competitive positioning.
Germany
Automotive OEMs in Stuttgart and Munich drive biometric authentication integration for fleet vehicles. The KBA enforces strict cybersecurity testing protocols under NHTSA-aligned guidelines. Bavaria's manufacturing belt hosts embedded systems security engineering hubs serving Continental AG and Bosch development centers.
Japan
DENSO Corporation and NEC Corporation anchor sensor-to-cloud platform development for vehicle access systems. METI coordinates domestic semiconductor supply resilience initiatives. The Nagoya-Tokyo corridor concentrates ultra-wideband positioning R&D for hands-free automotive entry modules.
China
Smart city infrastructure projects in Beijing and Chengdu concentrate residential retrofit demand for Bluetooth-enabled smart locks. SAMR enforces GB standards mandating domestic cloud infrastructure for biometric data localization. Shenzhen's hardware ecosystem supplies battery-dependent retrofit designs for legacy building integration.
United States
NHTSA cybersecurity testing protocols shape automotive keyless-entry certification requirements for over-the-air update capabilities. The IRA indirectly supports domestic semiconductor fabrication for NFC and Bluetooth Low Energy chips. Michigan's automotive engineering corridor and California's IoT design clusters split hardware and software development functions.
Singapore
Commercial landlords deploy biometric authentication systems for tenant-convenience differentiation in prime office stock. The Personal Data Protection Commission enforces strict breach-notification obligations on facial-recognition deployments. Property technology platforms bundle access control with energy management dashboards across the central business district.
Smart Entry System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the smart entry system value chain. The market structure splits between integrated automotive suppliers with captive semiconductor programs and modular hardware vendors sourcing connectivity chips from Taiwan and South Korea. Three archetypes dominate: automotive OEM-integrated tier-1s, architectural hardware incumbents with commercial real estate channels, and biometric specialists with government certification depth. Competitive moves concentrate on M&A for encryption-software capabilities and strategic partnerships for local cloud infrastructure in China.
Within the automotive-integrated tier, Continental AG and DENSO Corporation exemplify deep OEM relationship models. ASSA ABLOY AB anchors the architectural hardware archetype with European infrastructure project dominance. Among biometric specialists, NEC Corporation and Suprema Inc. occupy positions requiring FIPS 140-2 or Common Criteria certification for government and critical infrastructure applications.
| Leading Market Players |
|---|
| ASSA ABLOY AB |
| Continental AG |
| DENSO Corporation |
| Bosch |
| Valeo SA |
| Lear Corporation |
| NEC Corporation |
| Suprema Inc. |
| Safran Group |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement offices in Stuttgart and Munich anchor pricing power through multi-year platform contracts that compress hardware margins while expanding firmware-service revenue pools. Facility managers in Singapore commercial real estate are unbundling hardware procurement from installation contracts, shifting toward subscription-based uptime guarantees that reshape supplier pricing models.
Pricing Analysis
Bundled service contracts versus unbundled hardware transactions define the dominant pricing split across the smart entry system value chain. Three-tier pricing structure across premium biometric, standard RFID, and economy Bluetooth tiers separates certification-grade government installations from consumer retrofit hardware. Price differentiation rests on AES-256 encryption certification and domestic cloud infrastructure compliance in China. Cost compression in residential Bluetooth locks is intensifying because battery-dependent designs for legacy European buildings add mechanical fallback component costs. Residential consumers in India's tier-2 cities show highest price sensitivity, while government buyers in Germany and Japan accept premium positioning for FIPS 140-2 certified systems.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles handle hub-and-spoke patterns for finished smart lock inventory serving retrofit channels. Taiwan and South Korea dominate NFC and Bluetooth Low Energy chip fabrication, while China's Shenzhen ecosystem supplies battery-powered mechanical assemblies. Raw material dependencies include lithium-ion cells, rare-earth magnets for motor actuators, and AES-encryption processor cores. Single-source vulnerability in Taiwanese semiconductor foundries exposes manufacturers to allocation volatility during demand spikes. Distribution runs through architectural hardware distributors for commercial projects and direct-to-installer platforms for residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart entry system market functions as a regulatory compounder where the EU Cyber Resilience Act's encryption-certification mandates are forcing replacement cycles across European installed bases. Compliance-driven demand expansion creates defensive moats for certified suppliers while raising barriers for uncertified competitors.
For Market Incumbents: Deploy firmware-service revenue expansion as the primary defensive lever against margin compression in commoditized Bluetooth hardware. ASSA ABLOY and DENSO should deepen backward integration into encryption-software capabilities through targeted acquisition of embedded security engineering teams. Channel control through exclusive distributor relationships in India's emerging retrofit markets protects against Chinese hardware flooding. Certification investment in GB standards compliance for SAMR-mandated biometric data localization secures access to Beijing and Chengdu smart city contracts.
For New Entrants and Emerging Players: Capture India's residential retrofit channel in Bangalore and Mumbai where smart lock penetration remains low but security-service subscriptions are climbing. Underpenetrated healthcare facility convergence applications—patient-room access integrating nurse-call and asset-tracking—offer bundled procurement entry points. A direct-to-installer platform strategy bypassing established architectural hardware distributors reduces customer acquisition costs in price-sensitive emerging markets.
For Investors and Strategic Acquirers: Automotive tier-1 suppliers with captive OEM relationships are the most active acquirer in this space, seeking encryption-software capabilities to meet NHTSA cybersecurity testing mandates. The five-to-ten year viability window favors vendors with dual certification depth in both automotive and commercial building access segments. Acquisition target archetype: biometric specialists with FIPS 140-2 certification and established government channel relationships. The signal to watch is SAMR enforcement intensity on GB standard biometric data localization requirements, which will force multinational platform exits from Chinese commercial access contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Encryption-Software Acquisition | Continental AG and Bosch acquire embedded security firms to meet EU Cyber Resilience Act firmware mandates. |
| Local Cloud Infrastructure Partnership | Biometric vendors establish certified Chinese data centers to comply with SAMR GB standards enforcement. |
| Ultra-Wideband Platform Integration | DENSO and NEC Corporation integrate UWB positioning with Bluetooth Low Energy for hands-free automotive entry. |
| Healthcare Facility Convergence Development | Suprema Inc. and Safran Group bundle patient-room access with nurse-call systems for hospital procurement. |
| India Residential Channel Expansion | ASSA ABLOY and Valeo SA build installer networks in Bangalore and Mumbai for retrofit smart lock demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a complete demand-and-supply picture. Primary conversations with automotive OEM platform engineers, commercial real estate facility managers, embedded systems security firmware developers, smart city procurement officers, and biometric system integrators supplied forward-looking demand signals. Secondary validation drew from NHTSA cybersecurity testing protocols, EU Cyber Resilience Act implementation guidance, SAMR GB standard filings, IHS Markit vehicle production databases, and commercial building permit records. Bottom-up unit shipment modeling and top-down value chain triangulation cross-checked segment estimates.
Historical reference periods anchored the projection horizon through verified installed base measurements and replacement cycle analysis. The analytical framework modeled segmentation across product type, connectivity protocol, end-user vertical, and application use case, with additional dimensioning by encryption certification tier and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to biometric penetration rates in commercial real estate and Bluetooth smart lock retrofit velocity in Asian residential markets. Industry-specific inputs included automotive content-per-vehicle trajectories for passive entry modules and fire-safety code compliance rates affecting mechanical fallback requirements.
Semiconductor allocation volatility, regulatory enforcement timing shifts, and smart city budget cycle delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on encryption-certification adoption curves and OEM platform standardization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
Global Industrial Security Systems Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Keyless Entry System Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Digital Security Control Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Access Control Market
Access Control Systems
Latin America Smart Lock Market