
 Germany Identity Verification and Authentication Market | 2026-2036
Germany Identity Verification and Authentication Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Identity Verification and Authentication Market Foresight
Platform licensing revenue is reconfiguring competitive economics as vendors bundle verification APIs into recurring SaaS contracts. IDnow leverages its video-identification infrastructure to dominate regulated banking onboarding. Thales anchors its position through hardware security module integration with government credential systems. Experian differentiates via cross-border data orchestration linking German credit bureaus to international KYC networks.
Identity verification and authentication encompasses systems that validate claimed identities through credential comparison, biometric matching against ISO/IEC 30107 presentation attack detection standards, and cryptographic proofing of device and user binding. These systems serve commercial and governmental entities requiring non-repudiable trust establishment before transactional or access authorization. Biometric verification methods capture expanding margin pools as liveness detection complexity rises, while knowledge-based authentication faces structural compression from synthetic identity fraud. Cloud-based deployment models lead volume adoption among mid-market e-commerce firms, though hybrid architectures sustain premium pricing in BFSI and government sectors where data residency requirements persist.
BSI technical guidelines for eIDAS-compliant identity systems, GDPR Article 32 security mandates, and BaFin outsourcing circulars collectively shape product certification pathways and vendor qualification timelines. The EU AI Act's risk classification for biometric identification systems will impose additional conformity obligations on behavioral analytics and facial recognition deployments. Stakeholders must monitor regulatory divergence between federal procurement standards and sector-specific supervisory expectations as compliance costs become a primary vendor selection filter.
Market Dynamics
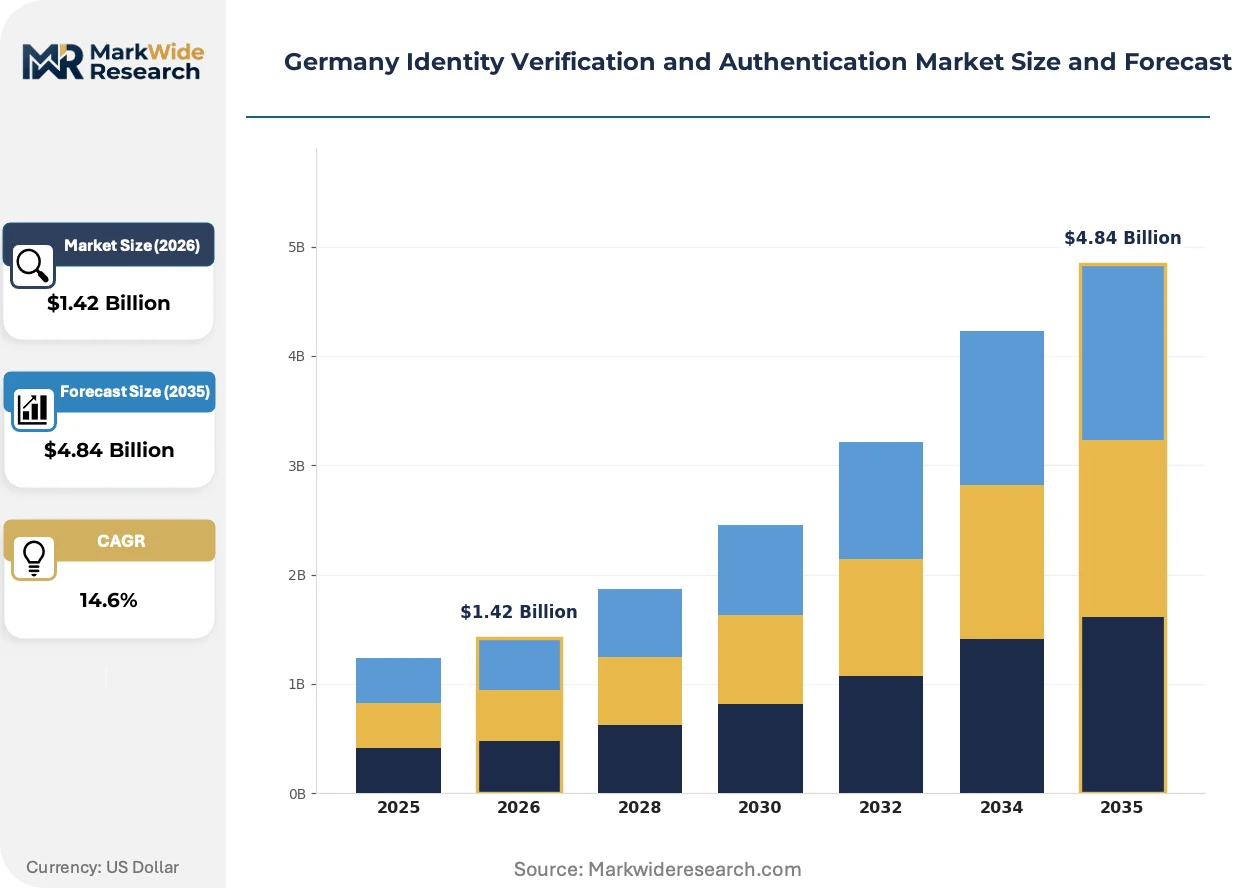
Platform licensing economics are restructuring vendor revenue models across German identity verification markets as API-based SaaS contracts displace perpetual software licenses. This shift concentrates margin capture among vendors with scalable cloud infrastructure and certified compliance pipelines.
Growth Catalysts
- BSI eID Framework Mandates:The Bundesamt für Sicherheit in der Informationstechnik technical guidelines for eIDAS-compliant systems compel banking and government procurement toward certified vendors. Federal digital service portals require standardized identity proofing.
- BaFin Outsourcing Circulars:Financial supervisors mandate auditable identity verification for remote customer onboarding. German banking institutions accelerate API procurement to meet regulatory timelines.
- Automotive Supplier Digitization:Bavaria-based automotive component manufacturers deploy workforce identity systems for zero-trust factory networks. Industrial IoT access controls drive biometric authentication procurement.
Market Restraints
- Certification Timeline Compression:BSI and eIDAS conformity assessments extend vendor qualification cycles to 18-24 months. New market entrants face structural barriers from accumulated compliance debt.
- Hardware Security Module Concentration:Thales and limited European suppliers dominate FIPS 140-2 Level 3 certified HSM production. Component scarcity constrains high-assurance deployment scaling.
- Synthetic Identity Fraud Escalation:Knowledge-based authentication methods face displacement from deepfake-enabled document forgery. Legacy verification stacks require costly biometric retrofitting.
Strategic Opportunities
- Behavioral Biometric Convergence:Keystroke dynamics and mouse-movement analytics merge with facial recognition for continuous authentication. Fintech platforms in Berlin-Brandenburg pilot passwordless transaction workflows.
- EU AI Act Risk Classification:Biometric identification systems face high-risk categorization with conformity obligations. First-mover vendors capturing notified body certifications secure federal procurement preference.
- Mid-Market E-Commerce Penetration:Cloud-native verification APIs remain underdeployed among German SME retailers. Subscription pricing models lower adoption barriers for marketplace sellers.
Industry Challenges
- ISO/IEC 30107-3 PAD Expertise Scarcity:Presentation attack detection engineering for liveness verification requires specialized computer vision talent. German universities produce insufficient biometric security graduates.
- Hybrid Architecture Integration Friction:Enterprises with on-premise legacy identity stores struggle to orchestrate cloud-based verification APIs. Data residency requirements complicate multi-cloud deployments.
- GDPR Article 32 Security Mandate Interpretation:Variable supervisory authority guidance on biometric data retention creates compliance uncertainty. Vendors face divergent technical implementation demands across German states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Identity Verification and Authentication Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Verification Method: Biometric, Knowledge-Based Authentication, Token-Based, Multi-Factor Authentication, Behavioral Analytics, Certificate-Based Solution Type: Identity Proofing, Access Management, Fraud Detection, Credential Management, Risk-Based Authentication, Privileged Account Management End User Sector: BFSI, Government Bodies, Telecom Operators, E-Commerce Firms, Educational Institutions, Transportation Providers Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services, API Integration, Edge Deployment |
| Companies Covered | IDnow, IDMERIT, Experian, Verimi, WebID, Thales, KYC Germany, Nect, IDEMIA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Identity Verification and Authentication Market Shifts & Advancements
Decentralized identity architectures and passwordless authentication protocols are compressing traditional credential-based security models. German enterprises pilot self-sovereign identity frameworks while regulators finalize interoperability standards.
Passive facial liveness detection is digitizing remote onboarding workflows for German banking institutions. The technology eliminates active user challenges through single-frame analysis. Deutsche Kreditbank and regional Sparkassen deploy these APIs for mobile account opening. Compliance teams reduce video-identification session abandonment while maintaining BaFin audit trails.
GDPR Article 9 biometric data processing restrictions are tightening vendor liability frameworks across German federal states. Supervisory authorities in Berlin and Hamburg issue divergent guidance on lawful basis documentation. Automotive and industrial IoT deployments face heightened consent mechanism requirements. Vendors invest in edge-based processing to minimize central biometric storage.
Consumption patterns among German enterprises favor outcome-based verification pricing over per-transaction models. Mid-market e-commerce platforms negotiate guaranteed false-acceptance-rate contracts. Risk transfer to vendors accelerates among marketplace operators in Munich and Hamburg. Insurance-backed verification guarantees emerge as competitive differentiators for high-value transaction segments.
Germany Identity Verification and Authentication Market Segmentation
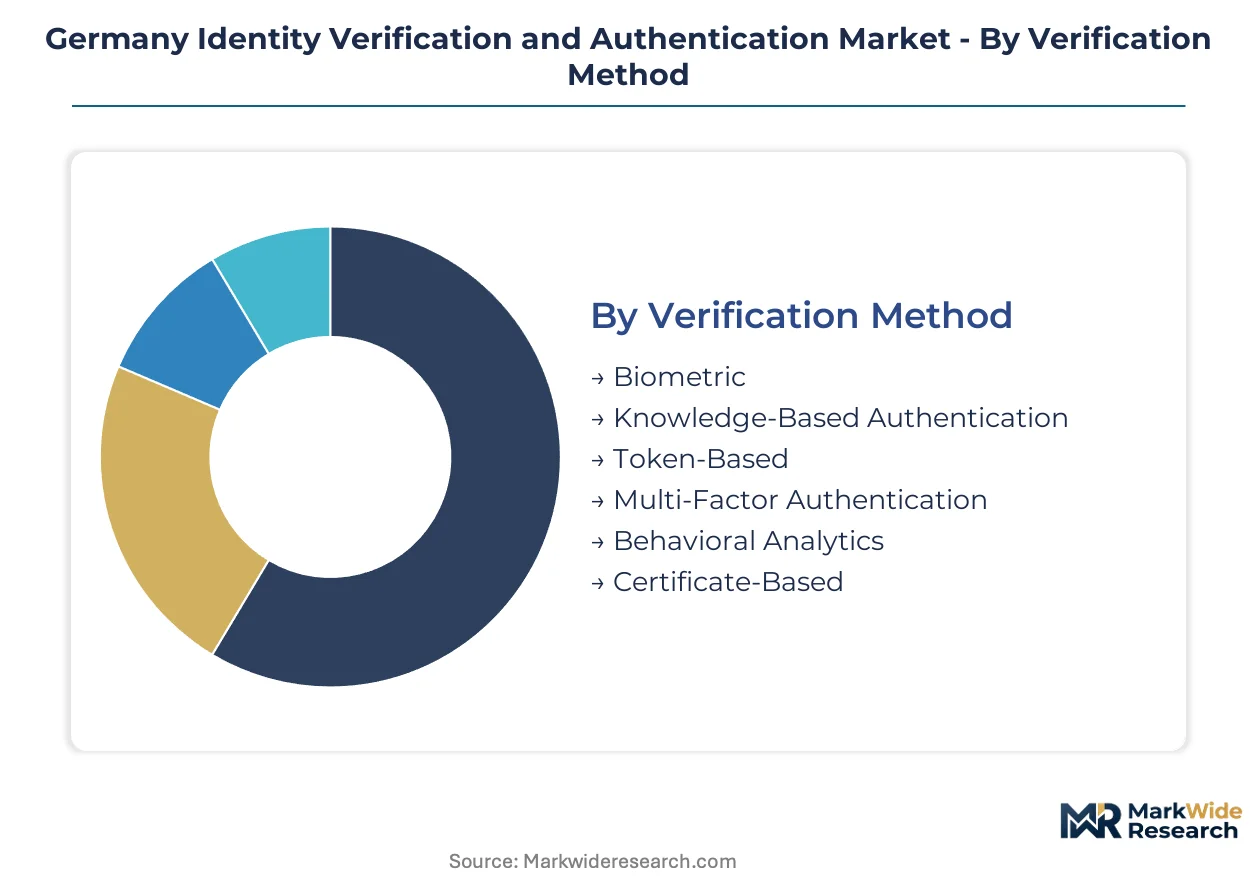
German enterprises select identity verification architectures based on regulatory exposure, transaction velocity, and data residency constraints. Segment boundaries blur as vendors bundle proofing, authentication, and fraud detection into unified platforms. Procurement cycles vary dramatically across deployment models and end-user sectors.
Verification Method:
Biometric systems refresh every 18-24 months as liveness detection standards tighten, while certificate-based infrastructure persists for 7-10 years in government credentialing. Knowledge-based methods face accelerated replacement cycles due to synthetic identity fraud.
- Biometric:Facial recognition with ISO/IEC 30107-3 presentation attack detection dominates banking onboarding in Berlin-Brandenburg. Bavarian automotive suppliers deploy fingerprint and iris matching for factory floor access control. Regulatory pressure from the EU AI Act high-risk classification drives continuous algorithm updates.
- Knowledge-Based Authentication:Static security questions face structural decline across German BFSI as deepfake-enabled document forgery escalates. Remaining deployments concentrate in legacy insurance policy administration where biometric retrofitting costs exceed fraud exposure.
- Token-Based:Hardware security keys with FIPS 140-2 certification anchor federal employee authentication. Supply constraints from limited European HSM manufacturers extend procurement timelines.
- Multi-Factor Authentication:SMS and TOTP combinations remain standard for mid-market e-commerce platforms in Hamburg and Munich. Push notification methods gain share among fintech applications.
- Behavioral Analytics:Keystroke dynamics and mouse-movement tracking pilot in Berlin fintech passwordless workflows. GDPR Article 9 consent requirements complicate deployment.
- Certificate-Based:eIDAS-qualified electronic signatures anchor German federal digital service portals. Long infrastructure lifecycles limit vendor switching.
Certificate-based infrastructure dominates installed base. Biometric verification is where expansion concentrates.
Solution Type:
Cost tier differentiation separates enterprise-grade platforms with BSI certification from lightweight API offerings targeting SME retailers. Identity proofing commands premium pricing due to regulatory liability concentration.
- Identity Proofing:Document verification with video-identification or passive liveness detection anchors regulated banking onboarding. BSI eID framework mandates concentrate demand among certified vendors serving Deutsche Kreditbank and Sparkassen networks.
- Access Management:Zero-trust architecture adoption among Bavarian automotive suppliers drives workforce authentication procurement. Convergence with privileged account management blurs segment boundaries.
- Fraud Detection:Real-time transaction scoring with device fingerprinting serves Munich-based marketplace operators. Insurance-backed verification guarantees emerge as competitive differentiators.
- Credential Management:Self-service password reset and lifecycle administration remain cost-pressured commoditized functions. Mid-market penetration lags in German SME retail.
- Risk-Based Authentication:Step-up challenges triggered by behavioral anomalies pilot in Berlin-Brandenburg fintech platforms. Integration friction with legacy identity stores constrains deployment.
- Privileged Account Management:Industrial IoT access controls for automotive supplier factory networks command premium pricing. Thales hardware security module integration anchors high-assurance deployments.
Identity proofing captures the steepest expansion trajectory. Credential management remains the most cost-pressured tier.
End User Sector:
Volume concentration varies sharply: BFSI generates highest per-seat spending while e-commerce drives transaction-scale economics. Government procurement cycles extend 24-36 months due to BSI certification requirements.
- BFSI:BaFin outsourcing circulars mandate auditable identity verification for remote customer onboarding. API procurement accelerates among banking institutions meeting regulatory timelines.
- Government Bodies:Federal digital service portals require eIDAS-compliant identity proofing under BSI technical guidelines. Procurement concentrates among vendors with accumulated compliance certifications.
- Telecom Operators:Subscriber identity verification for SIM registration follows BSI eID framework standards. Volume scale drives per-transaction pricing pressure.
- E-Commerce Firms:Marketplace sellers in Munich and Hamburg negotiate outcome-based verification contracts with guaranteed false-acceptance rates. Cloud-native API adoption lags among SME retailers.
- Educational Institutions:Student identity verification for examination proctoring expanded during remote learning transitions. Procurement budgets remain constrained compared to commercial sectors.
- Transportation Providers:Workforce authentication for logistics and fleet management follows automotive supplier digitization patterns. Bavaria-based deployments lead adoption.
BFSI dominates installed base. E-commerce firms represent the fastest volume expansion.
Deployment Model:
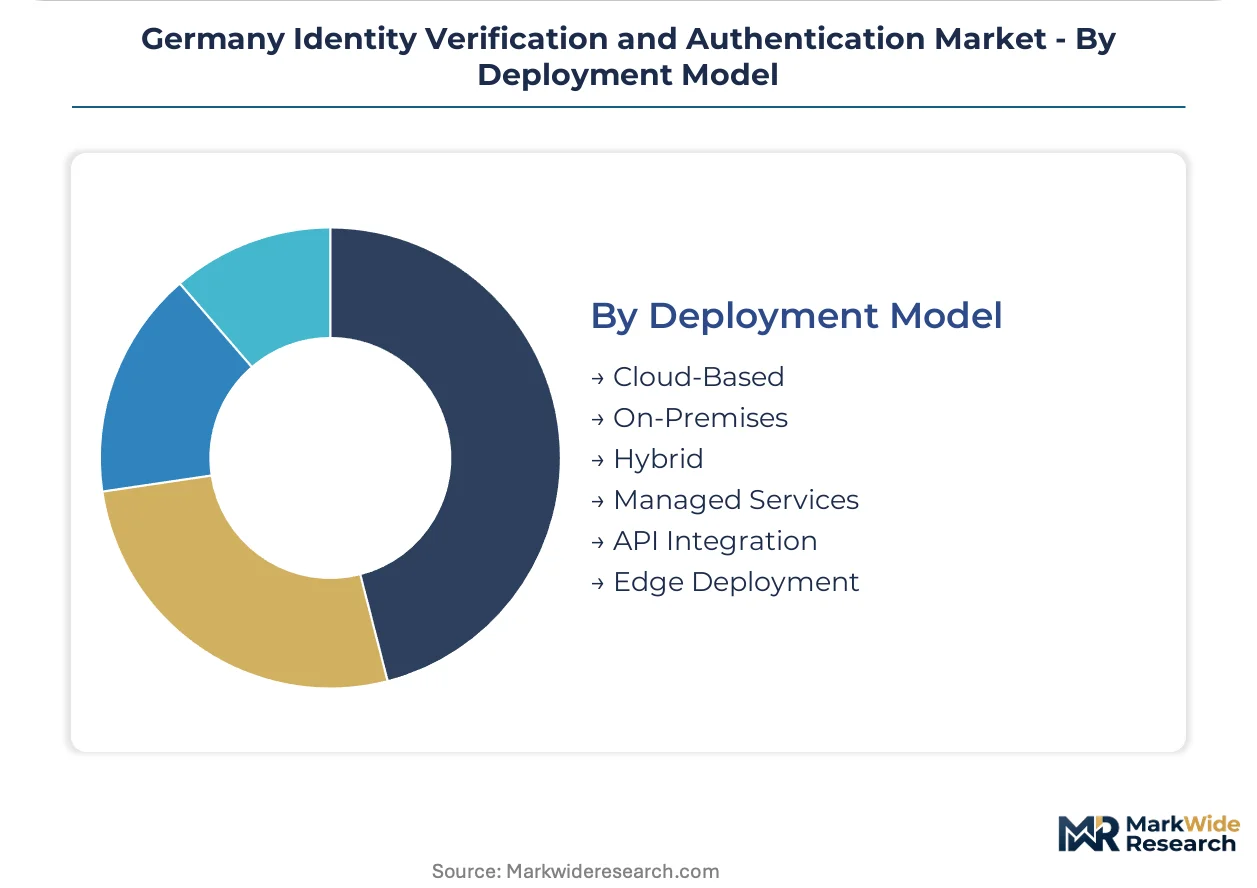
Margin structures diverge: cloud-based APIs scale efficiently but face commodity pressure, while hybrid architectures sustain premium pricing where data residency requirements persist. Edge deployment emerges as compliance-driven niche.
- Cloud-Based:SaaS verification APIs with subscription pricing lower adoption barriers for mid-market e-commerce platforms. GDPR Article 32 security mandate interpretation creates supervisory authority divergence across German states.
- On-Premises:Legacy identity store retention in Frankfurt and Düsseldorf banking headquarters constrains cloud migration. Maintenance revenue sustains incumbent vendors.
- Hybrid:Orchestration of cloud-based verification APIs with on-premise credential storage commands premium pricing in BFSI and government sectors. Integration friction extends implementation timelines.
- Managed Services:Outcome-based contracts with risk transfer to vendors accelerate among marketplace operators. Insurance-backed verification guarantees differentiate high-value transaction segments.
- API Integration:Embedded verification workflows within existing customer applications dominate fintech procurement in Berlin-Brandenburg. Developer experience becomes vendor selection criterion.
- Edge Deployment:Biometric processing on local devices minimizes central storage under GDPR Article 9 restrictions. Automotive and industrial IoT deployments in Bavaria pilot zero-trust factory networks.
On-premises infrastructure dominates legacy installed base. Cloud-based deployment is where vendor expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across German sub-regions. Berlin-Brandenburg fintechs prioritize API scalability over certification premiums, while Bavarian automotive suppliers absorb higher costs for zero-trust factory compliance. Hesse banking clusters occupy the middle ground, balancing regulatory liability with operational efficiency.
Bavaria
Automotive supplier digitization drives workforce authentication demand. The BSI eID framework mandates shape procurement for industrial IoT access controls. Munich-based component manufacturers deploy biometric systems for factory floor security, with Ingolstadt and Nuremberg clusters following.
Berlin-Brandenburg
Fintech density concentrates API-first verification procurement. BaFin outsourcing circulars accelerate cloud-native onboarding pipeline deployment. Berlin startups pilot passwordless behavioral biometric workflows, while Potsdam government tech procurement emphasizes eIDAS compliance.
North Rhine-Westphalia
Düsseldorf and Cologne banking headquarters retain hybrid identity architectures. GDPR Article 32 interpretation divergence across supervisory authorities complicates multi-cloud deployments. Legacy system integration friction extends implementation timelines for mid-tier financial institutions.
Baden-Württemberg
Industrial machinery manufacturers adopt certificate-based credentialing for supply chain access. The EU AI Act high-risk classification for biometric systems shapes vendor selection. Stuttgart engineering clusters balance innovation speed with conformity assessment accumulation.
Hamburg
E-commerce marketplace operators negotiate outcome-based verification contracts. Insurance-backed guarantees differentiate high-value transaction segments. Hanseatic trade finance traditions influence risk-transfer pricing models for SME retailer onboarding.
Germany Identity Verification and Authentication Market Competitive Landscape
Capability concentration sits with certified compliance specialists; scale advantage sits with API-native platform vendors. The market structures around three tiers: accumulated certification holders, cloud-scalable challengers, and hardware-anchored incumbents. Strategic moves concentrate on SaaS contract bundling and notified body certification racing. Partnership patterns favor orchestration between verification API providers and legacy identity store integrators.
Within the compliance-specialist tier, IDnow and Thales occupy distinct positions. IDnow leverages its video-identification infrastructure toward recurring SaaS contracts. Thales anchors through hardware security module integration with federal credential systems. Experian sits within the cross-border data orchestration archetype, linking German credit bureau networks to international KYC verification pipelines.
| Leading Market Players |
|---|
| IDnow |
| IDMERIT |
| Experian |
| Verimi |
| WebID |
| Thales |
| KYC Germany |
| Nect |
| IDEMIA |
| Others |
Supply & Pricing Matrix
Undercapacity in FIPS 140-2 Level 3 hardware security module production across European foundries is compressing supplier margins while amplifying pricing power for certified vendors serving BaFin-regulated institutions. This utilization squeeze propagates through the German identity verification stack, forcing buyers toward hybrid architectures that blend cloud API scalability with on-premise credential storage premiums.
Pricing Analysis
Recurring SaaS subscription tiers with embedded compliance certification drive lifetime value capture across German banking procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates BSI-certified enterprise platforms from lightweight API offerings, with certification grade and volume scale as the primary differentiation levers. Cost compression in mid-market e-commerce verification is intensifying because cloud-native vendors compete on per-transaction rates. SME retailers exhibit highest price sensitivity, while federal government bodies absorb premium tiers for accumulated compliance debt.
Supply Chain Analysis
Upstream feedstock in specialized biometric sensor fabrication and cryptographic processor manufacturing centers on Taiwan, South Korea, and limited European facilities in France and the Netherlands. Component sourcing draws from semiconductor foundries, optical sensor arrays, and secure element manufacturers. Single-source vulnerability in Thales-dominated HSM production constrains high-assurance deployment scaling. Distribution runs through certified systems integrators and direct API marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
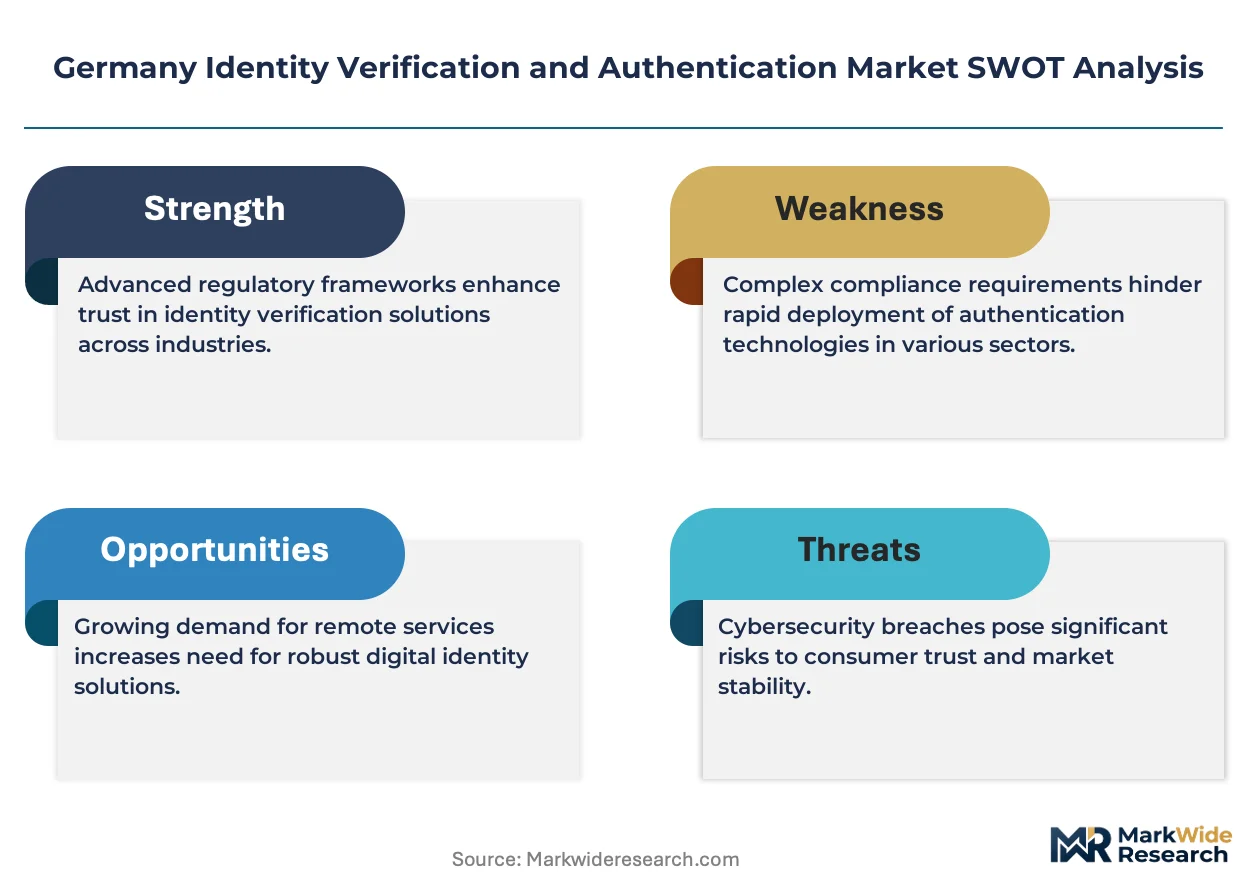
Fragmentation opportunity persists as BaFin outsourcing circulars and EU AI Act risk classifications splinter demand across compliance-specialist, cloud-scalable, and hardware-anchored vendor archetypes. Regulatory divergence between federal procurement standards and state-level supervisory guidance creates addressable niches for targeted positioning.
For Market Incumbents: Harden certification pipelines against EU AI Act high-risk conformity obligations by accelerating notified body relationships. Accumulate BSI eID framework pre-qualifications to defend against cloud-native challengers eroding banking API margins. Vertical integration into edge-based biometric processing offsets GDPR Article 9 liability concentration. For New Entrants and Emerging Players: Mid-market e-commerce platforms in Hamburg and Munich represent the most penetrable entry point, with outcome-based verification contracts and insurance-backed guarantees as the differentiated wedge. Cloud-native SaaS pricing with subscription models lowers adoption barriers among SME retailers underserved by incumbent certification complexity. Target automotive supplier digitization in Bavaria through zero-trust workforce authentication pilots. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native verification API development, compressing funding requirements for scalable challengers. Long-term viability over the coming decade favors vendors with orchestration capabilities bridging legacy identity stores and modern biometric stacks. Acquisition target archetype: mid-tier platforms with BSI certification momentum and developer-centric API documentation. The signal to watch is notified body certification queue lengths as procurement preference discriminator.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Racing | First-mover vendors capturing EU AI Act high-risk conformity secure federal procurement preference against uncertified rivals. |
| Hybrid Architecture Integration Partnership | Orchestration agreements between cloud API providers and legacy identity store integrators unlock BFSI and government premium pricing tiers. |
| Edge-Based Biometric Processing Investment | Local device processing minimizes central biometric storage under GDPR Article 9 restrictions for automotive IoT deployments. |
| Outcome-Based Contract Structuring | Guaranteed false-acceptance-rate pricing with risk transfer differentiates vendors among Munich and Hamburg marketplace operators. |
| Behavioral Biometric Convergence Development | Keystroke dynamics and mouse-movement analytics merged with facial recognition pilot passwordless workflows in Berlin-Brandenburg fintech. |
Research Methodology
Initial hypotheses were tested against primary input from identity verification platform CTOs, BaFin compliance officers at German banking institutions, BSI certification auditors, and automotive supplier IT security directors and refined through secondary validation. Primary fieldwork combined structured interviews with procurement leads at Deutsche Kreditbank and Sparkassen networks alongside integration specialists at Thales and IDnow. Secondary sources encompassed BSI technical guideline releases, BaFin outsourcing circulars, EU AI Act regulatory filings, and eIDAS interoperability framework documentation. Bottom-up transaction volume modeling and top-down market sizing triangulated segment-level outputs.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across verification method, solution type, end user sector, and deployment model dimensions. CAGRs were derived from regression analysis of historical procurement cycle data and regulatory mandate implementation timelines. Industry-specific forecast inputs included BSI certification queue projections and BaFin audit trail requirement phase-in schedules.
Practitioners should monitor BSI guideline revision cycles, EU AI Act delegated act releases, and FIPS 140-2 Level 3 HSM production capacity announcements for early signals of forecast deviation. Cross-checking against BSI-published vendor certification lists and BaFin supervisory circular archives is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
North America Biometrics in Government Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Asia-Pacific Government and Security Biometrics Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Global Personal Identity Management Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Identity Theft Protection Services Market