
 Europe Access Control Hardware Market | 2026-2036
Europe Access Control Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Access Control Hardware Market Foresight
Aftermarket service revenue is rewriting margin allocation across the Europe Access Control Hardware Market. ASSA ABLOY AB leverages its installed base of electromechanical locks to capture recurring maintenance contracts. Nedap N.V. anchors its position through specialized vehicle and reader integration for parking and perimeter applications.
Access control hardware encompasses physical security devices—card readers, biometric scanners, electronic locks, and keypads—typically operating on 12-24V DC power with IP65+ ingress protection for outdoor durability, designed to authenticate credentials and manage entry points in commercial, industrial, and institutional facilities. Biometric and cloud-based technology segments are outpacing wired legacy systems as organizations prioritize contactless authentication and centralized credential management. Card readers and electronic locks retain the largest installed base, though wireless retrofit installations are gaining traction in aging European building stock where cabling replacement proves cost-prohibitive.
The EU AI Act, GDPR, and CE marking under the MDR framework collectively shape product development by mandating algorithmic transparency for biometric systems, restricting data retention periods, and enforcing electromagnetic compatibility and safety standards for electronic locking mechanisms. ETSI cybersecurity certification requirements for connected access devices add another compliance layer for manufacturers seeking market access across member states. Stakeholders must evaluate whether their biometric processing architectures can satisfy both GDPR data minimization principles and the EU AI Act's risk-classification thresholds without fragmenting product lines across national implementations.
Market Dynamics
Biometric authentication systems are displacing card-based credentials across European enterprise campuses, forcing hardware vendors to reengineer product architectures for GDPR data minimization and EU AI Act algorithmic transparency compliance simultaneously.
Growth Catalysts
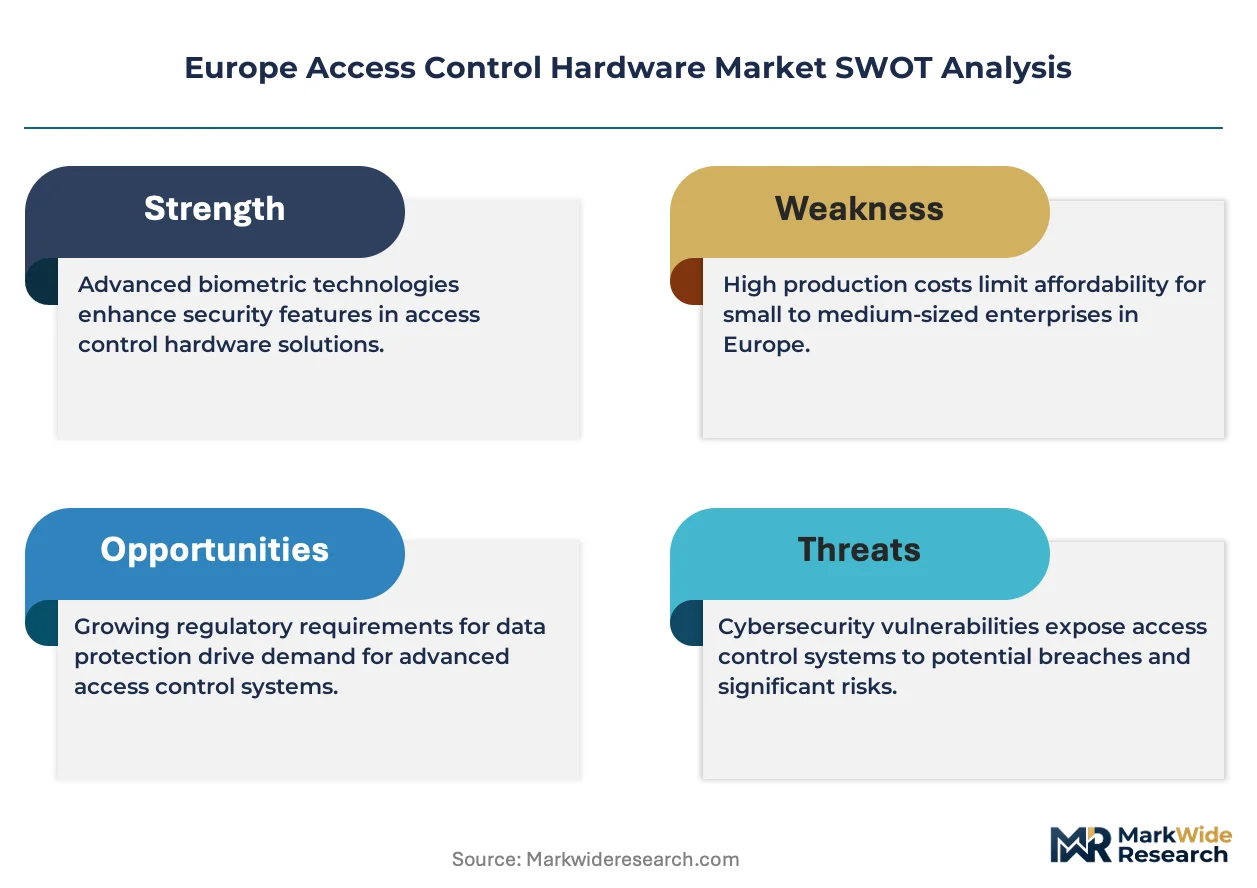
- EU AI Act risk classification:High-risk biometric system mandates are accelerating procurement of certified facial recognition hardware in France and Germany's smart building retrofit programs.
- Industrial facility hardening:Germany's manufacturing sector is expanding perimeter access control deployments to protect critical infrastructure against physical intrusion threats.
- Wireless retrofit technology:Battery-powered electronic locks eliminate cabling costs in aging European building stock where full infrastructure replacement proves economically unviable.
Market Restraints
- Semiconductor supply concentration:Microcontroller shortages from Asian foundries continue disrupting lead times for electronic lock and reader manufacturing.
- GDPR compliance costs:Biometric data processing requirements impose substantial legal and technical overhead on hardware vendors seeking multi-country deployment.
- Copper and rare earth volatility:Electromechanical lock production faces margin pressure from fluctuating magnet and wiring material input costs.
Strategic Opportunities
- Poland and Eastern Europe expansion:Underpenetrated commercial real estate markets offer first-mover advantage for cloud-integrated access control systems.
- Healthcare facility mandates:CSRD reporting requirements are driving hospital procurement of audit-trail-capable biometric systems for staff access tracking.
- Mobile credential convergence:Integration of Bluetooth Low Energy with existing reader infrastructure opens retrofit revenue streams without full hardware replacement.
Industry Challenges
- Cybersecurity certification timelines:ETSI certification processes for connected access devices extend product launch schedules by 8-14 months.
- Legacy system integration:Proprietary protocols from installed electromechanical lock bases complicate unified credential management platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Access Control Hardware Market |
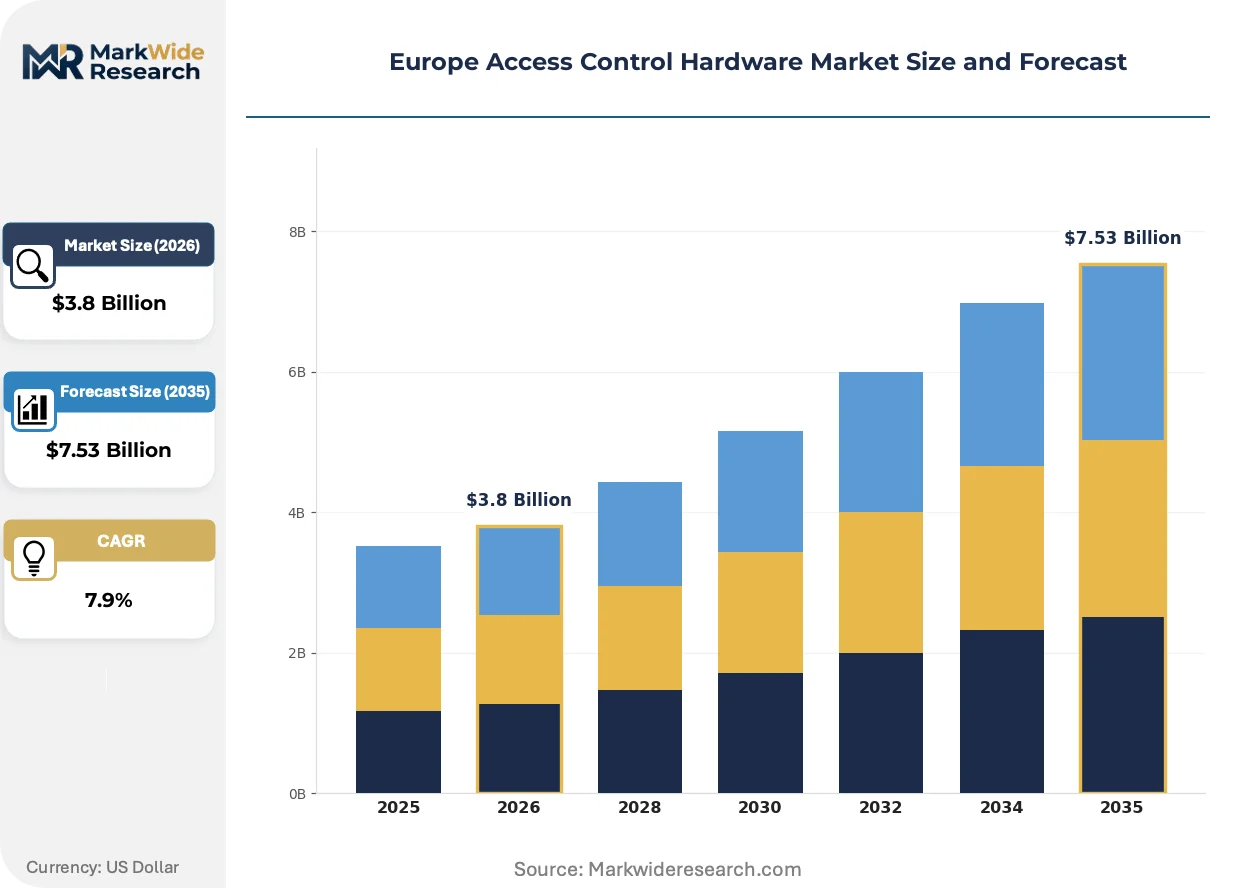
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card Readers, Keypads, Biometrics, Locks Technology: Wired, Wireless, Cloud-Based, Standalone End User: Commercial, Residential, Government, Industrial Installation Type: New, Retrofit, Integrated, Upgraded |
| Companies Covered | Honeywell International Inc., Nedap N.V., ASSA ABLOY AB, Siemens AG, Bosch, Dormakaba Holding AG, Johnson Controls International plc, Axis Communications, Allegion Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Access Control Hardware Market Shifts & Advancements
Contactless authentication architectures are compressing hardware replacement cycles across European commercial real estate, while regulatory pressure on biometric data handling forces simultaneous innovation in edge processing and privacy-preserving algorithm design.
Edge-based facial recognition with on-device template matching is rendering obsolete centralized biometric database architectures that previously dominated enterprise access control. German automotive manufacturers and French banking headquarters are deploying these systems at scale to eliminate network-dependent authentication latency. The shift is rendering obsolete traditional server-room biometric infrastructure investments and redirecting capex toward hardened endpoint hardware.
The EU AI Act's high-risk system classification is forcing biometric hardware vendors to implement algorithmic transparency documentation and human oversight interfaces by default. CE marking under MDR electromagnetic compatibility standards now overlaps with cybersecurity certification requirements, creating compound compliance burdens. French smart building integrators are responding by consolidating vendor relationships around suppliers with pre-certified product lines.
Facility managers are unbundling after-sales service contracts from initial hardware procurement, creating discrete revenue streams for maintenance and firmware update subscriptions. Systems integrators in Germany's industrial corridor are replacing bundled multi-year agreements with metered service tiers based on device count and authentication volume. This restructuring is most visible in Frankfurt and Munich's commercial property management sector, where operating expense optimization overrides capital expenditure preferences.
Europe Access Control Hardware Market Segmentation
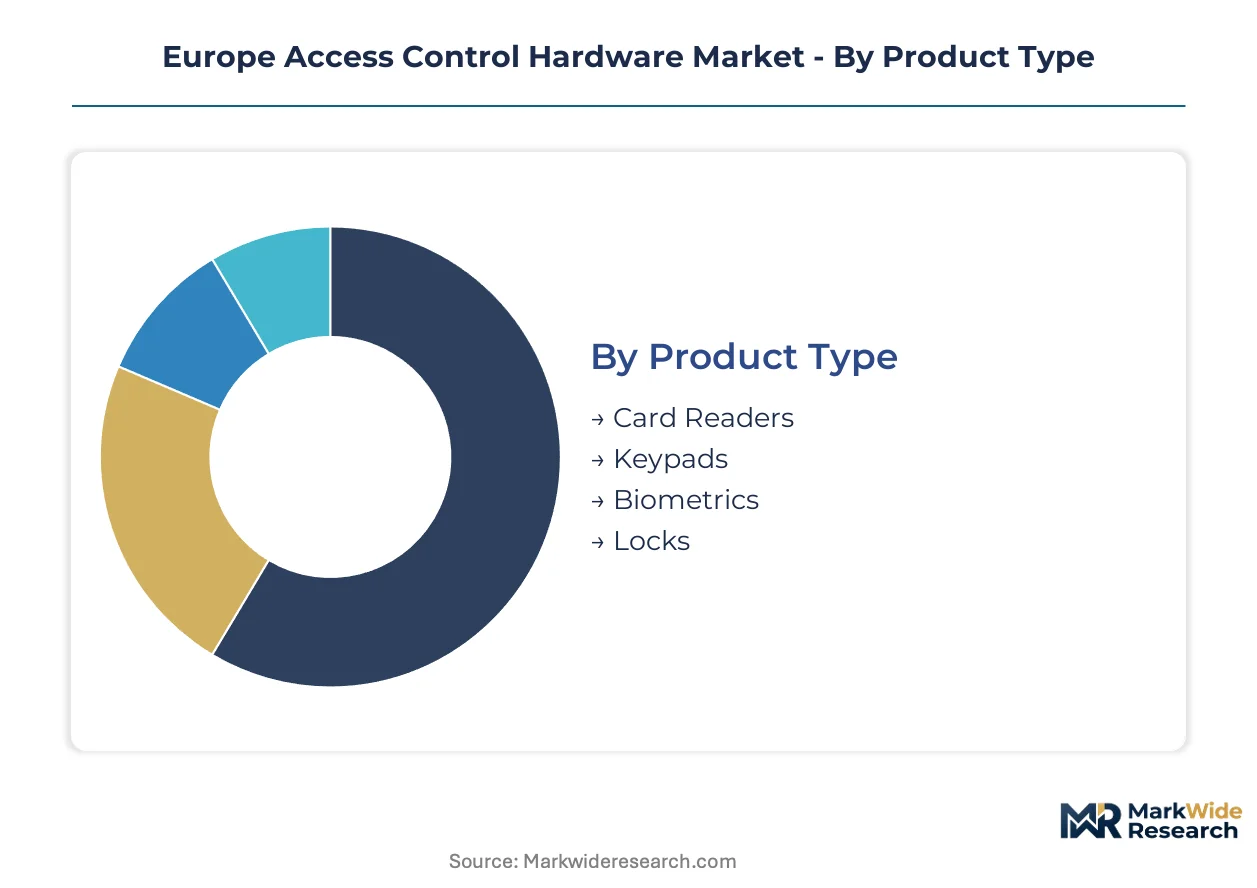
Segmentation in the Europe Access Control Hardware Market reveals divergent technology lifecycles and compliance burdens across product architectures. Understanding these divisions exposes where GDPR data minimization and EU AI Act mandates reshape procurement priorities.
Product Type:
Mature electromechanical hardware dominates installed bases while biometric systems emerge as the fastest-expanding category under regulatory pressure.
- Card Readers:Proximity and smart card readers operating on 13.56 MHz frequency constitute the largest legacy footprint across German industrial facilities. France's banking sector continues standardizing on contactless credential formats despite gradual displacement by mobile alternatives.
- Biometrics:Facial recognition and fingerprint terminals with edge-processing architectures are displacing centralized biometric databases. German automotive manufacturers deploy these systems to eliminate network latency while satisfying GDPR data retention limits.
- Locks:Electromechanical and magnetic locking mechanisms retain dominance in aging European building stock where full infrastructure replacement remains cost-prohibitive.
- Keypads:PIN-entry devices persist in low-security commercial applications across Eastern European markets where budget constraints override contactless preferences.
Card readers handle the majority of throughput; biometrics is the fastest mover on share.
Technology:
Cost tier stratification separates premium cloud-integrated systems from economy standalone units, with wireless retrofits commanding mid-tier positioning.
- Wired:Hardwired RS-485 and Wiegand protocol systems anchor enterprise campus deployments requiring deterministic response times. Germany's industrial corridor maintains preference for cabled infrastructure despite installation complexity.
- Cloud-Based:Browser-managed credential platforms with API integrations are capturing mid-market commercial real estate in France's smart building retrofit programs. Centralized policy enforcement reduces per-site administrative overhead.
- Wireless:Battery-powered locks and readers eliminate cabling costs in heritage European structures where building preservation rules restrict physical modifications.
- Standalone:Offline keypad and card reader units serve isolated entry points in rural Eastern European facilities with limited IT infrastructure.
Wired infrastructure retains the largest installed base; cloud-based systems are expanding most quickly in commercial retrofits.
End User:
Application-specific compliance requirements differentiate procurement patterns across facility types, with government and industrial segments facing the steepest certification burdens.
- Commercial:Office buildings and retail properties across Frankfurt and Munich prioritize mobile credential compatibility and visitor management integration. CSRD reporting requirements are accelerating audit-trail-capable system adoption.
- Government:Municipal and federal facilities require ETSI-certified connected devices with documented algorithmic transparency under EU AI Act high-risk system classifications. French administrative buildings lead procurement of privacy-certified facial recognition hardware.
- Industrial:Manufacturing plants and logistics centers in Germany's automotive belt demand perimeter hardening against physical intrusion threats. CE marking under MDR electromagnetic compatibility standards compounds hardware selection criteria.
- Residential:Multi-tenant housing developments in Poland and Czech Republic represent underpenetrated demand for cloud-integrated intercom and entry systems.
Commercial applications generate the highest unit volume; government procurement is climbing the fastest on compliance-driven replacement cycles.
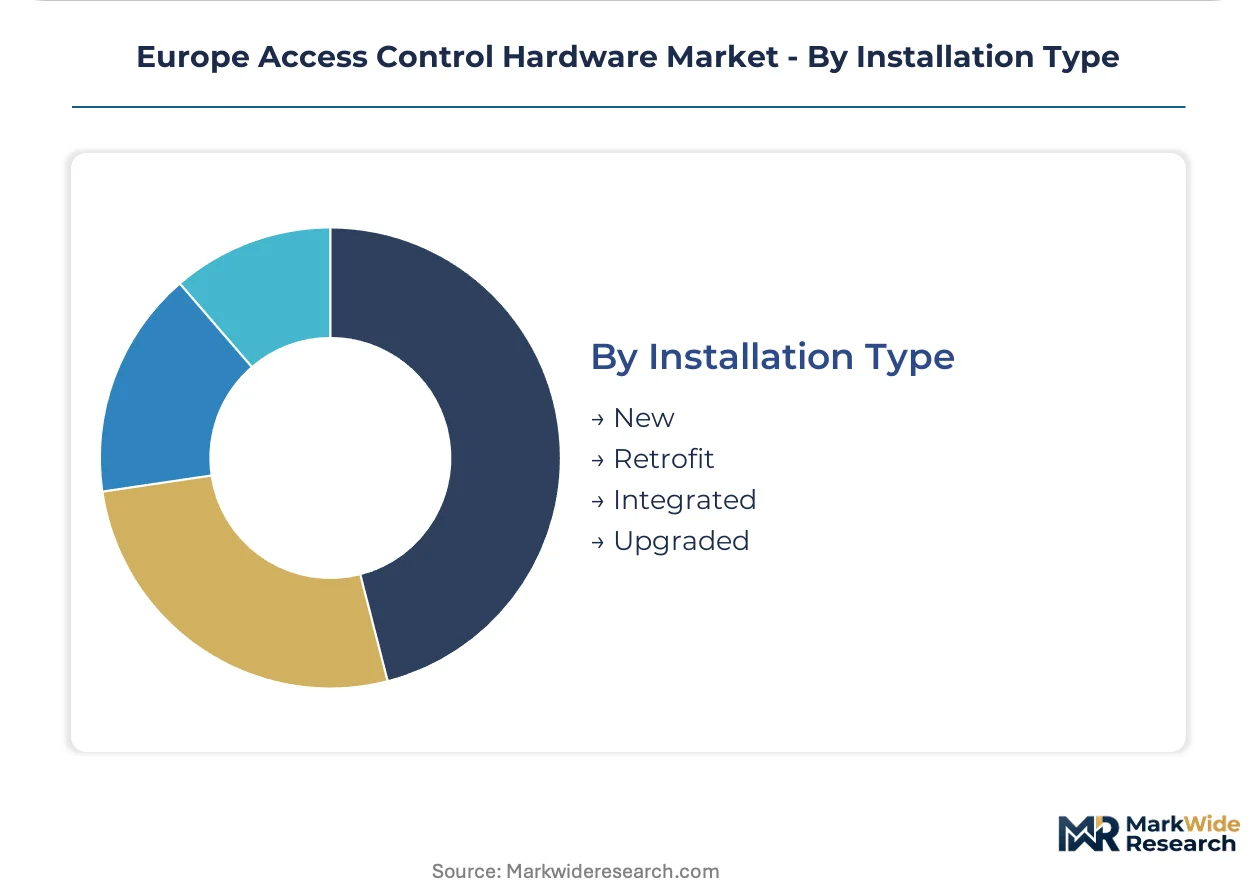
Installation Type:
Volume concentration favors retrofit deployments where wireless technology eliminates infrastructure replacement costs in aging European building stock.
- Retrofit:Wireless lock and reader installations bypass cabling replacement in pre-2000 commercial structures across France and Germany. Battery-powered electronic locks reduce deployment timelines from weeks to days.
- New:Greenfield construction in Poland's expanding commercial real estate market enables native cloud-architected system deployment without legacy protocol constraints.
- Integrated:Unified platforms combining access control with video surveillance and intrusion detection serve large German industrial campuses requiring centralized security operations.
- Upgraded:Firmware and reader module replacements extend functional life of existing electromechanical bases while adding mobile credential compatibility.
Retrofit installations command the dominant share of project volume; new construction is gaining share fastest in Eastern European expansion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Eastern European markets exhibit pronounced price elasticity, while German and French procurement teams prioritize compliance-certified systems regardless of premium positioning. This demand-elasticity contrast shapes vendor go-to-market strategies across the continent.
Germany
Automotive manufacturers and industrial facility operators dominate hardware procurement, with perimeter hardening programs accelerating biometric reader deployments. The EU AI Act's high-risk system classification mandates algorithmic transparency documentation for facial recognition installations. Munich and Frankfurt commercial property managers are unbundling after-sales service contracts from initial hardware procurement to optimize operating expenditures.
France
Smart building retrofit programs in Île-de-France drive concentrated demand for privacy-certified facial recognition hardware. GDPR data minimization requirements accelerate edge-processing biometric architectures that eliminate centralized database vulnerabilities. Lyon and Marseille integrators are consolidating vendor relationships around suppliers with pre-certified product lines to reduce compliance overhead.
United Kingdom
London's financial services sector prioritizes mobile credential convergence and visitor management integration for enterprise campus security. Post-Brexit regulatory divergence creates parallel certification tracks alongside EU AI Act compliance for vendors serving both markets. Birmingham and Manchester commercial real estate developments are adopting cloud-integrated access platforms to reduce per-site administrative burden.
Poland
Underpenetrated commercial real estate markets offer first-mover advantage for cloud-integrated access control systems in Warsaw and Kraków. Battery-powered wireless locks eliminate cabling costs in heritage building stock where preservation rules restrict infrastructure modifications. Czech Republic and Hungarian buyers exhibit similar price sensitivity, creating regional procurement patterns favoring mid-tier technology tiers.
Netherlands
Randstad logistics hubs and data centers demand ETSI-certified connected devices with documented cybersecurity postures. CE marking under MDR electromagnetic compatibility standards compounds hardware selection criteria for industrial facility operators. Rotterdam and Amsterdam smart city initiatives are piloting integrated access-video-intrusion platforms for centralized security operations.
Europe Access Control Hardware Market Competitive Landscape
Capability concentration sits with specialized biometric and wireless technology developers; scale advantage sits with diversified electromechanical and building automation conglomerates. The vendor base stratifies into three tiers: premium compliance-certified specialists, mid-market cloud-integrated platforms, and economy standalone hardware suppliers. Strategic archetypes include electromechanical legacy base exploiters, edge-processing biometric innovators, and parking-perimeter integration specialists. Dominant competitive moves encompass M&A activity targeting wireless retrofit capabilities and strategic partnerships with systems integrators for smart building retrofit programs.
Among Netherlands-based specialists, Nedap N.V. anchors the parking and perimeter integration segment through vehicle and reader system specialization. Swedish conglomerate ASSA ABLOY AB exemplifies the electromechanical legacy base exploiter archetype, leveraging installed lock populations for recurring maintenance contract capture. German industrial conglomerate Siemens AG occupies a position spanning building automation integration and compliance-certified connected device portfolios. These three entities represent distinct strategic postures without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Nedap N.V. |
| ASSA ABLOY AB |
| Siemens AG |
| Bosch |
| Dormakaba Holding AG |
| Johnson Controls International plc |
| Axis Communications |
| Allegion Plc |
| Others |
Supply & Pricing Matrix
Overcapacity in Asian microcontroller foundries is compressing component lead times while simultaneously intensifying price competition among European access control hardware vendors, forcing manufacturers to absorb margin pressure or accelerate vertical integration into firmware development.
Pricing Analysis
Long-term service contracts dominate enterprise procurement in Germany and France, though spot-market transactions persist for standalone hardware in Eastern European price-sensitive segments. Pricing stratifies across GDPR-certified biometric systems, CE-marked electromechanical locks, and uncertified economy keypads, with certification-grade differentiation commanding substantial premiums. Cost compression in wireless retrofit tiers is intensifying because battery-powered lock manufacturers face copper and rare earth magnet volatility. Polish commercial real estate buyers exhibit the highest price elasticity, while French government facilities prioritize compliance-certified systems regardless of premium positioning.
Supply Chain Analysis
Upstream semiconductor feedstock draws from Taiwan, South Korea, and China for microcontroller and sensor components essential to biometric reader and electronic lock production. Rare earth magnets for electromechanical locking mechanisms hinge on Chinese processing capacity, while copper wiring sources from Chilean and Indonesian mining operations. Single-source vulnerability concentrates in advanced facial recognition chipsets from Taiwanese foundries. Distribution runs through German industrial distributors for enterprise campus deployments, French smart building integrators for retrofit programs, and direct OEM relationships for automotive and banking verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates substantial switching costs—GDPR-compliant biometric architectures and ETSI-certified device portfolios lock in enterprise buyers across multi-year replacement cycles.
For Market Incumbents: Harden installed-base exploitation through firmware subscription tiers and predictive maintenance contracts that raise switching costs for German automotive and French banking customers. Deepen backward integration into edge-processing chip design to reduce Taiwanese foundry dependency and capture margin from biometric algorithm innovation. Neutralize emerging cloud-native entrants by pre-certifying entire product lines under EU AI Act high-risk system requirements before compliance deadlines tighten. For New Entrants and Emerging Players: Poland's underpenetrated commercial real estate sector offers white-space expansion for battery-powered wireless locks that bypass heritage building preservation constraints. Czech and Hungarian industrial facilities represent adjacent demand for standalone keypad and card reader systems with minimal IT infrastructure requirements. Target healthcare facility mandates by developing audit-trail-capable biometric systems that satisfy CSRD reporting requirements for hospital procurement committees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-integrated access control platforms as software-defined credential management reduces hardware refresh frequency. Acquisition candidates should display pre-certified GDPR and EU AI Act compliance portfolios with established French integrator relationships. Monitor ETSI cybersecurity certification backlog durations as an inflection indicator—extended timelines signal consolidation pressure on sub-scale vendors unable to absorb 8-14 month product launch delays.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Retrofit Technology Acquisition | Battery-powered lock capabilities eliminate cabling costs in France's heritage building retrofit programs. |
| ETSI Cybersecurity Pre-Certification | Pre-certified connected device portfolios reduce compliance overhead for German industrial facility operators. |
| Edge-Processing Biometric Development | On-device facial recognition architectures satisfy GDPR data minimization for French banking headquarters. |
| Service Contract Unbundling | Metered maintenance tiers optimize operating expenditures for Munich and Frankfurt property managers. |
| Eastern European Channel Partnership | Local integrator relationships capture first-mover advantage in Warsaw and Kraków commercial developments. |
Research Methodology
Desk research of EU regulatory filings, ETSI certification databases, and CE marking registries preceded structured interviews with access control systems integrators, enterprise security directors, and biometric hardware procurement leads. Primary fieldwork encompassed facility managers at German automotive plants, French smart building retrofit coordinators, and Polish commercial property developers. Secondary validation drew from customs trade data for electromechanical lock components, SEC filings of publicly traded security conglomerates, and industry association reports on wireless retrofit adoption patterns. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
The analytical framework held EU AI Act implementation timelines and GDPR enforcement intensity as fixed boundary conditions across the projection horizon, while varying wireless technology penetration rates and cloud-platform adoption curves by country. Segmentation dimensions modeled include product architecture, technology tier, end-user vertical, and installation type, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from logistic diffusion curves fitted to historical technology substitution patterns, incorporating semiconductor supply elasticity and copper price volatility as sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by electromechanical conglomerates or disruptive pricing by Asian cloud-native entrants would shift outcomes substantially. Cross-checking against ETSI certification queue data and German industrial distributor inventory reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Latin America Smart Lock Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Automated Smart Locker System Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Access Control Readers Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
China Access Control Market