
 Mexico Surveillance IP Camera Market | 2026-2036
Mexico Surveillance IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Surveillance IP Camera Market Insights
IFT's spectrum reallocation for IoT security applications is shifting the cost-of-entry calculus for wireless surveillance deployments across Mexican industrial zones. Axis Communications leverages its channel control to sustain dominance in premium enterprise installations. Honeywell International anchors its position through vertical integration into building management systems that incorporate video analytics. Bosch Sicherheitssysteme differentiates via manufacturing scale that supports localized assembly operations.
Surveillance IP cameras are digital video capture devices that encode and transmit footage over Internet Protocol networks, typically supporting resolutions from 2MP to 8MP with Power-over-Ethernet connectivity and ONVIF interoperability for unified management platforms. Their primary commercial purpose centers on real-time security monitoring, forensic evidence collection, and automated threat detection through edge-based analytics. Dome cameras lead the camera type segment due to vandal-resistant housing demand in public infrastructure, while IP-based technology captures the fastest expansion as analog-to-digital migration accelerates across government and commercial end users. Cloud storage features command premium positioning within the feature matrix as Mexican enterprises prioritize offsite redundancy over localized NVR maintenance.
IFT spectrum regulations and PROFECO consumer protection standards shape product certification requirements and warranty obligations for surveillance equipment sold in Mexico. The Federal Law on Protection of Personal Data held by Private Parties imposes operational constraints on video data retention and biometric processing that elevate compliance costs for system integrators. Stakeholders must monitor pending amendments to Mexico's cybersecurity framework that could mandate encryption standards for networked cameras deployed in critical infrastructure environments.
Market Dynamics
The Federal Telecommunications Institute's spectrum reallocation for IoT-enabled security devices is compressing deployment costs for wireless surveillance networks across Mexican industrial corridors, accelerating analog-to-digital migration timelines for municipal and enterprise buyers.
Growth Catalysts
- Smart city infrastructure mandates:Mexico City's integrated urban security programs are driving bulk procurement of networked video systems with centralized command platforms.
- IFT spectrum reallocation:The Federal Telecommunications Institute's IoT frequency designation is eliminating licensing barriers for wireless camera deployments in manufacturing zones.
- Border state manufacturing concentration:Nuevo León and Tamaulipas logistics corridors require perimeter surveillance integration for customs-adjacent facilities.
Market Restraints
- Import dependency for image sensors:CMOS sensor supply concentrates in East Asian foundries, exposing Mexican integrators to currency fluctuation and shipping volatility.
- Federal Law on Protection of Personal Data compliance costs:Video data retention limits and biometric processing restrictions elevate system integration expenses for private operators.
- Power infrastructure gaps:Rural and semi-urban deployment sites lack reliable PoE-capable electrical networks, constraining camera density.
Strategic Opportunities
- Underpenetrated southern states:Oaxaca and Chiapas municipal governments lack legacy analog infrastructure, enabling direct IP system installation without migration costs.
- Cloud storage service bundling:Mexican enterprises are prioritizing offsite redundancy over localized NVR maintenance, creating recurring revenue streams for managed service providers.
- Edge analytics convergence:On-camera AI processing is reducing bandwidth requirements for real-time threat detection in bandwidth-constrained northern border deployments.
Industry Challenges
- Cybersecurity certification timelines:Pending amendments to Mexico's cybersecurity framework could mandate encryption standards for critical infrastructure cameras, extending product validation cycles.
- Legacy analog system integration:Hybrid environments require protocol bridging equipment that complicates unified management platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Surveillance IP Camera Market |
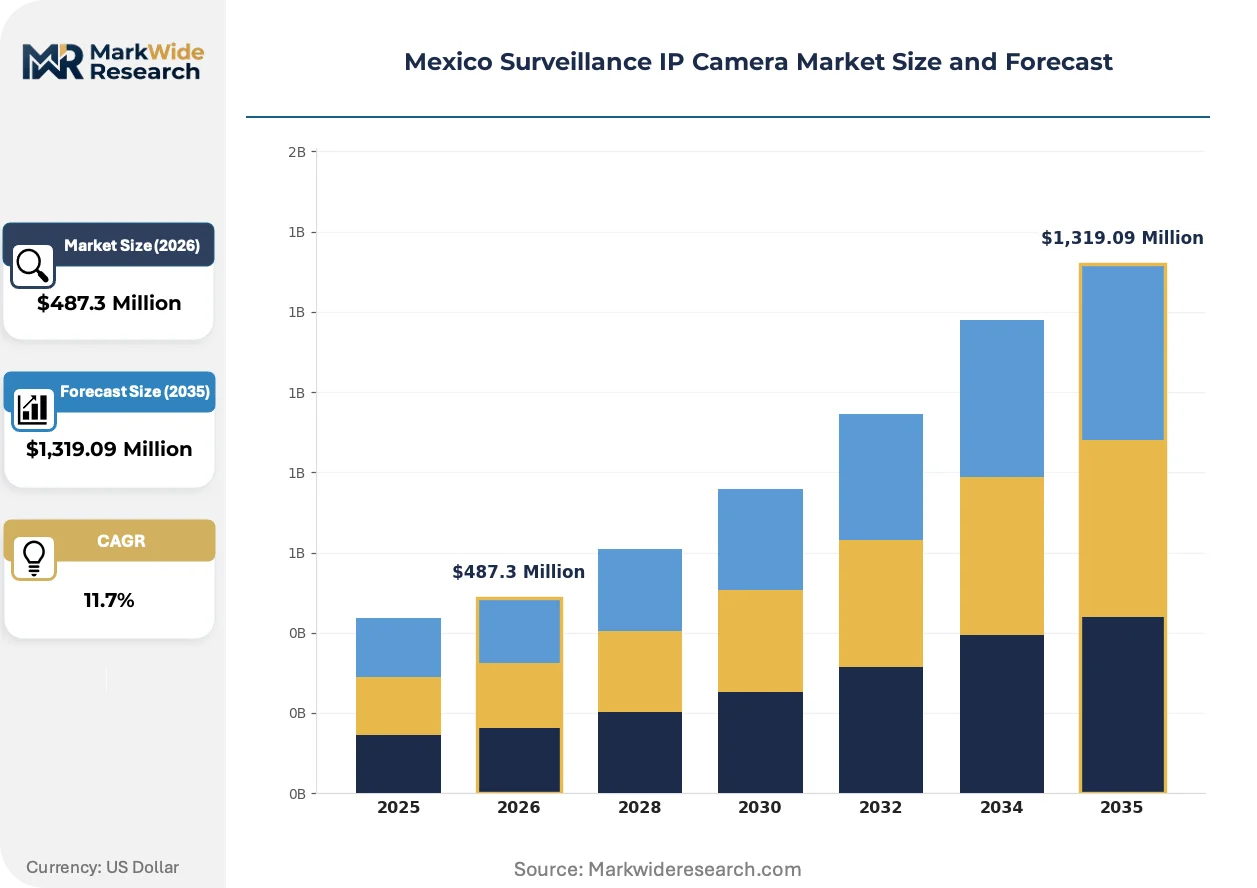
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Dome, Bullet, PTZ, Box End User: Commercial, Residential, Government, Industrial Technology: Analog, IP-Based, Wireless, Hybrid Feature: Night Vision, Motion Detection, Wireless Connectivity, Cloud Storage |
| Companies Covered | ACTi Corporation, Axis Communications, Teledyne FLIR, Honeywell International, Zhejiang Uniview Technologies, Hangzhou Hikvision Digital Technology, Bosch Sicherheitssysteme, Panasonic Corporation, Hanwha Vision America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Surveillance IP Camera Market Trends and Innovations
Edge-based video analytics and wireless networking protocols are converging to reshape how surveillance infrastructure deploys across Mexican public and private sectors.
Edge AI processing is converging with low-latency wireless transmission to enable real-time threat detection without centralized server dependency. Manufacturing facilities in Nuevo León are adopting cameras with on-board object recognition to reduce bandwidth consumption across sprawling plant perimeters. This convergence is compressing hardware refresh cycles as enterprises prioritize analytics-capable units over basic recording devices.
The Federal Law on Protection of Personal Data is imposing operational constraints on biometric processing and video retention periods for private sector operators. System integrators must now architect storage architectures with automated deletion workflows and access audit trails. Financial services and retail verticals are most affected, with compliance costs driving preference toward vendors with pre-certified data handling protocols.
Managed service procurement is displacing capital-heavy equipment ownership among mid-sized Mexican enterprises. Security-as-a-service providers are bundling hardware, cloud storage, and remote monitoring into monthly subscriptions. This shift is most visible in Mexico City commercial real estate, where property managers favor operational expenditure models over upfront NVR and server investments.
Mexico Surveillance IP Camera Market Segmentation
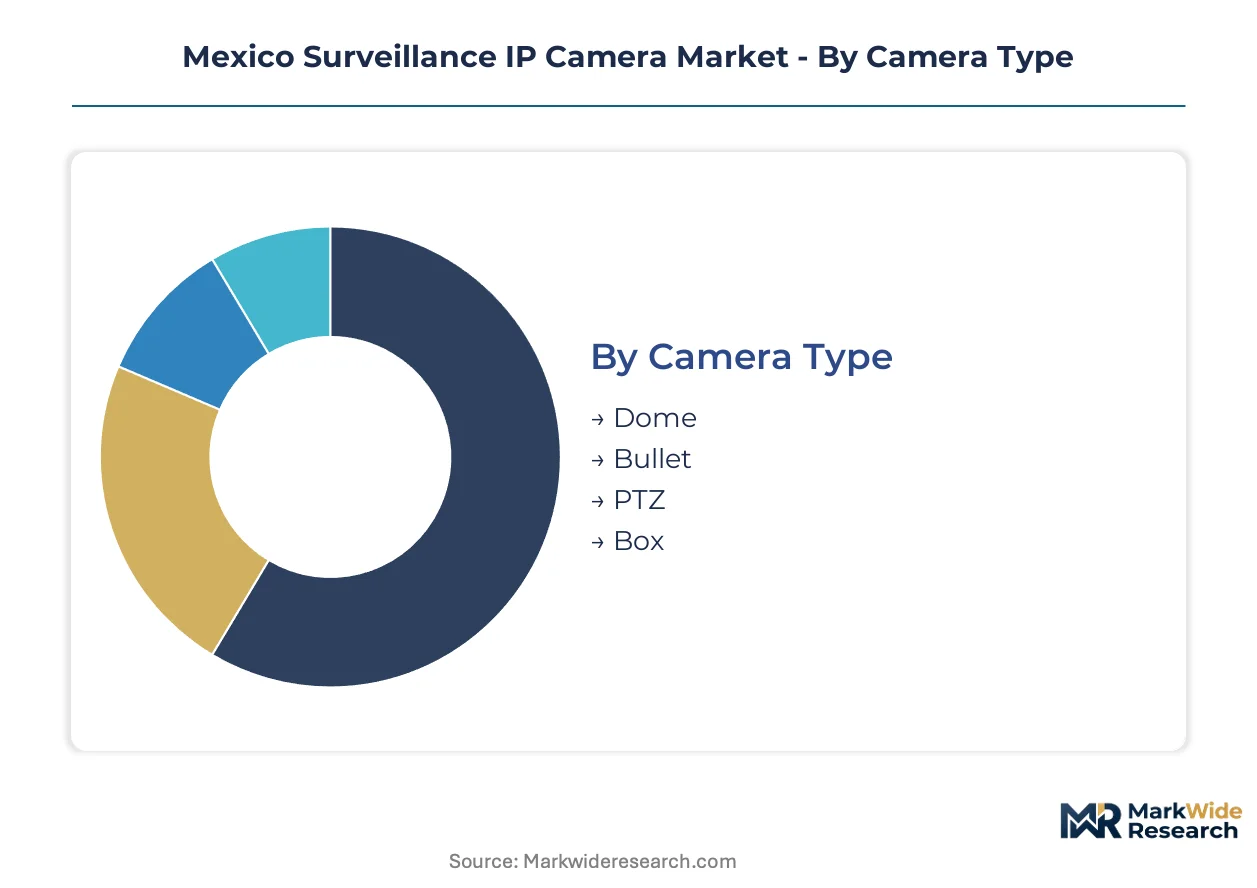
Segmentation reveals how procurement patterns diverge across Mexican surveillance buyers. IFT certification requirements and PROFECO warranty obligations apply unevenly across camera types and end-user categories, creating distinct compliance cost structures for integrators serving different verticals.
Camera Type:
Dome and bullet cameras carry mandatory PROFECO consumer protection compliance for residential sales, while PTZ units for critical infrastructure face pending cybersecurity framework encryption mandates.
- Dome:Vandal-resistant housings with impact-rated polycarbonate enclosures withstand public space abuse. Mexico City metro stations and municipal buildings specify dome units for their discrete profile and 360-degree coverage capability.
- Bullet:Weather-sealed cylindrical housings with integrated IR illuminators deliver long-range perimeter visibility. Manufacturing facilities in Nuevo León deploy bullet cameras across logistics yard boundaries where dust and temperature cycling demand IP66-rated sealing.
- PTZ:Motorized pan-tilt-zoom mechanisms with optical zoom ranges up to 30x enable operator-directed tracking of suspicious activity.
- Box:Modular lens-interchangeable designs accommodate specialized optics for license plate recognition and facial capture applications.
Leading the category by volume: Dome. Growing fastest: PTZ.
End User:
Commercial and industrial buyers absorb higher per-unit costs for analytics-enabled systems, while government procurement emphasizes interoperability with existing command platforms.
- Commercial:Retail banks, hospitality chains, and office complexes drive demand for unified management platforms with centralized credentialing. Mexico City commercial real estate operators prioritize cloud-architected systems that shift capital expenditure to operational models.
- Industrial:Automotive assembly plants and maquiladora facilities require explosion-proof housings and ONVIF-compliant edge analytics for hazardous zone monitoring. Tamaulipas petrochemical corridors specify corrosion-resistant coatings for salt-air environments.
- Government:Federal and municipal security programs mandate centralized video management with archival retention protocols.
- Residential:Gated communities and luxury condominiums in Monterrey and Guadalajara drive demand for app-integrated consumer-grade systems.
Commercial installations dominate unit volume. Industrial verticals show steepest expansion trajectory as manufacturing FDI accelerates border state facility construction.
Technology:
Cost tiers separate legacy analog replacement cycles from greenfield IP deployments, with wireless systems capturing share where PoE infrastructure remains incomplete.
- IP-Based:H.265 encoding and Power-over-Ethernet connectivity enable single-cable installation with 4K resolution support. New industrial facilities in Baja California bypass analog infrastructure entirely, deploying native IP architectures from commissioning.
- Wireless:Wi-Fi 6 and cellular LTE modules eliminate trenching costs for remote perimeter applications. Chiapas agricultural operations and Oaxaca mining sites adopt wireless cameras where grid connectivity is unreliable.
- Analog:Coaxial-based CVBS and HD-TVI systems persist in legacy municipal installations with phased replacement timelines.
- Hybrid:Multi-protocol recorders bridge analog and IP streams during transition periods.
IP-based systems command the largest installed base. Wireless deployments are gaining share fastest in southern states lacking legacy infrastructure.
Feature:
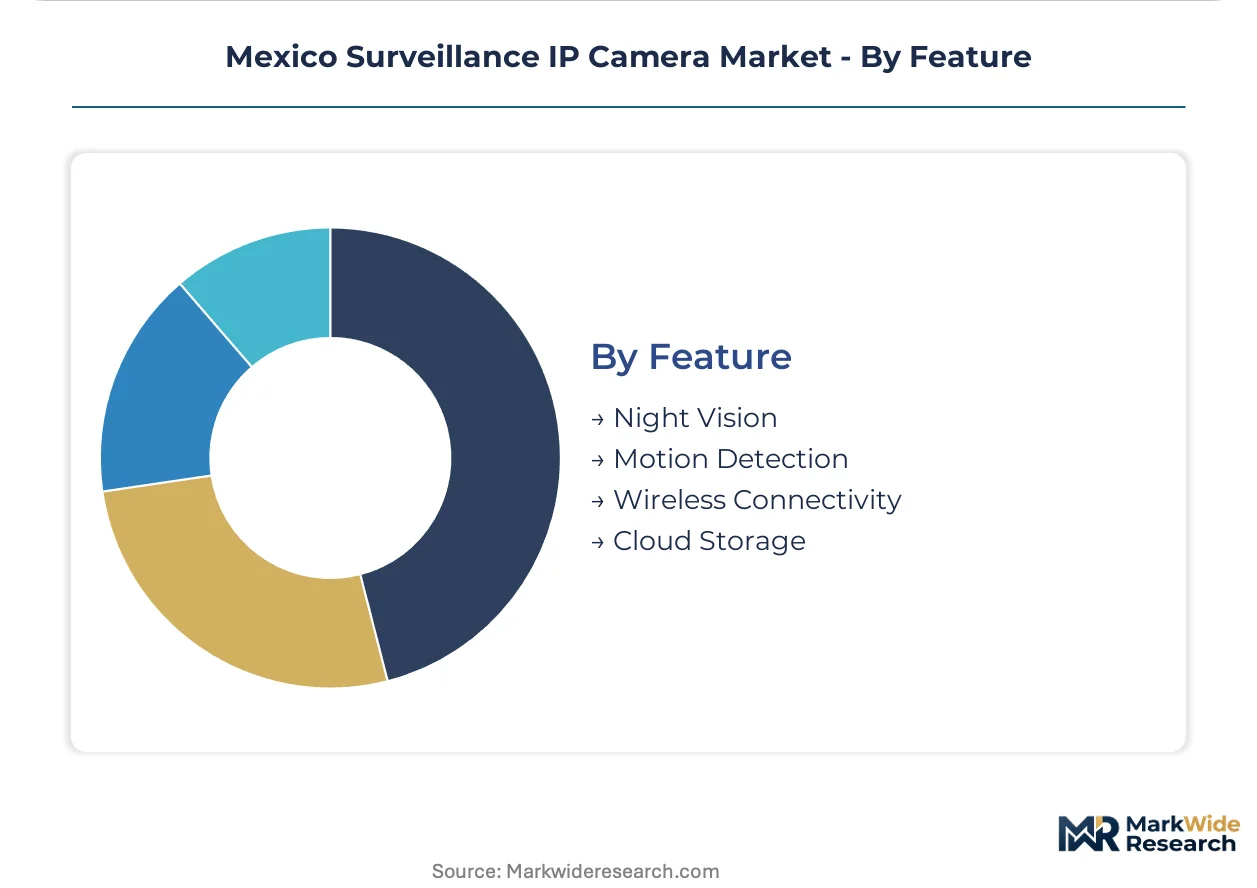
Feature bundling separates premium positioning from standard configurations, with cloud storage commanding recurring revenue premiums over localized NVR alternatives.
- Cloud Storage:Encrypted offsite redundancy with automated tiering and geographic replication addresses data sovereignty concerns under Federal Law on Protection of Personal Data. Financial services verticals in Mexico City mandate cloud architectures with audit-trail access logging.
- Motion Detection:Pixel-change algorithms and PIR sensors trigger event-based recording to reduce storage consumption. Border patrol-adjacent facilities in Tamaulipas deploy motion-activated analytics to filter false positives from wildlife and weather.
- Night Vision:IR LED arrays and starlight sensors extend operational hours for 24-hour facilities.
- Wireless Connectivity:Integrated Wi-Fi modules and cellular backhaul options reduce installation labor for retrofit projects.
Cloud storage features anchor premium pricing tiers. Motion detection capabilities show strongest uptake in bandwidth-constrained northern deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in northern border states where manufacturing FDI and logistics corridors require integrated perimeter surveillance systems. Southern states present greenfield deployment opportunities without legacy analog migration burdens. Central Mexico anchors municipal smart city procurement volume.
Northern Border States
Nuevo León and Tamaulipas automotive assembly plants and maquiladora facilities drive industrial-grade camera procurement with explosion-proof housing requirements. The Federal Telecommunications Institute's spectrum reallocation eliminates licensing barriers for wireless deployments across these manufacturing zones. Reynosa-Matamoros logistics corridors integrate perimeter surveillance for customs-adjacent facilities monitoring cross-border freight movements.
Mexico City Metro
Mexico City's integrated urban security programs command the largest municipal procurement volume for networked video systems with centralized command platforms. The Federal Law on Protection of Personal Data imposes video data retention limits that elevate compliance costs for system integrators serving government contracts. Metro stations and municipal buildings specify vandal-resistant dome units for discrete 360-degree coverage in high-traffic public infrastructure.
Jalisco
Guadalajara's commercial real estate operators and luxury condominium developments drive demand for app-integrated consumer-grade surveillance systems. PROFECO consumer protection standards shape warranty obligations and product certification requirements for residential sales channels. The Guadalajara metropolitan area shows fastest uptake of cloud-architected systems shifting capital expenditure to operational models.
Bajío Region
Querétaro and Guanajuato automotive supplier parks require ONVIF-compliant edge analytics for hazardous zone monitoring in tier-two manufacturing facilities. Pending amendments to Mexico's cybersecurity framework could mandate encryption standards for cameras deployed in critical infrastructure environments. Silao-Apaseo el Grande industrial corridors specify corrosion-resistant coatings for electronics manufacturing cleanroom environments.
Southern States
Oaxaca and Chiapas municipal governments lack legacy analog infrastructure, enabling direct IP system installation without migration cost penalties. Chiapas agricultural operations and Oaxaca mining sites adopt wireless cameras where grid connectivity remains unreliable. These underpenetrated markets attract managed service providers bundling hardware, cloud storage, and remote monitoring into monthly subscription offerings.
Mexico Surveillance IP Camera Market Competitive Landscape
East Asian producers anchor the volume tier; European specialists hold premium positioning through channel control and localized assembly. The market exhibits consolidated structure at the premium enterprise tier with fragmented competition in mid-market segments. Three archetypes dominate: multinational security conglomerates with building management integration, regional specialists with manufacturing scale advantages, and managed service providers with recurring revenue bundling. Competitive moves center on backward integration into image sensor supply chains and strategic partnerships for cloud storage service bundling.
Within the multinational tier, Axis Communications, Honeywell International, and Bosch Sicherheitssysteme exemplify distinct positioning strategies. Axis Communications represents channel-controlled premium enterprise installation dominance. Honeywell International anchors through upstream control over building management system integration incorporating video analytics. Bosch Sicherheitssysteme occupies a position supported by manufacturing scale enabling localized assembly operations. These three entities collectively illustrate how competitive differentiation in the Mexican market derives from vertical integration depth rather than hardware specification alone.
| Leading Market Players |
|---|
| ACTi Corporation |
| Axis Communications |
| Teledyne FLIR |
| Honeywell International |
| Zhejiang Uniview Technologies |
| Hangzhou Hikvision Digital Technology |
| Bosch Sicherheitssysteme |
| Panasonic Corporation |
| Hanwha Vision America |
| Others |
Pricing and Supply Chain Analysis
CMOS image sensor procurement from East Asian foundries cascades through three distinct pricing tiers as currency volatility and shipping costs compound at each distribution layer. Mexican system integrators absorb these upstream pressures differentially, with enterprise-grade analytics platforms commanding premium positioning while standard IP units face margin compression from spot-market component sourcing.
Pricing Analysis
Short lead-time premiums separate urgent-deployment municipal contracts from standard commercial procurement cycles in Mexican surveillance markets. Pricing stratifies across certified enterprise systems, PROFECO-compliant consumer units, and uncertified gray-market alternatives, with IFT cybersecurity framework amendments intensifying cost compression in the mid-tier segment. Government buyers demonstrate lowest price sensitivity due to centralized funding mandates, while southern state municipal governments prioritize capital efficiency over feature depth.
Supply Chain Analysis
Regional distribution centers in Mexico City, Monterrey, and Guadalajara anchor hub-and-spoke patterns that extend into Tijuana and Reynosa manufacturing corridors. Component sourcing draws from Taiwan and South Korea for CMOS sensors, China for lens assemblies and housings, and domestic maquiladora operations for final assembly and firmware localization. Single-source vulnerability concentrates in advanced image processing chipsets, with tariff exposure on Chinese electronics amplifying cost volatility for mid-market camera vendors. Distribution runs through authorized distributor networks serving vertical specialists rather than direct OEM-to-installer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in Mexican surveillance markets hinges on backward integration into cloud storage infrastructure and edge analytics IP, with first-movers capturing recurring revenue streams before standardization commoditizes hardware margins.
For Market Incumbents: Anticipate IFT encryption mandate acceleration by pre-certifying product portfolios and securing PROFECO warranty compliance across dome and bullet camera lines. Channel control investments in Nuevo León and Tamaulipas industrial corridors will preempt emerging entrants targeting maquiladora facility expansions. Cloud service bundling capabilities represent the critical defensive lever against managed service provider displacement. For New Entrants and Emerging Players: Southern state municipal governments lacking legacy analog infrastructure present direct-IP deployment opportunities without hybrid system integration costs. Chiapas agricultural operations and Oaxaca mining sites offer wireless-first penetration points where established vendors maintain limited presence. A security-as-a-service go-to-market model with Spanish-language remote monitoring support addresses capital-constrained buyer preferences in underpenetrated regions. For Investors and Strategic Acquirers: Accelerating PROFECO enforcement actions against non-compliant imports signal that regulatory certification capabilities will determine viable acquisition targets within the analysis window. Vertically integrated providers with captive cloud infrastructure and IFT pre-certification status represent the optimal acquisition archetype. Pending amendments to Mexico's cybersecurity framework constitute the leading indicator that encryption-ready product pipelines will command valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Storage Service Bundling | Recurring revenue capture shifts Mexican enterprises from capital-heavy NVR ownership to operational expenditure models. |
| IFT Pre-Certification Investment | Encryption-ready portfolios preempt competitive exclusion when cybersecurity framework amendments take effect. |
| Southern State Distribution Expansion | Greenfield IP deployment in Oaxaca and Chiapas bypasses legacy analog migration costs burdening northern markets. |
| Edge Analytics IP Acquisition | On-camera AI processing capabilities reduce bandwidth requirements for bandwidth-constrained border deployments. |
| Managed Service Provider Partnership | Monthly subscription bundling aligns with Mexico City commercial real estate operator preference for operational models. |
Research Methodology
Trade databases, IFT regulatory filings, and PROFECO consumer protection standards formed the secondary backbone for market sizing and competitive mapping. Primary interviews with system integration engineers, municipal procurement officers, maquiladora security directors, and cloud service provider executives validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled equipment shipment data against project-level deployment tracking across Mexican states.
Bottom-up modeling aggregated individual camera unit economics by technology type, feature bundle, and end-user vertical, while top-down analysis calibrated aggregate market expansion against smart city infrastructure budget disclosures and manufacturing FDI flows. Segmentation dimensions included camera type, end-user category, technology architecture, and feature configuration. CAGRs derived from regression analysis of historical procurement patterns and projected infrastructure investment schedules, with IFT spectrum reallocation timelines and Federal Law on Protection of Personal Data compliance cost trajectories informing elasticity assumptions.
Revisions become necessary when IFT cybersecurity framework amendments accelerate beyond modeled timelines, CMOS sensor supply disruptions extend lead times substantially, or southern state municipal funding allocations diverge from historical patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
AI Surveillance System Market