
 North America Access Control Market | 2026-2036
North America Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
North America Access Control Market Analytics
Enterprise buyer concentration across commercial real estate portfolios and healthcare networks is consolidating procurement decisions into fewer centralized security operations. ASSA ABLOY sustains broad hardware-to-software integration across North American distribution channels. Honeywell International Inc. leverages its building automation installed base to bundle access control with HVAC and fire safety systems. HID Global anchors its position through deep specialization in credential technology and secure identity issuance for federal agencies.
Access control comprises electromechanical and electronic systems that authenticate identities through biometric templates, encrypted credentials, or mobile tokens to grant or deny entry to secured facilities. These systems integrate with video management platforms and directory services to enforce time-bound permissions across perimeter doors, turnstiles, and logical network resources. Biometric systems command premium positioning due to liveness detection requirements and template protection standards, while cloud-based deployments are expanding fastest among mid-market commercial users seeking subscription-based operational expenditure models. RFID systems retain dominant volume share in industrial and government verticals where legacy credential infrastructure and FAR/FAR certification thresholds slow migration timelines.
FCC equipment authorization rules govern wireless transmission protocols in connected readers, while state biometric privacy laws in Illinois BIPA and Texas CUBI impose consent and retention mandates on fingerprint and facial recognition deployments. NIST SP 800-63 digital identity guidelines shape federal procurement specifications and cascade into enterprise RFP requirements. Stakeholders must monitor the divergence between federal zero-trust architecture mandates and fragmented state-level privacy enforcement to align product roadmaps with compliance trajectories.
Market Dynamics
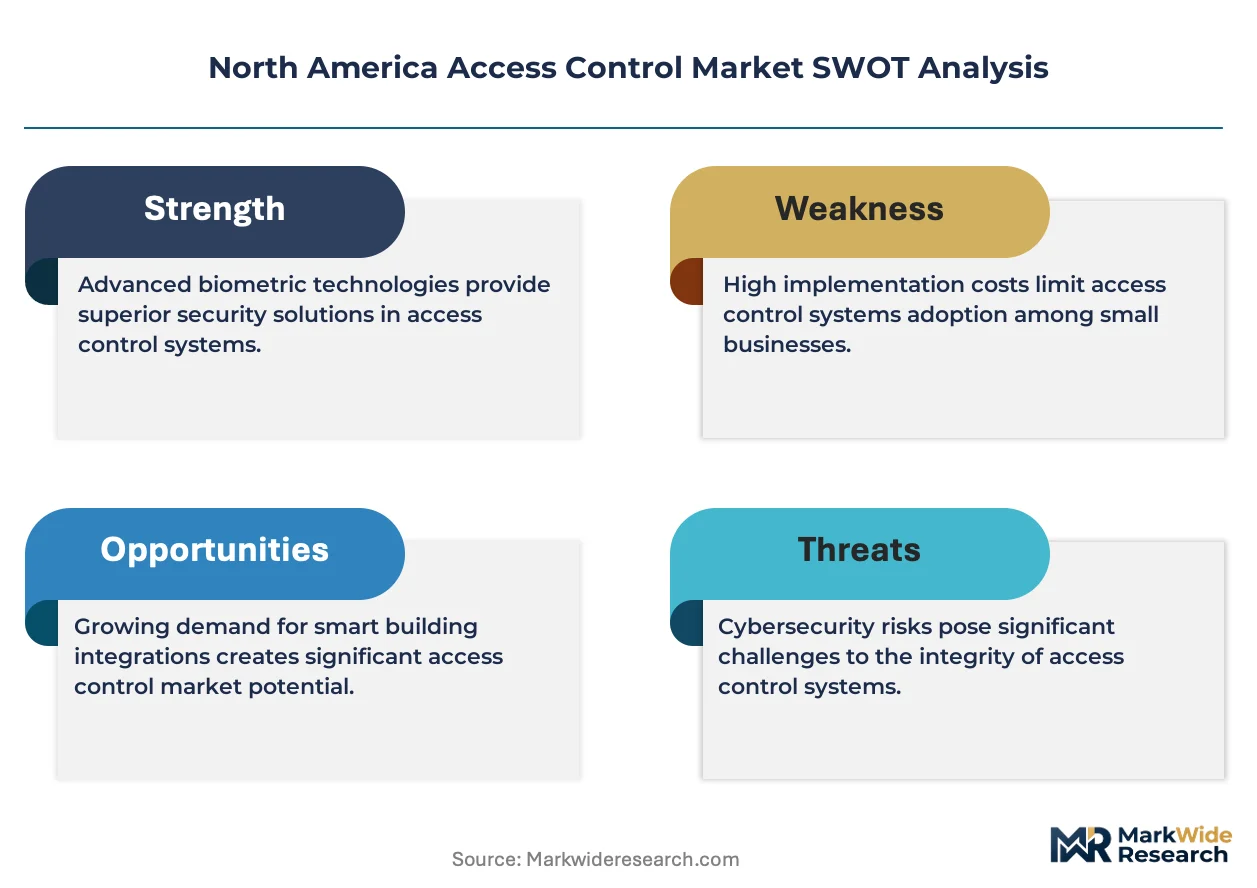
Enterprise consolidation of security operations into centralized command centers is compressing procurement cycles and favoring integrated platform vendors over point-product suppliers across commercial real estate and healthcare networks.
Growth Catalysts
- Mobile credentialing:Enterprise campuses across the US Sun Belt are replacing physical card systems with smartphone-based authentication, reducing credential reissuance costs and enabling remote provisioning for distributed workforces.
- NIST zero-trust mandates:Federal procurement specifications under SP 800-63 are cascading into enterprise RFP requirements, accelerating replacement of legacy physical access systems with identity-verified logical-physical convergence.
- Data center construction:Hyperscale facility clusters in Northern Virginia, Phoenix, and Dallas-Fort Worth are specifying multi-factor biometric authentication for cage-level access compliance.
Market Restraints
- Biometric template storage costs:Illinois BIPA and Texas CUBI impose strict retention and consent mandates that inflate operational expenditure for fingerprint and facial recognition deployments.
- Semiconductor supply concentration:Secure element chip fabrication for encrypted credentials remains concentrated among a limited supplier base, creating lead time vulnerability for credential manufacturers.
- FCC equipment authorization timelines:Wireless reader certification cycles average 12-18 months, delaying product launches for Bluetooth Low Energy and ultra-wideband-enabled devices.
Strategic Opportunities
- Mid-market cloud migration:Commercial buildings under 500,000 square feet in secondary US metros remain underpenetrated by cloud-native access control, presenting subscription revenue expansion potential.
- Healthcare network consolidation:Hospital system mergers are creating demand for unified identity platforms spanning acute care facilities, outpatient clinics, and remote physician access.
- Convergence of physical access and IT security:Chief Security Officer role unification is driving procurement of platforms integrating Active Directory, SIEM, and video management through single-pane administration.
Industry Challenges
- Cyber-physical security skills gap:Enterprises report shortages of personnel capable of administering both network security protocols and electromechanical hardware maintenance.
- Interoperability certification backlog:ONVIF and OSDP compliance testing queues extend deployment timelines for multi-vendor integrations.
- Legacy Wiegand infrastructure stranded:Decades of installed unencrypted wiring creates vulnerability exposure during phased upgrade programs.
Report Scope
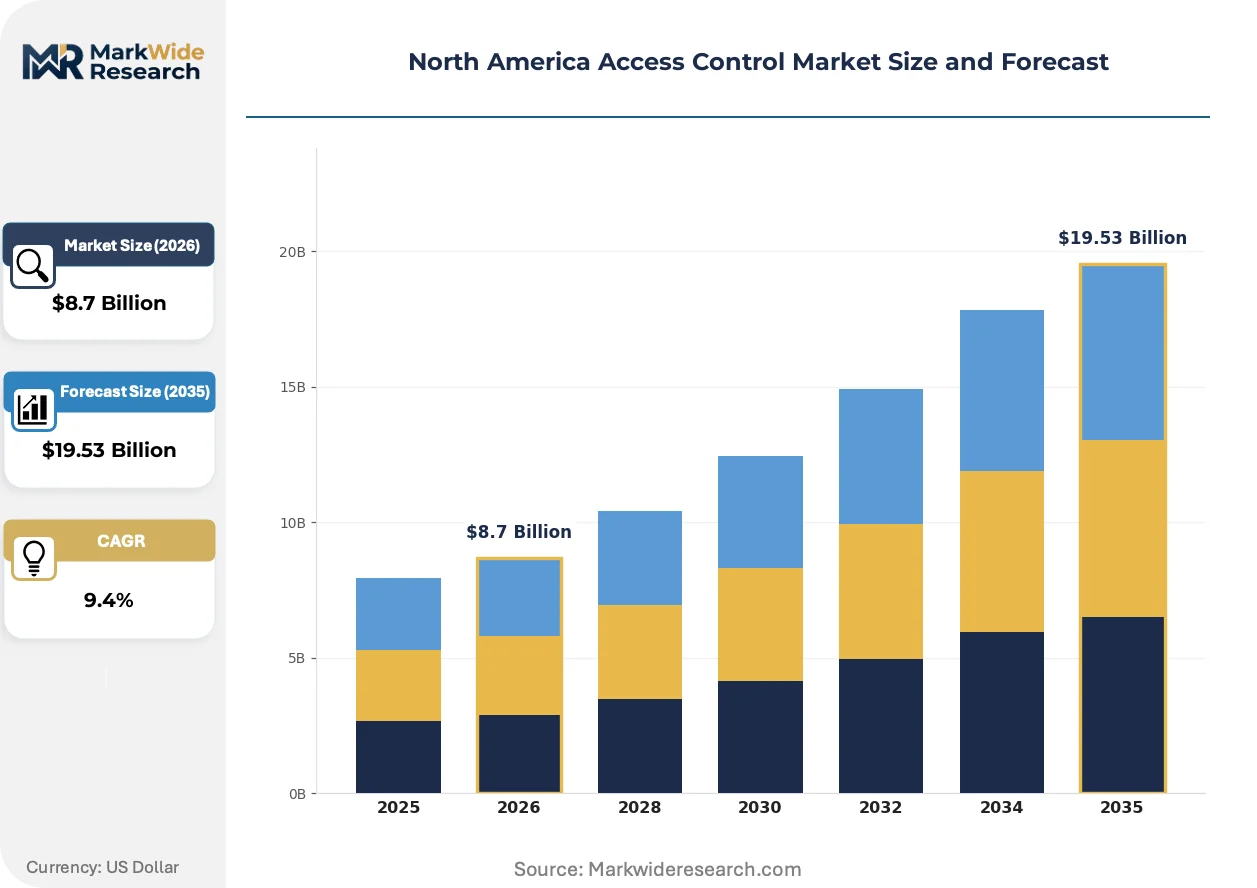
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Access Control Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Systems, Keypad Systems, RFID Systems, Smart Card Systems End User: Residential, Commercial, Government, Industrial Technology: Cloud-based, On-premise, Hybrid, Mobile Authentication Installation Type: Retrofit, New Construction, DIY, Managed Service |
| Companies Covered | Allegion plc, Securitas Technology, ASSA ABLOY, HID Global, Brivo Systems, LLC, dormakaba Group, Honeywell International Inc., Axis Communications, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Access Control Market Evolving Landscape
Credential technology is bifurcating between high-assurance biometric deployments in regulated environments and frictionless mobile authentication in commercial settings, with cloud architecture enabling both paths through common identity platforms.
Facial recognition with liveness detection is electrifying high-security perimeter applications. Federal agencies and financial institutions are adopting 3D structured light and infrared-based anti-spoofing for vault and data center entry. The technology is compressing throughput times at turnstiles while raising the bar for presentation attack resistance.
State biometric privacy statutes are fragmenting compliance architecture. Illinois BIPA's private right of action and Texas CUBI's retention limits create divergent operational templates for multi-state operators. Enterprise security teams are responding with jurisdiction-specific consent workflows and shortened template lifecycle policies.
Subscription-based service models are displacing perpetual license structures in the mid-market. Commercial real estate owners prefer operational expenditure treatment for access control, shifting vendor relationships toward recurring revenue and remote monitoring. This pattern is most visible in Class A office repositioning projects across Austin, Nashville, and Raleigh-Durham.
North America Access Control Market Segmentation
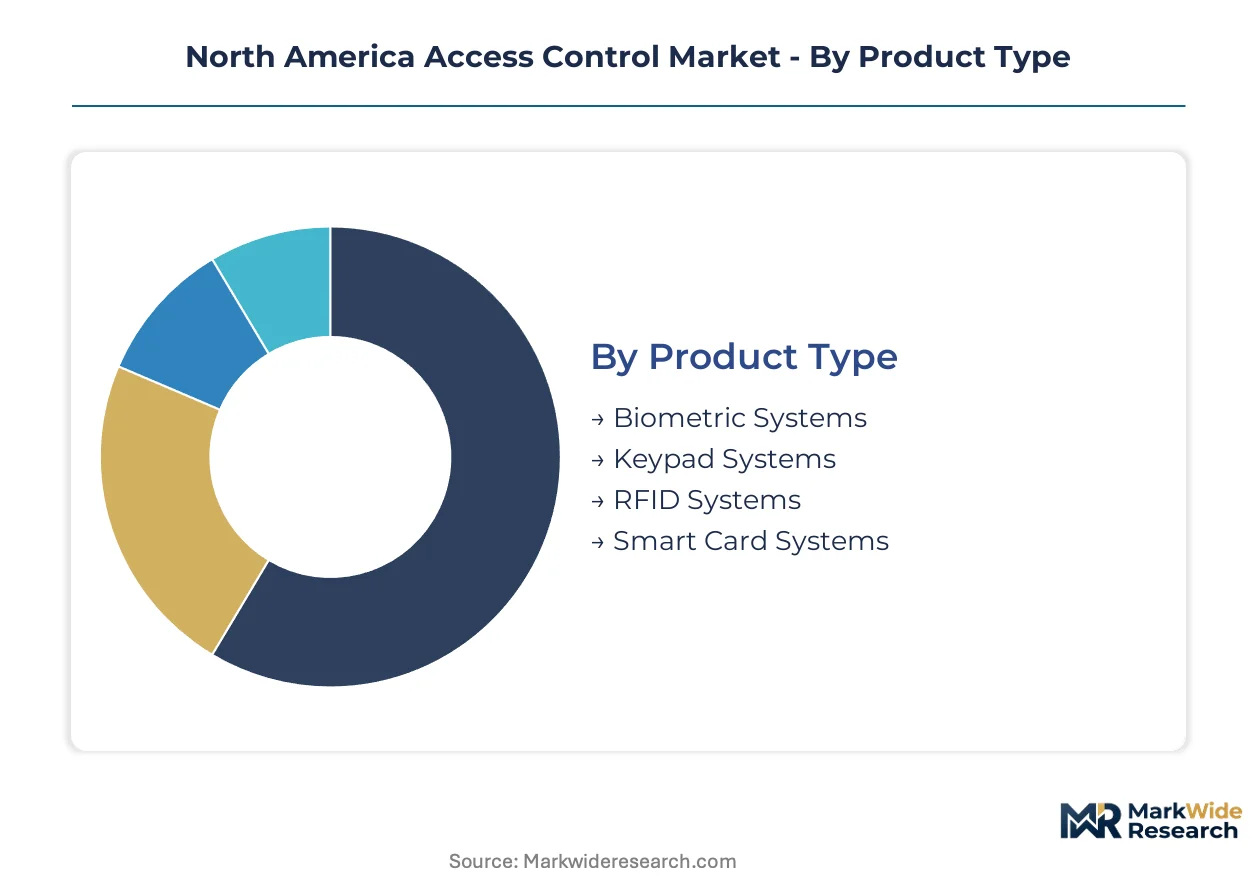
Access control procurement in North America diverges sharply across facility types and security postures. Biometric deployments in federal data centers operate on entirely different evaluation criteria than cloud-managed systems for suburban office parks. Understanding these segment boundaries clarifies where technology substitution accelerates versus where legacy infrastructure persists.
Product Type:
Buyer budgets and compliance thresholds determine hardware selection more than feature differentiation alone.
- Biometric Systems:Fingerprint, facial recognition, and iris scanning modalities incorporate liveness detection and template encryption per NIST SP 800-63 guidelines. Demand concentrates in Illinois and Texas facilities where BIPA and CUBI statutes mandate explicit consent workflows and shortened retention cycles, elevating operational complexity for multi-state operators.
- RFID Systems:Proximity and contactless card readers dominate government and industrial verticals where FIPS 201 PIV credential standards govern interoperability. Legacy Wiegand wiring in decades-old federal buildings slows migration timelines despite known vulnerability exposure.
- Smart Card Systems:Encrypted credential platforms with mutual authentication protocols serve healthcare networks consolidating identity across acute and outpatient facilities.
- Keypad Systems:PIN-based entry persists in cost-constrained residential and light commercial applications where credential management overhead outweighs security upgrade priorities.
Volume sits with RFID Systems; growth tilts toward Biometric Systems.
End User:
Facility ownership structure shapes procurement centralization and integration depth with building management systems.
- Commercial:Class A office repositioning in Austin, Nashville, and Raleigh-Durham drives mobile credential adoption as property managers seek operational expenditure treatment and remote provisioning capabilities for hybrid workforces.
- Government:Federal zero-trust mandates under SP 800-63 accelerate replacement of standalone physical access with converged identity platforms spanning logical and perimeter security.
- Industrial:Manufacturing and logistics facilities in the US Sun Belt prioritize ruggedized readers with OSHA-compliant environmental ratings for harsh operational conditions.
- Residential:Smart home integration and DIY installation channels expand in secondary metros where new construction lags national averages.
Procurement scale favors Commercial; compliance intensity peaks in Government.
Technology:
Deployment architecture determines capital recovery timelines and internal skill requirements for ongoing administration.
- Cloud-based:Subscription models with browser-based administration panels penetrate mid-market commercial buildings under 500,000 square feet where IT security staff are limited. Remote monitoring and automatic patch deployment reduce electromechanical maintenance burdens.
- Mobile Authentication:Smartphone credentialing with Bluetooth Low Energy and ultra-wideband proximity detection expands fastest among enterprise campuses replacing physical card reissuance programs. FCC equipment authorization timelines of 12-18 months constrain product launch velocity for new reader hardware.
- On-premise:Air-gapped servers retain preference in defense and intelligence facilities where network segmentation mandates preclude external connectivity.
- Hybrid:Edge computing architectures with local decision-making and cloud synchronization serve healthcare networks requiring offline continuity during network interruptions.
Recurring revenue concentrates in Cloud-based; capability expansion runs through Mobile Authentication.
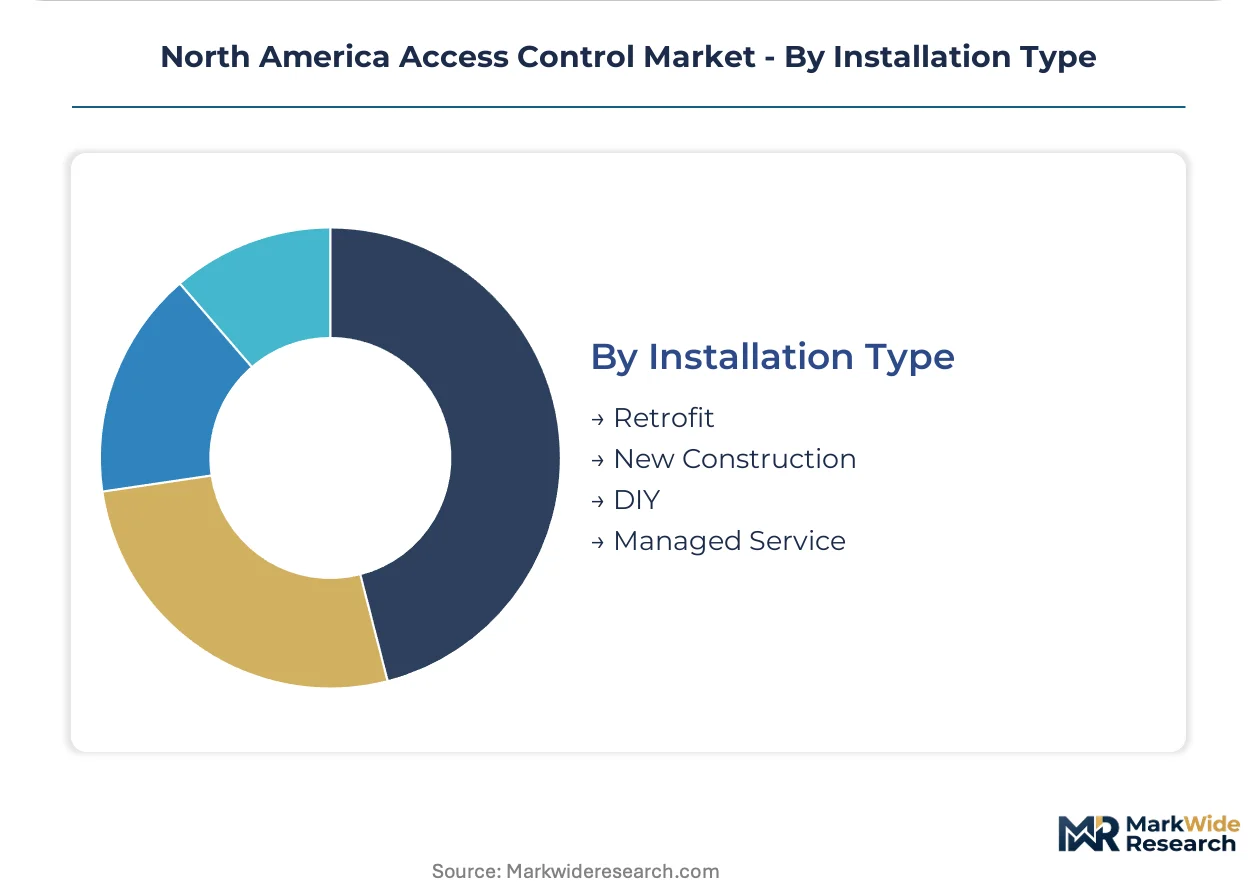
Installation Type:
Project delivery method reflects facility age, owner capital availability, and internal technical staffing.
- Retrofit:Phased upgrades of existing Wiegand infrastructure to OSDP-encrypted signaling dominate aging commercial portfolios in legacy metro cores. Installation crews must navigate live operational environments without disrupting tenant access.
- New Construction:Integrated specification during design phase enables converged physical-logical security platforms with structured cabling for video, access, and intrusion systems. Northern Virginia and Phoenix data center clusters exemplify this approach.
- DIY:Consumer-grade wireless locks with smartphone provisioning expand in residential and small commercial markets where professional integration costs exceed budget thresholds.
- Managed Service:Third-party monitoring and credential lifecycle administration appeal to healthcare networks undergoing merger-driven consolidation of disparate security operations.
Project volume flows through Retrofit; margin expansion aligns with Managed Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise security procurement concentrates in US Sun Belt metro corridors where commercial construction and data center expansion outpace national averages. Canadian and Mexican markets follow distinct regulatory and infrastructure maturity paths.
United States
Data center clusters in Northern Virginia, Phoenix, and Dallas-Fort Worth specify multi-factor biometric authentication for cage-level compliance. NIST SP 800-63 federal mandates cascade into enterprise RFP requirements. Illinois BIPA and Texas CUBI statutes impose divergent consent and retention workflows on fingerprint and facial recognition deployments.
Canada
Healthcare network consolidation across Ontario and Quebec drives demand for unified identity platforms spanning acute and remote facilities. Health Canada and the Office of the Privacy Commissioner govern biometric data handling. Toronto and Vancouver commercial portfolios are migrating to cloud-managed systems for operational expenditure treatment.
Mexico
Manufacturing and logistics facilities in Nuevo León and Baja California prioritize ruggedized readers for harsh operational conditions. The country's national data protection authority imposes retention limits on employee biometric records. Mexico City metro commercial construction is integrating mobile credentialing for Class A office repositioning.
North America Access Control Market Competitive Landscape
US-based producers anchor the integrated platform tier; European specialists hold credential technology and hardware manufacturing positions. Market structure tilts toward consolidation as enterprise buyers compress procurement cycles into centralized security operations. Three archetypes dominate: building automation bundlers, credential technology purists, and cloud-native platform disruptors. M&A activity and strategic partnerships are the primary competitive moves reshaping vendor positioning.
Within the integrated platform tier, Honeywell International Inc. and Johnson Controls represent building automation bundlers that leverage HVAC and fire safety installed bases. ASSA ABLOY anchors the hardware-to-software integration archetype across North American distribution channels. HID Global exemplifies credential technology specialization for federal agency secure identity issuance.
| Leading Market Players |
|---|
| Allegion plc |
| Securitas Technology |
| ASSA ABLOY |
| HID Global |
| Brivo Systems, LLC |
| dormakaba Group |
| Honeywell International Inc. |
| Axis Communications |
| Johnson Controls |
| Others |
Value Network & Pricing Analysis
Secure element chip spot prices and fabrication capacity utilization rates cascade through North American access control manufacturing, compressing margins on encrypted credential hardware while elevating subscription-based SaaS tiers as the preferred procurement model for cost-sensitive mid-market buyers.
Pricing Analysis
Volume concentrates in RFID readers and proximity cards where commoditized competition erodes hardware margins, while biometric systems with liveness detection command premium positioning through NIST SP 800-63 certification tiers. Price differentiation hinges on FIPS 201 PIV compliance levels and cloud-native architecture versus legacy on-premise licensing. Pricing pressure stems from semiconductor supply concentration inflating secure element costs for credential manufacturers. Commercial real estate portfolios under 500,000 square feet exhibit highest price sensitivity, whereas federal agencies prioritize assurance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for secure element chips mandate qualification of secondary fabrication partners, yet Taiwan and South Korea retain dominant positions in NFC and BLE-enabled credential silicon. Raw material dependencies span rare earth magnets for electromechanical locks, copper wiring for OSDP-encrypted signaling infrastructure, and optical components for 3D facial recognition modules. Supply chain risk centers on single-source vulnerability in advanced biometric sensor fabrication. Distribution runs through ASSA ABLOY and HID Global's North American channel networks, with direct-to-enterprise sales expanding for cloud-native platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform vendors as enterprise buyers compress procurement cycles and NIST zero-trust mandates raise compliance barriers for point-product suppliers.
For Market Incumbents: Lock in federal agency relationships through deep specialization in SP 800-63 certified identity issuance, while expanding cloud-native subscription offerings to capture mid-market commercial migration. Threat substitution from mobile authentication platforms demands accelerated Bluetooth Low Energy reader certification to maintain hardware relevance. Channel control through distributor exclusivity agreements represents the critical defensive lever against European hardware specialists. For New Entrants and Emerging Players: Capture healthcare network consolidation opportunities across Ontario and Quebec, where unified identity platforms spanning acute and remote facilities remain underpenetrated by incumbent bundlers. The most penetrable segment is cloud-managed systems for Class A office repositioning in secondary US Sun Belt metros. A direct-to-property-manager go-to-market angle, bypassing traditional security integrators, unlocks faster trial adoption. For Investors and Strategic Acquirers: The window for entry favors credential technology specialists with federal PIV issuance capabilities and established NIST certification pipelines. Long-term viability rests on convergence plays bridging physical access and IT security administration. The signal to watch is Chief Security Officer role unification announcements at Fortune 500 enterprises, indicating procurement centralization acceleration and platform vendor preference inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Converges physical access with Active Directory and SIEM through single-pane administration demanded by unified security operations. |
| Mobile Credential Expansion | Replaces physical card reissuance programs across US Sun Belt enterprise campuses with smartphone-based Bluetooth authentication. |
| Biometric Certification Investment | Secures NIST SP 800-63 compliance for federal data center cage-level access and financial institution vault entry. |
| Cloud-Native Subscription Migration | Captures operational expenditure preference among commercial real estate owners repositioning Class A office assets. |
| Channel Partnership Consolidation | Strengthens North American distribution control against European hardware specialists and emerging platform disruptors. |
Research Methodology
Independent corroboration across security operations executives at commercial real estate portfolios, federal agency procurement officers, and healthcare network CSOs underwrites the qualitative findings in this study. Primary interviews with facility managers, biometric system integrators, and cloud platform engineers combined with secondary validation from FCC equipment authorization databases, NIST SP 800-63 guideline revisions, and state legislative tracking of Illinois BIPA and Texas CUBI amendments. Bottom-up credential shipment analysis and top-down enterprise IT security spending estimates provided triangulation anchors.
Comparable-period anchoring to pre-pandemic physical security capital expenditure baselines established the forecast trajectory across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, facility ownership structure, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new construction specification trends. Industry-specific inputs encompass data center construction permits in Northern Virginia and Phoenix, plus healthcare merger announcement tracking across Ontario and Quebec.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC equipment authorization timeline compression and state-level biometric privacy statute proliferation. Deviation in federal zero-trust architecture implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
Vehicle Security System Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
China Access Control Market
Access Control Systems
Germany Access Control Market
Access Control Systems
South Korea Access Control Market