
 Personal Safety Alarms Market | 2026-2036
Personal Safety Alarms Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Safety Alarms Market Analysis
Polycarbonate housings is rebalancing cost-to-durability ratios across mid-tier personal safety alarms. SABRE Security Equipment Corporation leverages its North American manufacturing footprint to sustain price competitiveness in keychain and pepper spray-integrated units. Honeywell International Inc. anchors its position through commercial channel dominance, supplying institutional buyers with networked emergency alert systems. Mace Security International, Inc. differentiates via brand recognition in the personal attack alarm segment, where consumer trust directly influences purchase decisions.
A personal safety alarm is a portable, battery-powered acoustic or electronic device engineered to emit high-decibel sound bursts or transmit distress signals to preconfigured contacts or monitoring services, typically operating at 120-140 dB output levels. Its primary commercial purpose is to deter assailants, summon assistance, and provide geolocated emergency response coordination for vulnerable individuals. Smart alarms with mobile app integration command the fastest expansion trajectory as subscription-based monitoring services create recurring revenue streams for manufacturers. Keychain alarms retain the largest volume share due to minimal price points and impulse-purchase channel placement, though margin pools concentrate in GPS-enabled wristband formats targeting outdoor enthusiasts and lone-worker applications.
The FCC regulates radio-frequency transmission standards for GPS and Bluetooth-enabled devices in the United States, while the EU AI Act and GDPR impose data-handling requirements on smart alarms processing biometric or location information in European markets. OSHA guidelines for lone-worker protection in commercial settings increasingly specify audible alarm capability as a baseline compliance element. Stakeholders must monitor evolving cybersecurity certification requirements for connected safety devices as regulatory scope expands beyond hardware safety to encompass data integrity and encryption standards.
Market Dynamics
Bluetooth Low Energy and GPS integration is collapsing the functional boundary between standalone acoustic alarms and networked emergency response systems, forcing manufacturers to choose between hardware margins and recurring service revenue streams.
Growth Catalysts
- Campus Safety Mandates:United States educational institutions now require audible alarm capability under Clery Act compliance protocols, institutionalizing bulk procurement cycles for keychain and wristband formats.
- REACH Chemical Restrictions:European polycarbonate sourcing standards are accelerating housing material upgrades, pushing mid-tier suppliers toward certified supply chains that lock in durability claims.
- Lone-Worker Protection Guidelines:OSHA commercial specifications for isolated employees are converting reactive safety equipment into mandated compliance infrastructure across warehousing and utilities sectors.
Market Restraints
- Lithium-Ion Cell Volatility:Battery chemistry price swings and constrained cobalt supply from Central African sources compress margin predictability for GPS-enabled units requiring extended operational life.
- FCC Certification Friction:Radio-frequency device approval timelines for Bluetooth and cellular transmission modules create 4-6 month market entry delays that favor incumbents with established testing relationships.
- Smartphone Substitution Risk:Native emergency SOS functions in iOS and Android ecosystems threaten standalone device relevance among price-sensitive younger demographics.
Strategic Opportunities
- Subscription Monitoring Services:Recurring revenue models for 24/7 professional response coordination are unlocking lifetime value multiples that hardware sales alone cannot capture.
- India Urban Safety Infrastructure:Metro rail expansion and night-shift economy growth in Mumbai, Bangalore, and Delhi are creating first-time buyer cohorts without entrenched brand loyalties.
- EU AI Act Compliance Positioning:Early certification for biometric-adjacent processing creates defensible positioning as data-handling requirements tighten across connected safety devices.
Industry Challenges
- Firmware Security Talent Scarcity:Embedded systems engineering expertise for over-the-air update architectures remains concentrated in semiconductor hubs, forcing alarm manufacturers into costly contractor dependencies.
- Multi-Standard Certification Overlap:Simultaneous FCC, CE marking, and BIS compliance for global product lines fragments testing budgets and extends redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Safety Alarms Market |
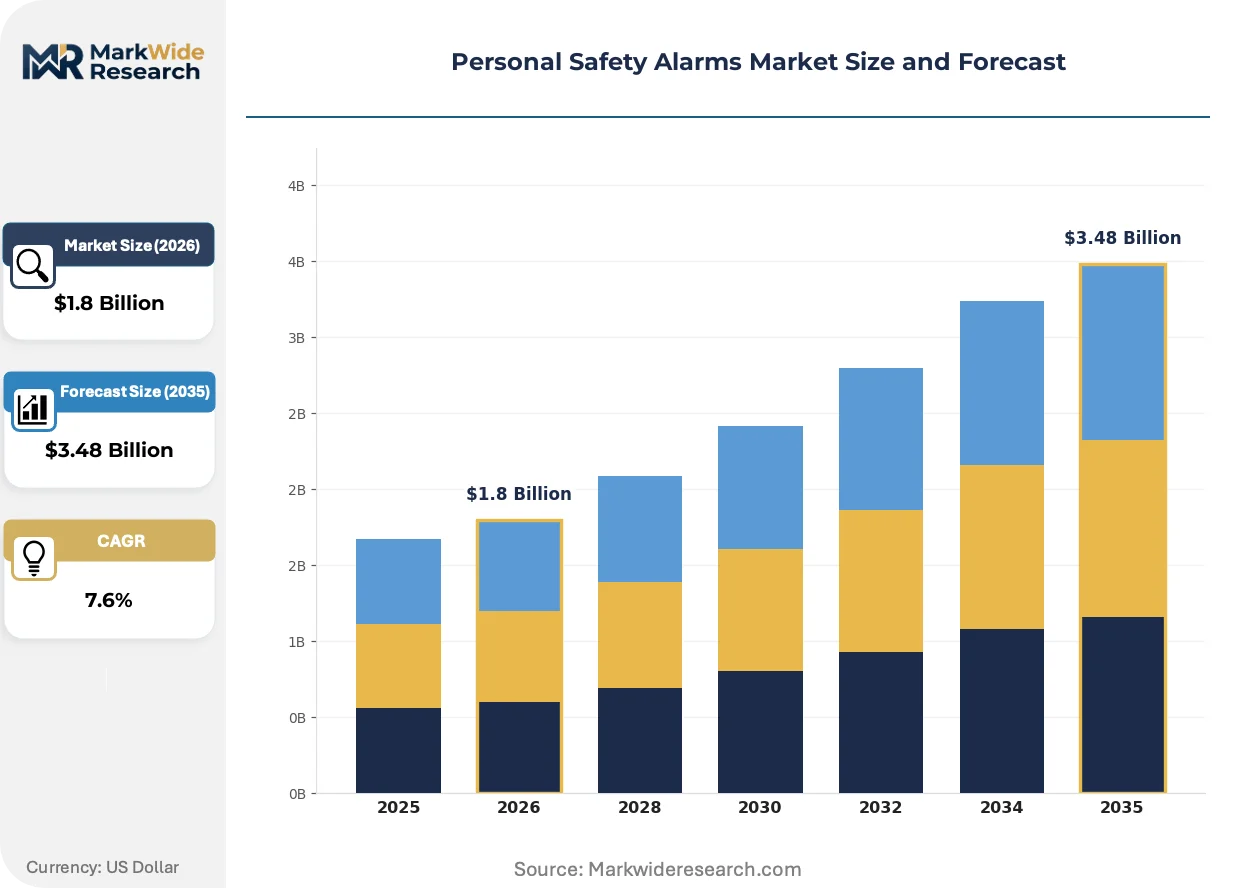
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keychain Alarms, Wristband Alarms, Personal Attack Alarms, Smart Alarms End User: Individual Consumers, Schools, Security Personnel, Outdoor Enthusiasts Technology: Bluetooth, Mobile App Integration, GPS Tracking, Sound Emitters Application: Personal Safety, Emergency Situations, Outdoor Activities, Travel Safety |
| Companies Covered | Basu Protective Products, JNE Security, Ltd., SABRE Security Equipment Corporation, Honeywell International Inc., Birdie Personal Safety, Inc., Mace Security International, Inc., Doberman Security Products Inc., Guard Dog Security, Streetwise Security, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Safety Alarms Market Emerging Trajectories
Acoustic hardware is surrendering standalone status to software-defined functionality, with mobile application ecosystems now determining user retention and upgrade cycles rather than decibel output specifications alone.
Polycarbonate-ABS composite housings is consolidating around mid-tier price-performance positioning as manufacturers abandon metal enclosures for weight reduction and RF transparency. Outdoor recreation buyers and campus procurement officers are standardizing on these formulations for drop-resistance claims. The shift is compressing premium-tier pricing power while elevating baseline durability expectations across impulse-purchase channels.
GDPR Article 35 data protection impact assessments are imposing documented risk analysis requirements on smart alarm vendors processing geolocation histories in European markets. Manufacturers must now maintain auditable consent chains and breach notification protocols that mirror financial services compliance burdens. GPS-enabled wristband suppliers targeting Germany and France are restructuring cloud architectures to satisfy CNIL and BfDI enforcement precedents.
Direct-to-consumer subscription bundling is displacing retail channel dependency as primary customer acquisition mechanics. Amazon and specialized outdoor retailers still dominate volume, but vendor-controlled websites with trial-period monitoring services capture higher lifetime value. This pattern concentrates in United States urban markets where digital-native buyers research safety devices through social proof rather than in-store comparison.
Personal Safety Alarms Market Segmentation
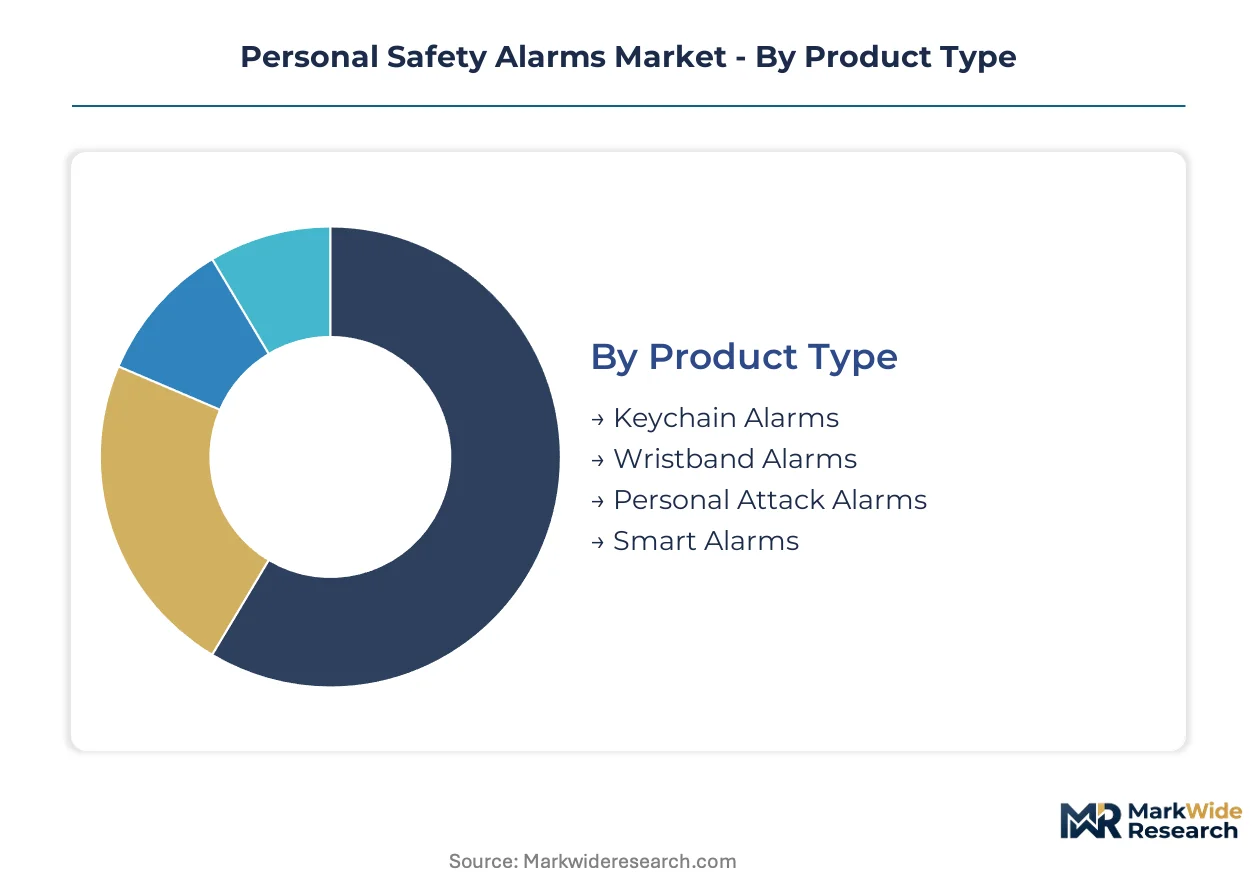
Segmentation in the personal safety alarms market reveals how certification requirements, price tiers, and connectivity standards fragment buyer behavior across consumer, institutional, and commercial channels. Each dimension carries distinct margin profiles and regulatory exposure that shape vendor positioning.
Product Type:
FCC certification timelines stretch longest for GPS-enabled formats, while simple acoustic devices clear regulatory gates fastest.
- Keychain Alarms:Compact acoustic devices operating at 120-140 dB with pull-pin activation. Demand concentrates in United States campus procurement channels under Clery Act compliance mandates, though margin compression limits supplier innovation investment.
- Smart Alarms:Bluetooth Low Energy and cellular-connected units with cloud-based monitoring backends. Outdoor enthusiasts and lone-worker employers in Germany and France drive fastest expansion as GDPR Article 35 compliance costs filter out smaller competitors.
- Wristband Alarms:Wearable formats with GPS tracking and fall detection. United States warehousing sector adoption accelerates under OSHA lone-worker guidelines.
- Personal Attack Alarms:Dedicated acoustic deterrents with pepper spray integration. United Kingdom and Australian urban self-defense markets sustain volume through retail impulse placement.
Keychain Alarms sits at the top of the volume ranking, with Smart Alarms climbing the fastest.
End User:
Procurement authority and compliance burden separate institutional buyers from discretionary consumer purchases.
- Individual Consumers:Price-sensitive buyers purchasing through Amazon and direct-to-consumer channels. United States urban millennials and Gen Z cohorts show highest smartphone substitution risk as native iOS and Android SOS functions improve.
- Outdoor Enthusiasts:GPS-dependent users requiring extended battery life and satellite fallback. Colorado and Utah trail-running communities, plus German Alpine Club members, command premium pricing for ruggedized wristband formats.
- Schools:United States educational institutions bound by Clery Act audible alarm mandates. Bulk procurement cycles favor established suppliers with FCC pre-certification and established campus security distributor relationships.
- Security Personnel:Commercial guards and facility managers requiring networked alert systems. United Arab Emirates and Saudi Arabia smart city deployments create concentrated demand for centralized monitoring integration.
Individual Consumers dominates absolute unit volume, while Schools delivers the most predictable recurring procurement cycles.
Technology:
Radio-frequency modules determine certification complexity and supply chain concentration for component sourcing.
- GPS Tracking:Satellite positioning with geofencing and breadcrumb trail logging. United States national park visitors and Indian metro rail commuters in Mumbai and Delhi generate divergent feature requirements.
- Mobile App Integration:Smartphone-tethered control interfaces with subscription monitoring backends. Recurring revenue potential attracts venture-funded entrants, though customer acquisition costs strain unit economics.
- Bluetooth:Short-range connectivity for proximity alerts and device location. Low power consumption suits keychain formats but limits standalone emergency response capability.
- Sound Emitters:Piezoelectric acoustic generators at 120-140 dB output. Simplest technology tier avoids FCC radio-frequency certification entirely, preserving margin for price-competitive positioning.
Sound Emitters retains manufacturing simplicity leadership, with GPS Tracking gaining feature premium traction fastest.
Application:
Use-case specificity determines whether buyers prioritize decibel output, connectivity redundancy, or concealment.
- Personal Safety:Urban commuting and daily carry scenarios emphasizing discrete activation. Tokyo and Seoul dense transit systems drive demand for silent alert modes with location sharing.
- Outdoor Activities:Remote-area recreation requiring satellite connectivity and weather resistance. Patagonia and REI retail placement validates premium wristband pricing in United States markets.
- Emergency Situations:Rapid response coordination with professional monitoring services. European GDPR compliance costs favor larger vendors with dedicated data protection officers and auditable consent chains.
- Travel Safety:International tourists seeking familiar brand assurance in unfamiliar environments. Airport duty-free and hotel gift shop placement sustains keychain alarm velocity.
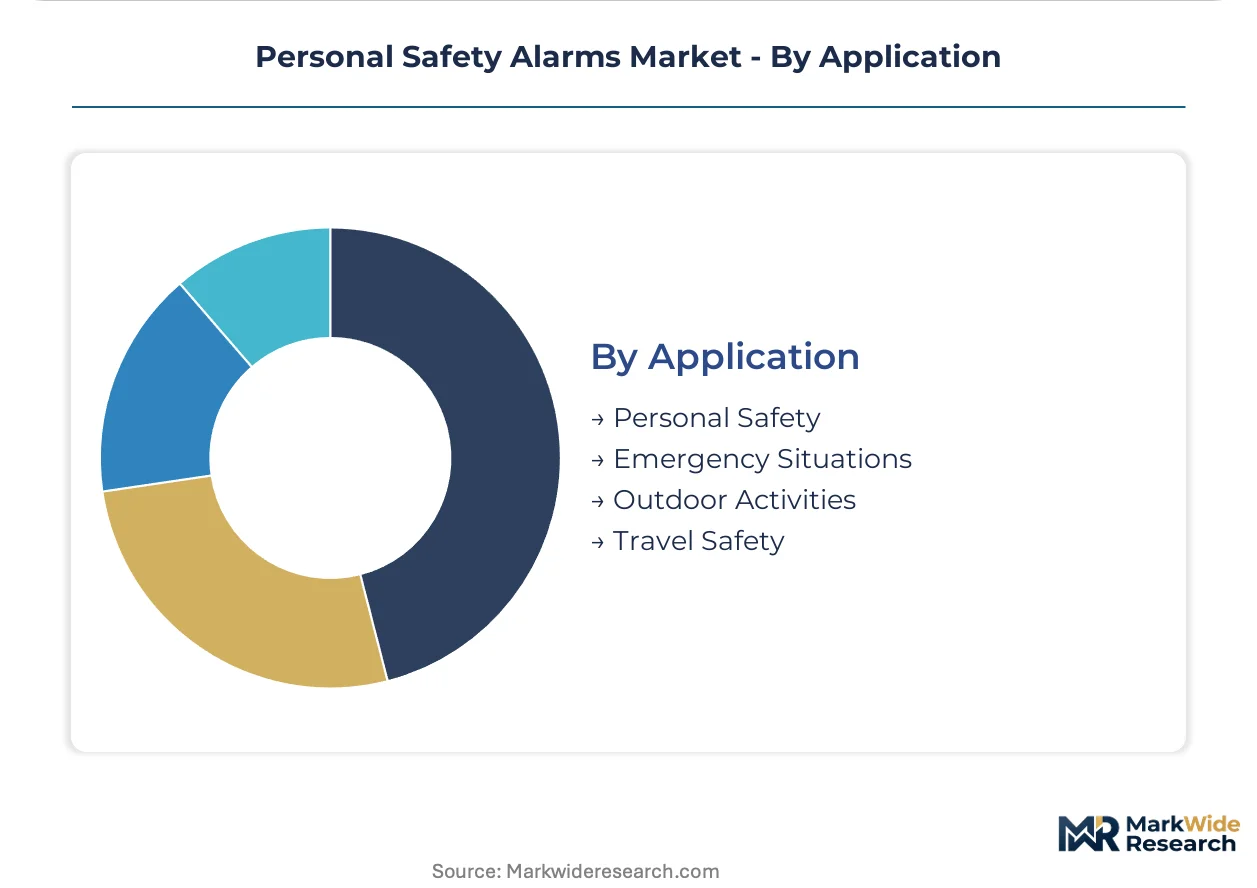
Personal Safety anchors baseline volume, with Outdoor Activities expanding most quickly as trail sports participation rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States campus safety procurement clusters anchor the personal safety alarms market, with institutional buyers driving volume through compliance-mandated bulk purchasing cycles. Federal and state-level safety regulations institutionalize demand across educational and commercial channels. Geographic concentration reflects both regulatory stringency and outdoor recreation participation rates.
United States
Clery Act compliance mandates at universities and colleges sustain predictable institutional procurement cycles for keychain and wristband formats. FCC radio-frequency certification requirements for Bluetooth and GPS-enabled devices create 4-6 month approval timelines that favor established suppliers with testing relationships. Colorado and Utah outdoor recreation communities command premium pricing for ruggedized GPS wristbands targeting trail runners and backcountry skiers.
Germany
GDPR Article 35 data protection impact assessments impose documented risk analysis requirements on smart alarm vendors processing geolocation histories. BfDI enforcement precedents in Berlin and Munich are restructuring cloud architectures for GPS-enabled wristband suppliers. The German Alpine Club membership base sustains premium demand for satellite-connected outdoor safety devices with extended battery specifications.
United Kingdom
Urban self-defense awareness in London and Manchester drives retail impulse placement of personal attack alarms with pepper spray integration. The CNIL-equivalent Information Commissioner's Office enforces data-handling standards on connected safety devices processing biometric information. Birmingham and Leeds distribution hubs concentrate fulfillment for direct-to-consumer subscription bundling models displacing traditional retail dependency.
India
Mumbai, Bangalore, and Delhi metro rail expansion creates first-time buyer cohorts without entrenched brand loyalties in urban safety infrastructure. BIS certification requirements for electronic safety devices filter out smaller competitors lacking testing infrastructure. Night-shift economy growth in Hyderabad and Pune commercial districts amplifies demand for discrete personal safety devices among female commuters.
France
CNIL enforcement of GDPR geolocation consent chains elevates compliance costs for smart alarm vendors targeting Paris and Lyon urban markets. The EU AI Act's biometric-adjacent processing requirements create defensible positioning for early-certified suppliers. Marseille and Toulouse campus procurement officers standardize on polycarbonate-ABS composite housings for drop-resistance claims in educational safety mandates.
Personal Safety Alarms Market Vendor Landscape
Global majors compete with regional champions across certification relationships and institutional distribution networks. The vendor base stratifies between diversified conglomerates with commercial channel dominance and specialized personal safety brands leveraging consumer trust. Three archetypes predominate: North American manufacturing-anchored suppliers, networked emergency system integrators, and direct-to-consumer digital-native entrants. Competitive moves concentrate on FCC pre-certification accumulation and subscription monitoring service bundling to capture lifetime value multiples.
Among North American-anchored suppliers, SABRE Security Equipment Corporation and Mace Security International, Inc. represent the brand-recognition tier where consumer trust directly influences purchase decisions in personal attack alarm segments. Honeywell International Inc. occupies a position exemplifying commercial channel dominance through institutional buyer relationships. These three companies anchor the competitive structure, with SABRE and Mace sitting within consumer-facing archetypes while Honeywell exemplifies the infrastructure-scale supplier model serving schools and security personnel networks.
| Leading Market Players |
|---|
| Basu Protective Products |
| JNE Security, Ltd. |
| SABRE Security Equipment Corporation |
| Honeywell International Inc. |
| Birdie Personal Safety, Inc. |
| Mace Security International, Inc. |
| Doberman Security Products Inc. |
| Guard Dog Security |
| Streetwise Security, Inc. |
| Others |
Supply Flow & Price Mechanics
Cobalt price volatility on the London Metal Exchange cascades through lithium-ion battery supply chains, compressing margin buffers for GPS-enabled wristband manufacturers while amplifying cost advantages for acoustic-only keychain producers sourcing alkaline cells domestically.
Pricing Analysis
Input-cost pass-through from polycarbonate resin and battery chemistry fluctuations stratifies pricing across three performance tiers. Premium GPS wristbands anchored by satellite module costs and GDPR-compliant cloud infrastructure command sustained markup power against mid-tier Bluetooth formats and economy acoustic keychains. Pricing pressure intensifies in the keychain segment as Amazon marketplace saturation erodes brand premiums and compresses landed costs toward battery-plus-housing material floors. Individual consumers exhibit highest price elasticity, while institutional buyers under Clery Act mandates absorb moderate premiums for FCC pre-certified bulk lots.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification regime and proposed EU Critical Raw Materials Act provisions are redirecting sourcing strategies toward qualified local polycarbonate compounders and approved battery cell assemblers. Component supply concentrates in China for piezoelectric sound emitters and Bluetooth Low Energy modules, South Korea for advanced lithium polymer cells, and Germany for precision GPS receivers. Raw material dependencies span cobalt from Central African sources, polycarbonate resin from Middle Eastern petrochemical complexes, and rare earth elements for magnetic transducers. Single-source vulnerability concentrates in satellite positioning chipsets where Broadcom and u-blox dominate qualified supplier lists. Distribution runs through campus security distributors in the United States, outdoor specialty retailers in Germany, and direct-to-consumer subscription platforms capturing highest lifetime value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost arbitrage between GDPR-heavy European markets and BIS-filtered Indian entry points creates geographic repositioning incentives for capital deployment, with data protection infrastructure investments in France and Germany running three to four times above equivalent certification outlays in Mumbai and Delhi.
For Market Incumbents: Lock in FCC pre-certification accumulation and established campus distributor relationships as defensive moats against venture-funded smart alarm entrants. Vertical integration into polycarbonate-ABS compounding secures housing cost predictability while subscription monitoring service bundling captures recurring revenue multiples that hardware-only competitors cannot match. Firmware security talent scarcity in semiconductor hubs demands contractor relationship cultivation or acquisition of embedded systems boutiques. For New Entrants and Emerging Players: Night-shift female commuters in Indian metro systems represent an underserved buyer archetype lacking entrenched brand loyalties and seeking discrete activation formats. White-space concentration appears in lone-worker wristband formats for United Arab Emirates warehousing and Saudi smart city deployments, plus GDPR-light acoustic devices for price-sensitive Southeast Asian urban transit markets. Direct-to-consumer trial-period subscription bundling offers the most penetrable go-to-market vector against Amazon-dependent incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware security capabilities and multi-standard certification expertise concentrate in sub-scale engineering teams unable to sustain GDPR, FCC, and BIS compliance overhead simultaneously. Long-term viability favors vendors with hybrid hardware-service revenue models and demonstrated campus procurement channel access. Acquisition target archetypes include GPS wristband specialists with proven OSHA compliance positioning and cloud-native monitoring backends. The signal to watch is BIS certification backlog clearance rates in India as a proxy for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Monitoring Service Launch | Recurring revenue models unlock lifetime value multiples exceeding hardware-only economics in United States urban markets. |
| Backward Integration into Battery Assembly | In-house lithium cell production mitigates cobalt price volatility and secures margin predictability for GPS-enabled formats. |
| GDPR Article 35 Pre-Certification | Early compliance positioning creates defensible moats as CNIL and BfDI enforcement tightens across European smart alarm deployments. |
| Campus Security Distributor Partnership | Clery Act procurement cycles favor established channel relationships over direct sales in United States educational institutions. |
| Firmware Security Capability Acquisition | Embedded systems engineering talent scarcity forces alarm manufacturers into costly contractor dependencies or specialist firm purchases. |
Methodological Framework
Bottom-up campus procurement and lone-worker employer modeling reconciled against top-down polycarbonate housing and battery cell supply tracking forms the analytical core of this study. Primary interviews with campus security directors, OSHA compliance officers at warehousing firms, outdoor specialty retail buyers, and smart alarm firmware engineers combined with secondary validation from FCC equipment authorization databases, BIS certification registries, GDPR enforcement precedent filings, and customs trade data for acoustic device imports. Triangulation across these sources calibrates volume estimates against material flow indicators.
Historical trendline analysis of Clery Act procurement cycles, outdoor recreation participation rates, and night-shift employment growth patterns informs the projection framework. Segmentation dimensions span product type, end-user archetype, connectivity technology, and application use case, with regional regulatory cluster differentiation across United States, German, British, Indian, and French enforcement jurisdictions. CAGRs derive from fitted growth curves against compliance mandate implementation timelines and smartphone SOS substitution risk diffusion models.
Underlying measurement precision varies by segment; institutional procurement through established distributors carries tighter precision than direct-to-consumer subscription velocity estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, battery chemistry cost trajectories, and firmware security talent market tightness. A small set of triggers warrants ongoing watch: FCC certification timeline extensions, cobalt supply disruptions from Central African sources, and native smartphone emergency function capability advancement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Smart Home Safety Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Life Jacket Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Fall Detection System Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Concealable Vest Market
Personal Safety
Child Leash Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Pepper Sprays Market