
 Plastic Lumber Market | 2026-2036
Plastic Lumber Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Lumber Market Analysis
Municipal infrastructure buyers are unwinding decades of pressure-treated timber dependence as coastal replacement cycles and maintenance-cost accounting favor engineered alternatives. Trex Company, Inc. leverages proprietary co-extrusion technology to dominate residential decking channels with fade-resistant capstock formulations. Tangent Technologies, LLC anchors industrial-grade boardwalk and marine applications through high-load structural profiles rated for heavy pedestrian traffic. Fiberon competes aggressively on price-positioned composite lines targeting mid-market home improvement center distribution.
Plastic lumber denotes extruded or molded structural profiles manufactured from recycled thermoplastics, typically high-density polyethylene or commingled post-consumer resins, often blended with wood fiber, mineral fillers, or pure polymer matrices to achieve specified flexural strength, moisture absorption below 2%, and ultraviolet stability for outdoor exposure. Composite lumber captures the dominant value share as builders balance aesthetics with dimensional stability across decking and railing systems. Polyethylene lumber represents the fastest-expanding product category, driven by abundant post-consumer bottle stock and lower processing energy versus PVC alternatives. Municipal end users concentrate demand in boardwalk, pier, and waterfront infrastructure where salt corrosion and insect degradation destroy conventional timber within seven to ten years.
The EPA administers recycled content procurement guidelines under the Comprehensive Procurement Guideline program, while ASTM International maintains D6662 specifications for polyolefin-based plastic lumber dimensional tolerances and structural properties. State regulators in California enforce CalRecycle procurement mandates that prioritize post-consumer recycled content in public works contracts, effectively screening out virgin-only suppliers. The European Chemicals Agency evaluates REACH compliance for additive packages and stabilizers used in exterior-grade formulations, raising formulation costs for exporters serving EU member states. Stakeholders must monitor evolving extended producer responsibility legislation across North American jurisdictions, as these frameworks will determine feedstock access economics and compliance cost allocation between resin suppliers, extruders, and finished goods distributors.
Market Dynamics
Extended producer responsibility frameworks are restructuring feedstock access economics across North American jurisdictions, forcing extruders to secure post-consumer resin supply through municipal collection partnerships rather than spot markets.
Growth Catalysts
- CalRecycle procurement mandates:California's public works contracts now screen for post-consumer recycled content, diverting municipal infrastructure spend toward qualified suppliers.
- Coastal boardwalk replacement cycles:Southeastern US municipalities face seven-to-ten-year timber degradation timelines from salt corrosion and insect damage, accelerating specification shifts.
- Co-extrusion capstock technology:Fade-resistant surface formulations now satisfy aesthetic durability requirements that previously blocked plastic lumber adoption in visible residential applications.
Market Restraints
- Post-consumer HDPE feedstock volatility:Bottle bale prices fluctuate with oil-indexed virgin polyethylene and seasonal collection rates, compressing extruder margins unpredictably.
- Structural load limitations:Current polyolefin formulations cannot match engineered timber span ratings for heavy vehicular bridge applications without excessive profile depth.
- REACH additive compliance costs:European Chemicals Agency evaluations of stabilizer packages raise formulation expenses for exporters serving EU member states.
Strategic Opportunities
- Marine piling and fender systems:Saltwater immersion applications remain underpenetrated by structural thermoplastics despite proven rot resistance versus treated timber.
- Integrated solar mounting platforms:Dual-purpose decking systems that incorporate photovoltaic racking represent an emerging residential retrofit category.
- State-level EPR legislation:New York and Maine extended producer responsibility frameworks will create captive feedstock streams for early-integrating extruders.
Industry Challenges
- ASTM D6662 certification timelines:Third-party structural testing for polyolefin lumber dimensional tolerances delays product launches by six to nine months.
- Extrusion die engineering scarcity:Complex hollow-profile tooling design expertise concentrates among aging specialist machinists in the US Upper Midwest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Lumber Market |
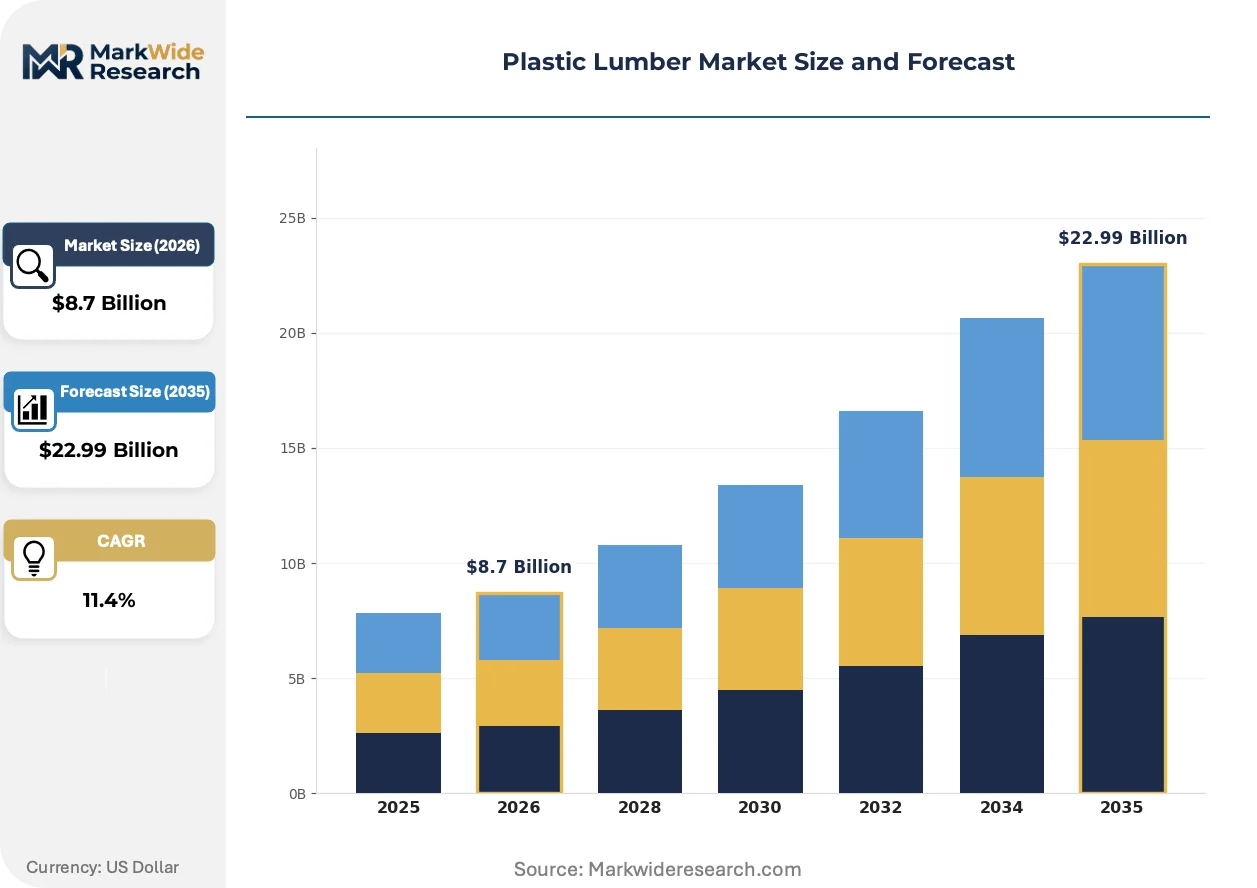
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recycled Plastic, Composite Lumber, Polyethylene Lumber, Polyvinyl Chloride (PVC) Lumber Application: Decking, Fencing, Furniture, Landscape Borders End User: Residential, Commercial, Industrial, Municipal Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Home Improvement Centers |
| Companies Covered | Tangent Technologies, LLC, KWK Plastic Lumber Co., Ltd., Trex Company, Inc., Advanced Environmental Recycling Technology Inc., PlasTEAK, Inc., Fiberon, Genova Products, Inc., Repeat Plastics Australia Pty Ltd., American Recycled Plastic, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Lumber Market Emerging Trajectories
Material science advances and procurement policy realignments are splitting the competitive landscape between premium performance formulations and commoditized recycled-content lines.
Co-extrusion manufacturing is bifurcating the residential decking segment. This process bonds a dense, color-saturated polymer cap over a recycled-content core, delivering fade resistance that satisfies warranty-driven channel requirements. Big-box home improvement retailers now demand capstock-backed products exclusively, compressing non-capped lines into contractor-direct salvage markets.
REACH regulation expansions are tightening additive disclosure requirements across EU member states. The European Chemicals Agency now evaluates UV stabilizer and pigment packages for Substances of Very High Concern classification, forcing reformulation investments. Exporters serving German and French infrastructure projects face elevated compliance documentation burdens that domestic EU competitors navigate more efficiently.
Municipal procurement departments are consolidating specifications around life-cycle cost accounting rather than first-cost bidding. Engineering firms in Florida and the Carolinas now model twenty-year maintenance avoidance against treated timber replacement schedules. This analytical shift favors plastic lumber in boardwalk RFPs where salt exposure previously triggered automatic timber specifications.
Plastic Lumber Market Segmentation
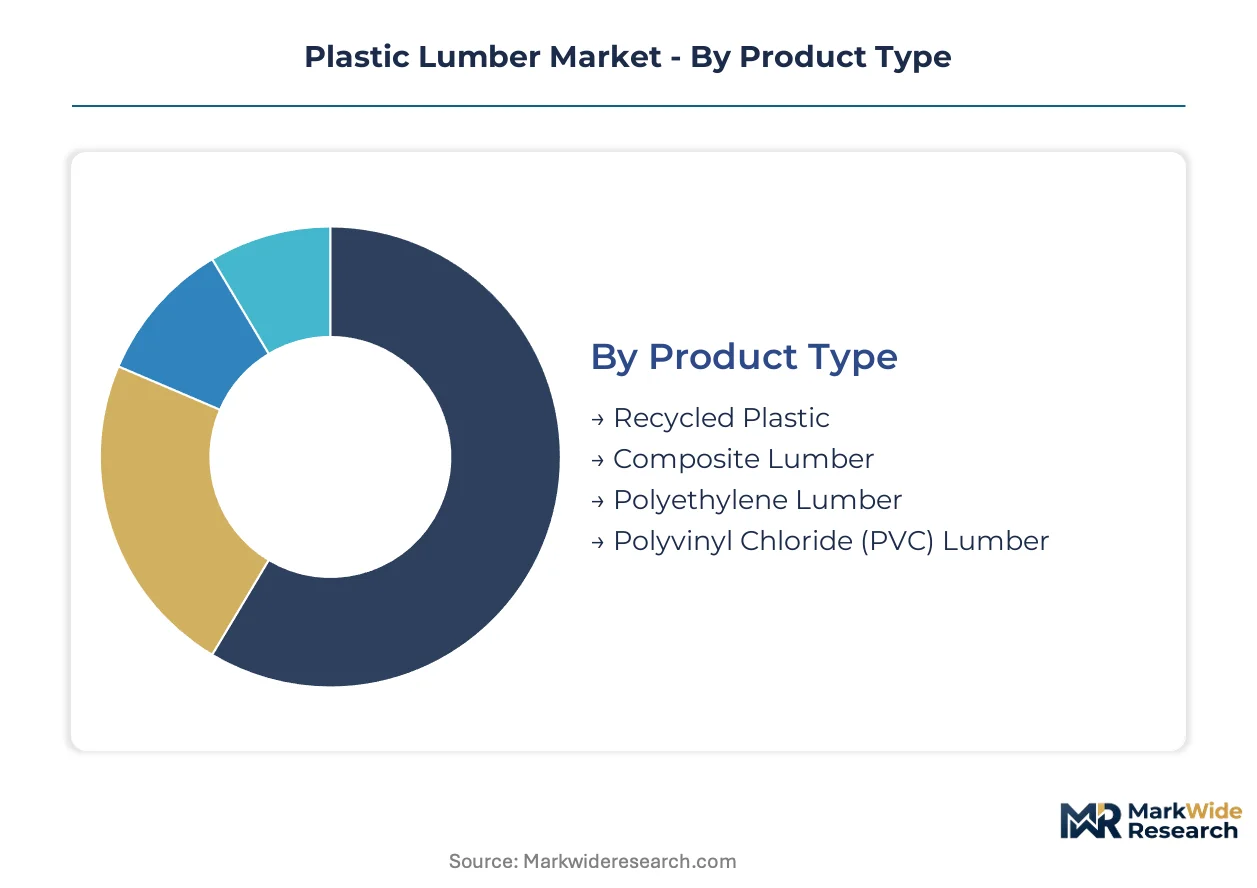
Segmentation in the plastic lumber market exposes how feedstock economics, load-bearing specifications, and procurement channel power reshape profitability across product tiers. Understanding where margin pools concentrate helps extruders prioritize formulation investments and distribution partnerships.
Product Type:
Margin pools sit with formulations that command specification premiums in structural and aesthetic applications while managing volatile post-consumer resin costs.
- Composite Lumber:Blends recycled thermoplastics with wood fiber or mineral fillers to achieve dimensional stability and natural wood aesthetics. Demand concentrates in residential decking across the southeastern United States, where humidity resistance and fade-resistant capstock technology satisfy warranty requirements from big-box retailers.
- Polyethylene Lumber:Manufactured from pure high-density polyethylene or commingled post-consumer resins without wood fiber additives, delivering moisture absorption below 2% for marine and waterfront infrastructure. Florida and Carolina municipalities specify this grade for boardwalk replacement cycles where salt corrosion destroys treated timber within seven to ten years.
- Recycled Plastic:Extruded profiles from mixed post-consumer streams with lower flexural strength ratings, serving non-structural landscape and utility applications.
- Polyvinyl Chloride (PVC) Lumber:Virgin or recycled-content formulations offering superior chemical resistance for industrial containment and specialized architectural profiles.
Composite lumber holds installed capacity. Polyethylene lumber is rotating up the share rankings.
Application:
Volume concentration tracks coastal infrastructure replacement cycles and residential retrofit activity, with specification power shifting toward engineering firms and municipal procurement departments.
- Decking:Capstock-backed co-extruded products dominate visible residential installations, with fade resistance now a non-negotiable channel requirement. Big-box home improvement centers demand exclusively capped formulations, compressing non-capped lines into contractor-direct salvage markets.
- Fencing:Privacy and perimeter systems favor polyethylene lumber for moisture immunity in humid climates, though load-bearing posts require reinforced profiles that increase material cost.
- Furniture:Outdoor seating and recreational fixtures specify lighter-weight recycled plastic grades where structural span requirements remain modest.
- Landscape Borders:Non-structural edging and retaining applications absorb lower-grade commingled resins with minimal performance certification overhead.
Decking captures the dominant revenue share. Fencing is climbing the fastest as perimeter security specifications expand.
End User:
Customer type determines procurement methodology, with municipal buyers leveraging life-cycle cost accounting against residential consumers prioritizing upfront price and aesthetic warranty terms.
- Municipal:Public works departments in coastal jurisdictions now model twenty-year maintenance avoidance against treated timber replacement schedules. Florida engineering firms specify plastic lumber for boardwalk RFPs where salt exposure previously triggered automatic timber specifications.
- Residential:Homeowners select decking and fencing through home improvement center channels, with purchase decisions driven by color retention warranties and installation contractor recommendations.
- Commercial:Hospitality and retail property managers balance durability requirements with brand aesthetic standards in outdoor seating and pedestrian platform applications.
- Industrial:Manufacturing facilities and logistics operations specify heavy-load profiles for platforms and containment systems where chemical resistance outweighs surface appearance.
Municipal end users hold specification influence. Residential buyers are rotating up the share rankings.
Distribution Channel:
Channel power concentrates with buyers who control shelf space and contractor specification authority, squeezing margin from extruders unable to secure preferred vendor status.
- Home Improvement Centers:National retailers demand exclusive capstock-backed product lines and volume commitments that favor scaled extruders with co-extrusion manufacturing capabilities.
- Wholesale Distributors:Regional lumber and building material distributors serve contractor channels with mixed product tiers, capturing margin through logistics consolidation and credit terms.
- Specialty Stores:Localized decking and outdoor living showrooms provide specification support for premium residential projects with custom color and profile requirements.
- Online Retail:Direct-to-consumer and contractor platforms expand access for standardized profiles in peripheral geographies with limited physical distribution.
Home improvement centers hold channel power. Wholesale distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Atlantic Intracoastal Waterway's boardwalk replacement cycles across southeastern states anchor United States demand for humidity-resistant structural materials. Port infrastructure rehabilitation from Florida to Virginia drives specification shifts toward engineered alternatives that withstand salt corrosion.
United States
Florida municipalities lead boardwalk procurement, with engineering firms modeling twenty-year maintenance avoidance against treated timber replacement schedules. The EPA's Comprehensive Procurement Guideline program mandates recycled content in federal contracts. Coastal counties from Miami-Dade to the Outer Banks specify polyethylene lumber for pier and waterfront infrastructure.
Germany
Industrial containment and chemical-resistant platforms drive specification of rigid PVC formulations in manufacturing corridors. ECHA's REACH evaluations of UV stabilizer packages force reformulation investments for exporters. The Ruhr industrial cluster absorbs specialized profiles for heavy-load platforms where chemical resistance outweighs surface appearance.
Canada
Waterfront trail systems and park boardwalks in Ontario and British Columbia accelerate polyethylene lumber adoption for freeze-thaw durability. Environment Canada's procurement guidelines prioritize post-consumer recycled content in federal infrastructure contracts. Vancouver's Stanley Park rehabilitation exemplifies municipal specification shifts toward rot-resistant alternatives.
Australia
Coastal council boardwalks from Queensland to New South Wales specify plastic lumber for termite resistance and salt-air degradation avoidance. The country's national environmental regulator enforces product stewardship frameworks that reshape feedstock access economics. Repeat Plastics Australia anchors domestic supply chains through municipal collection partnerships.
United Kingdom
Thames waterfront promenades and coastal path networks drive demand for slip-resistant decking profiles. The Environment Agency's procurement standards screen for recycled content in public works contracts. Engineering firms in southeast England now specify engineered alternatives for marine exposure applications previously reserved for treated timber.
Plastic Lumber Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and feedstock security dimensions. The vendor base concentrates around extrusion technology holders with co-extrusion capabilities and municipal procurement relationships. Three archetypes dominate: vertically integrated resin-to-profile manufacturers, pure-play extruders with regional collection partnerships, and diversified building materials conglomerates with composite divisions. Competitive moves center on municipal contract capture and backward integration into post-consumer resin supply.
Among North American fabricators, Trex Company, Inc. and Tangent Technologies, LLC occupy positions at opposite ends of the application spectrum. Trex exemplifies the residential decking specialist with capstock-backed product lines demanded by national home improvement retailers. Tangent Technologies, LLC represents the infrastructure-grade segment, anchoring industrial boardwalk and marine applications through structural profile capabilities. Fiberon sits within the price-competitive mid-market tier, targeting contractor channels with value-positioned composite lines. KWK Plastic Lumber Co., Ltd. indicates the geographic diversification of competitive presence beyond North American headquarters.
| Leading Market Players |
|---|
| Tangent Technologies, LLC |
| KWK Plastic Lumber Co., Ltd. |
| Trex Company, Inc. |
| Advanced Environmental Recycling Technology Inc. |
| PlasTEAK, Inc. |
| Fiberon |
| Genova Products, Inc. |
| Repeat Plastics Australia Pty Ltd. |
| American Recycled Plastic, Inc. |
| Others |
Supply Flow & Price Mechanics
Post-consumer HDPE bottle bale substitution for virgin polyethylene feedstock simultaneously concentrates supply geography around municipal collection hubs in the southeastern United States and compresses pricing power toward resin aggregators who control bale flow. This feedstock pivot reshapes extruder margins unpredictably as oil-indexed virgin resin and seasonal collection rates oscillate.
Pricing Analysis
Volume-discount tiering structures separate premium capstock-backed composite decking from standard polyethylene lumber and economy-grade recycled plastic profiles. Price differentiation rests on ASTM D6662 certification status and co-extrusion technology ownership, with certified structural grades commanding specification premiums in municipal RFPs. Pricing pressure stems from post-consumer resin volatility squeezing mid-tier extruders without backward integration into collection partnerships. Residential home improvement center buyers exhibit highest price sensitivity, while municipal procurement departments prioritize life-cycle cost accounting over first-cost bidding.
Supply Chain Analysis
Inbound logistics costs from port congestion on Asia-Pacific trade lanes elevate landed costs for specialty additive packages and UV stabilizers sourced from chemical manufacturers in China and South Korea. Raw material dependencies center on post-consumer HDPE bottle stock, wood fiber fillers from southern US timber operations, and REACH-compliant stabilizer formulations. Supply chain risk concentrates in single-source vulnerability for complex hollow-profile extrusion dies engineered by specialist machinists in the US Upper Midwest. Distribution runs through national home improvement centers and regional wholesale distributors serving contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic lumber market functions as a service-attach opportunity where installation contractor networks and extended color-retention warranty programs expand faster than base material sales. Recurring revenue from maintenance service contracts and replacement-part provisioning now outpaces hardware growth in premium residential segments.
For Market Incumbents: Shield market position by securing exclusive municipal collection partnerships for post-consumer resin feedstock before state-level EPR legislation in New York and Maine locks up supply. Invest in co-extrusion capacity additions in the southeastern United States to satisfy big-box retailer capstock requirements. Certification investment in marine-grade structural profiles defends against infrastructure-specialist competitors. For New Entrants and Emerging Players: Lead with marine piling and fender systems where saltwater immersion applications remain underpenetrated despite proven rot resistance versus treated timber. Target coastal municipalities from Florida to the Outer Banks with integrated solar mounting platforms as dual-purpose decking systems. Pursue direct contractor channel relationships bypassing home improvement center gatekeepers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated resin-to-profile manufacturers with captive post-consumer supply. Long-term viability hinges on EPR framework positioning across North American jurisdictions. Acquisition targets should demonstrate municipal procurement relationships and ASTM D6662 certification capabilities. The signal to watch is CalRecycle-style procurement mandate adoption in additional states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Resin Collection | Secures captive HDPE bottle bale supply ahead of EPR legislation in Maine and New York. |
| Co-Extrusion Capacity Expansion | Satisfies Home Depot and Lowe's capstock-backed product exclusivity requirements for residential decking. |
| ASTM D6662 Certification Investment | Unlocks municipal boardwalk RFPs in Florida and Carolina coastal counties. |
| Marine-Grade Structural Profile Development | Captures underpenetrated saltwater piling and fender system applications. |
| Installation Contractor Network Buildout | Generates recurring service revenue and specification influence in residential retrofit projects. |
Methodological Framework
Cross-validation between extrusion plant manager interviews and municipal procurement officer discussions anchors the qualitative findings in operational reality. Primary fieldwork encompassed resin procurement leads at compounders, distribution channel partners in building materials, technical R&D directors at formulation houses, and public works engineers in coastal jurisdictions. Secondary validation drew from EPA Comprehensive Procurement Guideline documentation, CalRecycle mandate filings, ASTM International standards publications, and SEC 10-K disclosures from listed building materials conglomerates. Bottom-up capacity modeling and top-down demand triangulation from construction permit data converge on segment-level outputs.
Sensitivity analysis around post-consumer resin price volatility and EPR adoption timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application load-bearing specification, end-user procurement methodology, and regional climatic exposure pattern. CAGRs derive from elasticity-adjusted demand curves and capacity utilization trajectories. Industry-specific forecast inputs encompass coastal boardwalk replacement cycle timing and home improvement center inventory policy shifts.
The analysis sits within stated boundaries; outcomes outside sustained municipal procurement mandate enforcement and co-extrusion technology diffusion would require recalibration. Forecasts reflect documented assumptions regarding resin feedstock availability and certification timeline stability. Specific risk factors that could revise projections include REACH additive compliance cost escalation and extrusion die engineering talent attrition. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
South-East Asia (SEA) Plastics Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
China Plastics Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Plastic Compounds Market