
 Aluminum Powders Pastes and Flakes Market | 2026-2036
Aluminum Powders Pastes and Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Powders Pastes and Flakes Market Outlook
Direct supply contracts between atomization mills and automotive Tier 1 suppliers is rewriting traditional distributor relationships in the aluminum powders channel. Alcoa Corporation leverages captive bauxite-to-powder integration to sustain cost advantages across North American forging feedstock. ALTANA AG anchors European flake supply through ECKART's dedicated effect-pigment vertical, while Hindalco Industries dominates South Asian spherical powder output for additive manufacturing.
Aluminum powders, pastes, and flakes comprise metallic aluminum reduced to particulate form through atomization, milling, or stamping processes, with particle sizes ranging from sub-micron flakes to millimeter-grade granules depending on end-use thermal or optical requirements. These materials function primarily as feedstock for powder metallurgy compaction, chemical reaction media, and reflective or conductive surface coatings. The powders category leads volume due to mature press-and-sinter infrastructure across automotive and industrial sectors, while flakes command premium positioning in coatings applications where leafing-grade brightness differentiates supplier margins. Pastes represent the fastest-growing form segment as ready-to-dispense formulations reduce VOC handling costs for coatings contractors.
EPA air-quality standards and OSHA combustible-dust regulations constrain U.S. facility siting and material-handling protocols, while REACH registration requirements in Europe mandate full substance characterization for flake imports. China's GB standards for industrial powder purity, administered by SAMR, create divergent certification pathways that fragment cross-border trade eligibility. Stakeholders must monitor regulatory divergence between EPA/OSHA frameworks and China's evolving GB standards when siting blending operations or qualifying new powder grades for aerospace specification.
Market Dynamics
Automotive lightweighting mandates are compressing traditional powder metallurgy timelines as electric vehicle platforms demand aluminum-intensive chassis components at unprecedented scale. Tier 1 suppliers now specify atomized powder lots directly from mills, bypassing established distributor networks and rewiring margin capture across the value chain.
Growth Catalysts
- REACH and RoHS compliance tightening:European purity specifications for leafing-grade flakes are accelerating investment in closed-loop atomization systems. Coatings formulators prioritize certified feedstock to maintain CE marking eligibility.
- Powder metallurgy adoption in automotive:Press-and-sinter infrastructure expansion across North American and Chinese forging operations is pulling spherical aluminum grades into high-volume transmission and suspension programs.
- China's domestic EV scaling:SAMR-administered GB standards for industrial powder purity are concentrating demand around qualified domestic atomizers serving BYD and CATL supply chains.
Market Restraints
- Alumina price volatility:Bauxite refining cost swings transmit directly into atomization feedstock economics, compressing margin visibility for non-integrated powder producers.
- Combustible-dust regulatory burden:OSHA facility-siting constraints and EPA air-quality permitting in the United States limit greenfield expansion options for high-capacity atomization plants.
- Titanium and carbon fiber substitution:Aerospace structural applications are migrating toward composite alternatives in non-critical load paths, capping aluminum flake penetration in premium coatings segments.
Strategic Opportunities
- India's additive manufacturing buildout:PLI scheme incentives for metal 3D printing are creating qualified demand for gas-atomized spherical powders in medical and aerospace prototyping.
- Ready-to-dispense paste formulations:VOC handling cost reduction is driving coatings contractors toward pre-mixed aluminum pastes, opening formulation service revenue streams.
- Dual carbon goals alignment:China's MEE carbon intensity benchmarks favor recycled-content aluminum powders, rewarding secondary smelter integration into atomization supply.
Industry Challenges
- Atomization specialist talent scarcity:Gas-flow dynamics expertise and plasma torch operation skills concentrate among retiring cohorts at legacy aerospace powder facilities.
- Aerospace certification timelines:AMS and ASTM qualification protocols for new powder lots extend 18-24 months, freezing formulation innovation cycles for speculative alloy grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Powders Pastes and Flakes Market |
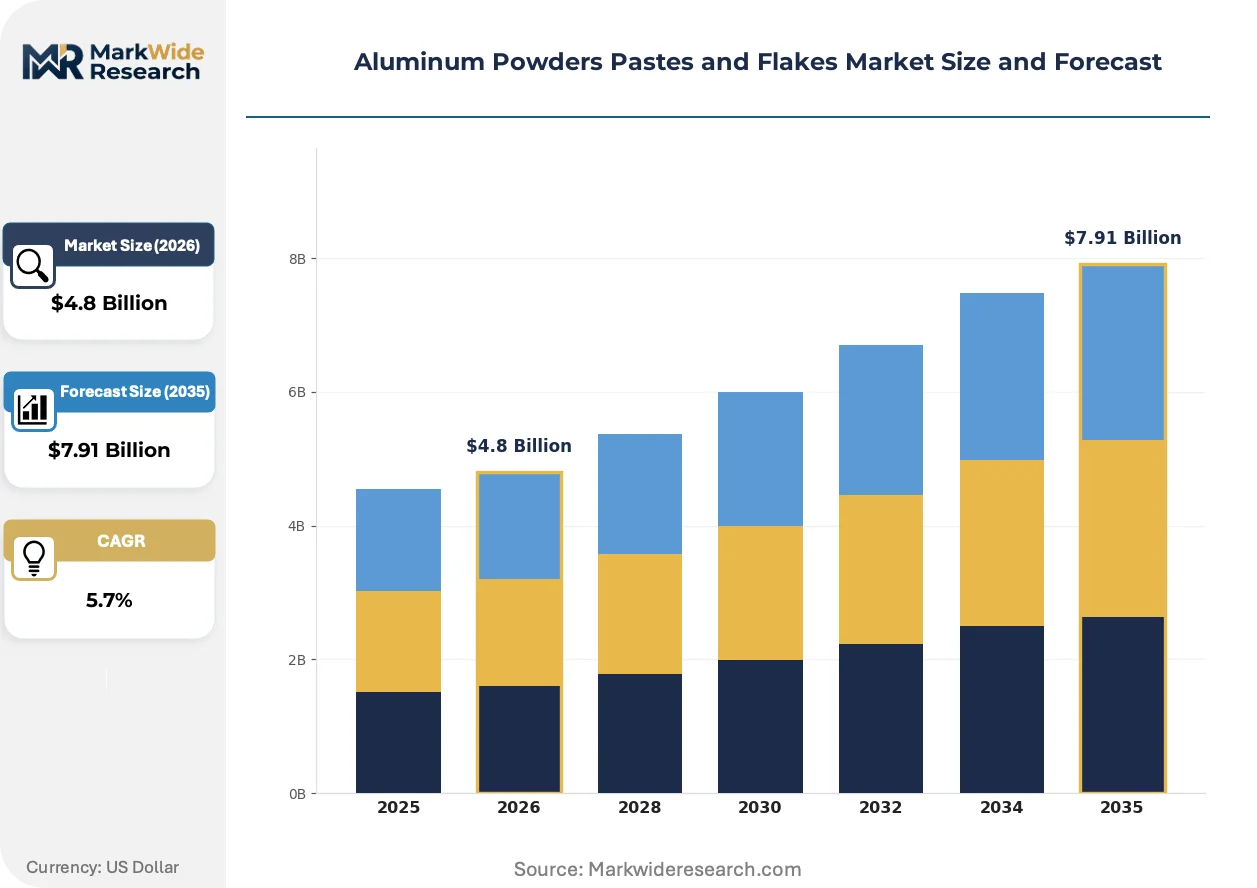
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Powders, Pastes, Granules Application: Aerospace, Automotive, Chemical, Coatings Form: Dry, Wet, Molten, Slurry End User: Manufacturers, Contractors, Retailers, Researchers |
| Companies Covered | Alcoa Corporation, ALTANA AG (ECKART Division), Hindalco Industries Limited, Rio Tinto Group, Norsk Hydro ASA, Metal Powder Company Ltd. (MEPCO), Valimet, Inc., TOYAL Group, Kymera International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Powders Pastes and Flakes Market Strategic Shifts
Plasma rotating electrode atomization is disrupting conventional gas-atomization economics as spherical powder premiums compress and additive manufacturing tolerances tighten. The technology frontier is migrating from premium aerospace toward industrial tooling and automotive prototyping.
Ultrasonic atomization is migrating from laboratory-scale titanium production into commercial aluminum powder streams, enabling tighter particle-size distribution for binder-jet printing applications. German automotive tooling suppliers are qualifying these lots for serial production jigs and fixtures. The structural consequence is that premium spherical grades are migrating from aerospace exclusivity toward mid-volume industrial tooling markets.
REACH registration requirements for imported flake intermediates are forcing full substance characterization down to trace-element fingerprinting. ECHA enforcement is pushing non-European suppliers toward dedicated EU-based blending facilities or joint-venture structures. Leafing-grade pigment producers are responding with captive EU toll-manufacturing arrangements to preserve automotive coatings access.
Direct mill-to-Tier-1 contracting is displacing traditional distributor stocking models as automotive buyers demand lot-traceable atomized powder with embedded carbon-accounting data. This pattern is most visible in China's Yangtze River Delta cluster, where CATL and NIO procurement teams specify SAMR-certified powder streams with integrated blockchain provenance tracking.
Aluminum Powders Pastes and Flakes Market Segmentation
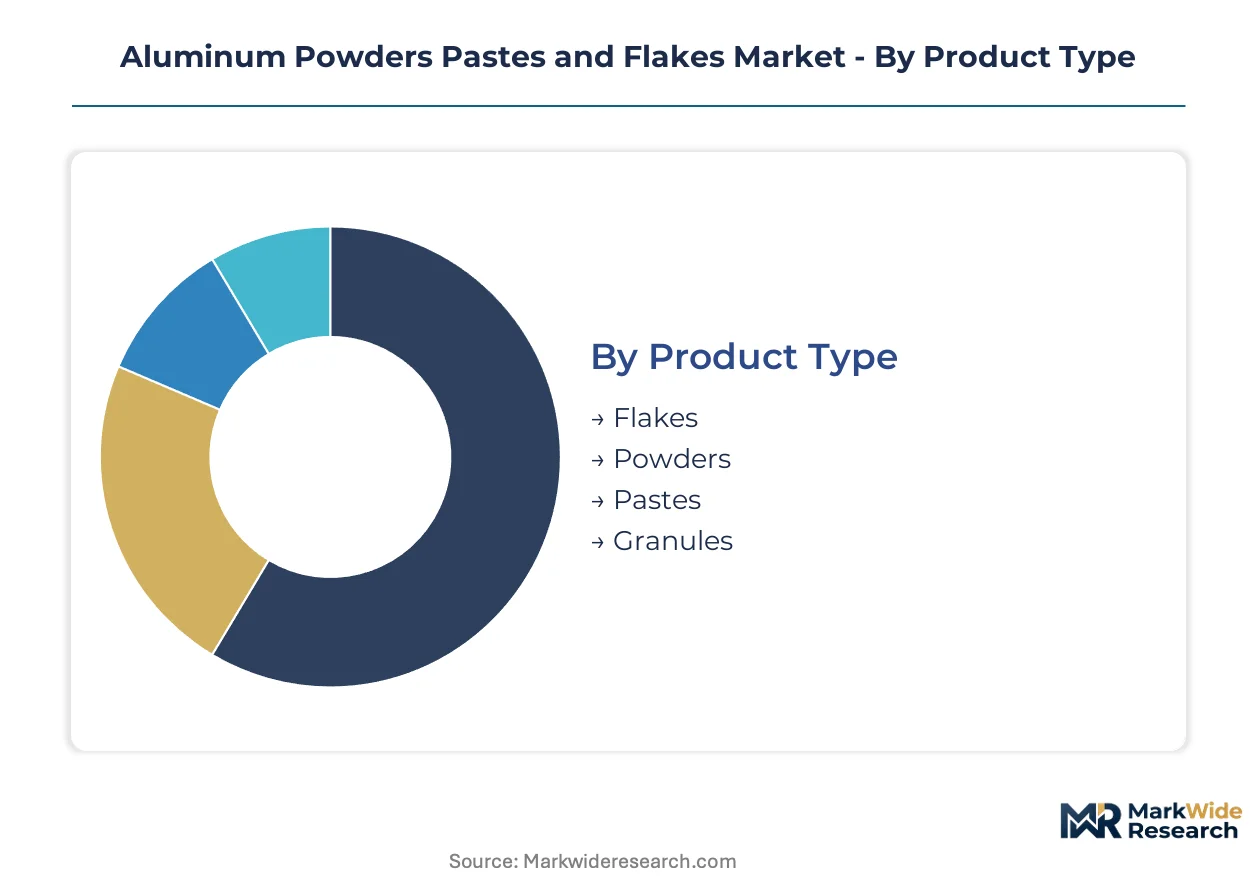
Segmentation in aluminum powders, pastes, and flakes reflects divergent technical specifications across atomization grades, leafing characteristics, and dispersion requirements. Each dimension carries distinct certification burdens and margin structures that reshape supplier positioning.
Product Type:
Cost tier stratification separates commodity atomized grades from premium spherical powders and effect-pigment flakes.
- Flakes:Leafing-grade aluminum flakes achieve directional brightness through controlled milling of atomized feedstock. REACH-registered flake supply is concentrating around German and Austrian toll-manufacturing facilities serving automotive OEM coatings programs.
- Powders:Gas-atomized spherical powders dominate press-and-sinter infrastructure across automotive transmission and suspension forging operations. SAMR-certified atomizers in China's Yangtze River Delta are capturing qualified supply positions for domestic EV chassis programs.
- Pastes:Pre-dispersed aluminum pastes reduce VOC handling costs for coatings contractors. Ready-to-use formulations are climbing the fastest as regulatory pressure on solvent emissions intensifies across European and North American jurisdictions.
- Granules:Millimeter-grade granules serve chemical reaction media and pyrotechnic applications. BIS specifications in India govern purity thresholds for domestic fireworks manufacturing clusters.
Powders hold installed capacity. Pastes are rotating up the share rankings.
Application:
End-use maturity spans from established press-and-sinter automotive volumes to emerging additive manufacturing qualification timelines.
- Aerospace:AMS-specified spherical powders for turbine blade repair and structural additive manufacturing carry 18-24 month qualification protocols. Plasma rotating electrode atomization is compressing premium grade economics as tolerance requirements tighten.
- Automotive:Direct mill-to-Tier-1 contracting is displacing distributor stocking models as EV platforms demand lot-traceable powder with embedded carbon-accounting data. NHTSA lightweighting mandates accelerate aluminum-intensive chassis adoption.
- Chemical:Sub-micron powders function as reduction agents and reaction catalysts across specialty chemical synthesis. Process safety management under OSHA PSM constrains U.S. facility siting for high-surface-area grades.
- Coatings:Leafing and non-leafing flakes deliver reflectivity and corrosion protection across industrial and decorative finishes. ECHA enforcement on REACH registration is forcing non-European suppliers toward dedicated EU blending facilities.
Automotive commands volume concentration. Aerospace maintains premium pricing power through certification barriers.
Form:
Physical state determines handling protocols, shipping economics, and customer processing requirements.
- Dry:Free-flowing powders require nitrogen inerting and explosion-proof handling systems. Combustible dust regulations under OSHA and EPA air-quality standards constrain U.S. greenfield atomization capacity.
- Wet:Solvent-based pastes dominate automotive OEM coatings specifications. VOC content thresholds in EU F-Gas Regulation and parallel U.S. state-level rules are accelerating waterborne formulation migration.
- Molten:Direct melt delivery serves continuous casting and thermal spray operations with minimal oxidation. Metallurgical-grade purity under GB standards governs Chinese domestic trade eligibility.
- Slurry:Aqueous dispersions support binder-jet printing and chemical process integration. Ultrasonic atomization is enabling tighter particle-size distribution for emerging additive manufacturing tooling applications.
Dry form retains infrastructure dominance. Wet formulations are capturing share in regulated coatings markets.
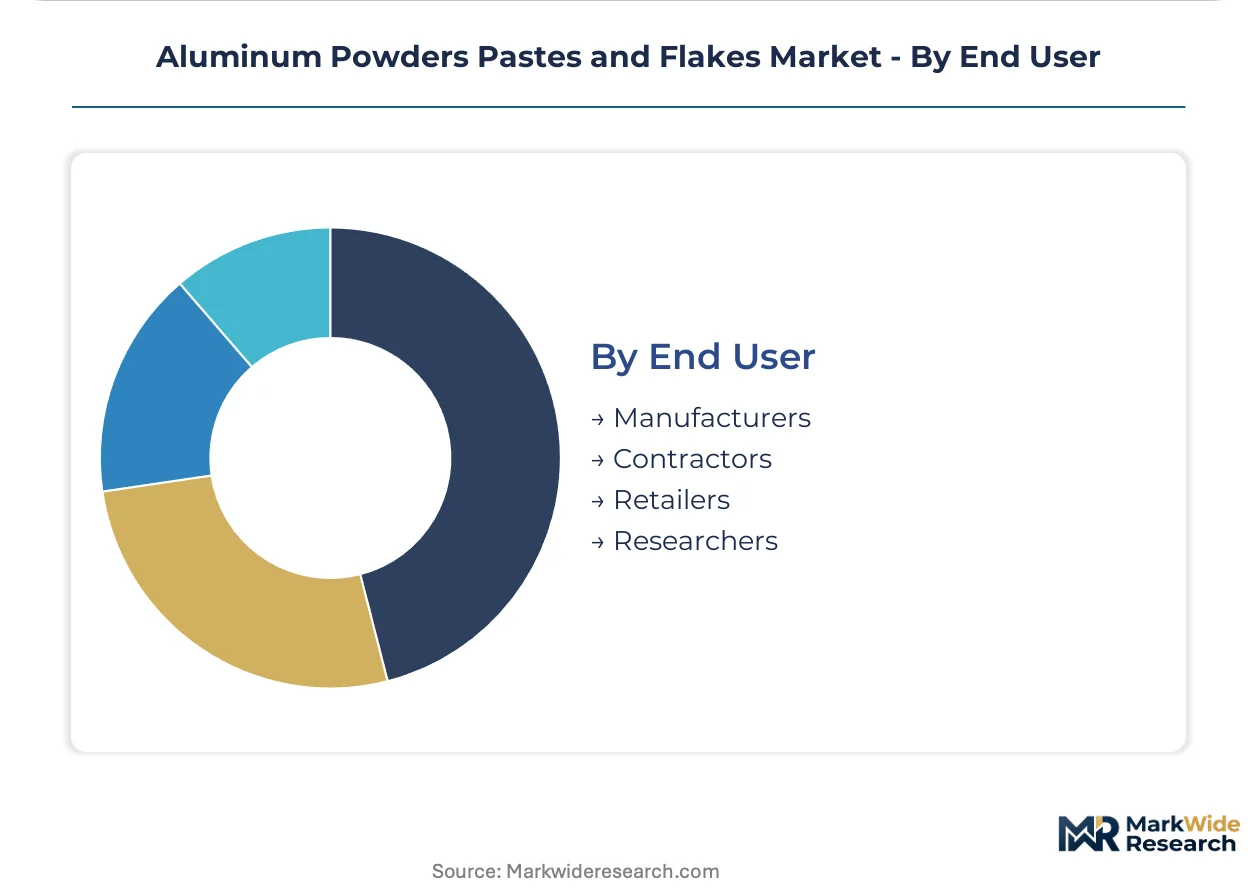
End User:
Customer type shapes procurement patterns from specification-driven OEM qualification to spot-market distributor purchasing.
- Manufacturers:Tier 1 automotive and aerospace forgers specify atomized powder lots directly from mills, bypassing traditional distributor networks. Blockchain provenance tracking is becoming mandatory for CATL and NIO supply chains.
- Contractors:Coatings application specialists prioritize ready-to-dispense pastes to minimize solvent handling compliance costs. Formulation service revenue streams are opening around VOC-reduced product portfolios.
- Researchers:Additive manufacturing prototyping labs drive qualification demand for novel alloy grades. India's PLI scheme incentives are concentrating gas-atomized spherical powder demand in medical and aerospace prototyping.
- Retailers:Specialty chemical and pyrotechnic supply channels serve fragmented downstream applications. BIS certification requirements fragment import eligibility for non-domestic powder sources.
Manufacturers anchor procurement volume. Researchers are expanding fastest as additive manufacturing scales from prototyping toward production tooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR-administered GB standards anchor the dominant geography, fragmenting cross-border trade eligibility while concentrating qualified supply around domestic atomizers serving electric vehicle chassis programs.
China
BYD and CATL procurement teams specify lot-traceable powder with blockchain provenance tracking for aluminum-intensive chassis programs. MEE carbon intensity benchmarks favor recycled-content powders, rewarding secondary smelter integration. The Yangtze River Delta cluster hosts qualified domestic atomizers scaling output for NIO supply chains.
United States
NHTSA lightweighting mandates accelerate press-and-sinter infrastructure expansion across transmission and suspension forging operations. OSHA combustible-dust regulations and EPA air-quality permitting constrain greenfield atomization capacity siting. Michigan and Ohio forging corridors specify direct mill contracts with embedded carbon-accounting data requirements.
Germany
Automotive OEM coatings programs drive REACH-registered flake demand through dedicated toll-manufacturing arrangements. ECHA enforcement on substance characterization pushes non-European suppliers toward EU-based blending facilities. Bavaria and Baden-Württemberg host ECKART's effect-pigment vertical serving leafing-grade brightness specifications.
India
PLI scheme incentives for metal 3D printing concentrate gas-atomized spherical powder demand in medical and aerospace prototyping. BIS specifications govern purity thresholds for pyrotechnic applications in domestic fireworks manufacturing clusters. Karnataka and Tamil Nadu additive manufacturing labs drive qualification timelines for novel alloy grades.
Japan
Automotive prototyping tooling suppliers qualify ultrasonic atomization lots for serial production jigs and fixtures. METI industrial standards govern powder metallurgy feedstock specifications for precision forging operations. Kansai and Chubu industrial corridors maintain press-and-sinter infrastructure for transmission component programs.
Aluminum Powders Pastes and Flakes Market Competitive Environment
Integrated primary aluminum producers and specialized atomization specialists split the market along feedstock control versus technical specification vectors. Captive bauxite-to-powder operations sustain cost advantages across high-volume automotive forging feedstock, while toll-manufacturing arrangements dominate European flake supply for coatings compliance. Three archetypes define positioning: upstream-integrated majors controlling refining and atomization, regional specialists with SAMR or REACH certification depth, and formulation service providers capturing paste formulation revenue streams. Competitive moves center on backward integration into secondary smelter networks and geographic expansion through EU toll-manufacturing joint ventures.
Among upstream-integrated majors, Alcoa Corporation exemplifies captive bauxite-to-powder economics across North American forging feedstock. ALTANA AG anchors European flake supply through its ECKART division's dedicated effect-pigment vertical, occupying a position calibrated to REACH compliance requirements. Hindalco Industries Limited represents South Asian spherical powder output for additive manufacturing, sitting within the certification-focused specialist tier serving India's PLI-scheme buildout.
| Leading Market Players |
|---|
| Alcoa Corporation |
| ALTANA AG (ECKART Division) |
| Hindalco Industries Limited |
| Rio Tinto Group |
| Norsk Hydro ASA |
| Metal Powder Company Ltd. (MEPCO) |
| Valimet, Inc. |
| TOYAL Group |
| Kymera International |
| Others |
Value Chain & Pricing Dynamics
Alumina price volatility transmitted from bauxite refining economics determines both the spread between captive-integrated and merchant powder pricing and the geographic clustering of atomization capacity around secondary smelter networks. REACH compliance costs for flake imports into Europe further stratify pricing tiers while forcing non-European suppliers toward toll-manufacturing joint ventures that reshape traditional distribution channels.
Pricing Analysis
The customization-premium spread separates standard gas-atomized grades from configured-to-order spherical powders qualified for aerospace additive manufacturing. Pricing stratifies across premium, standard, and economy tiers based on certification level (AMS-specified vs. industrial-grade) and volume scale, with lot-traceable automotive feedstock commanding premiums for embedded carbon-accounting data. Cost compression in commodity atomized grades is intensifying because of alumina feedstock swings, while Tier 1 automotive buyers show least price sensitivity due to lightweighting mandate urgency and long-term offtake security requirements.
Supply Chain Analysis
Tariff exposure between China and Western aerospace OEMs dominates supply chain risk calculations for spherical powder trade. Production gravity centers on China, Germany, and the United States, with the Yangtze River Delta cluster feeding domestic EV chassis programs and Bavaria hosting REACH-registered flake toll-manufacturing. Raw material sourcing draws from bauxite refining networks, secondary aluminum smelter output, and metallurgical-grade scrap streams. Single-source vulnerability concentrates in gas-atomization specialist talent pools nearing retirement. Distribution runs through direct mill-to-Tier-1 contracts that displace traditional distributor stocking models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
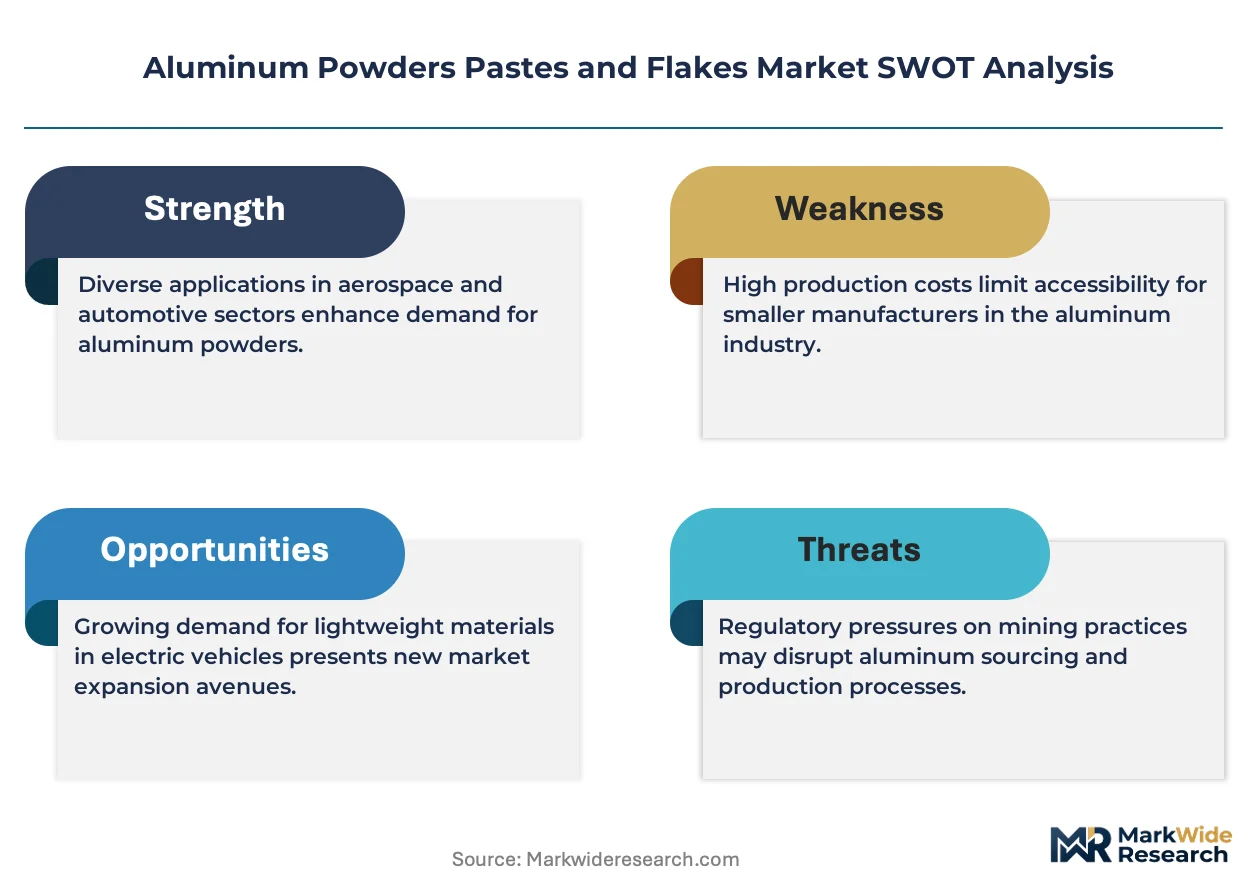
Titanium and carbon fiber substitution threats in aerospace structural applications demand defensive repositioning by aluminum powder incumbents, while paste formulation services offer white-space expansion for agile entrants.
For Market Incumbents: Harden supply security through backward integration into secondary smelter networks that satisfy China's MEE carbon intensity benchmarks. Deepen certification moats by accelerating AMS and ASTM qualification timelines for novel alloy grades before titanium composite penetration advances. Channel control through direct mill contracts with blockchain provenance tracking defends margin position against distributor displacement. For New Entrants and Emerging Players: India's PLI-scheme medical and aerospace prototyping labs represent the most penetrable entry point for gas-atomized spherical powder qualification. Waterborne paste formulations for European coatings contractors offer formulation-service revenue with lower capital intensity than atomization capacity. A go-to-market angle anchored to VOC-handling cost reduction for coatings contractors bypasses incumbent powder metallurgy relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors REACH-certified toll-manufacturing specialists with captive EU blending facilities. Long-term viability over a multi-year window hinges on carbon-accounting integration and secondary smelter feedstock access. The signal to watch is automotive OEM procurement teams mandating blockchain traceability as a qualification threshold.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secondary Smelters | Captive recycled-content feedstock secures MEE carbon benchmark compliance for Chinese EV supply chains. |
| EU Toll-Manufacturing Joint Venture | REACH-registered flake production preserves automotive coatings access under ECHA enforcement. |
| Ultrasonic Atomization Scale-Up | Tighter particle-size distribution captures binder-jet printing demand from German tooling suppliers. |
| Waterborne Paste Formulation Service | VOC-reduced offerings align with EU F-Gas Regulation thresholds for coatings contractors. |
| Blockchain Provenance Integration | Lot-traceability satisfies CATL and NIO procurement mandates for carbon-accounting data. |
Study Parameters
Initial hypotheses were tested against primary input from atomization plant managers, automotive Tier 1 procurement leads, coatings formulators, and REACH compliance consultants and refined through secondary validation. Sources included customs and trade flow databases, SEC filings from integrated aluminum producers, SAMR GB standard documentation, and ECHA registration dossiers. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-verify volume estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions covering product type, application, physical form, and end-user procurement pattern. CAGRs were derived from slope analysis of segment-specific volume trajectories. Industry-specific forecast inputs incorporated NHTSA lightweighting mandate timelines, China's dual carbon policy implementation, and plasma rotating electrode atomization technology diffusion curves.
Practitioners should monitor alumina price volatility, REACH enforcement intensity, and titanium composite substitution rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Lightweight Aluminium Pistons Market
Metals
Beryllium Copper Plate Market
Metals
Copper Wire Market
Metals
Global Electrolytic Copper Foil Market
Metals
Zinc Plating Market
Metals
Bismuth Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Reconditioned Steel Drums Market
Metals
Anodized Titanium Market
Metals
Lanthanum Market
Metals
Palladium Market
Metals
North America Aluminum Market
Metals
Global Bronze Market
Metals
High Purity Iron Powder Market
Metals
Stainless Steel Sheet Market
Metals
Nickel Sulfate Market