
 Plastic Color Sorter Market | 2026-2036
Plastic Color Sorter Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Color Sorter Market Insights
Recycling facilities is pivoting toward higher-purity output requirements as brand owners commit to post-consumer recycled content targets. Hefei Meyer Optoelectronic Technology Inc. leverages its manufacturing scale to dominate mid-capacity optical sorter shipments across Asia. Tomra sustains technology leadership in near-infrared detection for multilayer plastic identification. Buhler SORTEX anchors European demand through specialized channel control in food-contact recycling applications.
Plastic color sorters are electro-optical separation machines that use CCD cameras, LED illumination arrays, and pneumatic ejectors to classify polymer flakes or pellets by color, resin type, and contamination level at throughput rates exceeding several tons per hour. Their primary purpose is to upgrade recycled plastic streams to virgin-comparable purity for reprocessing into new products. Optical sorters and camera-based systems capture the dominant share of unit shipments, while machine learning algorithms represent the fastest-expanding technology layer as neural networks improve defect recognition accuracy. Gravity-based sorters occupy a mature niche in pre-sorting applications where margin pools remain thin.
The EU REACH regulation and FDA food-contact material standards shape equipment specifications by mandating contaminant thresholds that only advanced sorting configurations can reliably achieve. ISO 9001 quality management protocols further constrain supplier qualification for multinational recycling operators. Stakeholders must weigh capital deployment timing against evolving extended producer responsibility schemes and the pace of mechanical recycling capacity buildouts.
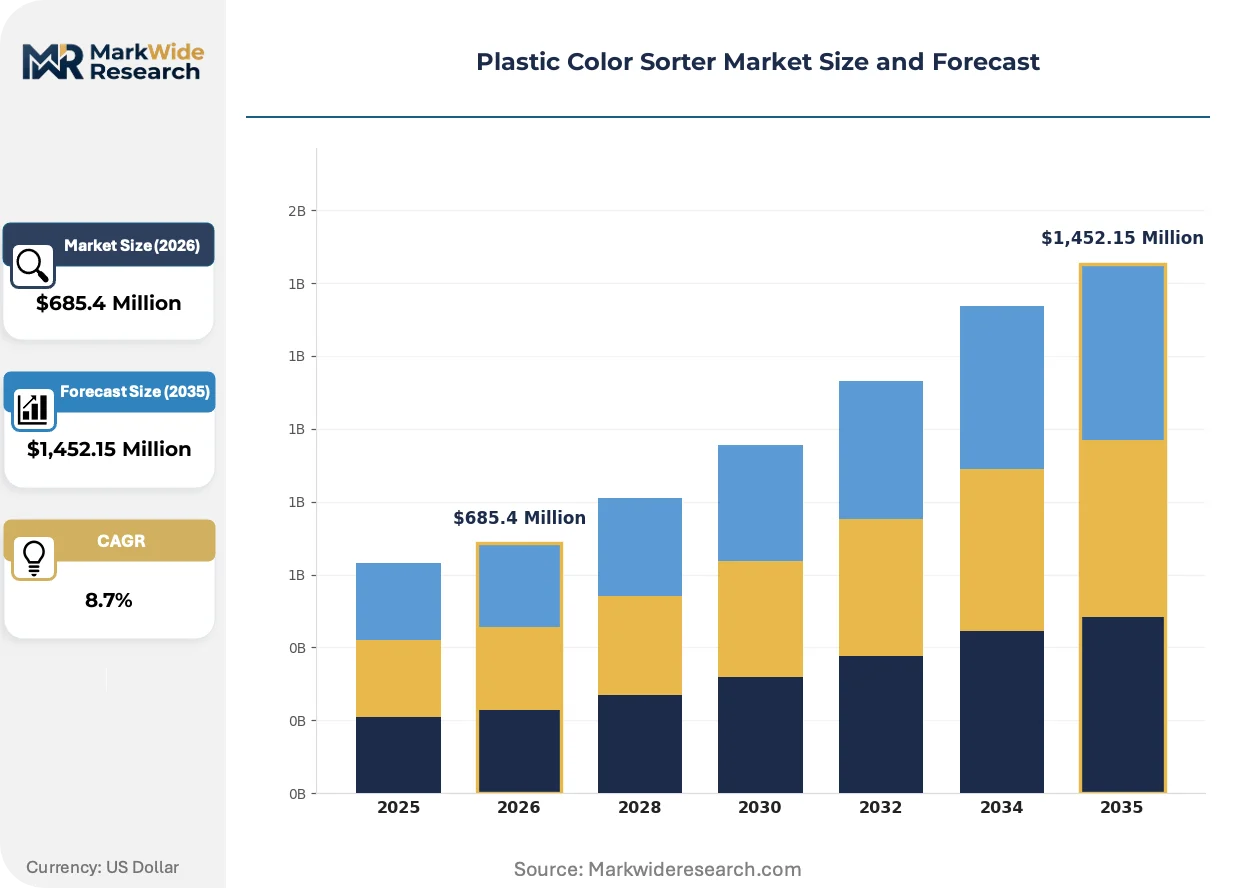
Market Dynamics
Mechanical recycling capacity buildouts across Europe and Asia are forcing processors to install higher-throughput optical sorting lines capable of achieving food-grade rPET purity thresholds mandated by the EU Single-Use Plastics Directive.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content targets for beverage bottles are compelling processors to upgrade sorting infrastructure to achieve virgin-comparable polymer purity.
- Near-infrared spectroscopy:Advanced NIR detection modules now identify multilayer plastics and black carbon contaminants that legacy systems miss, expanding addressable feedstock pools.
- German collection infrastructure:Post-consumer plastic collection rates exceeding neighboring economies are concentrating demand for high-capacity color sorter installations in Central European mechanical recycling clusters.
Market Restraints
- Capital intensity:Multi-camera optical sorters with pneumatic ejector arrays require substantial upfront investment that thin-margin pre-sorting operations cannot absorb.
- Component supply concentration:High-resolution CCD sensors and specialized LED illumination modules depend on concentrated Asian electronics manufacturing clusters.
- Technical limitation:Current systems struggle to differentiate chemically similar polymers like PET and PETG at flake-scale throughput without supplementary detection layers.
Strategic Opportunities
- India mechanical recycling:Underpenetrated formal collection networks and emerging extended producer responsibility frameworks create whitespace for optical sorting deployment.
- Chemical recycling feedstock preparation:Pyrolysis and depolymerization facilities require ultra-low contamination input streams that only advanced multi-sensor sorting configurations can reliably deliver.
- Machine learning convergence:Neural network defect recognition algorithms layered atop camera-based systems are reducing false-positive ejection rates and expanding yield recovery.
Industry Challenges
- Optoelectronics engineering talent:Shortage of specialists capable of integrating CCD calibration, pneumatic timing, and algorithm tuning constrains deployment velocity.
- ISO 9001 certification timelines:Multinational recycling operators require supplier qualification protocols that extend equipment procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Color Sorter Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Near Infrared Sorters, Optical Sorters, Color Sorters, Gravity-Based Sorters End User: Recycling Facilities, Plastics Manufacturers, Agricultural Processors, Waste Management Companies Technology: Electro-Optical Systems, Machine Learning Algorithms, Image Processing Tools, Camera-Based Systems Application: Plastics Recycling, Raw Material Sorting, Quality Control, Product Purification |
| Companies Covered | Hefei Meyer Optoelectronic Technology Inc., Key Technology, Tomra, National Recovery Technologies, DAEWON GSI, Buhler SORTEX, Cimbria, Anysort, Satake Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Color Sorter Market Trends and Innovations
Sensor fusion architectures and embedded AI inference engines are compressing the performance gap between laboratory-grade polymer analysis and production-line throughput, reshaping equipment specification criteria.
Hyperspectral imaging systems are absorbing sorting tasks previously reserved for manual inspection or density-based separation. Large-scale PET reclaimers in the Netherlands and Belgium are retrofitting existing lines with hyperspectral modules to capture full-wavelength signature data for black plastic identification. This technology is absorbing margin from gravity-based pre-sorters as processors prioritize single-pass purity over capital-light multi-stage configurations.
REACH regulation amendments tightening persistent organic pollutant thresholds are forcing equipment redesigns to eliminate brominated flame retardant cross-contamination risks. German mechanical recyclers serving food-contact applications must now demonstrate sub-ppm contaminant detection capabilities that exceed prior industrial-grade specifications. The FDA's updated food-contact notification requirements for post-consumer recycled content are similarly compressing acceptable variance bands for North American installations.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into componentized offerings. Recycling cooperatives in Spain and Italy are procuring sorting hardware from specialized vendors while sourcing algorithm updates and remote diagnostics through separate software subscriptions. This procurement pattern is most visible among mid-capacity processors seeking to preserve operational flexibility without captive service commitments.
Plastic Color Sorter Market Segmentation
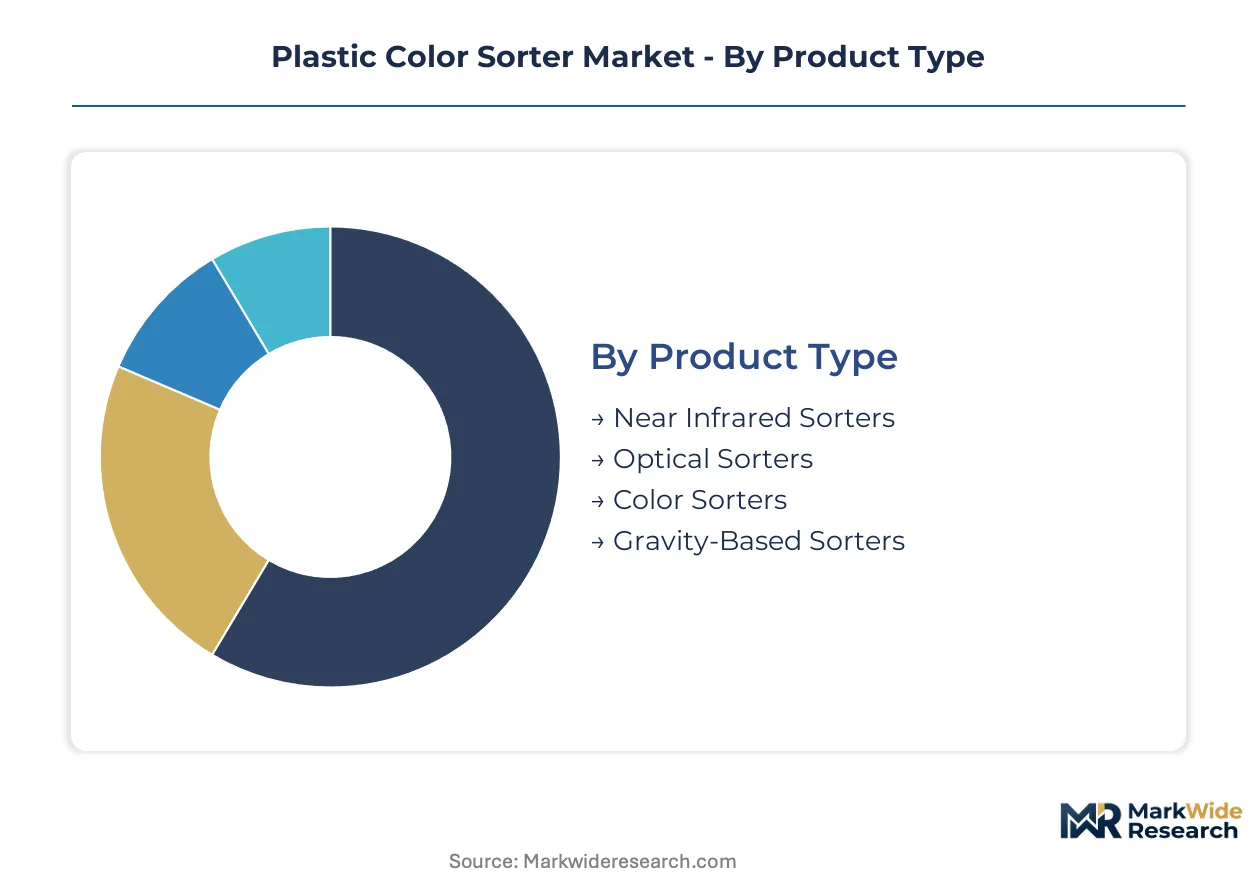
Plastic color sorter procurement patterns diverge sharply by operational scale and purity requirements. Equipment specifications vary from high-throughput optical lines for food-grade rPET reclaimers to gravity-based units serving thin-margin pre-sorting operations.
Product Type:
Buyers differentiate primarily by contaminant detection depth versus capital deployment capacity.
- Near Infrared Sorters:NIR detection modules identify multilayer plastics and black carbon contaminants through spectroscopic signature analysis. German mechanical recyclers serving beverage bottle applications concentrate procurement here to meet EU Single-Use Plastics Directive purity mandates.
- Optical Sorters:These systems integrate CCD cameras, LED illumination arrays, and pneumatic ejectors for polymer flake classification at multi-ton-per-hour throughput. Recycling facilities across Belgium and the Netherlands retrofit existing lines with hyperspectral-capable optical units.
- Color Sorters:Conventional RGB camera systems target color-based separation for homogeneous polymer streams.
- Gravity-Based Sorters:Density-separation units occupy pre-sorting niches where margin constraints exclude electro-optical investment.
Optical sorters lead volumes today; near infrared sorters are gaining share fastest.
End User:
Customer type determines specification rigor and service contract structure.
- Recycling Facilities:Post-consumer plastic reclaimers deploy multi-sensor configurations to achieve virgin-comparable output purity. REACH amendments tightening persistent organic pollutant thresholds force German operators toward sub-ppm detection capabilities.
- Plastics Manufacturers:Virgin polymer producers integrate color sorters for in-house regrind processing and contamination control.
- Agricultural Processors:Seed and grain sorting applications repurpose plastic-capable optical systems for foreign material removal.
- Waste Management Companies:Municipal material recovery facilities deploy mid-capacity units for mixed-plastic stream upgrading.
Recycling facilities dominate current procurement; waste management companies show the steepest expansion trajectory.
Technology:
Technology selection tracks the tension between proven reliability and algorithmic advancement.
- Electro-Optical Systems:Hardware-centric architectures combining CCD sensors, LED arrays, and pneumatic ejectors deliver deterministic sorting performance. FDA food-contact notification requirements for post-consumer recycled content compress acceptable variance bands for North American electro-optical installations.
- Machine Learning Algorithms:Neural network defect recognition layered atop camera systems reduces false-positive ejection rates. Spanish and Italian recycling cooperatives source algorithm updates through separate software subscriptions.
- Image Processing Tools:Edge-detection and blob-analysis software modules enable real-time flake classification.
- Camera-Based Systems:Baseline vision architectures serve cost-sensitive applications with standardized polymer streams.
Camera-based systems anchor installed base; machine learning algorithms are climbing the fastest.
Application:
Application scope defines sensor configuration complexity and certification requirements.
- Plastics Recycling:Post-consumer flake upgrading to food-grade rPET demands multi-sensor fusion architectures. ISO 9001 quality management protocols constrain supplier qualification for multinational recycling operators in this application.
- Raw Material Sorting:Virgin polymer pellet classification for color consistency and contamination screening.
- Quality Control:In-line inspection for extrusion and compounding operations.
- Product Purification:Final-stage polishing for high-value engineered resin output.
Plastics recycling commands the largest equipment footprint; product purification exhibits the most rapid specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mechanical recycling clusters anchor demand concentration for high-capacity optical sorting installations. Post-consumer plastic collection infrastructure and food-grade rPET purity mandates drive procurement patterns across the country. Belgium and the Netherlands follow as secondary concentration zones for hyperspectral retrofit activity.
Germany
Mechanical recyclers serving beverage bottle applications deploy multi-sensor configurations to meet EU Single-Use Plastics Directive thresholds. ECHA REACH amendments tightening persistent organic pollutant limits force sub-ppm detection capabilities. The Rhine-Ruhr industrial corridor concentrates high-throughput line installations serving food-contact rPET output.
United States
FDA food-contact notification requirements for post-consumer recycled content compress acceptable variance bands for North American equipment specifications. Brand owner recycled content commitments drive reclaimers toward neural-network-enhanced sorting architectures. The Great Lakes region hosts dense clusters of PET reclaimers retrofitting lines for black plastic identification.
China
Domestic mechanical recycling capacity buildouts absorb mid-capacity optical sorter shipments from manufacturing-scale producers. MIIT circular economy directives and dual carbon goals accelerate formal collection network expansion. The Yangtze River Delta concentrates electro-optical system assembly and LED illumination module supply.
India
Emerging extended producer responsibility frameworks create whitespace for optical sorting deployment in underpenetrated formal collection networks. BIS quality standards for recycled plastics gradually tighten material purity expectations. Gujarat and Maharashtra host early mover installations among integrated recycling cooperatives.
Netherlands
Large-scale PET reclaimers retrofit existing lines with hyperspectral modules for full-wavelength signature capture. The country's national waste management regulator enforces stringent output purity protocols for circular economy certification. Rotterdam-Antwerp port logistics clusters enable high-volume flake import-sorting-reexport operations.
Plastic Color Sorter Market Competitive Landscape
Capacity expansion dominates the current landscape as processors race to install lines ahead of regulatory deadlines. The vendor base stratifies across three tiers: integrated optoelectronics manufacturers with captive sensor production, specialized sorting machinery fabricators sourcing components externally, and regional assembly operations serving price-sensitive markets. Two strategic archetypes have emerged: technology leaders layering machine learning atop hardware platforms, and scale-driven producers competing on unit economics for mid-capacity shipments. Geographic expansion and technology licensing represent the dominant competitive vectors as players seek access to underpenetrated recycling markets.
Among Asia-based integrated manufacturers, Hefei Meyer Optoelectronic Technology Inc. exemplifies the scale-driven archetype through manufacturing depth in electro-optical components. Tomra occupies a position representing technology leadership in near-infrared detection architectures. Buhler SORTEX anchors the European specialist tier through channel control in food-contact recycling applications. These three entities collectively illustrate the competitive tension between hardware scale, algorithmic advancement, and application-specific certification depth that defines current procurement decisions.
| Leading Market Players |
|---|
| Hefei Meyer Optoelectronic Technology Inc. |
| Key Technology |
| Tomra |
| National Recovery Technologies |
| DAEWON GSI |
| Buhler SORTEX |
| Cimbria |
| Anysort |
| Satake Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up optical sorting specialists have consolidated component sourcing power across Asian electronics manufacturing clusters, compressing distributor margins while enforcing rigid pricing discipline on mid-capacity system deployments.
Pricing Analysis
Distributor margins in the 15-25% range separate OEM-direct procurement from channel-mediated sales, with three-tier pricing stratifying across food-contact certified, industrial-grade, and pre-sorting economy configurations. Price differentiation centers on detection depth—hyperspectral modules command substantial premiums over RGB camera baselines—and ISO 9001 certification tier. Pricing pressure stems from thin-margin pre-sorting operations deferring electro-optical upgrades, forcing vendors to absorb LED illumination module cost volatility. Waste management companies exhibit highest price sensitivity; German mechanical recyclers serving beverage applications demonstrate lowest elasticity due to EU Single-Use Plastics Directive compliance deadlines.
Supply Chain Analysis
Freight cost absorption from Hefei and Shenzhen assembly hubs to European mechanical recycling clusters has intensified margin compression, prompting regional LED module stocking strategies. Component supply concentrates in China for high-resolution CCD sensors, Taiwan for specialized illumination drivers, and Germany for precision pneumatic ejector arrays. Raw material dependencies span gallium arsenide substrates, rare-earth phosphors, and aerospace-grade aluminum extrusions. Single-source vulnerability in NIR spectroscopy detector modules poses structural risk. Distribution runs through specialized recycling equipment distributors in Europe, direct OEM relationships in Asia, and integrated service contracts in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement shifting toward food-grade rPET purity specifications that only multi-sensor fusion architectures can reliably deliver.
For Market Incumbents: Extend algorithmic differentiation through embedded AI inference engines, defending against component commoditization by Hefei Meyer and other scale-driven Asian manufacturers. Backward integration into CCD calibration capabilities preserves margin on high-throughput installations. Prioritize REACH amendment compliance engineering to lock in German mechanical recycler loyalty. For New Entrants and Emerging Players: Launch via software-subscription models targeting Spanish and Italian recycling cooperatives seeking operational flexibility without captive hardware commitments. India's emerging extended producer responsibility frameworks represent the most penetrable whitespace. Chemical recycling feedstock preparation offers premium pricing escape from saturated mechanical recycling competition. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized sorting machinery fabricators sourcing components externally, as integrated optoelectronics manufacturers capture scarcity premiums. Long-term viability favors vendors with machine learning convergence capabilities and food-contact certification depth. Watch EU Single-Use Plastics Directive enforcement velocity as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Hyperspectral-NIR integration enables black plastic identification that legacy systems miss. |
| Machine Learning Algorithm Licensing | Neural network defect recognition reduces false-positive ejection rates for PET reclaimers. |
| Food-Contact Certification Investment | FDA notification compliance unlocks North American beverage bottle recycling contracts. |
| Regional Assembly Footprint Expansion | European LED module stocking mitigates freight cost volatility from Asian supply hubs. |
| Chemical Recycling Partnership Formation | Pyrolysis feedstock preparation contracts command ultra-low contamination premiums. |
Research Methodology
Coverage spans Germany, the United States, China, India, and the Netherlands, with primary inputs from each market gathered through structured interviews with recycling facility operations directors, OEM procurement managers at plastics manufacturers, electro-optics R&D engineers, and aftermarket service heads. Secondary validation draws from EU ECHA REACH amendment filings, FDA food-contact notification databases, MIIT circular economy policy circulars, and mechanical recycling capacity buildout announcements. Bottom-up equipment shipment tallies triangulate against top-down purity mandate compliance requirements.
Rate-of-change decomposition separates volume growth from specification escalation effects across the projection horizon, with segmentation modeling across sorter product type, end-user operational scale, detection technology layer, and application purity tier. CAGRs derive from installed base replacement cycles, regulatory deadline clustering, and neural network adoption S-curves. Forecast inputs incorporate EU Single-Use Plastics Directive recycled content phase-in schedules and chemical recycling capacity announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under supply chain disruption scenarios or accelerated REACH amendment enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
United States Non-Ferrous Scrap Recycling Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market